
 Vietnam Displays Market | 2026-2036
Vietnam Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Displays Market Insights
Market Dynamics
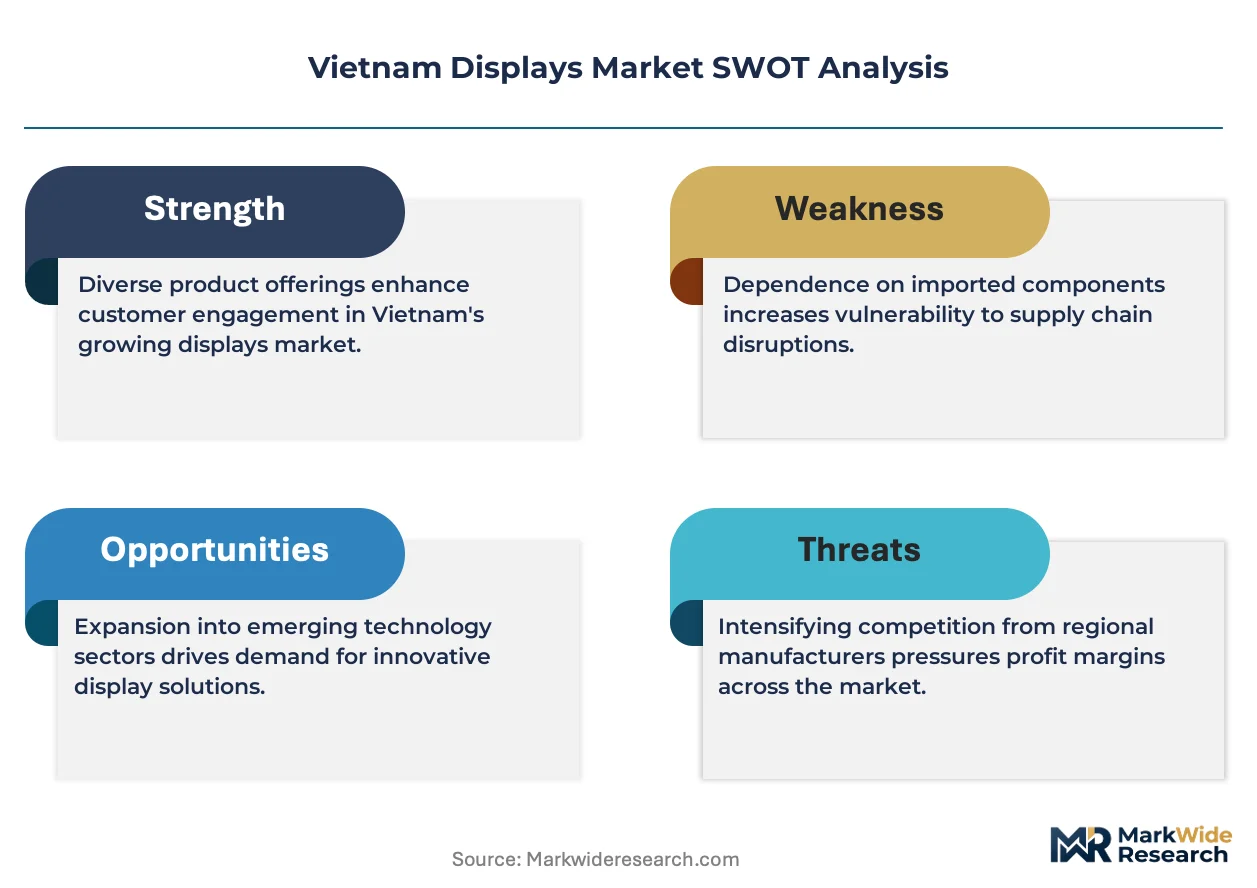
The domestic distributor network for consumer electronics is reconfiguring as provincial retailers gain direct access to panel manufacturers. Samsung Electronics Vietnam leverages its integrated semiconductor-to-display campus in Thai Nguyen to sustain cost leadership in large-format LCD output. LG Display Vietnam anchors premium OLED supply for regional export markets, while BOE Technology Group Co., Ltd. competes aggressively on price in commercial monitor segments. TCL Electronics Vietnam differentiates through localized assembly partnerships that reduce landed costs for domestic television brands.
Product Landscape
Displays are optoelectronic devices that modulate light through liquid crystal matrices, organic electroluminescent compounds, or inorganic micro-LED arrays to render visual information, with pixel densities ranging from sub-100 ppi in digital signage to over 500 ppi in handheld panels. LCD technology still occupies the dominant production volume position across Vietnamese fabs due to mature supply chains and lower capital intensity, though OLED is displacing premium television and mobile device applications where contrast ratios and power efficiency command margin premiums. Flexible display technology remains nascent in local manufacturing but represents the fastest-growing investment category as equipment suppliers establish service centers in Bac Ninh.
Regulatory Environment
The Ministry of Information and Communications enforces national technical regulations on electromagnetic compatibility and energy labeling for display products sold domestically, while the Vietnam General Department of Standards, Metrology and Quality administers conformity assessment procedures that align with ASEAN harmonized standards. These frameworks shape demand by restricting import of non-compliant panels and incentivizing local assembly of certified finished goods. Stakeholders must monitor forthcoming circulars on hazardous substance limits, as these will determine which overseas component suppliers qualify for continued market access.
Market Dynamics
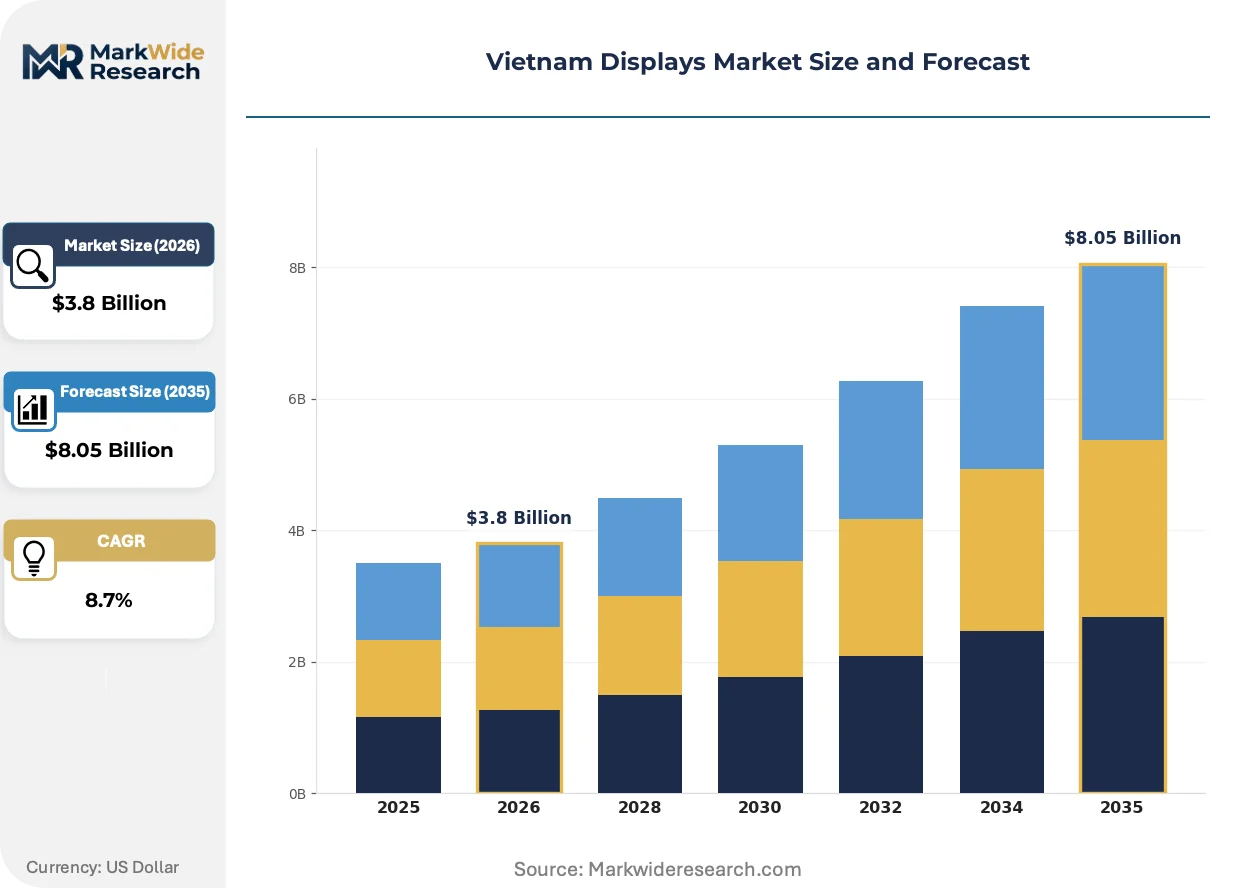
The Vietnamese display sector is restructuring around localized panel assembly and tightening energy efficiency mandates from the Ministry of Information and Communications, which are compressing import channels while expanding domestic manufacturing capacity.
Growth Catalysts
- Green transition mandates:The Ministry of Information and Communications is tightening display energy efficiency standards under national green transition mandates, forcing domestic assembly of certified finished goods and expanding local fab utilization.
- Flexible display investment:Flexible display technology represents the fastest-growing investment category as equipment suppliers establish service centers in Bac Ninh, drawing capital into next-generation manufacturing capabilities.
- Ho Chi Minh City demand concentration:Demand concentrates in Ho Chi Minh City and the northern industrial corridor around Bac Ninh and Hai Phong, creating dense logistics networks that reduce landed costs for domestic television brands.
Market Restraints
- OLED capital intensity:OLED production requires substantially higher capital expenditure than mature LCD lines, limiting local fab conversion and preserving LCD dominance in volume terms.
- Component import dependency:Hazardous substance limits in forthcoming circulars will determine which overseas component suppliers qualify for continued market access, creating supply uncertainty.
- Micro-LED technical barriers:Inorganic micro-LED arrays remain unmanufacturable at scale in Vietnamese facilities due to epitaxy equipment gaps and yield management complexity.
Strategic Opportunities
- Provincial retailer direct access:The domestic distributor network is reconfiguring as provincial retailers gain direct access to panel manufacturers, bypassing traditional wholesale tiers in secondary cities.
- ASEAN harmonized standards alignment:The Vietnam General Department of Standards, Metrology and Quality administers conformity assessment procedures that align with ASEAN harmonized standards, enabling export qualification to regional markets.
- Semiconductor-to-display integration:Integrated semiconductor-to-display campuses allow captive supply of driver ICs and timing controllers, compressing bill-of-material costs for large-format output.
Industry Challenges
- Electromagnetic compatibility certification:The Ministry of Information and Communications enforces national technical regulations on electromagnetic compatibility that extend product approval timelines and require specialized testing infrastructure.
- Epitaxy equipment service scarcity:Flexible display manufacturing depends on equipment suppliers establishing localized service centers, but technical talent for precision maintenance remains concentrated in northern industrial provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Displays Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, MicroLED End User: Retail, Education, Healthcare, Corporate Application: Digital Signage, Televisions, Monitors, Mobile Devices Technology: Flat Panel, Projection, Touchscreen, Flexible |
| Companies Covered | Samsung Electronics Vietnam, LG Display Vietnam, Panasonic Vietnam, Sharp Vietnam, Sony Vietnam, TCL Electronics Vietnam, BOE Technology Group Co., Ltd., Foxconn Technology Group, NEC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Displays Market Trends and Innovations
Display technology evolution in Vietnam is compressing traditional technology lifecycles while regulatory pressure and channel restructuring reshape how panels reach end-users.
Mini-LED backlighting is collapsing the price-performance gap between premium LCD and entry OLED television panels. Domestic television brands in Vietnam are adopting mini-LED configurations at accelerating rates to capture margin in the mid-premium segment. This diffusion is collapsing the historical tiering that separated LCD volume production from OLED premium positioning.
The Ministry of Information and Communications is enforcing national technical regulations on electromagnetic compatibility and energy labeling for display products sold domestically. These frameworks restrict import of non-compliant panels and incentivize local assembly of certified finished goods. Provincial retailers and domestic television brands are responding by consolidating procurement relationships with Thai Nguyen and Bac Ninh manufacturing clusters.
Direct procurement relationships between provincial retailers and panel manufacturers are displacing traditional distributor hierarchies. Secondary cities outside Ho Chi Minh City are establishing direct supply contracts with Bac Ninh and Hai Phong fabs, compressing margin extraction by wholesale intermediaries. This channel disintermediation is most visible in northern provinces where industrial corridor proximity reduces logistics coordination costs.
Vietnam Displays Market Segmentation
Vietnam's display market segments exhibit sharply divergent replacement cycles, with mobile panels refreshing every 18-24 months while digital signage installations persist for 7-10 years. These temporal mismatches create distinct inventory management and capacity planning challenges for Thai Nguyen and Bac Ninh manufacturing clusters.
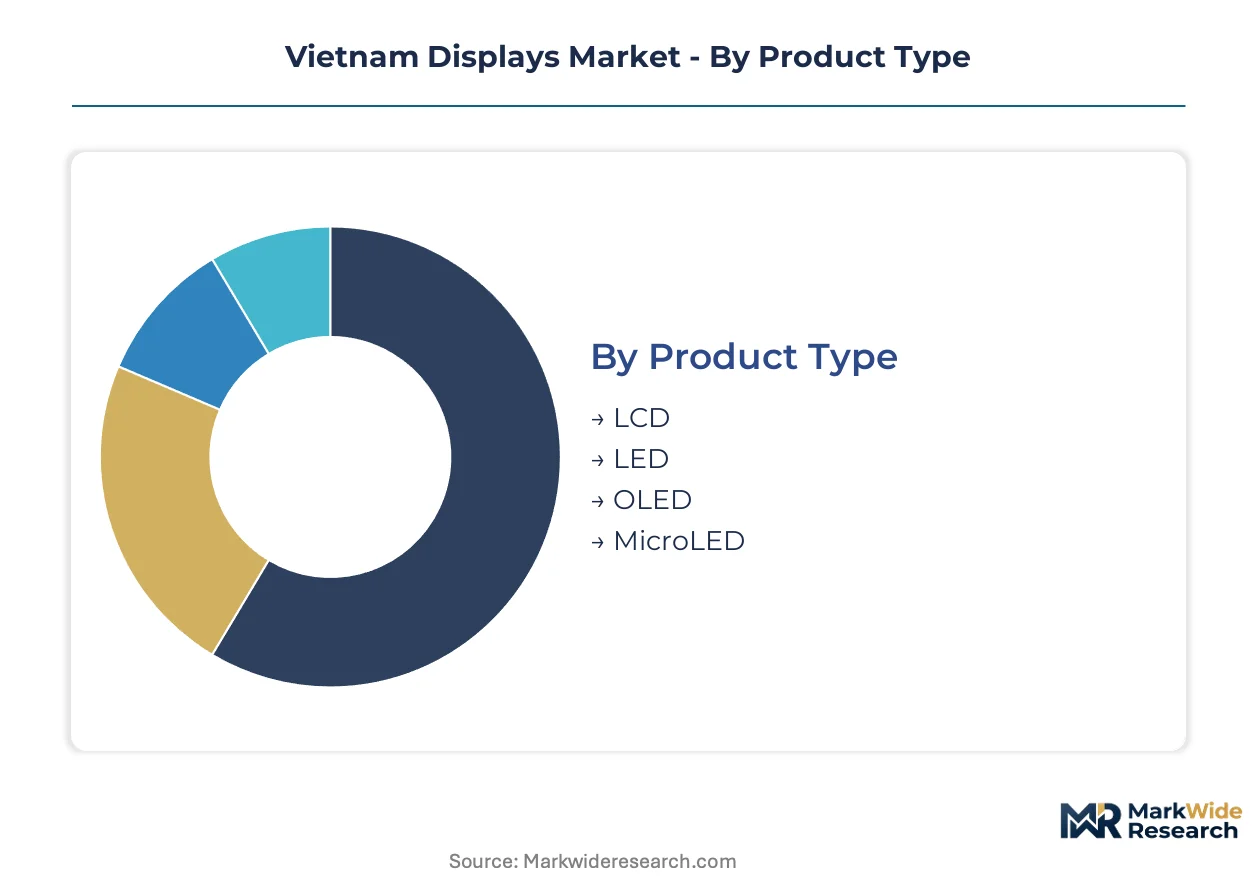
Product Type:
Cycle times range from mature LCD lines running at full depreciation to MicroLED pilot lines requiring decade-long amortization schedules.
- LCD:Liquid crystal matrices with mature supply chains dominate Vietnamese fab output due to lower capital intensity and established driver IC ecosystems. Thai Nguyen manufacturing clusters sustain cost leadership in large-format panels for domestic television brands and regional export markets.
- LED:Direct-view LED arrays serve high-brightness commercial applications where luminance requirements exceed 1,000 nits. Bac Ninh assembly lines prioritize outdoor digital signage and stadium display contracts with compressed delivery timelines.
- OLED:Organic electroluminescent compounds enable self-emissive pixels with infinite contrast ratios. Premium television and mobile device applications in Ho Chi Minh City command margin premiums that justify higher capital expenditure per wafer.
- MicroLED:Inorganic micro-LED arrays remain pre-commercial in Vietnamese facilities due to epitaxy equipment gaps and mass transfer yield challenges.
LCD anchors the volume base while OLED gains share at the steepest rate.
End User:
Customer procurement sophistication ranges from retail chains negotiating consolidated annual contracts to healthcare systems requiring IEC 60601-1 medical-grade certifications.
- Retail:Point-of-sale displays and customer-facing digital signage demand high brightness and 16/7 operational durability. Provincial electronics distributors in secondary cities outside Ho Chi Minh City are consolidating direct procurement relationships with Bac Ninh panel manufacturers.
- Education:Interactive flat panels and classroom projectors require anti-glare coatings and extended warranty terms. Ministry of Information and Communications energy efficiency mandates are accelerating replacement of legacy fluorescent-backlit installations in public schools.
- Healthcare:Diagnostic imaging displays demand DICOM calibration compliance and luminance stability over 50,000-hour lifespans. The Vietnam General Department of Standards, Metrology and Quality administers conformity assessment procedures that restrict import of non-certified panels.
- Corporate:Video conferencing endpoints and control room video walls prioritize color accuracy and bezel minimization. Northern industrial corridor proximity reduces logistics coordination costs for Hai Phong-based enterprise integrators.
Retail commands the largest shipment volumes while healthcare exhibits the most stringent certification barriers.
Application:
Margin structures diverge between commodity television panels and specialized mobile device displays requiring sub-2mm bezel architectures.
- Digital Signage:Large-format commercial displays for advertising and wayfinding operate in uncontrolled thermal environments. Outdoor installations in Ho Chi Minh City's tropical climate demand IP65 ingress protection and active cooling systems.
- Televisions:Consumer display panels range from entry HD resolution to premium 8K mini-LED configurations. Domestic brands leverage localized assembly partnerships in Thai Nguyen to reduce landed costs against import competition.
- Monitors:Desktop and commercial office displays prioritize ergonomic adjustability and blue-light reduction certifications. Corporate procurement consolidation is compressing margin extraction by traditional wholesale intermediaries.
- Mobile Devices:Handheld panels require pixel densities exceeding 500 ppi with flexible substrate compatibility. Equipment suppliers establishing service centers in Bac Ninh are enabling next-generation manufacturing capability investments.
Televisions generate the revenue base while mobile devices are climbing the fastest on flexible display investments.
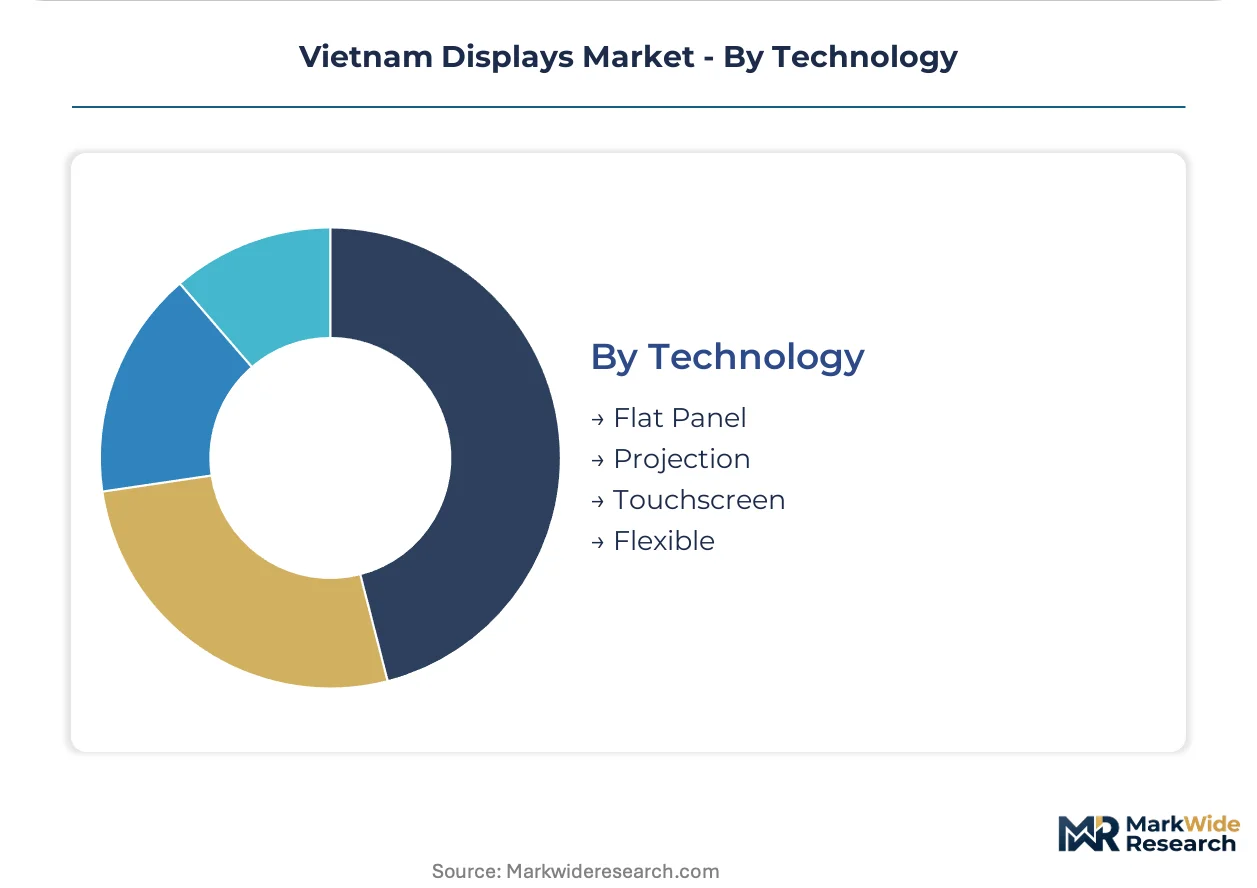
Technology:
Manufacturing complexity escalates from passive projection systems to active-matrix flexible substrates requiring polyimide handling expertise.
- Flat Panel:Rigid substrate displays encompass the vast majority of Vietnamese production volume. Mature TFT-LCD and OLED lines in the northern industrial corridor supply regional export markets with established logistics networks.
- Projection:DLP and laser phosphor systems serve large-venue applications where direct-view panel costs scale prohibitively. Education sector procurement favors projection for classroom footprints exceeding 100-inch diagonal requirements.
- Touchscreen:Projected capacitive and infrared overlay technologies integrate sensor layers with display substrates. Retail and corporate end-users are standardizing on 10-point multitouch for interactive kiosk deployments.
- Flexible:Bendable and foldable displays on polyimide substrates represent emerging manufacturing investments. Technical talent for precision equipment maintenance remains concentrated in northern industrial provinces.
Flat Panel sustains production dominance while Flexible technology expands most quickly on capital inflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lach Huyen deep-water port in Hai Phong anchors northern Vietnam's display export corridor, handling containerized panel shipments to ASEAN and East Asian markets while the Cai Mep-Thi Vai port complex serves southern manufacturing clusters.
Ho Chi Minh City
Ho Chi Minh City concentrates premium television and mobile device consumption, with electronics retailers commanding the highest average selling prices nationally. The Ministry of Information and Communications enforces electromagnetic compatibility certification at its southern testing facilities, extending product approval timelines for imported panels. District 7 and Thu Duc City host dense logistics networks that reduce landed costs for domestic brands assembling certified finished goods.
Bac Ninh Province
Bac Ninh anchors flexible display equipment investment as foreign machinery suppliers establish localized service centers. The Vietnam General Department of Standards, Metrology and Quality administers conformity assessment procedures that align with ASEAN harmonized standards, enabling export qualification from northern fabs. Yen Phong and Tien Du industrial zones attract capital inflows for next-generation manufacturing capabilities.
Hai Phong
Hai Phong leverages port infrastructure to sustain large-format LCD export volumes for regional television markets. The Ministry of Information and Communications energy labeling requirements restrict import of non-compliant panels, incentivizing local assembly of certified finished goods. Dinh Vu-Cat Hai economic zone hosts enterprise integrators supplying corporate video wall installations across northern provinces.
Thai Nguyen
Thai Nguyen hosts integrated semiconductor-to-display campuses that compress bill-of-material costs through captive supply of driver ICs. National green transition mandates from the Ministry of Information and Communications force domestic assembly of certified finished goods, expanding local fab utilization. Samsung Electronics Vietnam anchors the province's cost leadership position in large-format panel output.
Da Nang
Da Nang represents the central coastal corridor's emerging electronics distribution hub, with provincial retailers gaining direct access to panel manufacturers. The Ministry of Information and Communications hazardous substance limits in forthcoming circulars will determine which overseas component suppliers qualify for continued market access. Hoa Khanh and Hoa Cam industrial zones attract assembly partnerships that reduce logistics coordination costs for secondary city markets.
Vietnam Displays Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturing campuses that combine semiconductor fabrication with panel assembly. Korean and Chinese capital dominates capital-intensive OLED and flexible display investments, while domestic assembly partnerships compete on landed cost reduction for television brands. Three archetypes define competitive positioning: integrated fab operators, equipment-dependent technology licensors, and localized assembly specialists. Capacity expansion and backward integration into driver IC production represent the dominant competitive moves.
Among integrated fab operators, Samsung Electronics Vietnam and LG Display Vietnam exemplify the capital-intensive archetype through their northern industrial corridor presence. BOE Technology Group Co., Ltd. occupies a position within the technology-licensor tier, representing Chinese state-backed expansion into regional commercial monitor segments. These three entities anchor the competitive structure by demonstrating how geographic concentration in Bac Ninh and Thai Nguyen provinces creates defensive positioning against import-dependent assemblers.
| Leading Market Players |
|---|
| Samsung Electronics Vietnam |
| LG Display Vietnam |
| Panasonic Vietnam |
| Sharp Vietnam |
| Sony Vietnam |
| TCL Electronics Vietnam |
| BOE Technology Group Co., Ltd. |
| Foxconn Technology Group |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Thai Nguyen and Bac Ninh manufacturing clusters concentrate panel production capacity, anchoring margin pools with domestic television brands and provincial retailers who negotiate direct procurement contracts. The Ministry of Information and Communications energy efficiency mandates compress import channels, shifting pricing power toward certified local assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Vietnam's display market, with premium OLED panels commanding substantial markups for Ho Chi Minh City electronics retailers while economy LCD volumes compete on landed cost. Price differentiation rests on certification grade under national technical regulations and volume scale in annual procurement contracts. Cost compression in mid-tier mini-LED configurations is intensifying because domestic brands accelerate adoption to bridge the LCD-OLED gap. Provincial retailers exhibit highest price sensitivity due to compressed margins in secondary city distribution, whereas healthcare systems prioritize DICOM calibration compliance over unit cost.
Supply Chain Analysis
Foxconn Technology Group and Samsung Electronics Vietnam anchor contract-manufacturing concentration in the northern industrial corridor, with integrated semiconductor-to-display campuses in Thai Nguyen compressing bill-of-material costs for large-format output. Geographic supply concentration draws from South Korea for OLED deposition equipment, China for glass substrates and polarizers, and Taiwan for driver ICs. Raw material dependencies include indium tin oxide sputtering targets, liquid crystal compounds, and polyimide flexible substrates. Single-source vulnerability in epitaxy equipment service creates supply chain risk as technical talent remains concentrated in Bac Ninh and Hai Phong provinces. Distribution runs through provincial retailers consolidating direct relationships with panel manufacturers, displacing traditional wholesale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxy equipment maintenance capability scarcity concentrates in northern industrial provinces, creating defensive moats for integrated operators while constraining flexible display expansion for capital-constrained entrants.
For Market Incumbents: Pre-empt OLED line conversion at Thai Nguyen facilities before capital requirements escalate further, locking in premium positioning as mini-LED diffusion compresses mid-tier margins. Capture driver IC production in-house to reduce exposure to Taiwan supply volatility. Defensive consolidation through certification pre-positioning under forthcoming hazardous substance circulars will disqualify import-dependent competitors from domestic procurement channels. For New Entrants and Emerging Players: Da Nang and central coastal corridor underpenetration offers white-space expansion as provincial retailers there seek direct panel manufacturer access bypassing Ho Chi Minh City wholesale tiers. Target education sector interactive flat panel replacement cycles accelerated by Ministry of Information and Communications energy efficiency mandates. Pursue assembly partnerships with Bac Ninh equipment suppliers establishing localized service centers to reduce technical talent barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across flexible display manufacturing as polyimide handling expertise and mass transfer yield management become critical differentiators. Long-term viability favors integrated fab operators with captive semiconductor supply over pure-play assemblers exposed to component import dependency. Monitor equipment supplier service center establishment announcements in northern provinces as inflection indicator for next-generation manufacturing capability deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Production | Captive supply from Thai Nguyen semiconductor fabs compresses bill-of-material costs for large-format LCD output. |
| Flexible Display Equipment Localization | Service center establishment in Bac Ninh reduces maintenance downtime and accelerates next-generation manufacturing investment. |
| Provincial Retailer Direct Procurement | Channel disintermediation in secondary cities outside Ho Chi Minh City extracts margin from traditional wholesale hierarchies. |
| ASEAN Harmonized Standards Alignment | Conformity assessment procedures administered by Vietnam General Department of Standards enable regional export qualification. |
| Mini-LED Configuration Expansion | Domestic television brands capture mid-premium segment margin as price-performance gap between LCD and OLED collapses. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Vietnamese electronics manufacturing, including panel fabrication engineers at Thai Nguyen and Bac Ninh facilities, procurement directors at domestic television brands, provincial electronics distributors in secondary cities, and regulatory affairs specialists navigating Ministry of Information and Communications technical regulations. Secondary validation drew from Vietnam General Department of Standards conformity assessment databases, ASEAN harmonized standards documentation, customs trade records for display panel imports, and industrial zone investment disclosures. Bottom-up capacity utilization data from northern manufacturing clusters was triangulated against top-down consumption estimates from Ho Chi Minh City retail channel audits.
Calibration against historical replacement cycles and technology diffusion patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include display technology type, end-user vertical, application format, and regional manufacturing cluster. CAGRs were derived from capacity expansion announcements, equipment investment flows, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated Ministry of Information and Communications energy efficiency standard phase-in schedules and flexible display equipment supplier service center establishment trajectories.
Practitioners should monitor hazardous substance circular publication, epitaxy equipment service center expansion announcements, and provincial retailer procurement consolidation rates for early signals of supply chain restructuring. Forecasts reflect assumptions regarding regulatory implementation pace, technology yield improvement curves, and capital inflow continuity into northern industrial provinces. Quarterly review of equipment import license approvals and industrial zone occupancy permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
E-Paper Display Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Light Field Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Touch Screen Film Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
DLP Projector Market
Display Technologies
Computer Monitor Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Backlit Displays Market
Display Technologies
AMOLED Display Market