
 Touch Screen Display Market | 2026-2036
Touch Screen Display Market Size, Share, and Industry Trends Forecast 2026-2036
Touch Screen Display Market Intelligence
ISO 13406-2 pixel defect tolerance classification is rotating as a de facto gatekeeper for industrial and medical-grade panel qualification. BOE Technology leverages captive Gen 10.5 oxide-TFT capacity to anchor supply for extra-large format commercial displays. Samsung Display sustains technology leadership through in-house quantum-dot OLED integration for premium automotive consoles. LG Display competes in medium-to-large touch modules by specializing in in-cell touch architecture for slim-profile applications.
A touch screen display is an electro-optical input-output device comprising a transparent conductive layer stack—typically indium tin oxide or metal mesh—laminated to a liquid-crystal or OLED substrate, which detects finger or stylus contact through capacitive coupling, resistive pressure, or optical interruption and translates positional data to host processors. The primary commercial purpose is to collapse input and output functions into a single surface, eliminating mechanical switches in space-constrained or sealed environments. Capacitive technology dominates volume across consumer and automotive applications due to multi-touch gesture fidelity and optical clarity, while resistive panels retain structural share in industrial and legacy retail POS terminals where gloved operation and cost floors matter more than responsiveness. Infrared and optical variants occupy niche positions in extra-large format digital signage where physical durability against public abrasion outweighs precision demands.
FCC Part 15 emissions compliance gates North American market access for capacitive controllers, while REACH substance restrictions on indium compounds reshape material sourcing for European-bound panels. China's GB 4943.1 safety standard for information technology equipment enforces touch surface temperature and electrical isolation thresholds that influence panel stack design for export manufacturing. Stakeholders must monitor evolving automotive-grade reliability specifications from NHTSA and ECE R10 as touch displays migrate from infotainment to safety-critical instrument clusters.
Market Dynamics
Automotive OEMs are collapsing mechanical switch counts into unified glass surfaces, forcing touch controller suppliers to meet ASIL-D functional safety grades for instrument cluster migration while display fabs retool oxide-TFT lines for curved automotive form factors.
Growth Catalysts
- EU Ecodesign Directive:Tightening power consumption thresholds for display modules accelerate low-power oxide-TFT adoption in commercial signage and kiosks.
- Electric vehicle lineups:Automotive OEMs expand touch interface deployments across cabin domains from infotainment to climate control, creating dedicated demand for automotive-grade bonded stacks.
- Capacitive multi-touch:Gesture fidelity requirements in premium consumer electronics sustain indium tin oxide and metal mesh sensor demand despite alternative material exploration.
Market Restraints
- Indium supply concentration:Primary indium refining concentrates in Chinese and South Korean smelters, exposing ITO sputtering target costs to concentrate supply disruptions.
- Reach substance restrictions:European chemical regulations on indium compounds reshape material sourcing for EU-bound panels, forcing qualification of alternative transparent conductors.
- Resistive legacy lock-in:Industrial and retail POS terminals retain resistive panels for gloved operation, fragmenting procurement volumes and preventing full capacitive conversion.
Strategic Opportunities
- Safety-critical instrument clusters:NHTSA and ECE R10 automotive-grade reliability specifications create certification barriers that qualified suppliers can monetize through premium positioning.
- In-cell touch architecture:Slim-profile applications in mobile and automotive consoles reward panel makers integrating touch sensors directly onto display backplanes.
- Extra-large format digital signage:Infrared and optical touch variants capture share where physical durability against public abrasion outweighs precision demands in transit hubs and retail environments.
Industry Challenges
- ISO 13406-2 pixel defect classification:Industrial and medical-grade panel qualification requires sub-pixel tolerance testing that extends certification timelines and strains quality systems.
- GB 4943.1 compliance:China's safety standard for information technology equipment enforces touch surface temperature and electrical isolation thresholds that force stack redesigns for export manufacturing.
- Controller firmware integration:Capacitive touch ICs must synchronize with host processors across multiple operating systems, multiplying software validation cycles for automotive and medical device deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch Screen Display Market |
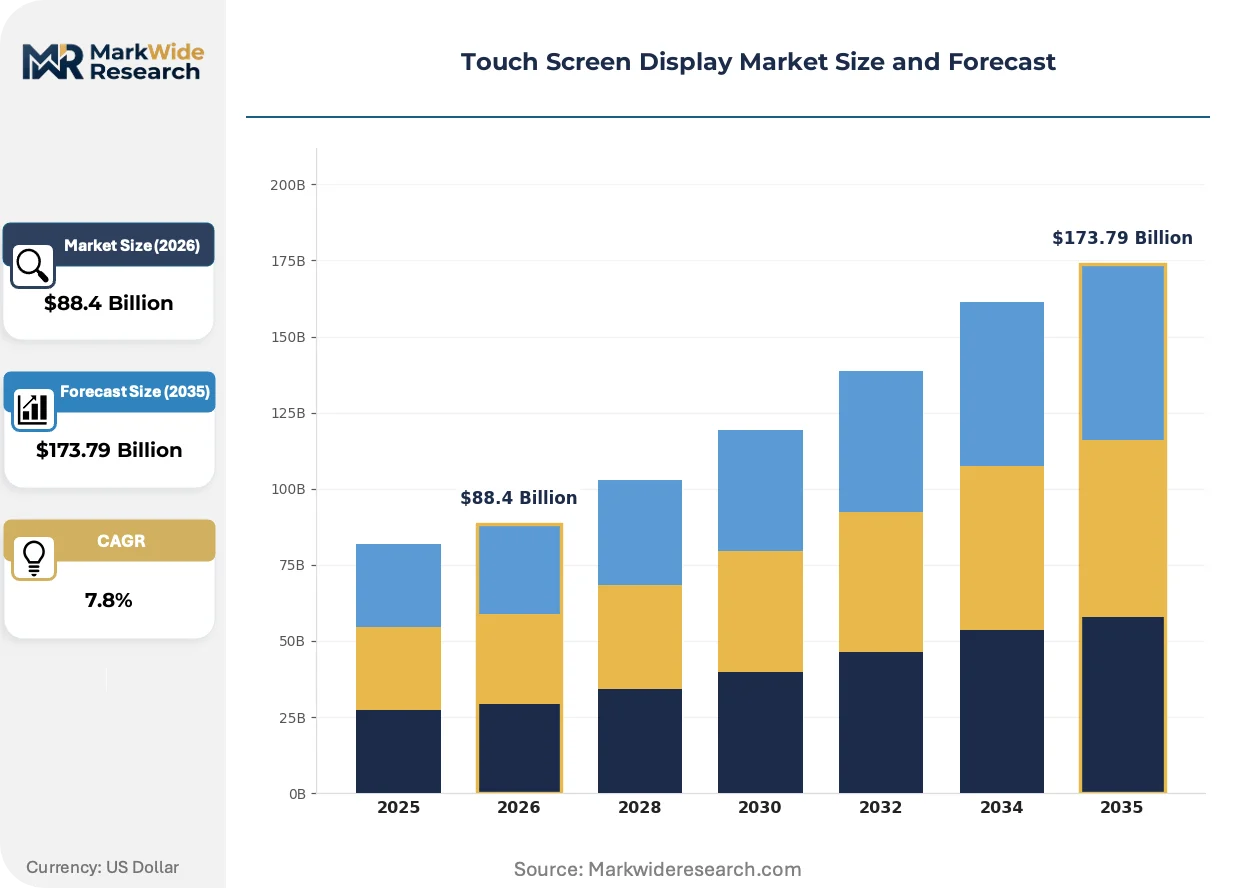
| Market Size in 2026 | $88.4 Billion |
| Market Size in 2035 | $173.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Optical, Infrared End User: Retail, Automotive, Healthcare, Industrial Technology: Multi-Touch, Single-Touch, 3D Touch, Holographic Size: Small, Medium, Large, Extra Large |
| Companies Covered | ELO Touch Solutions, BOE Technology, Samsung Display, AIS, Biamp Systems, LG Display, AU Optronics, New Vision Display, Panox Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch Screen Display Market Strategic Shifts & Innovations
Touch display technology is bifurcating between premium multi-layer bonded stacks for automotive safety and cost-optimized single-sensor solutions for commoditized consumer applications, with manufacturing equipment choices locking fabs into irreversible process pathways.
Metal mesh transparent conductors are fragmenting the indium tin oxide monopoly in large-format and flexible applications. Automotive console makers adopt copper mesh sensors for curved surfaces where ITO brittleness risks cracking. The structural consequence is compressing ITO to smaller rigid panels while metal mesh and silver nanowire alternatives capture automotive and foldable device volumes.
REACH substance restrictions on indium compounds are forcing European-bound panel suppliers to requalify alternative transparent conductive oxides and conductive polymers. The industrial consequence extends supplier qualification timelines by 12-18 months for new material stacks. Medical device and industrial panel categories face the tightest compliance windows as they cannot absorb rapid material substitutions without full recertification.
Automotive OEMs are consolidating touch display procurement around vertically integrated module suppliers capable of bonded optical stack delivery. Tier-1 suppliers without in-house lamination capability are losing position to panel makers with captive cover glass and optical bonding assets. German and South Korean automotive electronics corridors show the fastest procurement consolidation as OEMs reduce supplier counts to simplify ASIL-D liability chains.
Touch Screen Display Market Segmentation
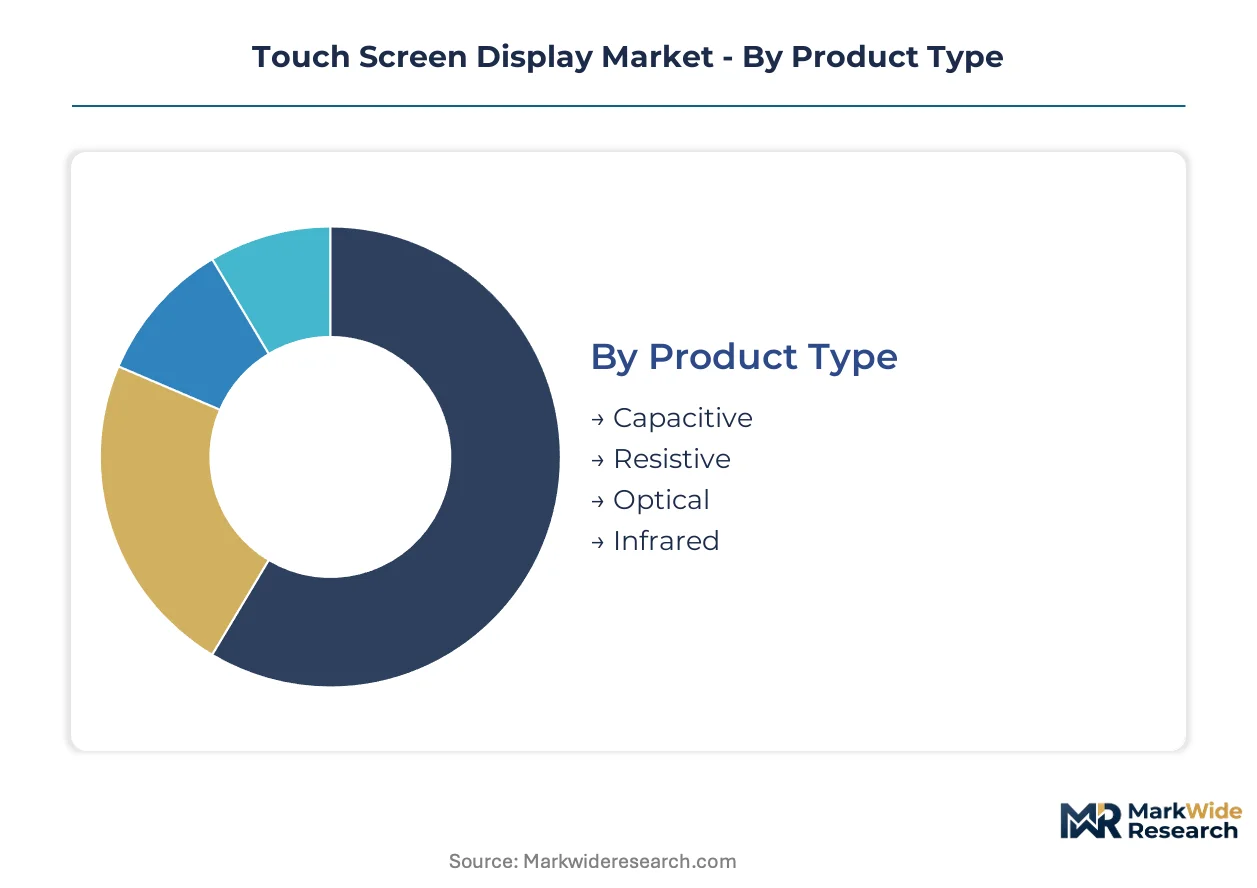
Touch screen display procurement fragments across four orthogonal dimensions. Technology choices lock fabs into irreversible capital commitments, while end-use certifications create distinct margin tiers that reshape supplier positioning.
Product Type:
Margin pools concentrate in capacitive architectures where multi-touch fidelity commands automotive and consumer premiums, while resistive panels compete on cost floors in legacy industrial deployments.
- Capacitive:Transparent conductive layers—typically indium tin oxide or metal mesh—detect finger contact through electrical coupling. Automotive OEMs in Germany and South Korea specify bonded capacitive stacks for curved instrument clusters, driving oxide-TFT line conversions.
- Resistive:Pressure-sensitive conductive layers separated by spacer dots respond to mechanical deformation. Industrial terminals and legacy retail POS systems in the United States retain resistive panels where gloved operation outweighs gesture precision requirements.
- Optical:Image sensors track touch points through display backlight interruption. Extra-large format deployments in transit hubs favor optical durability against public abrasion.
- Infrared:LED arrays and photodetectors create invisible touch grids above display surfaces. Museum and wayfinding installations specify infrared for vandal-resistant operation without surface lamination.
The dominant share belongs to Capacitive, while Metal mesh variants within this category are closing the gap fastest in automotive curved surfaces.
End User:
Application-specific certification requirements fragment procurement, with automotive ASIL-D grades and medical ISO 13406-2 tolerances creating distinct qualification barriers.
- Automotive:Bonded optical stacks must survive thermal cycling and vibration per ECE R10 specifications. NHTSA safety-critical instrument cluster migration is forcing controller suppliers to meet functional safety grades that extend software validation cycles.
- Healthcare:Medical-grade panels require sub-pixel defect tolerance testing under ISO 13406-2 classification. Diagnostic imaging and surgical navigation systems in the United States and Germany specify antimicrobial surface treatments and sealed enclosures.
- Industrial:HMI terminals in manufacturing floors prioritize electromagnetic immunity and wide temperature operation. FCC Part 15 emissions compliance gates North American access for capacitive controllers deployed in factory automation.
- Retail:Self-service kiosks and POS terminals balance cost against durability. EU Ecodesign Directive power thresholds accelerate low-power oxide-TFT adoption in commercial signage across France and Italy.
Automotive commands the steepest pricing tier, while Healthcare is expanding most quickly through diagnostic display upgrades.
Technology:
Gesture complexity determines controller architecture and firmware integration burden, with multi-layer sensing stacks multiplying validation cycles.
- Multi-Touch:Mutual-capacitance arrays track ten or more simultaneous contact points. Premium smartphones and automotive consoles specify multi-touch for pinch-zoom and rotation gestures.
- Single-Touch:Self-capacitance or resistive sensing registers one contact point. Cost-optimized industrial panels and legacy retail terminals deploy single-touch where interaction complexity remains minimal.
- 3D Touch:Force-sensitive layers detect pressure magnitude alongside position. Previous smartphone flagship implementations have contracted as manufacturers prioritize display refresh rates over pressure sensing.
- Holographic:Volumetric displays project touch-interactive imagery into free space. Niche deployments in medical visualization and automotive concept vehicles remain pre-commercial.
Multi-Touch retains volume leadership, while Holographic approaches are gaining share fastest in specialized visualization applications.
Size:
Manufacturing equipment and substrate handling constraints create distinct cost curves, with Gen 10.5 oxide-TFT lines optimized for extra-large formats.
- Extra Large:Diagonal dimensions exceeding 65 inches dominate digital signage and collaborative conferencing. BOE Technology leverages captive Gen 10.5 capacity to anchor supply for this category.
- Large:32-65 inch panels serve automotive consoles and commercial kiosks. Curved form factors in this range require metal mesh alternatives to ITO brittleness.
- Medium:10-32 inch formats cover industrial HMI and medical monitors. In-cell touch integration reduces stack thickness for slim-profile applications.
- Small:Sub-10 inch panels saturate consumer mobile and wearables. Indium supply concentration from Chinese and South Korean smelters exposes ITO sputtering target costs to disruption.
Medium formats dominate shipment volume, while Extra Large is climbing the fastest through signage replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement and display fab concentration drive geographic demand patterns. South Korea and China dominate manufacturing capacity. Germany and the United States anchor premium automotive specification development. Japan sustains materials and equipment supply chains.
United States
Automotive OEMs in Detroit and Silicon Valley specify ASIL-D grade touch controllers for instrument cluster migration. NHTSA safety-critical reliability specifications extend software validation cycles for suppliers. The Southeast manufacturing corridor hosts bonded stack assembly for domestic EV production.
Germany
BMW, Mercedes-Benz, and Volkswagen consolidate procurement around vertically integrated module suppliers with captive optical bonding assets. ECE R10 automotive electromagnetic compatibility regulations gate market access for controller firmware. The Baden-Württemberg electronics corridor concentrates Tier-1 supplier engineering centers.
South Korea
Samsung Display and LG Display anchor the Gyeonggi-do manufacturing belt with captive Gen 6 and Gen 8.5 oxide-TFT lines. MFDS medical device regulations intersect with ISO 13406-2 for diagnostic imaging panel qualification. The Busan-Ulsan port complex handles indium concentrate imports for ITO sputtering target production.
China
BOE Technology leverages Beijing and Hefei Gen 10.5 fabs for extra-large format commercial display output. GB 4943.1 safety standards enforce touch surface temperature thresholds that reshape stack designs for export manufacturing. The Yangtze River Delta cluster concentrates metal mesh sensor etching capacity.
Japan
Equipment makers in Nagoya and Osaka supply oxide-TFT deposition systems for automotive curved form factor retooling. METI industrial policy supports alternative transparent conductor R&D in response to REACH indium restrictions. The Kyushu materials corridor refines high-purity indium for sputtering target production.
Touch Screen Display Market Key Industry Players
Player mix skews toward vertically integrated display fabs with captive touch sensor capacity. Market structure concentrates around three Korean and Chinese manufacturers controlling oxide-TFT line output. Strategic archetypes include: bonded stack specialists serving automotive ASIL-D grades; cost-optimized single-sensor suppliers for retail POS; and in-cell touch integrators for slim-profile mobile and console applications. Dominant competitive moves span capacity expansion into Gen 10.5 lines and strategic partnerships with automotive Tier-1s for module supply.
Within the vertically integrated tier, Samsung Display, LG Display, and BOE Technology occupy positions that exemplify the bifurcation between premium automotive bonded stacks and commoditized consumer single-sensor solutions. Samsung Display represents the quantum-dot OLED integration archetype for premium console applications. LG Display anchors the in-cell touch specialization vector for slim-profile deployments. BOE Technology sits within the extra-large format scale-driven segment through captive Gen 10.5 capacity.
| Leading Market Players |
|---|
| ELO Touch Solutions |
| BOE Technology |
| Samsung Display |
| AIS |
| Biamp Systems |
| LG Display |
| AU Optronics |
| New Vision Display |
| Panox Display |
| Others |
Cost & Logistics Intelligence
ECE R10 automotive electromagnetic compatibility certification gates both supplier qualification timelines and price differentiation across bonded optical stack tiers simultaneously. OEM procurement consolidation around ASIL-D grade controllers compresses margins for non-qualified suppliers while concentrating premium pricing power with vertically integrated module makers.
Pricing Analysis
Cost-plus contracts with indium price indexation dominate ITO sputtering target procurement. Pricing stratifies across automotive ASIL-D, industrial ISO 13406-2, and consumer economy tiers based on certification grade and volume scale. Cost compression in consumer capacitive panels intensifies due to metal mesh substitution, while automotive buyers show lowest price sensitivity given liability exposure and safety-critical integration requirements.
Supply Chain Analysis
Busan-Ulsan port transit underwrites indium concentrate flows from Chinese and South Korean smelters to ITO target manufacturers. The supply chain draws from Japanese equipment makers for oxide-TFT deposition systems, Chinese metal mesh etching capacity, and Korean Gen 8.5+ fab output. Single-source vulnerability concentrates in indium refining, while distribution runs through vertically integrated panel makers with captive lamination assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The touch screen display market represents a high-growth disruption as NHTSA instrument cluster safety mandates force ASIL-D controller migration across automotive lineups. This regulatory inflection compresses supplier qualification windows while expanding addressable value pools for certified module providers.
For Market Incumbents: Secure backward integration into cover glass and optical bonding assets to defend against Tier-1 supplier consolidation. Reinforce oxide-TFT line positions in Gen 8.5+ formats as Korean and Chinese competitors expand captive capacity. Prioritize ECE R10 and ASIL-D certification maintenance as non-compliant suppliers face exclusion from German and US automotive procurement. For New Entrants and Emerging Players: Differentiate on metal mesh sensor architectures for curved automotive surfaces where ITO brittleness creates technical barriers. Target extra-large format digital signage in transit hubs where infrared durability requirements favor new optical touch variants. Pursue white-label module supply partnerships with commercial kiosk OEMs seeking alternatives to dominant Korean panel sources. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Gen 10.5 oxide-TFT fab expansions, favoring scaled incumbents over greenfield entrants. Long-term viability over the next decade rests on certification moats rather than commodity panel volume. Acquisition targets should display captive lamination capability plus automotive Tier-1 relationships. Watch indium price volatility and REACH regulatory expansion as signals for alternative transparent conductor substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive ASIL-D Certification Investment | ECE R10 compliance gates German OEM procurement and enables premium module pricing. |
| Gen 10.5 Oxide-TFT Capacity Expansion | BOE Technology's Beijing-Hefei footprint anchors extra-large format commercial display supply. |
| Metal Mesh Sensor Qualification | Copper mesh alternatives displace ITO in curved automotive consoles from BMW and Mercedes-Benz. |
| In-Cell Touch Architecture Integration | LG Display's slim-profile specialization captures mobile and automotive console design wins. |
| Indium Supply Diversification | Japanese Kyushu refining capacity reduces concentrate dependence on Chinese smelters. |
Research Approach
A spread of perspectives from automotive platform engineers, display fab procurement directors, Tier-1 supplier quality managers, and touch controller IC designers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs trade data, and IHS Markit vehicle production databases. Bottom-up segment sizing triangulated against top-down industry value chain estimates.
Segmentation dimensions modeled span product type, end user certification grade, gesture complexity tier, and diagonal size class across the projection horizon. CAGRs derived from fitted growth curves applied to unit shipment and average selling price trajectories. Forecast inputs incorporated oxide-TFT line conversion schedules, automotive content-per-vehicle assumptions, and REACH regulatory phase-in timelines.
Material uncertainties — indium supply disruptions, ASIL-D certification delays, and alternative transparent conductor substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as automotive electrification penetration and regulatory enforcement evolve. Practitioners should keep alternative scenarios live as Ecodesign Directive power thresholds and NHTSA safety-critical mandates tighten.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Interactive Video Wall Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Global Display Controllers Market
Display Technologies
Multi-Function Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Backlit Displays Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
3D Holographic Display Market
Display Technologies
Electrochromic Window Market
Display Technologies
Flexible OLED Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Portable Projector Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
4K VR Displays Market
Display Technologies
United States Microdisplay Market
Display Technologies
Paper-Thin Display Market