
 Global Medical Display Market | 2026-2036
Global Medical Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Display Market Foresight
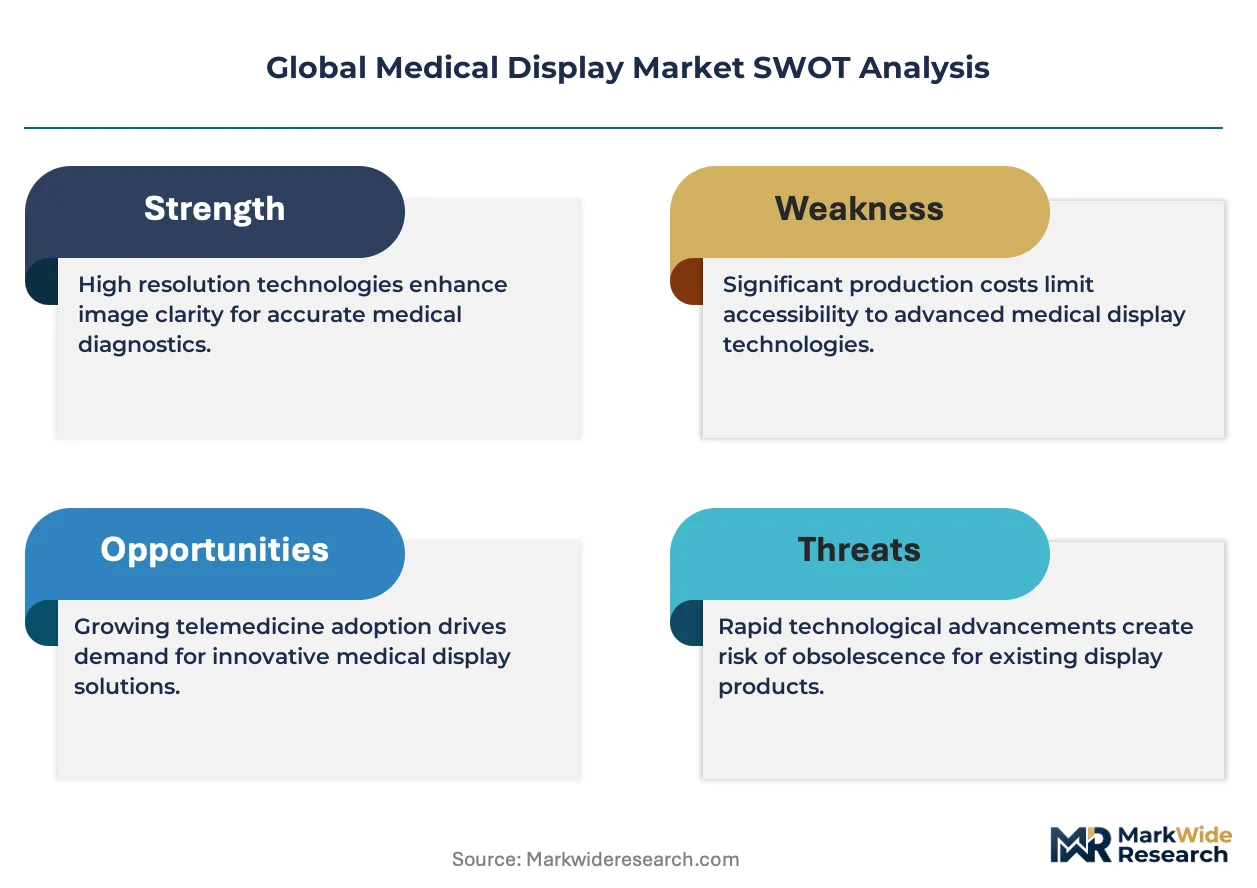
MDR compliance is expanding the cost-of-entry calculus for display manufacturers seeking European market access. EIZO Corporation leverages in-house calibration systems to sustain premium positioning across radiology workstations. Barco anchors its surgical display franchise through dedicated visualization R&D centers in Belgium and the United States. Sony Corporation differentiates by controlling image sensor-to-display color pipelines for endoscopy suites.
Medical displays are precision-calibrated visualization devices engineered to reproduce grayscale and color accuracy within tight DICOM Part 14 tolerances, serving diagnostic interpretation and intraoperative guidance where visual fidelity directly affects clinical outcomes. Diagnostic monitors occupy the highest margin tier due to luminance stability requirements and extended warranty obligations, while surgical displays are gaining share fastest as hybrid operating rooms proliferate across hospital systems. LCD technology still dominates unit volumes though OLED panels are capturing premium niches in pathology and surgical applications where contrast ratio thresholds exceed liquid crystal capabilities.
FDA premarket notification pathways, EU MDR technical documentation requirements, and IEC 60601-1 third-edition electrical safety standards collectively shape product development timelines and certification expenditures for display vendors. Japan's PMDA enforces supplementary quality management protocols that filter out smaller competitors lacking dedicated regulatory affairs infrastructure. Stakeholders must monitor how AI-integrated diagnostic workstations trigger reclassification debates at multiple regulators simultaneously.
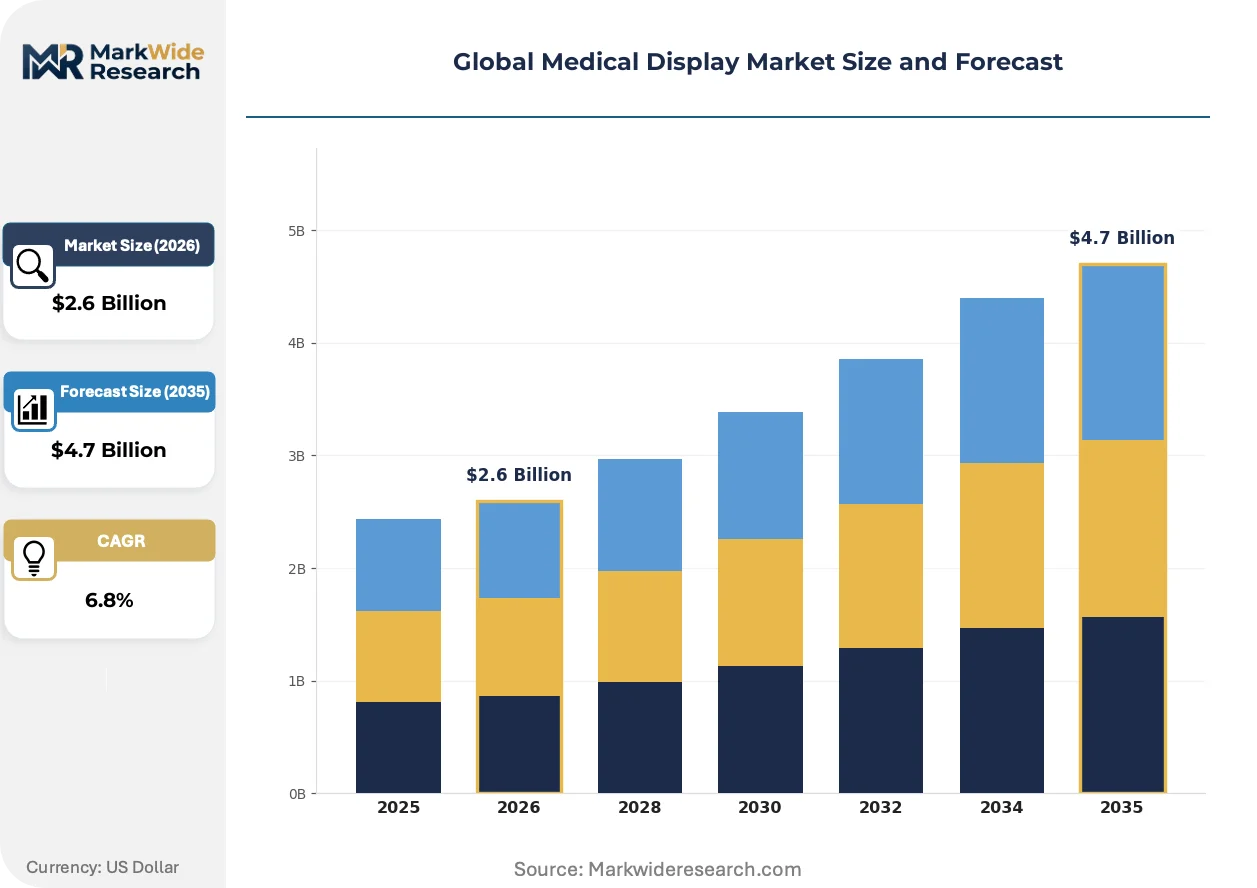
Market Dynamics
Hybrid operating room construction is compressing replacement cycles for surgical displays while EU MDR technical documentation requirements extend certification timelines for diagnostic monitor vendors seeking European market access.
Growth Catalysts
- EU MDR compliance mandates:Tighter premarket review pathways for software-integrated displays are filtering out marginal competitors and consolidating procurement toward certified vendors in tertiary hospital systems.
- OLED contrast ratio thresholds:Pathology laboratories and endoscopy suites are adopting organic light-emitting diode panels where liquid crystal capabilities fall short of clinical visualization requirements.
- Japan replacement acceleration:Capital equipment refresh cycles in diagnostic imaging departments are compressing as PMDA quality management protocols drive infrastructure modernization.
Market Restraints
- Indium supply concentration:OLED manufacturing depends on indium tin oxide substrates sourced predominantly from Chinese refining operations, creating input cost volatility and geopolitical exposure.
- IEC 60601-1 third-edition compliance:Electrical safety certification expenditures for display vendors have escalated substantially, extending product development timelines and freezing smaller manufacturers from market participation.
- Extended warranty obligations:Diagnostic monitors require luminance stability guarantees spanning five to seven years, compressing margin structures and elevating service infrastructure costs.
Strategic Opportunities
- AI-integrated workstation reclassification:Regulatory debates at FDA and EMA over software-as-medical-device displays are creating first-mover advantages for vendors with established quality management systems.
- German hospital consolidation:Tertiary care network mergers are standardizing procurement specifications across multi-site radiology departments, favoring vendors with scalable calibration infrastructure.
- Telepathology distribution channels:Remote diagnostic networks are opening subscription-based display-as-a-service models for community laboratories lacking capital equipment budgets.
Industry Challenges
- DICOM Part 14 calibration expertise:Precision grayscale reproduction engineering talent remains scarce, forcing vendors to maintain dedicated in-house metrology teams or outsource to specialized service providers.
- Legacy PACS integration complexity:New display installations must interface with decade-old picture archiving systems, requiring custom middleware development and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Display Market |
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Monitors, Surgical Displays, Clinical Review Monitors, Patient Monitoring Displays, Portable Medical Displays Technology: LCD, OLED, LED, Touch Screen, 3D Display, MicroLED Application: Radiology, Surgery, Endoscopy, Pathology, Telemedicine, Veterinary Medicine End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Research Laboratories, Ambulatory Surgical Centers |
| Companies Covered | LG Electronics, Novanta Inc., Barco, NEC Corporation, Advantech Co., Ltd., EIZO Corporation, Siemens Healthineers, BenQ Medical Technology, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Display Market Shifts & Advancements
Display technology convergence with artificial intelligence inference engines is redefining workstation architectures, while regulatory harmonization efforts across FDA, EMA, and PMDA are reshaping certification strategies for multi-jurisdictional vendors.
Mini-LED local dimming arrays are expanding into surgical visualization applications where high dynamic range reproduction supports fluorescence-guided procedures. Hybrid operating room construction teams specify these panels for neurosurgery and cardiac suites. The technology is expanding into premium niches previously reserved for full OLED implementations, compressing price thresholds for high-contrast surgical displays.
FDA's evolving premarket notification pathways for AI-integrated diagnostic workstations are extending review timelines and triggering reclassification debates. Software-enabled displays capable of real-time image enhancement now face heightened scrutiny. Radiology workstation vendors are responding by segregating hardware and algorithm submissions, fragmenting product development roadmaps.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisitions, forcing display manufacturers to compete on calibration and maintenance pricing separately from panel sales. Integrated delivery networks in the United States are driving this behavior through centralized capital committees. German hospital procurement associations have adopted similar unbundling standards, compressing service margin structures across European markets.
Global Medical Display Market Segmentation
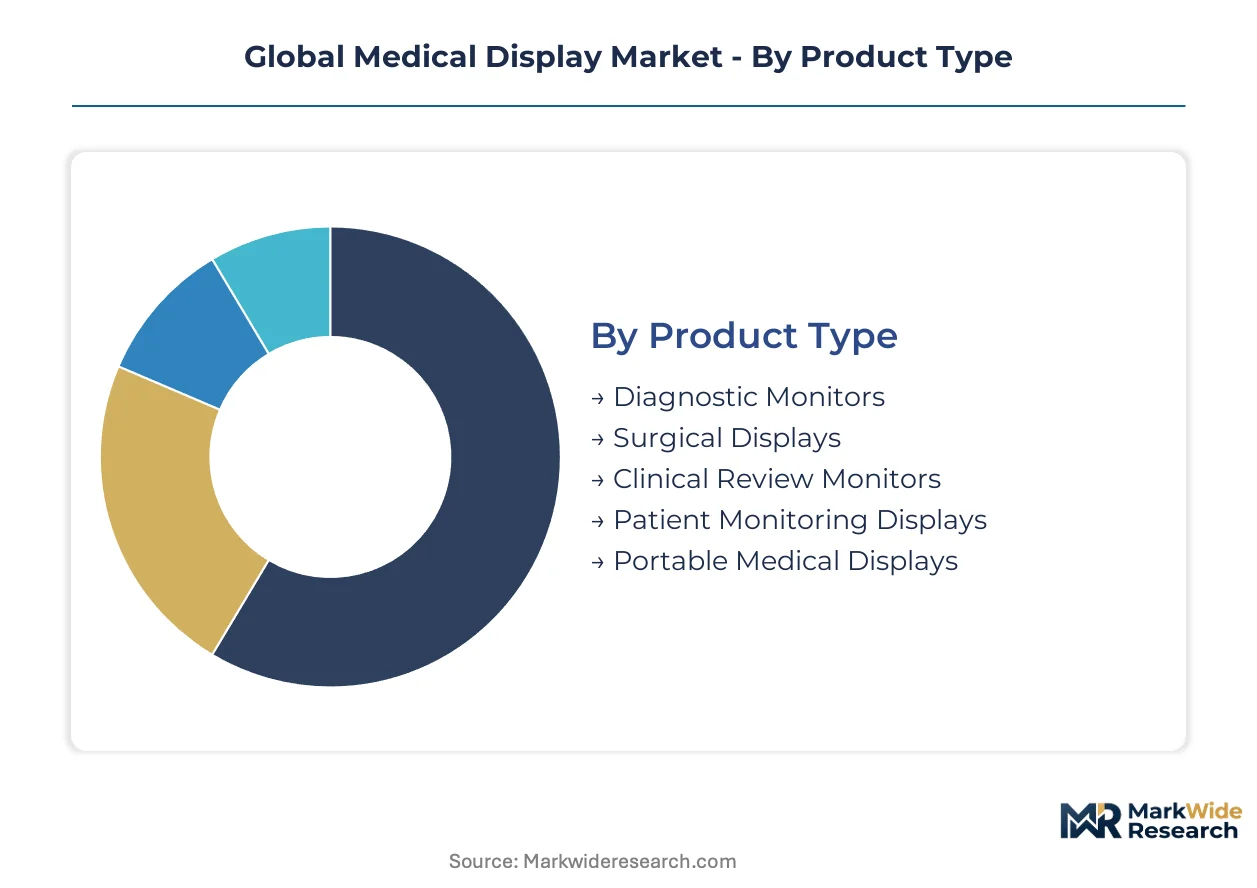
Medical display segmentation reveals how precision requirements fragment procurement patterns across clinical workflows. Technical specifications diverge sharply between diagnostic interpretation and intraoperative visualization, creating distinct margin architectures that vendors must navigate simultaneously.
Product Type:
Supply concentration in panel manufacturing favors vendors with captive calibration infrastructure and extended service networks.
- Diagnostic Monitors:Grayscale luminance stability within DICOM Part 14 tolerances defines technical performance. Tertiary hospital radiology departments in Germany and Japan concentrate replacement demand as PMDA and EU MDR compliance timelines compress procurement decisions.
- Surgical Displays:High-brightness panels engineered for ambient light tolerance in hybrid operating rooms. Hybrid OR construction across United States hospital systems is accelerating refresh cycles for fluorescence-compatible visualization systems.
- Clinical Review Monitors:Secondary interpretation displays with relaxed calibration requirements serve ward-based consultation workflows.
- Patient Monitoring Displays:Bedside vital sign visualization with continuous operation reliability specifications.
- Portable Medical Displays:Mobile diagnostic review units for point-of-care deployment in field and emergency settings.
Diagnostic monitors absorb the bulk of installed capacity; surgical displays are expanding most quickly.
Technology:
Cost tier differentiation separates premium OLED implementations from volume LCD deployments across hospital capital budgets.
- LCD:Dominant volume technology leveraging mature manufacturing scale. Panel supply concentrates in South Korean and Chinese fabrication facilities serving price-sensitive clinical review and patient monitoring applications.
- OLED:Self-emissive architecture delivering contrast ratios exceeding liquid crystal capabilities for pathology and surgical visualization where fluorescence detection demands precise black-level reproduction.
- LED:Backlight-enhanced variants extending LCD performance envelopes for mid-tier diagnostic implementations.
- Touch Screen:Sterilizable capacitive interfaces for surgical navigation and interventional radiology control surfaces.
- 3D Display:Stereoscopic visualization for preoperative planning and complex anatomical review in neurosurgical suites.
- MicroLED:Emerging emissive technology targeting eventual displacement of OLED in premium surgical applications.
LCD retains the dominant share of unit shipments; OLED is climbing the fastest as pathology laboratories upgrade visualization infrastructure.
Application:
Customer type segmentation separates high-acuity diagnostic interpretation from procedural guidance workflows with distinct regulatory pathways.
- Radiology:Primary diagnostic interpretation requiring grayscale calibration traceability. United States academic medical centers and German university hospitals drive demand for multi-head workstation configurations.
- Surgery:Real-time visualization for open and minimally invasive procedures. Hybrid OR construction in Japan and United States health systems is standardizing on large-format 4K panels.
- Endoscopy:Color-critical pipelines for gastrointestinal and pulmonary diagnostic procedures.
- Pathology:Whole-slide imaging review demanding color consistency across networked consultation platforms.
- Telemedicine:Remote diagnostic consultation displays for distributed clinical networks.
- Veterinary Medicine:Cross-adapted diagnostic and surgical visualization for companion and livestock animal care.
Radiology commands the largest installed base; surgery is gaining share fastest as procedural volume shifts to image-guided interventions.
End User:
Geography and maturity factors concentrate procurement authority in consolidated health systems versus fragmented outpatient settings.
- Hospitals:Integrated delivery networks with centralized capital committees in United States and German tertiary systems. Multi-site standardization programs favor vendors with scalable calibration service infrastructure.
- Outpatient Clinics:Distributed primary and specialty care settings with constrained equipment budgets and simplified technical requirements.
- Diagnostic Centers:Independent imaging facilities with high-utilization workflows demanding rapid turnaround on maintenance contracts.
- Research Laboratories:Preclinical and clinical trial visualization with specialized color space and resolution requirements.
- Ambulatory Surgical Centers:Procedure-focused facilities prioritizing compact form factors and rapid installation timelines.
Hospitals absorb the dominant share of premium diagnostic monitor procurement; ambulatory surgical centers are expanding most quickly as procedural migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates in German, United States, and Japanese hospital systems where capital equipment replacement cycles are compressing. Tertiary care network consolidation is standardizing display specifications across multi-site radiology departments. Regulatory divergence between FDA, EU MDR, and PMDA compliance timelines is fragmenting vendor certification strategies.
United States
Academic medical centers in Boston and the Research Triangle are driving multi-head workstation configurations for diagnostic interpretation. FDA premarket notification pathways for AI-integrated displays are extending review timelines and triggering reclassification debates. Integrated delivery networks with centralized capital committees in California and Texas are unbundling service contracts from hardware acquisitions.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are concentrating demand for grayscale-calibrated diagnostic monitors. EU MDR technical documentation requirements are filtering out smaller competitors lacking dedicated regulatory affairs infrastructure. The Berlin-Brandenburg cluster hosts visualization R&D centers serving hybrid operating room construction across Central European health systems.
Japan
Diagnostic imaging departments in Tokyo and Osaka are accelerating capital equipment refresh cycles. PMDA quality management protocols enforce supplementary certification standards that elevate compliance expenditures for display vendors. The Nagoya industrial corridor anchors panel manufacturing partnerships serving domestic hospital procurement.
China
Tier-3 hospital construction in Shanghai and Guangzhou is expanding clinical review monitor installations. NMPA medical device registration pathways are harmonizing with IEC 60601-1 electrical safety standards. The Yangtze River Delta concentrates LCD panel fabrication serving price-sensitive patient monitoring applications.
South Korea
Seoul-based hospital systems are adopting OLED surgical displays for fluorescence-guided procedures. MFDS quality system regulations align with MDR technical documentation requirements for European market access. The Busan-Ulsan corridor hosts backlight-enhanced LED manufacturing for mid-tier diagnostic implementations.
Global Medical Display Market Competitive Landscape
Japanese and Belgian producers anchor the premium calibration tier; South Korean and Taiwanese fabricators hold volume positions in panel supply. The vendor structure stratifies across three tiers: integrated healthcare conglomerates with captive display divisions, specialized visualization firms with dedicated metrology infrastructure, and contract manufacturers serving price-sensitive segments. Competitive maneuvering concentrates on M&A to secure calibration expertise and strategic partnerships to access hospital procurement networks.
Among specialized visualization firms, EIZO Corporation and Barco exemplify the premium-tier archetype through in-house calibration systems and dedicated R&D infrastructure. Sony Corporation occupies a position controlling image sensor-to-display color pipelines for endoscopy suites. LG Electronics represents the scale-driven fabricant supplying panel technologies across multiple clinical application tiers.
| Leading Market Players |
|---|
| LG Electronics |
| Novanta Inc. |
| Barco |
| NEC Corporation |
| Advantech Co., Ltd. |
| EIZO Corporation |
| Siemens Healthineers |
| BenQ Medical Technology |
| Sony Corporation |
| Others |
Supply & Pricing Matrix
Captive calibration infrastructure anchors both supply security and margin protection for display vendors serving diagnostic radiology departments. Manufacturers controlling in-house metrology teams command pricing premiums while insulating procurement committees from third-party service volatility.
Pricing Analysis
Volume shipments cluster in patient monitoring and clinical review tiers where LCD panel commoditization compresses margins, while diagnostic monitors sustain premium positioning through DICOM Part 14 certification requirements. Price differentiation rests on luminance stability guarantees and extended warranty obligations spanning five to seven years. Cost compression in surgical display tiers is intensifying as Mini-LED backlights displace full OLED implementations in hybrid operating room specifications. Outpatient clinics and ambulatory surgical centers exhibit highest price sensitivity, whereas German university hospitals and United States academic medical centers prioritize calibration traceability over unit cost.
Supply Chain Analysis
IEC 60601-1 third-edition electrical safety certification filters panel sourcing to qualified fabricators in South Korea, Japan, and Taiwan. Indium tin oxide substrates for OLED manufacturing draw from Chinese refining operations, creating single-source vulnerability for premium surgical display production. Tariff exposure concentrates on backlight-enhanced LED components shipped through the Busan-Ulsan manufacturing corridor. Distribution runs through hospital GPO contracts and specialized medical device distributors serving tertiary care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in active display technology transition as Mini-LED local dimming arrays displace full OLED implementations across premium surgical visualization tiers.
For Market Incumbents: Deepen captive calibration infrastructure to defend margin position against emerging entrants offering unbundled service contracts. Expand metrology team capacity in Germany and Japan where PMDA and EU MDR compliance timelines compress procurement decisions. Target hybrid operating room construction pipelines in United States health systems before Mini-LED price thresholds fully commoditize surgical display tiers. For New Entrants and Emerging Players: Telepathology platform operators represent the most penetrable channel partner type for subscription-based display-as-a-service models. Community laboratories in distributed diagnostic networks lack capital equipment budgets for DICOM-calibrated workstations. Target fluorescence-guided surgery niches where OLED contrast ratio requirements still exceed liquid crystal capabilities and incumbent positioning remains incomplete. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated healthcare conglomerates seeking captive visualization divisions. Long-term viability favors vendors with established FDA premarket notification track records and scalable quality management systems. Monitor regulatory reclassification debates at FDA and EMA over AI-integrated diagnostic workstations as the critical inflection signal for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates European market access for software-integrated display vendors ahead of compliance deadlines. |
| Hospital System Partnership | Locks multi-site standardization contracts across German tertiary care network consolidations. |
| Mini-LED Surgical Display Launch | Captures hybrid OR construction demand in United States academic medical centers. |
| Calibration Service Infrastructure Expansion | Defends margin structure against procurement committee unbundling of after-sales contracts. |
| AI Workstation Reclassification Strategy | Positions vendors for first-mover advantage as FDA extends review timelines for software-as-medical-device displays. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, and PMDA quality management protocols, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, and IEC 60601-1 third-edition certification records. Bottom-up demand modeling across diagnostic imaging departments was cross-referenced with top-down vendor shipment estimates.
Historical revenue trajectories were cross-referenced against panel input cost indices and regulatory compliance expenditure patterns. Segmentation dimensions included product type, display technology, clinical application, and end-user facility tier. CAGRs were derived from replacement cycle compression rates in Japan and Germany, OLED penetration assumptions in pathology laboratories, and hybrid operating room construction forecasts across United States health systems.
Caveats apply where indium supply disruptions, regulatory reclassification of AI-integrated workstations, or accelerated Mini-LED cost declines could materially shift the outlook. A model refresh is warranted upon material change in FDA premarket review timelines for software-as-medical-device displays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electrochromic Window Market
Display Technologies
Foldable Display Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Global Display Panel Market
Display Technologies
Portable Video Wall Market
Display Technologies
Display Port Market
Display Technologies
3D Display Module Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Display Mask Market
Display Technologies
Portable Projector Market
Display Technologies
Interferometric Modulator Display Market