
 Global Next Generation Display Market | 2026-2036
Global Next Generation Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Display Market Intelligence
Manufacturing capacity for MicroLED panels is shifting towards new large-scale fabrication plants in South Korea and Taiwan to address future demand from television OEMs. Samsung Electronics leverages its dominant position in OLED production for the premium smartphone market. LG Display specializes in large-format OLEDs for high-end televisions and digital signage. Meanwhile, AUO Corporation competes by offering specialized display solutions for automotive instrument panels and industrial equipment, focusing on durability and performance.
Next generation displays encompass technologies that offer significant improvements over conventional LCDs in color accuracy, contrast, power efficiency, and form factor. These displays, such as OLEDs with self-emissive pixels or MicroLEDs using inorganic light-emitting diodes, enable novel applications. Their primary purpose is to create more immersive, flexible, and interactive visual interfaces in consumer and commercial products. While OLED technology currently leads in high-value applications like smartphones, the foldable screens category is expanding rapidly. Automotive instrument panels represent a critical growth application for advanced, durable displays.
Regulatory frameworks directly influence material composition and energy consumption in display manufacturing. The European Union's RoHS directive restricts the use of hazardous materials, impacting component sourcing for companies selling into Europe. In parallel, the US EPA's ENERGY STAR program sets voluntary energy efficiency benchmarks that guide product design for television OEMs and monitor manufacturers. China's GB standards also impose strict quality and safety requirements on electronic components. Stakeholders must navigate the strategic decision of scaling mature OLED production versus investing in emerging MicroLED technology.
Market Dynamics
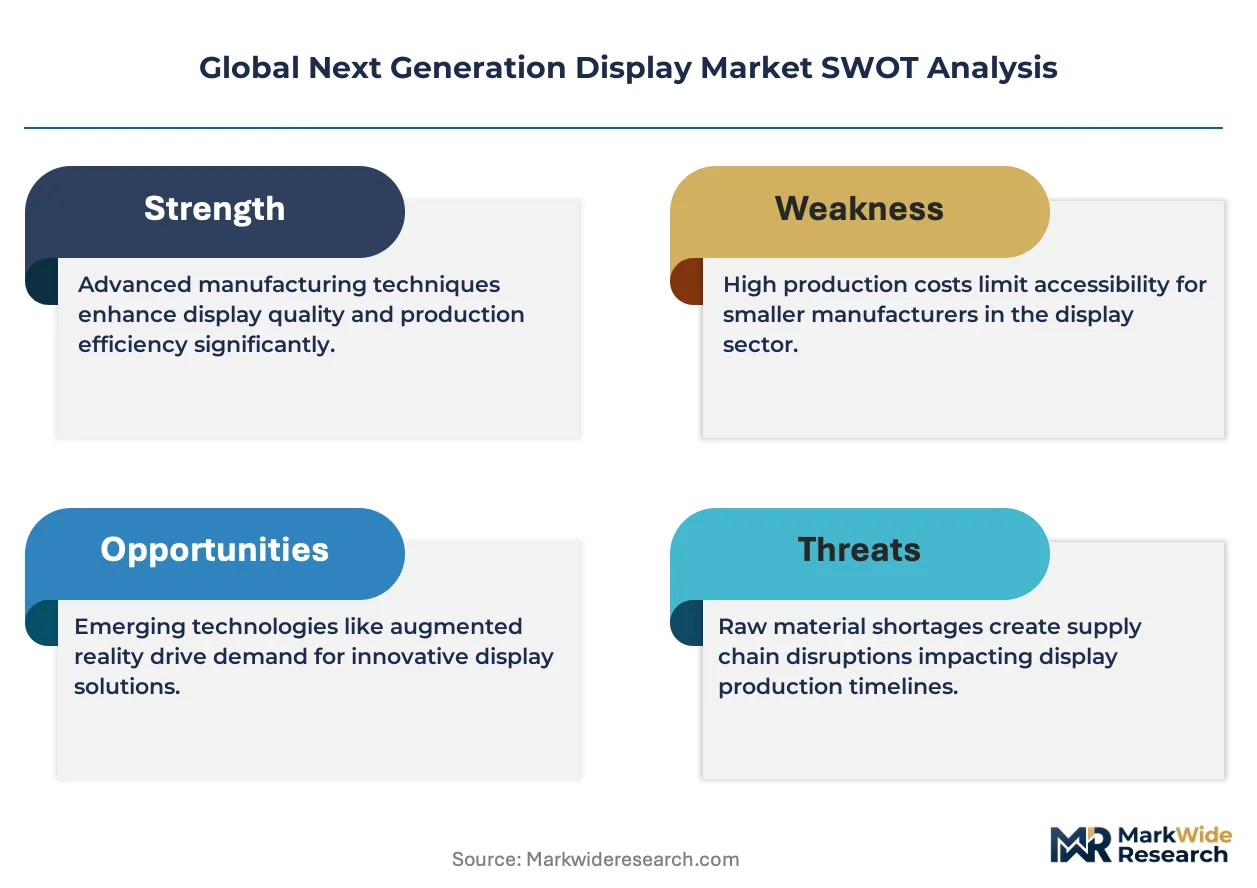
The central force shaping the market is the capital-intensive race between scaling mature OLED production and pioneering nascent MicroLED fabrication. This creates a strategic dilemma for manufacturers balancing current market demand for proven technologies against the long-term potential of emerging, more durable display platforms.
Growth Catalysts
- Foldable/Flexible Screens:Consumer electronics demand for novel smartphone form factors accelerates R&D in flexible substrates and thin-film encapsulation.
- Automotive Sector Integration:The automotive industry’s shift to digital cockpits and large infotainment systems creates a high-value market for durable displays.
- Manufacturing Investment:New fabrication plants in South Korea and Taiwan are expanding capacity to meet future television OEM demand for advanced panels.
Market Restraints
- High Production Costs:Capital expenditure for MicroLED mass transfer equipment and low initial manufacturing yields inhibit cost-competitiveness against mature OLED technology.
- Material Sourcing Dependencies:The supply chain for essential organic compounds used in OLEDs is highly concentrated, creating risks of price volatility and disruption.
- Technical Hurdles:Achieving color uniformity and efficiency for blue emitters in MicroLEDs remains a significant barrier to mass production and adoption.
Strategic Opportunities
- Augmented Reality Microdisplays:The AR/VR sector requires high-pixel-density, low-latency microdisplays, creating a new frontier for technologies like MicroOLED and MicroLED.
- Energy Efficiency Mandates:Stricter ecodesign regulations in Europe and the US EPA's ENERGY STAR program favor self-emissive displays over less efficient LCDs.
- Smart Textile Integration:The convergence of flexible display technology with fabrics opens opportunities in wearable computing and interactive architectural surfaces.
Industry Challenges
- Manufacturing Yield Scalability:Scaling mass transfer processes for MicroLEDs to achieve consistent, defect-free yields on large-area substrates is a primary operational hurdle for fabricators.
- Intellectual Property Navigation:A dense patent landscape surrounding MicroLED fabrication, particularly mass transfer techniques, creates significant licensing complexity and risk of litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Display Market |
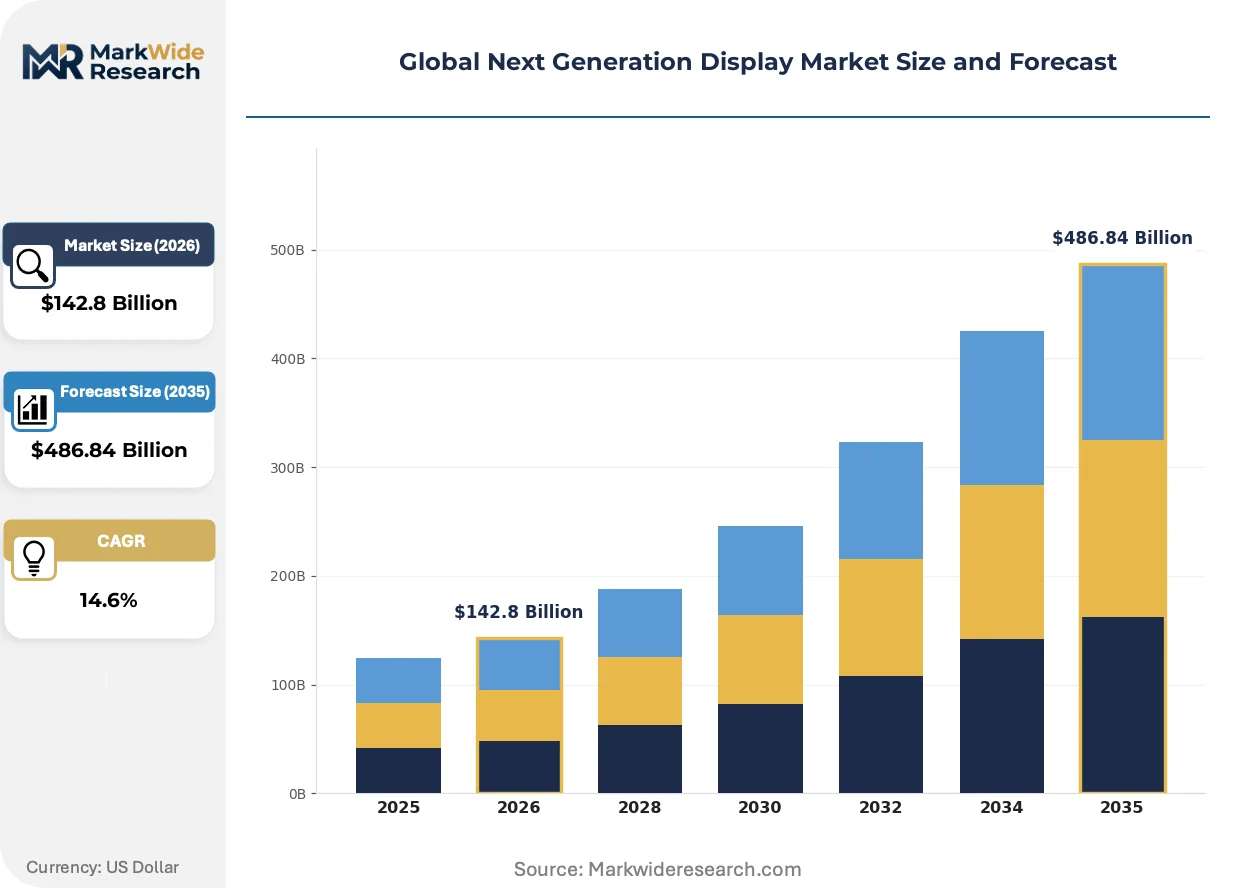
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $486.84 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, QLED, MicroLED, E-Ink, LCD, Quantum Dot Technology: Flexible Displays, Transparent Displays, 3D Displays, Foldable Screens, Touchscreen, Curved Displays Application: Consumer Electronics, Wearable Devices, Digital Signage, Automotive Instrument Panels, Aviation Cockpit Displays, Gaming Devices End User Industry: Smartphone Manufacturers, Television OEMs, Advertising Agencies, Vehicle Manufacturers, Aerospace Companies, Gaming Hardware Producers |
| Companies Covered | AUO Corporation, Japan Display, Samsung Electronics, Apple, Universal Display Corporation, LG Display, Innolux Corporation, Sony, BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Display Market Strategic Shifts & Innovations
Application-specific design is fundamentally altering product development, moving the industry away from standardized panels toward customized display solutions integrated into final product forms. This shift prioritizes form factor, durability, and environmental performance alongside visual quality.
MicroLED technology utilizes arrays of microscopic inorganic LEDs to form individual, self-emissive pixels, offering superior brightness and longevity. It is being adopted by developers of large-format digital signage and premium home cinema systems. This technology is modularizing display construction, enabling seamless, scalable video walls of custom sizes and non-standard aspect ratios.
The European Union's RoHS directive restricts hazardous materials like cadmium in electronic components, impacting quantum dot chemistries. This regulation forces material science innovation to develop compliant, high-performance alternatives for displays sold in Europe. Panel makers must now validate their component sourcing to meet these strict environmental standards.
A significant behavioral shift involves integrating displays as structural or aesthetic elements, not merely as functional screens. This trend disrupts the traditional flat-panel-in-a-bezel design, particularly within automotive interiors and consumer appliance design. This evolution is most visible in the automotive sector, where curved displays are molded into dashboards in German and South Korean vehicles.
Global Next Generation Display Market Segmentation
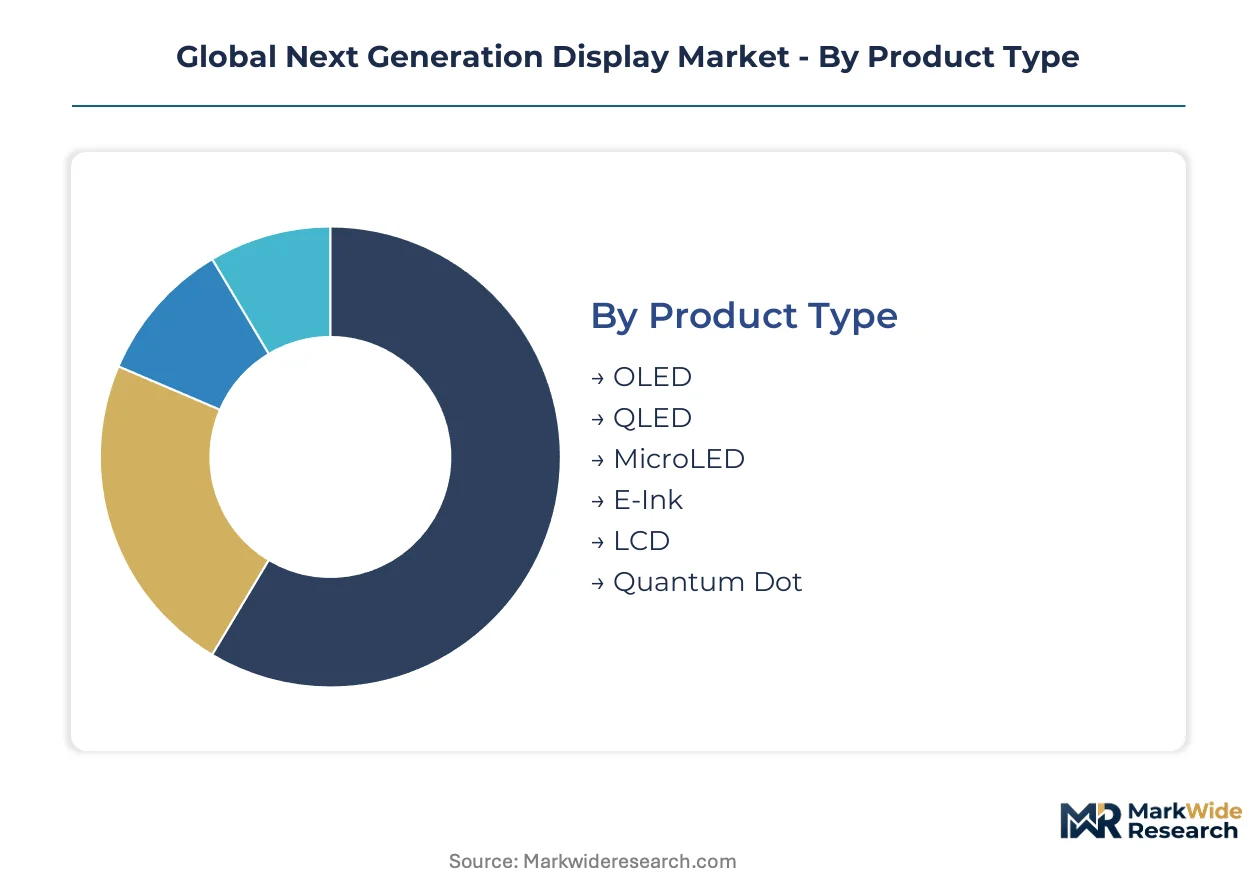
The global next generation display market is segmented to understand distinct technology adoption patterns and end-user requirements. Each segment highlights specific performance attributes and application areas driving innovation. This detailed classification helps manufacturers align product development with evolving consumer and industrial demands.
Product Type:
Manufacturers continuously evaluate product types based on their upgrade cycle potential and replacement market dynamics.
- OLED:Organic Light Emitting Diodes utilize self-emissive pixels, delivering superior contrast and color accuracy. Demand concentrates in premium smartphone and high-end television markets due to their visual performance.
- MicroLED:Microscopic inorganic LEDs form individual pixels, offering exceptional brightness, longevity, and energy efficiency. Demand is emerging from large-format digital signage and future television OEMs seeking modular solutions.
- QLED:Quantum Dot Light Emitting Diodes enhance LCD panels with quantum dots for improved color volume and brightness.
- E-Ink:Electrophoretic displays offer ultra-low power consumption and paper-like readability, primarily used in e-readers.
- LCD:Liquid Crystal Displays utilize a backlight and liquid crystals, remaining a cost-effective option for various consumer electronics.
- Quantum Dot:These nanocrystals emit light at specific wavelengths when illuminated, enhancing color purity in display backlights.
Volume placements concentrate in LCD; the faster expansion belongs to MicroLED.
Technology:
The maturity of display technologies dictates their market penetration and specialized use cases.
- Flexible Displays:These displays are built on pliable substrates, allowing for non-flat and conformable designs in various products. Demand is strong in wearable computing and advanced automotive interiors.
- Foldable Screens:A subset of flexible displays, these enable devices to bend and fold, drastically altering device form factors. Consumer electronics, especially smartphones, drive significant demand.
- Transparent Displays:These allow users to see through the screen, integrating digital information for innovative retail and architectural applications.
- 3D Displays:These technologies create a perception of depth without special glasses, finding niche applications in medical imaging.
- Touchscreen:Interactive display overlays register user input through touch, ubiquitous in smartphones, tablets, and public kiosks.
- Curved Displays:Screens with a fixed curvature enhance immersion for viewers, popular in high-end televisions and gaming monitors.
Innovation in flexible substrates drives new product categories, while established touchscreen technologies maintain broad market penetration.
Application:
Application segments are differentiated by their volume requirements and specific performance criteria.
- Consumer Electronics:This broad category includes smartphones, tablets, and televisions, representing the largest volume segment for display panels. Demand is driven by continuous innovation in visual quality.
- Automotive Instrument Panels:Displays integrated into vehicle dashboards provide critical information and infotainment, requiring high durability and reliability. The shift to digital cockpits creates significant demand.
- Wearable Devices:Small, energy-efficient displays are crucial for smartwatches and fitness trackers, focusing on compact size and low power.
- Digital Signage:Large-format displays for advertising require high brightness and modularity for various indoor and outdoor environments.
- Aviation Cockpit Displays:Displays in aircraft cockpits demand extreme reliability, clarity, and specific certifications for critical flight information.
- Gaming Devices:High refresh rates, low latency, and vibrant color reproduction are essential for displays used in gaming monitors and consoles.
While consumer electronics absorb the majority of display production, automotive applications demonstrate strong growth in value per unit.
End User Industry:
End user industries exert distinct pressures on display manufacturers regarding supply chain configuration and customization needs.
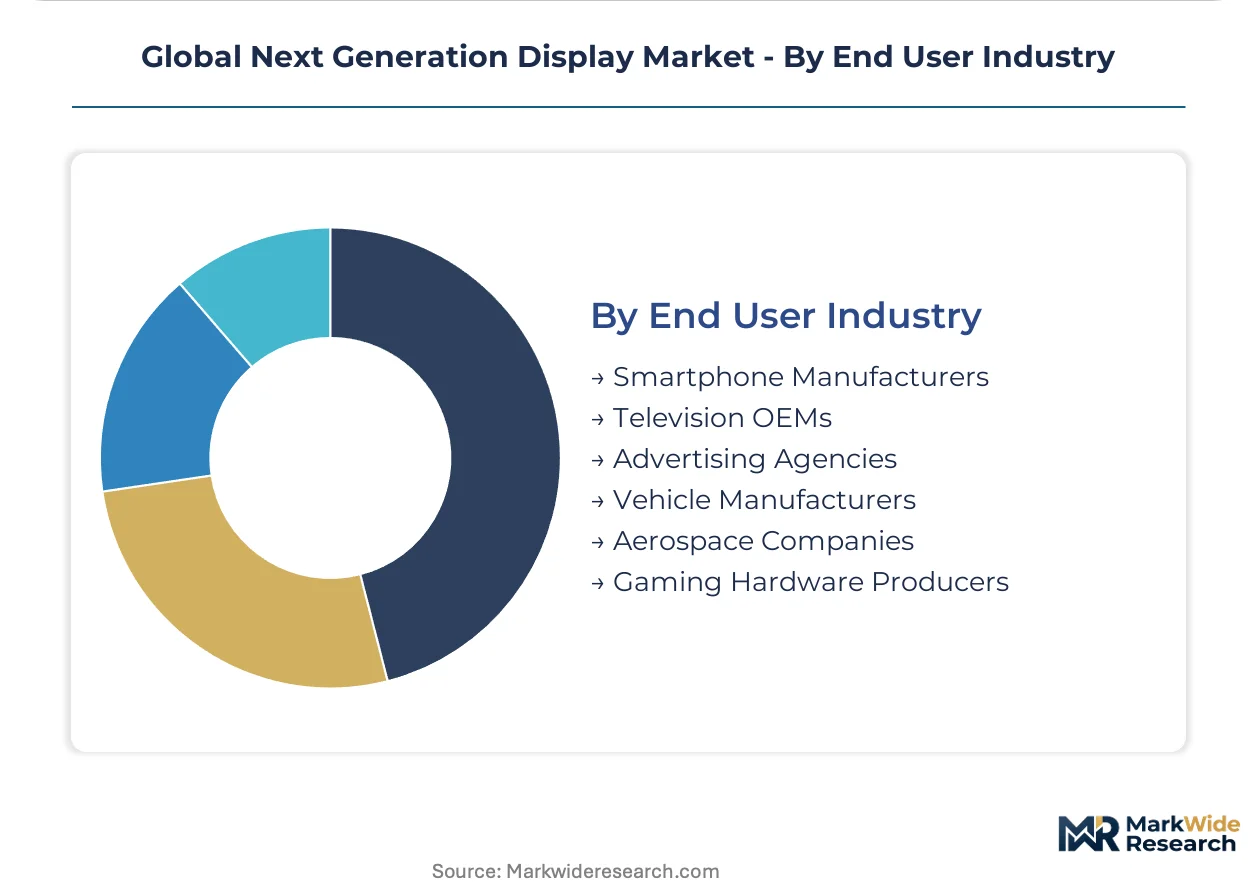
- Smartphone Manufacturers:These companies are primary consumers of high-volume, advanced OLED and foldable display panels. Their demand focuses on compact form factors and energy efficiency.
- Vehicle Manufacturers:The automotive sector integrates durable, high-performance displays into modern vehicle interiors for instrumentation and infotainment. They require stringent quality controls.
- Television OEMs:These manufacturers require large-format OLED and MicroLED panels for premium televisions, focusing on visual fidelity.
- Advertising Agencies:They procure large-scale digital signage solutions for advertising, prioritizing brightness, modularity, and content flexibility.
- Aerospace Companies:These firms demand highly reliable and certified displays for cockpit and cabin systems, emphasizing extreme environmental tolerance.
- Gaming Hardware Producers:They source high-refresh-rate, low-latency display panels for monitors and consoles, catering to performance demands.
Smartphone and vehicle manufacturers represent the largest procurement volumes, while aerospace companies demand specialized, low-volume solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea, a hub for advanced display manufacturing, anchors the global supply chain for next generation displays. This nation's technological prowess and investment drive innovation. Manufacturing centers in East Asia and key demand markets globally shape regional dynamics.
South Korea
South Korean manufacturers prioritize advanced panel production for premium consumer electronics and large-format displays. The Ministry of Food and Drug Safety (MFDS) oversees general electronics safety and quality standards for display components. The Seoul Capital Area and Gyeonggi Province host major research and development centers alongside advanced fabrication plants.
China
China's vast manufacturing ecosystem drives significant panel output for global consumer electronics markets. The nation's GB standards impose strict quality and safety requirements on electronic components. The Yangtze River Delta and Pearl River Delta regions contain massive display production facilities and assembly operations.
Taiwan
Taiwanese fabricators focus on specialized display solutions and expanding production capabilities for next generation technologies. The Bureau of Standards, Metrology and Inspection (BSMI) ensures compliance with national quality standards for display exports. The Hsinchu Science Park concentrates display component manufacturers and research institutes.
United States
United States demand for advanced displays stems from automotive integration and emerging AR/VR applications. The US EPA's ENERGY STAR program guides energy efficiency benchmarks for monitor and television manufacturers. Silicon Valley drives innovation in microdisplay technologies, while Detroit's automotive cluster integrates durable displays into vehicle cockpits.
Germany
German automotive manufacturers integrate curved and flexible displays into modern vehicle cockpits, emphasizing durability and performance. The European Union's RoHS directive directly influences material composition for displays sold within the country. Bavaria and Baden-Württemberg host significant automotive research and development alongside display integration specialists.
Global Next Generation Display Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces like MicroLED and AR microdisplays. The market structure features large-scale panel manufacturers, specialized technology providers, and niche innovators. Capacity expansion and strategic partnerships remain dominant competitive moves across the industry.
Specialists in advanced display technologies include Samsung Electronics, a South Korean firm, which represents a dominant force in OLED production for the premium smartphone market. LG Display, another South Korean entity, exemplifies leadership in large-format OLEDs for high-end televisions and digital signage. AUO Corporation, a Taiwanese company, occupies a position focused on specialized display solutions for automotive instrument panels and industrial equipment.
| Leading Market Players |
|---|
| AUO Corporation |
| Japan Display |
| Samsung Electronics |
| Apple |
| Universal Display Corporation |
| LG Display |
| Innolux Corporation |
| Sony |
| BOE Technology Group |
| Others |
Cost & Logistics Intelligence
The clear performance gap between premium self-emissive displays and conventional LCDs drives distinct pricing strategies and supply chain configurations. This divergence reflects varying production complexities and material dependencies across the market.
Pricing Analysis
Warranty and service agreements often bundle with premium display sales, reflecting the high value and complexity of next generation panels. Pricing primarily follows a contract-based long-term offtake model for major OEMs, with per-unit transactional pricing for smaller volume buyers. Price differentiation stems from visual performance, such as contrast and color accuracy, and durability requirements for automotive applications. Pricing pressure stems from the high capital expenditure for MicroLED fabrication, while mature LCD technology experiences downward pressure from intense competition. Consumer electronics buyers, particularly in the mass market, exhibit the highest price sensitivity, whereas aerospace companies prioritize performance and reliability over cost.
Supply Chain Analysis
Organic compound supply for OLED production rests heavily on a few specialized chemical producers, primarily located in East Asia. The geographic supply concentration for display panels centers on South Korea, China, and Taiwan, which host major fabrication facilities. Raw material dependencies include flexible substrates for foldable screens and specialized inorganic light-emitting diodes for MicroLEDs. A structural risk involves single-source vulnerability for critical mass transfer equipment required for MicroLED manufacturing. Distribution runs through direct sales channels to large OEMs, while specialized distributors serve industrial and digital signage applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market navigates a technology-transition phase, with advanced OLED and MicroLED replacing legacy LCDs in high-value applications. Manufacturers must strategically position themselves to capitalize on evolving display demands.
For Market Incumbents: Deploy strategic R&D investment to accelerate MicroLED mass production, directly addressing future demand from television OEMs. Secure intellectual property rights through licensing agreements to mitigate litigation risks from emerging MicroLED startups. Capacity addition in South Korea and Taiwan helps maintain market dominance against increasing competition. Focus on integrating advanced displays into digital cockpits to counter the threat of commoditization in traditional panel segments.
For New Entrants and Emerging Players: The significant price-point gap between high-end OLEDs and more accessible LCDs creates opportunities for new entrants. Target specialized industrial display solutions requiring high durability and specific performance attributes, such as those for medical imaging or ruggedized equipment. The most penetrable segment lies within niche commercial applications that value customization over sheer volume. A go-to-market angle focusing on performance-per-cost in specific industrial applications can drive early adoption.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized display component manufacturers given the rapid expansion in automotive and AR/VR applications. Long-term viability rests on successful MicroLED mass production and adoption across diverse high-value applications over the next decade. Acquisition targets should include firms with proprietary mass transfer technologies or unique material science expertise for flexible substrates. A significant signal to watch is a breakthrough in MicroLED mass transfer yields, indicating readiness for broader market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New fabrication plants in South Korea and Taiwan are crucial for MicroLED panel production scale-up. |
| Product Diversification | Developing flexible displays for smart textiles and wearable computing expands application areas. |
| IP Licensing | Securing critical patents for MicroLED mass transfer technologies reduces legal and operational risks. |
| Strategic Partnerships | Collaborating with automotive OEMs enables advanced cockpit integration and secures high-value contracts. |
| R&D Focus | Investing in blue emitter efficiency for MicroLEDs overcomes technical hurdles for mass market adoption. |
Research Approach
Multi-period observation of panel production volumes, R&D spending, and patent filings anchored the trend analysis, supplemented by interviews with display panel R&D directors, automotive infotainment system designers, consumer electronics product managers, and regulatory compliance officers. Secondary data sources included company annual reports, industry association reports, government technology roadmaps, and academic research papers. This approach enabled bottom-up and top-down triangulation for robust data validation.
An input-output matrix formed the analytical framework, modeling display market segmentation across product type, technology, application, and end user industry. This framework also incorporated regional adoption patterns. Compound annual growth rates were derived by extrapolating historical growth, factoring in technological adoption curves, and considering market saturation points across the analysis window. Key industry-specific forecast inputs included MicroLED yield rates and flexible substrate material costs.
Underlying measurement precision varies by segment; consumer electronics volume data carries tighter precision than emerging AR microdisplays. Forecasts reflect assumptions regarding technological advancements and market acceptance. Significant shifts in raw material costs or changes in global trade policies represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electrochromic Window Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
DLP Projector Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Thin Display Technology Market
Display Technologies
Foldable Display Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
IGZO Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Portable Projector Market
Display Technologies
Display Mask Market