
 Gaming Monitors Market | 2026-2036
Gaming Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Monitors Market Analysis
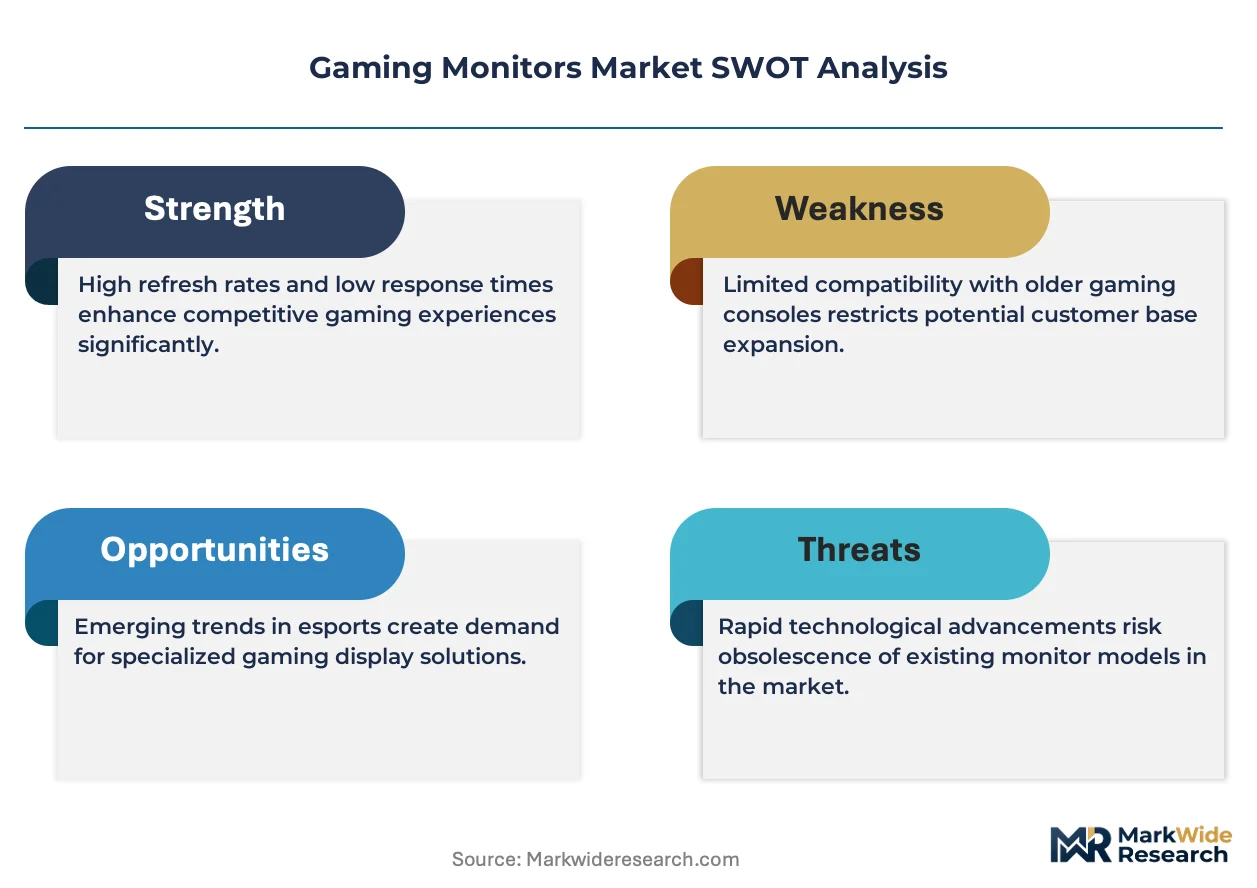
Multi-source panel procurement is hardening as a standard practice among tier-one brands. Samsung leverages captive OLED fabrication to secure supply continuity for premium lines. LG sustains IPS leadership through dedicated Gen 8.5 fab capacity in Paju. ASUS differentiates via R&D intensity in 240Hz-plus variable refresh architectures.
Gaming monitors are display devices engineered for interactive entertainment, combining refresh rates above 144Hz with sub-5ms gray-to-gray response times and adaptive sync protocols to eliminate frame tearing during high-motion gameplay. Commercial purpose centers on delivering competitive visual performance for esports professionals and enthusiast consumers. OLED panel types command premium positioning due to per-pixel dimming and infinite contrast ratios, while 240Hz refresh rate tiers attract the fastest-growing segment of competitive gamers. Screen size segmentation shows 27-inch formats occupying the volume sweet spot between desk-space constraints and immersive field-of-view requirements.
EPA Energy Star specifications and EU Ecodesign requirements shape minimum efficiency thresholds for display imports into the United States and Europe respectively. China's MIIT enforces GB standards that limit standby power and mandate refresh rate disclosure accuracy, tightening market access for uncertified entrants. South Korea's KC certification adds electromagnetic compatibility testing that extends product validation timelines. Stakeholders must monitor whether OLED burn-in warranty terms become a regulated consumer protection battleground.
Market Dynamics
Refresh rate escalation beyond 240Hz is compressing product lifecycles as esports leagues mandate competitive-grade displays. Panel fabs in South Korea and Taiwan face yield constraints on OLED sub-6ms response architectures.
Growth Catalysts
- Esports league standardization:Tournament operators now require 240Hz minimum refresh rates for official competition hardware, pulling fleet purchases from amateur leagues seeking parity with professional circuits.
- China's GB 21520 energy standards:MIIT mandates tighten standby power ceilings and force refresh rate accuracy disclosure, eliminating specification inflation among uncertified suppliers.
- OLED burn-in mitigation:Pixel-refresh algorithms and sub-pixel shifting extend panel longevity, reducing warranty risk perception among competitive gamers who run static HUDs.
Market Restraints
- OLED substrate concentration:Gen 8.5 oxide-TFT backplane supply concentrates in Paju and Gumi, exposing brands to single-source disruption from Korean fab maintenance cycles.
- Driver IC allocation bottlenecks:240Hz timing controllers face foundry competition from smartphone OLED demand, extending lead times for high-refresh desktop panels.
- Import tariff layering:US Section 301 duties on Chinese-assembled displays compound with anti-dumping margins on Taiwanese LCD imports, inflating landed costs for value-tier SKUs.
Strategic Opportunities
- India's duty-drawback assembly:Brands establishing SKD operations under PLI scheme incentives access Southeast Asian gaming demand with reduced effective tariffs versus direct China-origin shipments.
- Console VRR convergence:HDMI 2.1 variable refresh implementation on PlayStation and Xbox creates addressable base beyond PC builders, opening retail placement in consumer electronics chains.
- EU Ecodesign repairability mandates:Upcoming requirements for replaceable backlights and standardized power connectors enable aftermarket service revenue streams and extended product lifecycles.
Industry Challenges
- Color calibration labor scarcity:Factory-grade Delta-E tuning below 2.0 requires specialized technicians concentrated in Seoul-Incheon corridor, constraining capacity expansion.
- KC certification electromagnetic testing:South Korea's sequential validation protocol adds weeks to product launch timelines versus parallel FCC and CE filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Monitors Market |
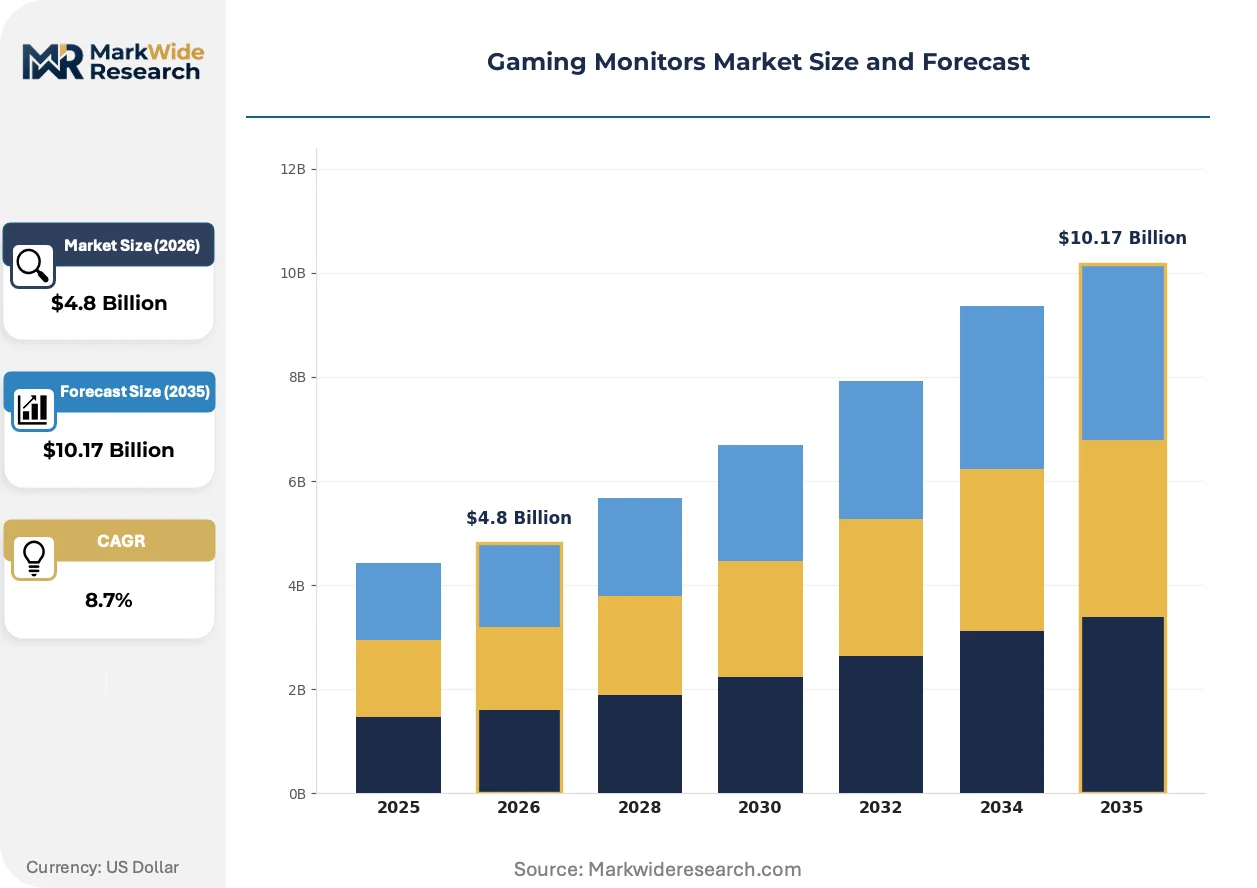
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Panel Type: IPS, TN, VA, OLED Refresh Rate: 60Hz, 120Hz, 144Hz, 240Hz Screen Size: 24 inches, 27 inches, 32 inches, 34 inches Connectivity: HDMI, DisplayPort, USB-C, DVI |
| Companies Covered | Philips, LG, ASUS, Gigabyte, Dell, MSI, Acer, BenQ, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Monitors Market Emerging Trajectories
Display architecture is fragmenting across competing premiumization paths as OLED, Mini-LED, and advanced IPS technologies pursue overlapping performance claims. Panel makers now optimize for specific competitive gaming sub-segments rather than universal specifications.
QD-OLED quantum dot enhancement is decentralizing premium positioning away from traditional WOLED dominance. Samsung Display's inkjet-printed blue emitter stacks enable higher peak luminance for HDR certification. Esports monitor buyers now evaluate contrast and color volume alongside raw refresh metrics. This technology is decentralizing what "competitive-grade" means across price tiers.
Europe's Ecodesign for Energy-Related Products Directive is tightening standby power limits and mandating on-mode efficiency disclosures for displays above 27 inches. Manufacturers must redesign power supply architectures to meet sub-0.5W standby requirements. Premium curved ultrawide models face the steepest compliance costs due to backlight zone complexity. Korean exporters are pre-certifying through notified bodies in Germany to avoid border delays.
Direct-to-consumer configuration is displacing traditional retail bundling among enthusiast buyers. ASUS and MSI now offer factory overclock validation and per-unit color reports through owned web channels. Amazon and Newegg lose attach-rate revenue as brands capture full margin on premium SKUs. This shift concentrates in North American and Western European markets where credit-card chargeback protections reduce purchase risk perception.
Gaming Monitors Market Segmentation
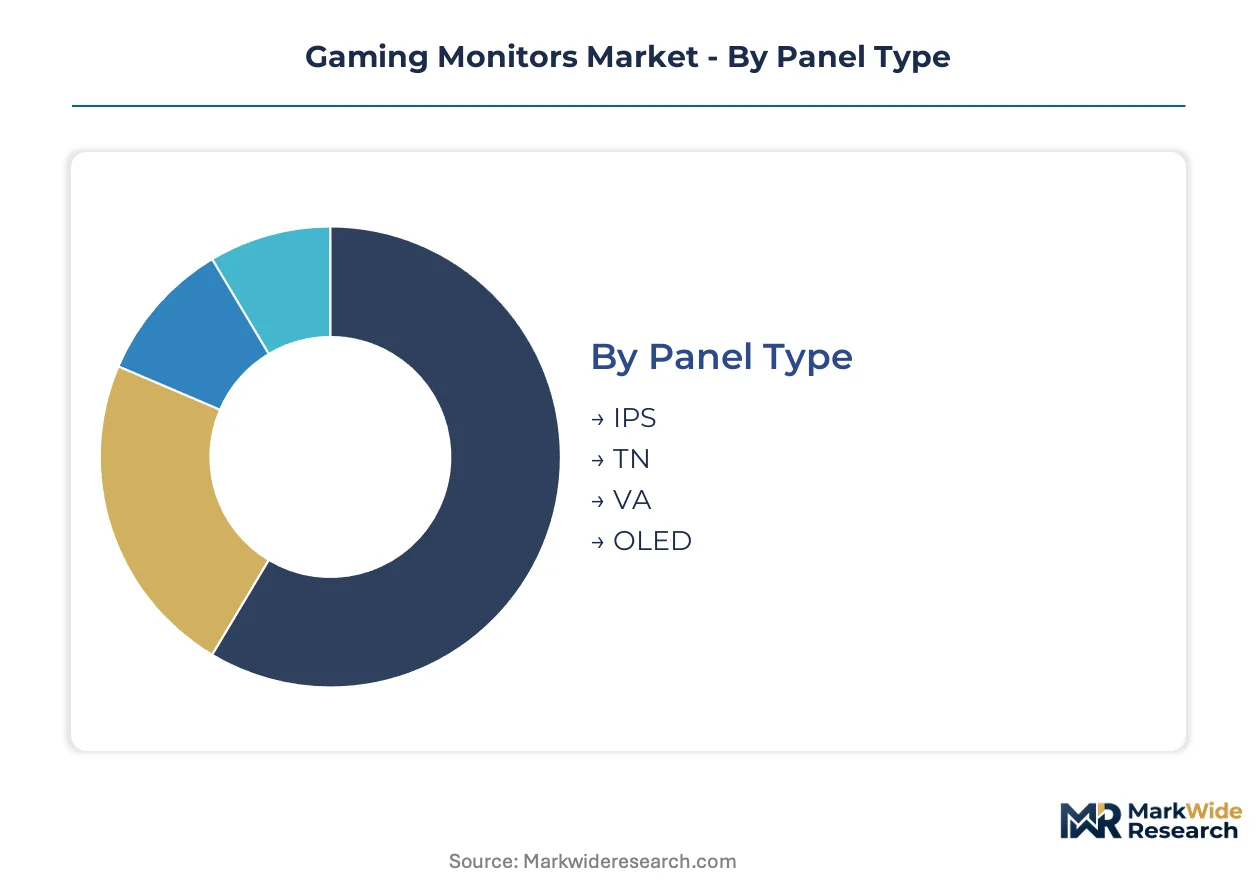
Gaming monitor segmentation separates volume plays from margin capture. Panel technology and refresh rate tiers create distinct competitive battlegrounds where supply constraints and certification costs reshape positioning.
Panel Type:
OLED commands premium shelf space while IPS anchors mainstream volume. TN and VA occupy cost-sensitive niches with divergent technical compromises.
- OLED:Per-pixel dimming delivers infinite contrast and sub-1ms response times. Demand concentrates among esports professionals in South Korea's Seoul-Incheon corridor where burn-in warranty terms influence procurement decisions.
- IPS:In-plane switching maintains color accuracy across wide viewing angles with 1-4ms gray-to-gray response. Volume deployment dominates North American and European retail channels where factory calibration to Delta-E below 2.0 justifies modest premiums.
- TN:Twisted nematic cells achieve the fastest raw response times at lowest manufacturing cost. Budget-conscious competitive gamers in Southeast Asian markets accept color shift trade-offs.
- VA:Vertical alignment layers deliver superior contrast ratios versus IPS with deeper blacks. Curved ultrawide configurations exploit VA's flexibility for immersive single-player experiences.
Mature deployment sits with IPS. Newer deployment is concentrated in OLED.
Refresh Rate:
Refresh tiering now follows esports league mandates rather than gradual consumer upgrade cycles. Higher frequencies compress product lifecycles and concentrate R&D investment.
- 240Hz:Tournament-grade timing controllers eliminate motion blur for competitive first-person shooters. Fleet purchases by esports operators in the United States and Germany pull amateur league procurement toward specification parity.
- 144Hz:The enthusiast sweet spot balances GPU rendering demands with display cost. Mainstream adoption concentrates in Western European markets where HDMI 2.1 console compatibility extends addressable base beyond PC builders.
- 120Hz:Console-optimized tier matching PlayStation and Xbox VRR implementation. Living room gaming setups in Japan and South Korea favor this specification for hybrid entertainment use.
- 60Hz:Entry threshold for casual gaming and secondary displays. Emerging market volume in India and Brazil accepts this tier where import tariff layering inflates landed costs for premium SKUs.
Volume leadership belongs to 144Hz. Steepest expansion trajectory is concentrated in 240Hz.
Screen Size:
Desk-space constraints and competitive field-of-view requirements create non-linear demand curves across diagonal measurements.
- 27 inches:The volume anchor balancing pixel density with peripheral vision coverage. Professional esports facilities in South Korea standardize on this format for uniform training environments.
- 32 inches:4K resolution compatibility drives adoption among content creators and simulation enthusiasts. North American home office configurations favor this size for dual-purpose productivity and gaming use.
- 24 inches:Compact footprint suits dormitory and shared living constraints. Budget-tier procurement in European student markets maintains residual demand.
- 34 inches:Curved ultrawide aspect ratios deliver cinematic immersion for racing and flight simulations. Premium positioning targets affluent consumers in Germany and the United Kingdom.
Established deployment sits with 27 inches. Newer deployment is concentrated in 32 inches.
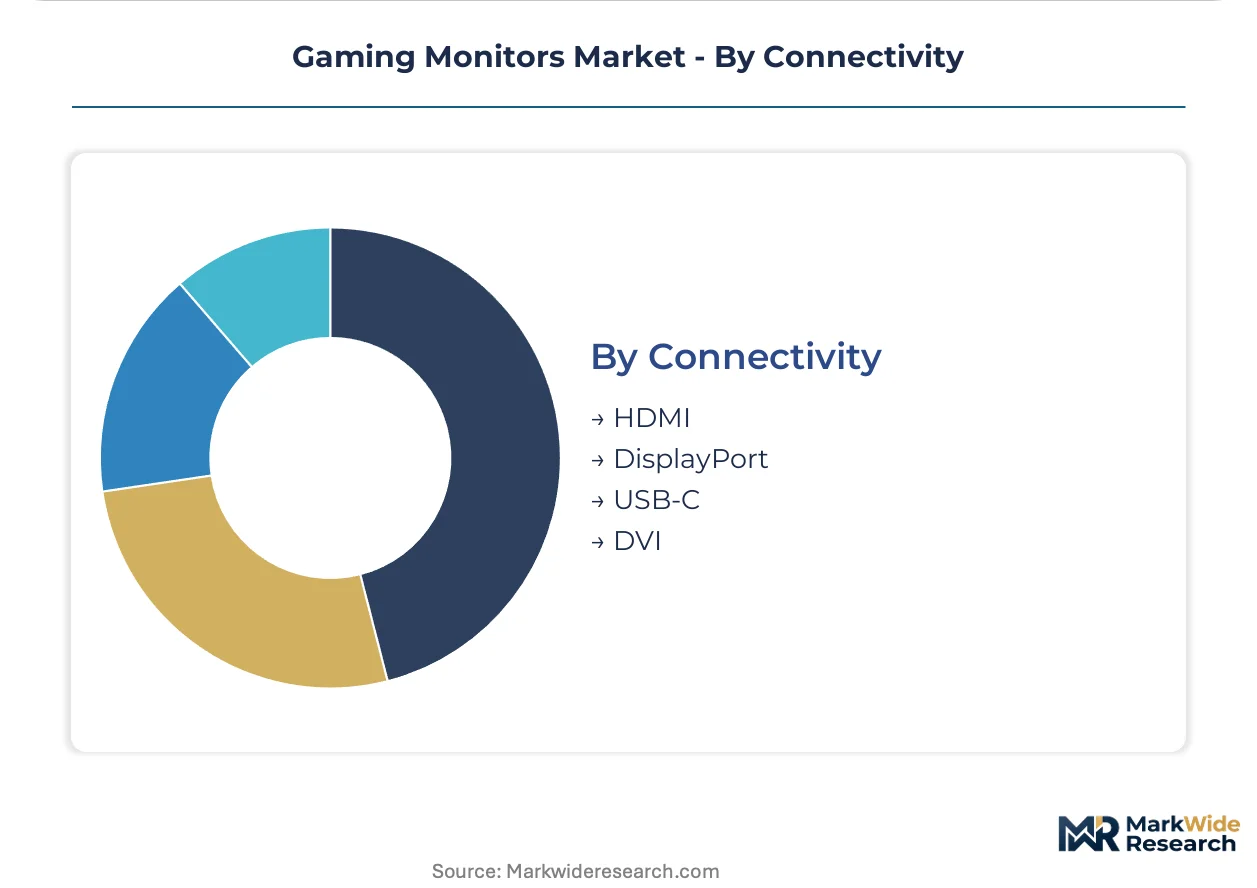
Connectivity:
Interface selection determines ecosystem compatibility and future-proofing against GPU and console generation transitions.
- DisplayPort:PC-native standard supporting highest refresh rates and adaptive sync protocols. Enthusiast builds in the United States and Germany require DisplayPort 1.4 or 2.1 for uncompressed 4K high-refresh signaling.
- HDMI:Universal compatibility spanning consoles, streaming devices, and laptops. HDMI 2.1 implementation is expanding most quickly as PlayStation and Xbox VRR convergence opens consumer electronics retail placement.
- USB-C:Single-cable docking for laptop-driven setups with power delivery integration. Mobile workstation users in Japan and South Korea favor this for clean desk configurations.
- DVI:Legacy support for aging GPU hardware and industrial applications. Replacement demand concentrates in cost-sensitive emerging markets with extended hardware refresh cycles.
Mature deployment sits with DVI. Newer deployment is concentrated in USB-C.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display-grade glass substrate production concentrates in South Korea's Gumi corridor, feeding panel fabrication clusters across East Asia. This feedstock locality anchors procurement patterns for brands sourcing high-refresh-rate backplanes.
United States
Esports league standardization drives fleet procurement from tournament operators in California and Texas. The FCC enforces electromagnetic compatibility testing under Part 15 rules for display imports. Austin's technology corridor hosts assembly operations serving North American retail channels with reduced tariff exposure versus direct Asia-origin shipments.
South Korea
Seoul-Incheon manufacturing corridor concentrates Gen 8.5 oxide-TFT backplane fabrication for premium OLED lines. The MFDS regulates electromagnetic emissions through KC certification protocols that extend validation timelines. Paju's dedicated fab capacity sustains IPS leadership for brands requiring supply continuity.
China
Domestic esports venue construction accelerates procurement of 240Hz displays for training facilities in Shenzhen and Chengdu. The MIIT enforces GB 21520 energy standards that limit standby power and mandate refresh rate disclosure accuracy. Yangtze River Delta assembly plants face tightening efficiency requirements under dual carbon goals.
Germany
Consumer electronics retail chains expand gaming monitor placement driven by HDMI 2.1 console VRR convergence. The EU Ecodesign Directive mandates repairability requirements for displays above 27 inches including replaceable backlights. Bavaria's industrial automation sector supplies precision calibration equipment for factory-grade Delta-E tuning.
Japan
Mobile workstation users in Tokyo and Osaka favor USB-C connectivity for clean desk configurations. METI oversees JIS standards for display energy efficiency that align with international certification frameworks. Nagoya's precision electronics cluster produces timing controller components for high-refresh architectures.
Gaming Monitors Market Vendor Landscape
Global majors compete with regional champions across panel technology access and refresh rate tier positioning. The vendor base organizes around captive OLED supply, dedicated IPS fabrication, and third-party panel procurement strategies. Three archetypes dominate: vertically integrated display makers, specialist gaming peripheral brands, and diversified electronics conglomerates. Capacity expansion and strategic partnerships constitute the primary competitive moves as fabs prioritize 240Hz timing controller allocation.
Among diversified electronics conglomerates, LG Electronics Inc. and Samsung Electronics Co., Ltd. exemplify the captive supply archetype through in-house panel production. ASUS Tek Computer Inc. occupies a position within specialist gaming peripheral brands emphasizing R&D intensity in variable refresh architectures. These three companies represent distinct strategic postures regarding supply chain control versus external procurement flexibility.
| Leading Market Players |
|---|
| Philips |
| LG |
| ASUS |
| Gigabyte |
| Dell |
| MSI |
| Acer |
| BenQ |
| Samsung |
| Others |
Supply Flow & Price Mechanics
Factory-grade Delta-E calibration specialists concentrated in South Korea's Seoul-Incheon corridor command wage premiums that compress margins on mid-tier IPS panels while widening spreads between premium OLED and economy TN configurations.
Pricing Analysis
Warranty bundling separates premium positioning from unbundled economy tiers, with OLED burn-in coverage extending to three years on flagship SKUs versus one-year standard terms for IPS alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors on panel technology and refresh rate certification, with 240Hz tournament-grade timing controllers justifying substantial uplifts. Pricing pressure stems from import tariff layering on Chinese-assembled displays, compressing landed costs for value-tier SKUs. Esports fleet buyers exhibit lowest price sensitivity given league mandate compliance requirements, while Southeast Asian amateur leagues prioritize specification parity at minimal cost.
Supply Chain Analysis
Dual-sourcing mandates from tier-one brands now require qualified panel supply from both South Korean and Taiwanese fabs, reducing single-source exposure to Paju or Gumi maintenance cycles. Gen 8.5 oxide-TFT backplane fabrication concentrates in South Korea, while timing controller foundry capacity clusters in Taiwan and Japan. Driver IC allocation for 240Hz architectures draws from smartphone OLED competition, extending lead times for desktop panel procurement. Distribution runs through consumer electronics retail chains in Germany and the United States, with direct-to-consumer web channels capturing growing attach-rate revenue in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT GB 21520 energy standards erect compliance barriers that eliminate uncertified suppliers, creating sustainable moats for brands with established certification infrastructure and disclosed refresh rate accuracy.
For Market Incumbents: Lock in captive OLED supply through long-term fab allocation agreements at Samsung Display and LG Display, insulating premium lineups from driver IC bottlenecks. Secure KC certification pre-validation in Seoul to compress product launch timelines versus sequential filing strategies. Reinforce position by acquiring precision calibration equipment suppliers in Bavaria to internalize Delta-E tuning capacity. For New Entrants and Emerging Players: The 144Hz-to-240Hz price-point gap in Western European retail channels offers white-space entry for brands with HDMI 2.1 console compatibility and modest adaptive sync R&D. Target India's PLI scheme assembly incentives to access Southeast Asian demand with reduced effective tariffs versus direct China-origin shipments. Pursue esports training facility procurement in Shenzhen and Chengdu where domestic venue construction accelerates fleet refresh cycles. For Investors and Strategic Acquirers: Re-rating potential sits with specialist gaming peripheral brands possessing R&D intensity in variable refresh architectures given esports league standardization pulling amateur procurement toward specification parity. Long-term viability favors archetypes with backward integration into timing controller design or panel procurement flexibility across Korean and Taiwanese supply bases. Monitor OLED burn-in warranty claim rates as inflection indicator for panel longevity perception and premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive OLED Fab Allocation | Long-term supply agreements at Paju and Gumi secure premium panel continuity for 240Hz lines. |
| KC Certification Pre-Validation | Parallel electromagnetic testing in Seoul compresses launch timelines versus sequential FCC filing. |
| India PLI Assembly Entry | SKD operations under duty-drawback incentives reduce effective tariffs for Southeast Asian demand. |
| Direct-to-Consumer Channel Buildout | Owned web platforms capture full margin on factory-overclocked SKUs with per-unit color reports. |
| Precision Calibration Equipment Acquisition | Internalizing Bavaria-sourced Delta-E tuning capacity reduces labor scarcity constraints. |
Methodological Framework
Document review covered panel maker capacity disclosures, MIIT GB standard filings, and esports league equipment mandates, complemented by interviews with display procurement directors at tournament operators, panel fab planning executives in Seoul-Incheon, and consumer electronics category buyers in Germany. Secondary validation drew from customs trade data, SEC 10-K display segment disclosures, and Ecodesign Directive regulatory notices. Bottom-up and top-down triangulation reconciled shipment estimates with fab utilization rates.
Cross-referencing historical refresh rate adoption curves against panel maker capex plans anchored the projection framework across the analysis window. Segmentation dimensions modeled included panel technology, refresh rate tier, screen size, and regional regulatory cluster. CAGRs derived from slope analysis of technology transition S-curves, with inputs from timing controller allocation forecasts and console VRR implementation timelines.
Inputs from KC certification bodies and EU notified bodies were available through the study window; gaps in real-time fab yield data introduce uncertainty bands around OLED volume assumptions. Deviation in China's dual carbon enforcement intensity or MIIT standby power ceiling revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electronic Display Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Portable Video Wall Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Global OLED Market
Display Technologies
IGZO Display Market
Display Technologies
Touch Screen Module Market
Display Technologies
4K Technology Market
Display Technologies
Europe E-Paper Display Market