
 Portable Video Wall Market | 2026-2036
Portable Video Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Video Wall Market Analytics
Modular tile bundling with fly-case logistics is consolidating buyer preference around rapid-deployment packages. Samsung Electronics leverages semiconductor integration to control core driver IC supply. Leyard Optoelectronic anchors high-volume LED tile production through captive SMD packaging lines. Barco NV differentiates on color-calibration software that sustains brand premium in broadcast rental channels.
A portable video wall comprises tiled display panels, typically LED or LCD, mounted on collapsible truss or frame systems with integrated signal distribution and power management, designed for rapid assembly and disassembly at temporary venues. Pixel pitch below 2.5 millimeters now dominates corporate and entertainment specifications where viewers stand within ten feet of the surface. LED temporary installations command the largest revenue pool due to brightness superiority in uncontrolled ambient light, while OLED mobile configurations represent the fastest-growing niche as weight and bezel width shrink. Advertising agencies and event organizers constitute the dominant end-user pair, with retailers expanding fastest as pop-up store formats multiply.
FCC equipment authorization in the United States, CE marking under EU electromagnetic compatibility directives, and IEC 62368-1 safety standards collectively govern product market access and signal-interface compliance. RoHS substance restrictions and REACH chemical registration in Europe constrain solder and coating chemistries, pushing manufacturers toward halogen-free PCB substrates. Stakeholders must monitor whether emerging state-level e-waste extended producer responsibility rules in California and New York reshape fleet retirement economics for rental operators.
Market Dynamics
Carbon-fiber framing and sub-2.5mm pixel pitch compression are compressing transport logistics costs while expanding addressable venue types for rental fleet operators. This hardware-lightweighting dynamic is redrawing procurement criteria across temporary installation markets.
Growth Catalysts
- FCC equipment authorization:Streamlined electromagnetic compliance testing in the United States accelerates product launch cycles for LED panel manufacturers targeting North American rental channels.
- Pop-up retail formats:European and Japanese retailers deploy modular video walls for temporary flagship activations, converting 72-hour installation windows into competitive differentiation.
- RoHS substance restrictions:Halogen-free PCB substrate mandates across the European Union push component suppliers toward lead-free solder chemistries that reduce long-term liability for fleet operators.
Market Restraints
- Driver IC supply concentration:Semiconductor foundry capacity constraints in East Asia create procurement bottlenecks for LED tile manufacturers dependent on integrated circuit sourcing.
- CE marking friction:Electromagnetic compatibility directive compliance costs disproportionately burden smaller rental operators refreshing aging inventory across European markets.
- Fixed LED substitution:Permanent direct-view LED installations in corporate atriums capture budgets previously allocated to recurring temporary deployments.
Strategic Opportunities
- Brazilian event infrastructure:Underpenetrated touring production markets in São Paulo and Rio de Janeiro offer first-mover positioning for fly-case logistics providers.
- Extended producer responsibility:California and New York state-level e-waste mandates create service revenue streams for end-of-life panel recovery and refurbishment operations.
- OLED-LCD convergence:Hybrid display architectures combining OLED color fidelity with LCD cost structures target broadcast rental channels demanding sub-3mm bezels.
Industry Challenges
- Color-calibration technician scarcity:Broadcast rental channels face pipeline constraints for specialists capable of maintaining brand-standard uniformity across multi-panel arrays.
- IEC 62368-1 certification timelines:Safety standard testing delays average fourteen weeks, compressing product launch windows for manufacturers targeting Q4 event seasons.
- Legacy signal distribution integration:Rental operators struggle to interface SDI-based broadcast infrastructure with emerging IP-based video-over-Ethernet protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Video Wall Market |
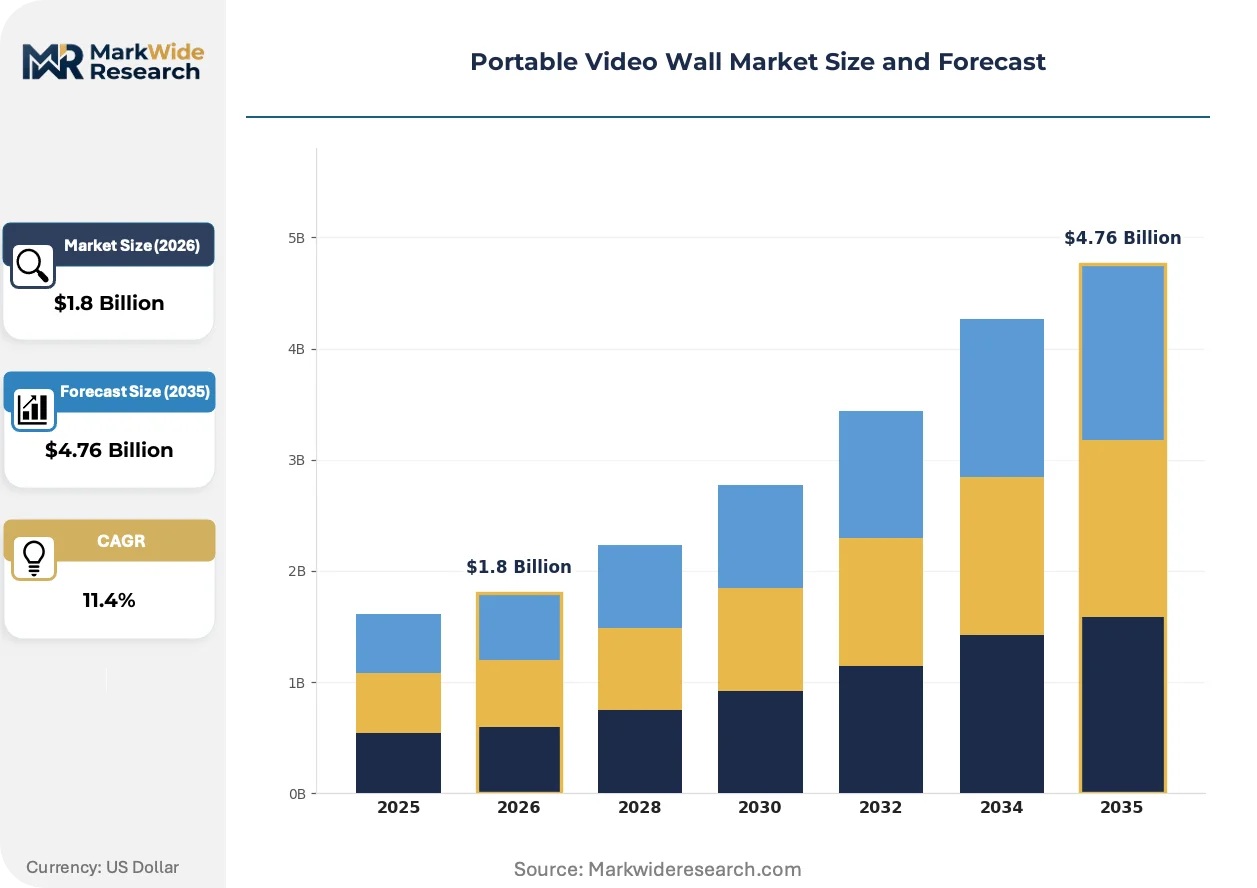
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, Projection, OLED Application: Events, Retail, Corporate, Entertainment End User: Advertising Agencies, Event Organizers, Retailers, Corporations Installation: Fixed, Temporary, Semi-Permanent, Mobile |
| Companies Covered | Panasonic Corporation, Leyard Optoelectronic, Samsung Electronics, Absen, Planar Systems, LG Electronics, Sony Corporation, Delta Electronics, Barco NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Video Wall Market Evolving Landscape
Active-matrix driver architectures and software-defined color management are displacing hardware-centric competitive moats. Rental operators now prioritize firmware upgradeability over fixed hardware specifications in procurement evaluations.
Micro-LED transfer printing is rewriting brightness-to-weight ratios for touring productions. Concert promoters now specify sub-15kg per-square-meter panels for aerial rigging applications previously restricted to projection. This capability expansion is compressing the addressable market for conventional lamp-based projection in live entertainment.
REACH chemical registration expansions in the European Union are constraining coating chemistries for outdoor-rated LED tiles. Manufacturers reformulate conformal coatings to eliminate restricted phthalates while maintaining IP65 ingress protection. German rental fleet operators absorb compliance costs through longer depreciation schedules rather than price premiums.
Rental-as-a-service contracting is consolidating buyer preference around outcome-based agreements. Advertising agencies now specify lumens-per-watt guarantees and same-day replacement SLAs rather than capital purchase of panel inventory. This shift is most visible in London and New York, where pop-up retail clients demand 48-hour deployment commitments without asset ownership.
Portable Video Wall Market Segmentation
Procurement patterns in portable video walls diverge sharply across display technologies and deployment models. Rental fleet operators refresh inventory on 3-5 year cycles, creating distinct upgrade windows for LED, LCD, and emerging OLED formats. Understanding these segment boundaries clarifies where component suppliers and system integrators allocate R&D resources.
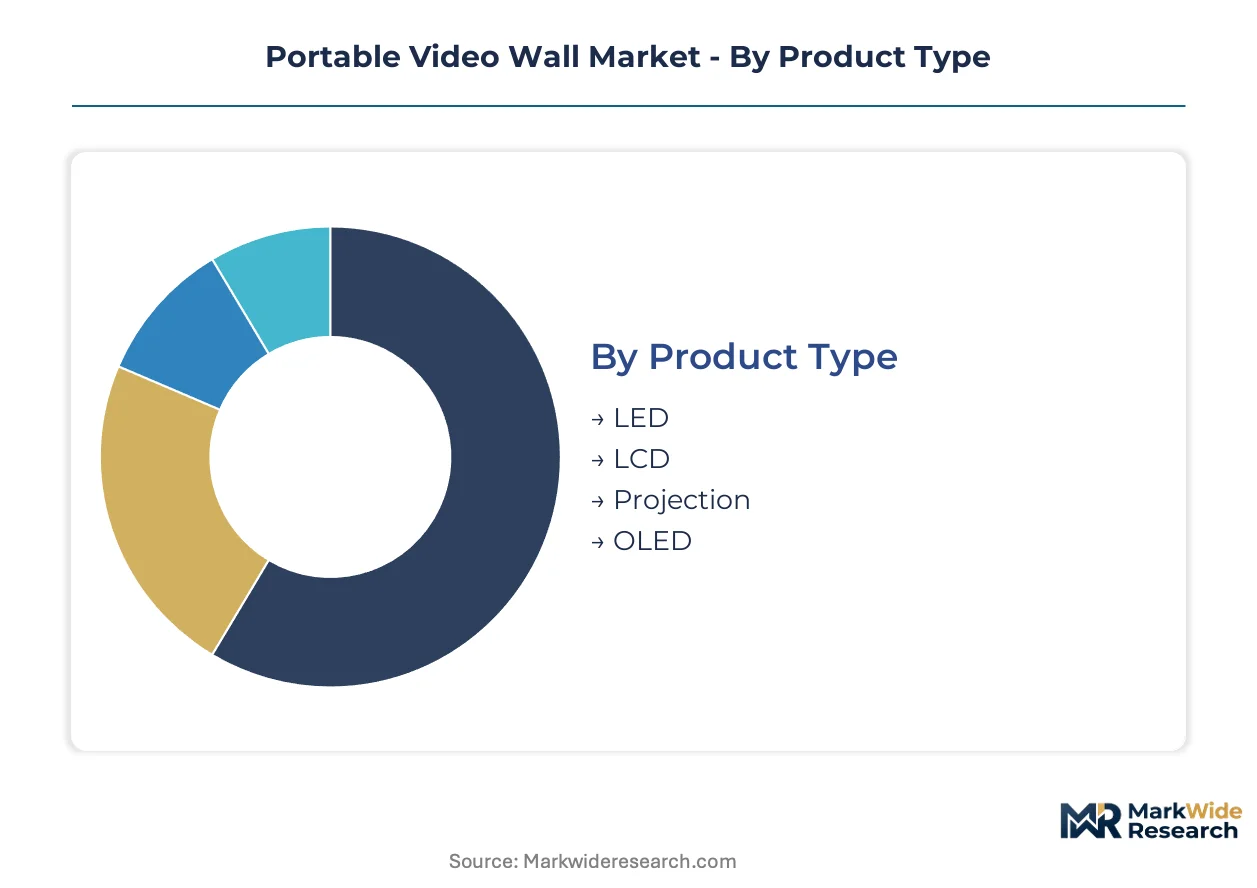
Product Type:
Upgrade cycles compress as pixel pitch thresholds drop below 2.5mm, forcing rental operators to retire aging panels earlier than depreciation schedules originally assumed.
- LED:Direct-view LED tiles dominate uncontrolled ambient light environments with brightness exceeding 1,000 nits. Corporate command centers in Germany and touring productions across the United States drive replacement demand as sub-2mm pixel pitch becomes standard for viewer distances under three meters.
- LCD:Narrow-bezel LCD arrays retain cost advantage for controlled indoor environments where brightness requirements stay below 500 nits. Retail pop-up activations in Japan leverage existing LCD rental pools for 48-hour deployment windows rather than investing in LED premium.
- Projection:Lamp-based and laser projection persists for oversized non-rectangular surfaces where tile mounting proves impractical. Museum temporary exhibitions and immersive art installations represent residual demand pockets.
- OLED:Organic light-emitting diode panels deliver sub-3mm bezels and superior color fidelity for broadcast rental channels. Weight reduction below 10kg per square meter enables aerial rigging applications previously restricted to projection systems.
LED sits at the top of the volume ranking, with OLED climbing the fastest as weight and bezel specifications tighten for touring productions.
Application:
Margin structures vary threefold across application types, with broadcast entertainment commanding premium pricing against standardized corporate deployments.
- Events:Trade show exhibitors and conference producers specify rapid-deployment packages with fly-case logistics and same-day technical support. FCC equipment authorization timelines compress procurement windows for North American event seasons.
- Retail:Pop-up flagship activations in London and New York demand 72-hour installation commitments with lumens-per-watt guarantees rather than capital purchase. Rental-as-a-service contracting consolidates buyer preference around outcome-based agreements.
- Corporate:Command center installations prioritize 24/7 reliability ratings and color-calibration stability across multi-year leases. IEC 62368-1 safety certification becomes non-negotiable for enterprise procurement committees.
- Entertainment:Concert promoters and broadcast rental channels specify sub-15kg panels for aerial rigging. Micro-LED transfer printing rewrites brightness-to-weight ratios for touring productions previously dependent on projection.
Events capture the largest revenue pool, with Retail expanding most quickly as temporary store formats multiply across European and Japanese markets.
End User:
Customer sophistication determines whether procurement emphasizes hardware specifications or outcome-based service level agreements.
- Advertising Agencies:Creative shops bundle video wall deployment with content production, demanding firmware upgradeability over fixed hardware specs. Active-matrix driver architectures displace hardware-centric competitive moats in agency evaluations.
- Event Organizers:Rental fleet operators refresh aging inventory across German, United States, and Japanese markets where carbon-fiber framing and pixel pitch compression reduce transport logistics costs.
- Retailers:European and Japanese pop-up store formats convert 72-hour installation windows into competitive differentiation. REACH chemical registration constraints push manufacturers toward halogen-free PCB substrates.
- Corporations:Enterprise buyers specify extended producer responsibility clauses for end-of-life panel recovery as California and New York state-level e-waste mandates reshape fleet retirement economics.
Advertising Agencies anchor procurement volume, with Retailers gaining share fastest as temporary retail formats proliferate.
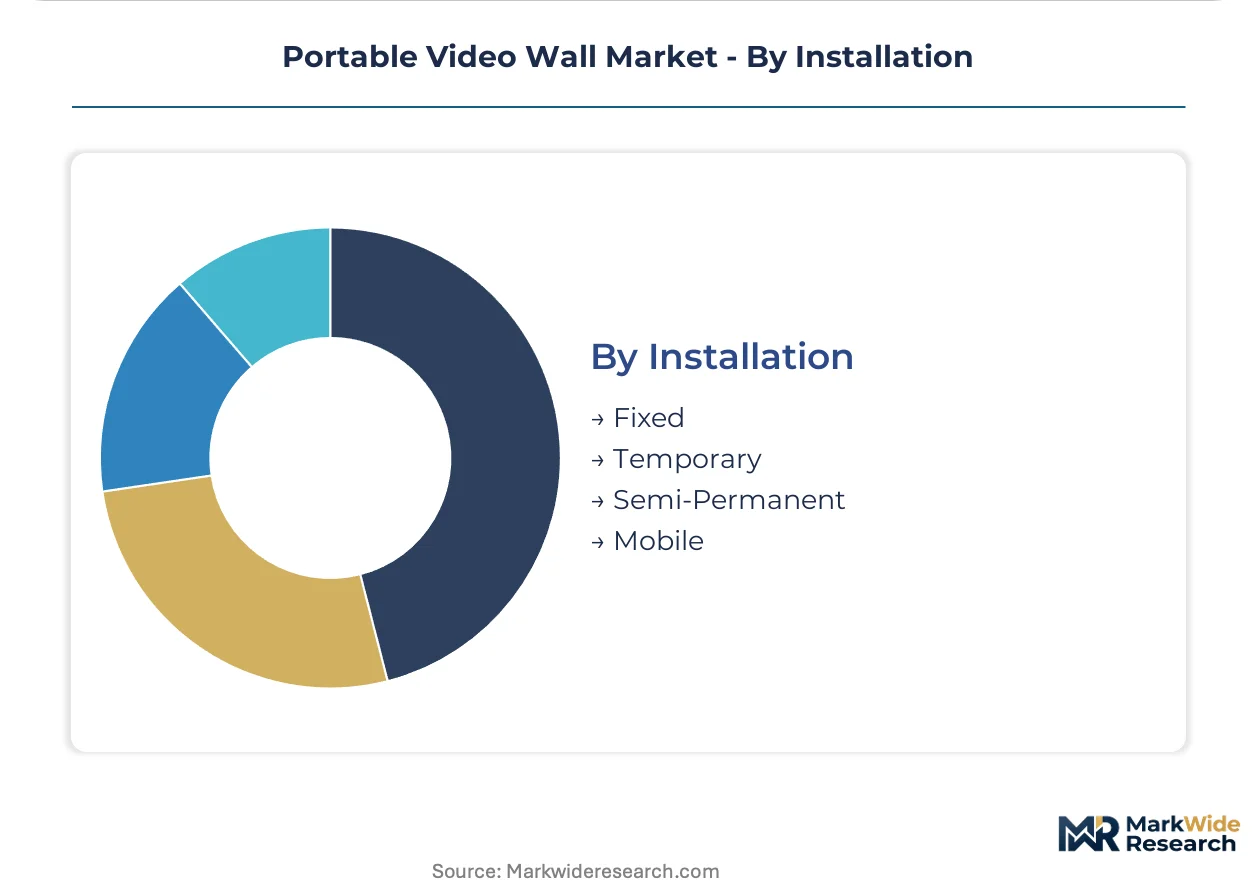
Installation:
Deployment duration determines whether buyers optimize for capital efficiency or operational flexibility.
- Fixed:Permanent direct-view LED installations in corporate atriums capture budgets previously allocated to recurring temporary deployments. RoHS substance restrictions constrain solder and coating chemistries for European fixed installations.
- Temporary:Modular tile bundling with fly-case logistics consolidates preference for rapid-deployment packages. LED temporary installations command the largest revenue pool due to brightness superiority in uncontrolled ambient light.
- Semi-Permanent:Seasonal retail activations and touring productions with 6-18 month cycles balance depreciation schedules against technology refresh timing. CE marking friction disproportionately burdens smaller operators refreshing inventory across European markets.
- Mobile:Trailer-mounted and vehicle-integrated configurations serve outdoor advertising and emergency response applications. Driver IC supply concentration in East Asian foundries creates procurement bottlenecks for mobile LED tile manufacturers.
Temporary installations lead by revenue contribution, with Mobile posting the steepest expansion trajectory as vehicle-integrated formats penetrate outdoor advertising.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale LED rental fleet operations during the 1990s trade show boom, establishing technical standards later adopted across European event infrastructure. This heritage shapes procurement patterns visible today in corporate command center specifications and touring production logistics.
Germany
Rental fleet operators in Frankfurt and Munich refresh aging inventory as sub-2.5mm pixel pitch becomes standard for viewer distances under three meters. CE marking under EU electromagnetic compatibility directives governs product market access for temporary installations. The Cologne-Düsseldorf corridor anchors high-volume LED tile distribution through captive SMD packaging lines serving Central European event circuits.
United States
Corporate command centers in Chicago and touring productions across Los Angeles drive replacement demand for carbon-fiber framed panels. FCC equipment authorization streamlines electromagnetic compliance testing for manufacturers targeting North American rental channels. The Las Vegas convention cluster concentrates fly-case logistics providers specializing in 72-hour deployment windows for trade show exhibitors.
Japan
Retail pop-up activations in Tokyo and Osaka leverage existing LCD rental pools for rapid-deployment formats rather than investing in LED premium. METI standards govern display energy efficiency in commercial installations. The Nagoya industrial belt hosts precision framing manufacturers supplying lightweight truss systems for broadcast rental channels.
United Kingdom
Advertising agencies in London specify outcome-based rental-as-a-service contracts with lumens-per-watt guarantees rather than capital purchase. RoHS substance restrictions constrain solder chemistries for fleet operators refreshing inventory across British markets. The Manchester-Leeds corridor specializes in broadcast calibration services maintaining brand-standard uniformity across multi-panel arrays.
Brazil
Underpenetrated touring production markets in São Paulo and Rio de Janeiro offer first-mover positioning for fly-case logistics providers. ANVISA registration requirements apply to electronic equipment deployed in healthcare-related corporate events. The São Paulo exhibition district attracts regional investment in rapid-deployment packages for Latin American concert circuits.
Portable Video Wall Market Competitive Landscape
Premium-margin players sit above commodity-margin players across color-calibration software and semiconductor integration capabilities. The vendor base organizes into three tiers: integrated electronics conglomerates controlling core component supply, specialized LED tile manufacturers with captive packaging operations, and regional system integrators focused on rental fleet services. Two dominant competitive moves reshape positioning: backward integration into driver IC supply chains and strategic partnerships between framing specialists and logistics providers.
Within the integrated electronics tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through semiconductor capabilities. Leyard Optoelectronic occupies a specialist position in high-volume LED tile production. Barco NV anchors premium-tier differentiation in broadcast rental channels. Panasonic Corporation and Sony Corporation represent diversified conglomerates with heritage display technologies. Absen, Planar Systems, and Delta Electronics sit within the specialized manufacturer archetype focused on modular deployment systems.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Leyard Optoelectronic |
| Samsung Electronics |
| Absen |
| Planar Systems |
| LG Electronics |
| Sony Corporation |
| Delta Electronics |
| Barco NV |
| Others |
Value Network & Pricing Analysis
Micro-LED transfer printing and carbon-fiber framing advances simultaneously compress panel weight thresholds and consolidate procurement leverage among East Asian semiconductor foundries, reshaping cost economics for rental fleet operators while tightening supply concentration around driver IC packaging hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies LED tile procurement by pixel pitch grade and FCC equipment authorization tier. Price differentiation rests on color-calibration software licensing and carbon-fiber framing specifications. Cost compression in standard-tier panels is intensifying because LCD rental pools absorb budget-conscious retail activations. Pop-up retailers exhibit highest price sensitivity; broadcast rental channels accept premium positioning for sub-2mm pixel pitch guarantees.
Supply Chain Analysis
Dual-sourcing requirements for driver ICs now mandate qualification across Taiwan, South Korea, and mainland China foundries to mitigate procurement bottlenecks. Raw material dependencies center on gallium nitride substrates, halogen-free PCB laminates, and carbon-fiber prepreg composites. Single-source vulnerability concentrates in East Asian semiconductor packaging capacity. Distribution runs through German and United States rental fleet operators who consolidate fly-case logistics and same-day technical support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in portable video walls rest on carbon-fiber framing cost-down curves and the shift toward rental-as-a-service premium tiers with lumens-per-watt guarantees.
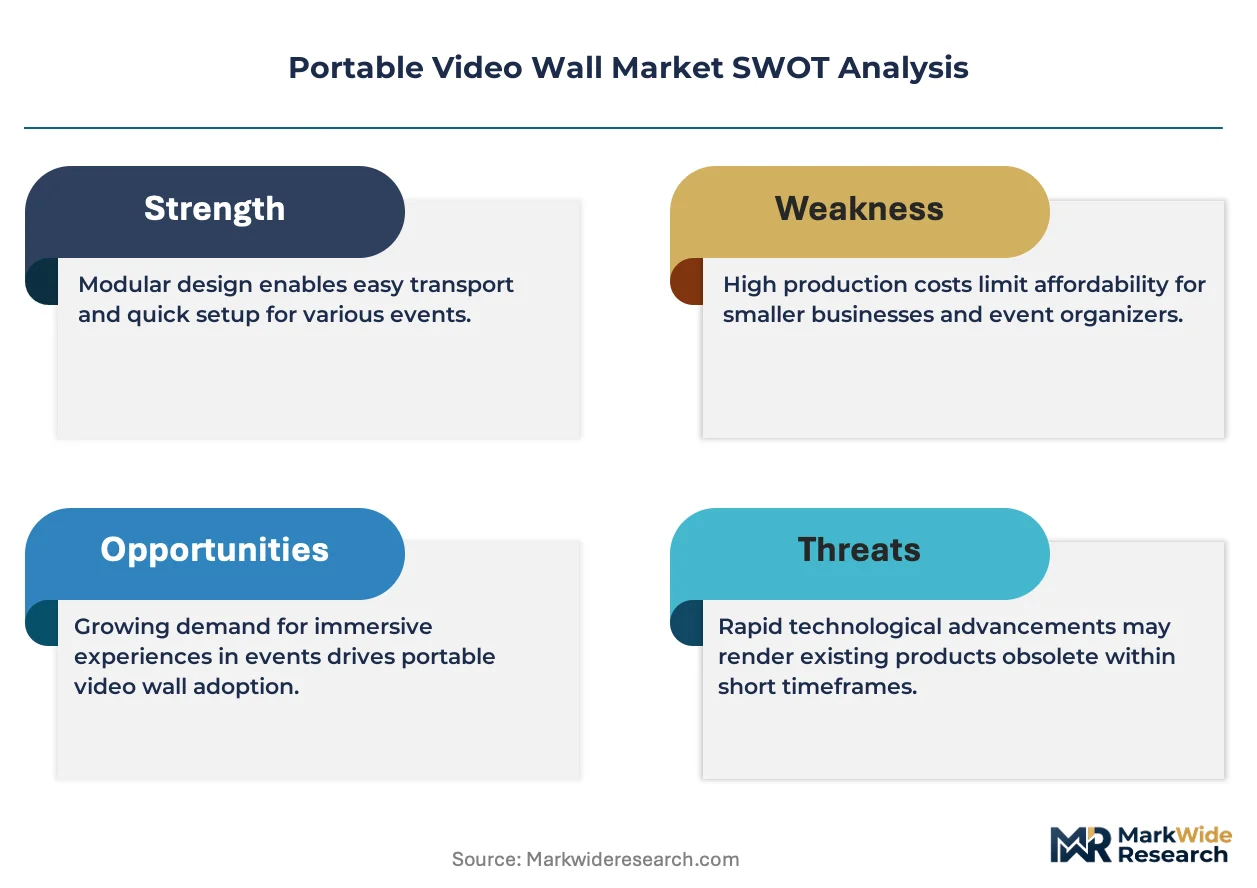
For Market Incumbents: Deploy backward integration into driver IC supply chains to secure semiconductor foundry allocation against emerging LED tile manufacturers. Anchor broadcast rental channel relationships through captive color-calibration technician training pipelines. Counter fixed LED substitution threats by positioning temporary installations as firmware-upgradeable platforms rather than depreciating hardware assets.
For New Entrants and Emerging Players: Software-defined color management capabilities offer entry wedges against hardware-centric incumbents in the broadcast calibration services segment. Brazilian touring production markets present underpenetrated white-space with ANVISA registration pathways for healthcare-corporate event crossovers. Pursue fly-case logistics partnerships rather than capital-intensive panel manufacturing to compress market entry costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with established rental fleet relationships but limited semiconductor integration. Long-term viability across the analysis window favors specialist LED tile manufacturers with captive SMD packaging lines over pure-play logistics providers. Monitor IEC 62368-1 certification timeline compression as an inflection signal for product launch velocity advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Supply | Samsung Electronics and LG Electronics anchor procurement leverage through captive semiconductor foundry relationships. |
| Rental-as-a-Service Platform Launch | London and New York advertising agencies now specify outcome-based contracts with same-day replacement SLAs. |
| Carbon-Fiber Framing Manufacturing Scale-Up | Nagoya precision manufacturers supply sub-15kg panels enabling aerial rigging applications for concert promoters. |
| Color-Calibration Software Licensing | Barco NV sustains premium positioning in broadcast rental channels through brand-standard uniformity guarantees. |
| Brazilian Logistics Partnership Formation | São Paulo exhibition district attracts regional investment for Latin American concert circuit rapid-deployment packages. |
Research Methodology
Direct dialogue with rental fleet operators, event production managers, broadcast calibration technicians, and LED tile procurement directors grounded qualitative insights. Secondary validation drew from FCC equipment authorization databases, CE marking directive filings, IEC safety standard test reports, and trade show industry association deployment surveys. Bottom-up panel shipment aggregation and top-down event infrastructure spending estimates were cross-referenced for triangulation.
Bottom-up modeling tracked LED, LCD, and OLED unit volumes across pixel pitch tiers, installation duration categories, and end-user segments. Top-down validation referenced corporate command center capital expenditure patterns and touring production budget allocations. CAGRs were derived from technology substitution curves and rental fleet refresh cycle compression. Forecast inputs incorporated REACH chemical registration expansion timelines and state-level e-waste mandate adoption rates.
The model holds under stable semiconductor foundry capacity allocation and continued pixel pitch compression trajectories; deviation in East Asian trade policy or abrupt driver IC supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Seven Segment Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Thin Display Technology Market
Display Technologies
Head Up Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Flexible OLED Market
Display Technologies
Plasma Display Module Market
Display Technologies
Video Projector Market
Display Technologies
DLP Projector Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Privacy Screens Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Light Field Display Market