
 Low Power Display Market | 2026-2036
Low Power Display Market Size, Share, and Industry Trends Forecast 2026-2036
Low Power Display Market Foresight
High-resolution AMOLED specifications with sub-1-watt idle power draw is reorganizing procurement priorities across device OEMs. Samsung Display leverages captive OLED foundry capacity to anchor premium smartphone supply chains. BOE Technology Group sustains aggressive Gen-6 flexible OLED expansion to compete for wearable panel contracts. E Ink Holdings dominates reflective electrophoretic technology for e-reader applications requiring weeks-long battery endurance.
Low power display denotes emissive or reflective screen technologies engineered to minimize energy consumption per rendered frame, typically operating below 500 milliwatts in active mode and micro-watts in standby through techniques such as partial screen refresh, ambient light harnessing, and self-illuminating pixel architectures. These systems serve battery-constrained devices where display subsystem drain determines usable runtime between charges. Active matrix OLED configurations command the highest value per unit in smartphone and smart watch deployments where deep black states eliminate backlight drain entirely. E-Ink reflective panels occupy a mature, high-margin niche in e-reader hardware where color transition speed constraints limit competitive entry. Passive matrix LCD segments face structural compression as active matrix backplanes displace them from industrial handheld terminals.
FCC equipment authorization rules in the United States constrain electromagnetic emissions from display driver circuits, while the EU Ecodesign Directive mandates standby power ceilings that directly favor low-power panel selection in imported devices. China's MIIT enforces GB standard compliance for display energy efficiency labeling, creating market access friction for non-conforming imports. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional e-waste directives that will increasingly internalize lifecycle energy costs into panel procurement decisions.
Market Dynamics
Dual carbon mandates across East Asia and the EU are compressing display subsystem power budgets, forcing OEMs to abandon legacy backlight architectures in favor of self-illuminating or ambient-light-harnessing alternatives.
Growth Catalysts
- EU Ecodesign Directive:Standby power ceilings for imported electronics are mandating low-power panel selection in consumer devices entering European distribution channels.
- Wearable OEM procurement:Smartwatch and fitness tracker manufacturers are expanding orders for reflective and emissive panels that extend battery endurance between charges.
- China's dual carbon goals:MIIT enforcement of GB standard compliance for display energy efficiency labeling is accelerating domestic substitution of high-drain LCD backlights.
Market Restraints
- Flexible OLED substrate cost volatility:Polyimide and thin-film encapsulation material prices fluctuate with specialty chemical feedstock markets, compressing margin predictability for Gen-6 fabs.
- South Korean supply concentration:Captive OLED foundry capacity in Seoul and Gumi creates procurement bottlenecks when geopolitical friction disrupts cross-border component flows.
- Reflective panel refresh-rate ceiling:Electrochromic and electrophoretic technologies face hard physics limits on color transition speed that constrain video-capable applications.
Strategic Opportunities
- India BIS energy labeling:Mandatory star ratings for electronic displays create first-mover advantage for low-power panel suppliers establishing local assembly partnerships.
- Automotive e-mirror applications:Side-view and rear-view camera-monitor systems in electric vehicles demand sunlight-readable reflective panels with near-zero standby draw.
- Hybrid reflective-emissive convergence:Dual-mode architectures combining E-Ink static states with mini-LED local dimming are opening medical wearable and industrial handheld niches.
Industry Challenges
- AMOLED backplane lithography talent scarcity:Gen-6 flexible fabrication requires process engineers with compound semiconductor experience that outstrips vocational pipeline output in East Asian manufacturing clusters.
- FCC Part 15 certification timelines:Display driver electromagnetic emission testing for US market entry adds quarters to product launch schedules for non-captive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Power Display Market |
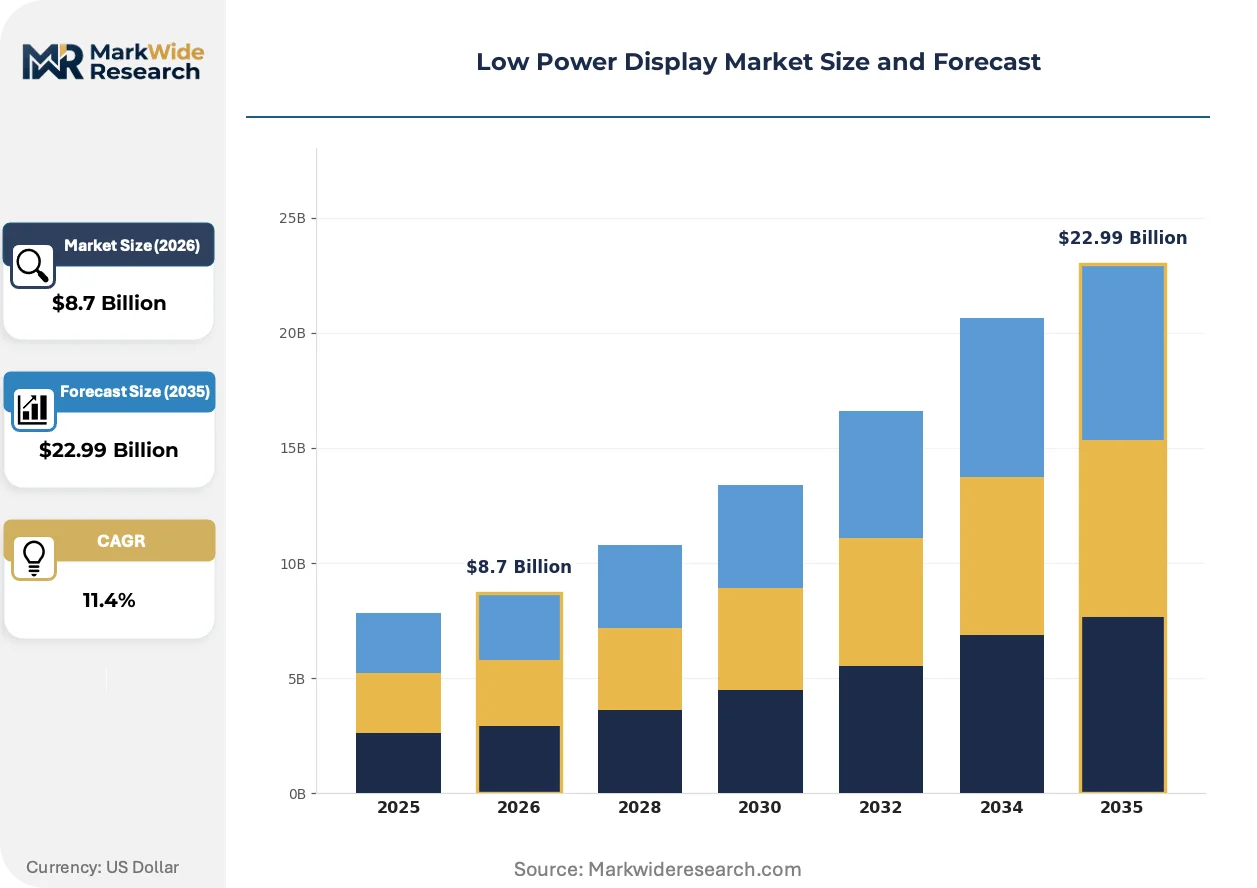
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, E-Ink, MicroLED End User: Consumer Electronics, Automotive, Wearables, Industrial Technology: Passive Matrix, Active Matrix, Digital Signage, Flexible Displays Application: Smartphones, Tablets, Smart Watches, E-Readers |
| Companies Covered | Samsung Display, BOE Technology Group, LG Display, AU Optronics Corporation, Visionox Technology, Sharp Corporation, Universal Display Corporation, E Ink Holdings, Innolux Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Power Display Market Shifts & Advancements
Panel architecture is splitting between premium emissive stacks for dynamic content and ultra-low-power reflective surfaces for static information display, with hybrid intermediates carving out specialized verticals.
LTPO backplane technology is bifurcating smartphone and smartwatch display supply chains. Variable refresh-rate oxide semiconductors enable 1-120Hz dynamic scaling that cuts active-mode power by half versus legacy LTPS. Apple and Samsung flagship procurement is compressing LTPS into mid-tier handset segments while LTPO captures premium wearable contracts.
China's MIIT is tightening GB 21520 energy efficiency testing protocols for computer monitors and televisions. The revised standard lowers maximum active-mode power thresholds by approximately one-third versus 2015 baselines. Domestic brands including Xiaomi and Hisense are accelerating mini-LED backlight adoption to maintain market access while foreign suppliers face retesting costs.
Healthcare procurement officers are unbundling display subsystem specifications from整机 vendor contracts. Hospital IT departments now source patient monitor panels separately through specialized distributors, prioritizing IEC 60601-1-8 alarm signal compliance and sub-300-mW idle draw over brand loyalty. This pattern concentrates in German and Japanese acute care networks with centralized biomedical engineering functions.
Low Power Display Market Segmentation
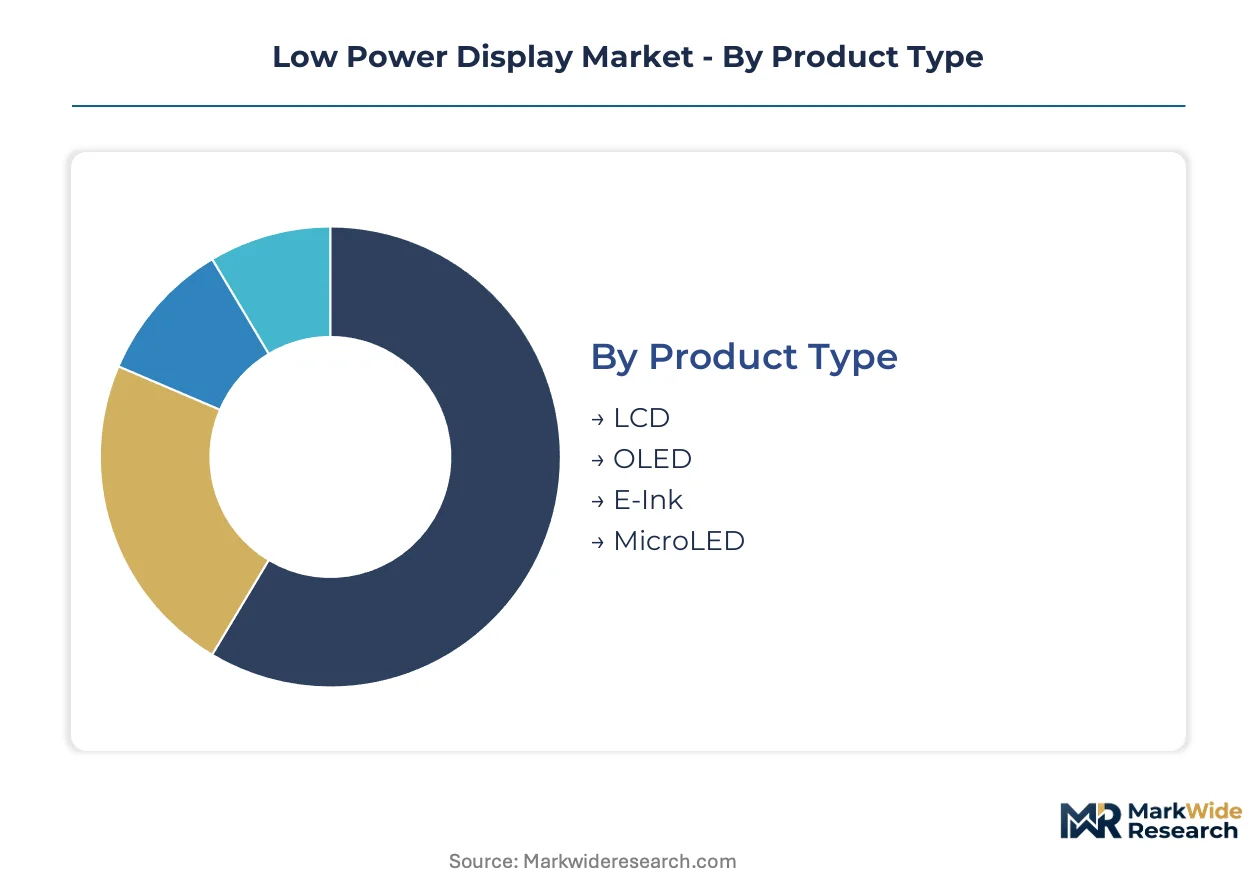
Low power display procurement splits across four analytical dimensions that reshape supplier targeting. Product type determines foundry partnerships and substrate chemistry investments. End user concentration drives certification requirements and power specification negotiations.
Product Type:
Domestic procurement in China and South Korea favors emissive architectures, while European and North American device OEMs import reflective panels for specialized endurance applications.
- LCD:Twisted nematic and in-plane switching configurations with edge-lit LED backlights dominate industrial handheld terminals and budget consumer devices. China's MIIT GB standard enforcement is accelerating domestic substitution toward lower-drain alternatives, compressing LCD share in premium tiers.
- OLED:Active matrix organic stacks with self-illuminating pixels eliminate backlight drain entirely, commanding premium smartphone and smartwatch contracts in Seoul and Gumi manufacturing clusters. Samsung Display and BOE Technology Group compete for Gen-6 flexible fab output with sub-1-watt idle specifications.
- E-Ink:Electrophoretic reflective technology harnesses ambient light for e-reader displays requiring weeks-long battery endurance.
- MicroLED:Gallium nitride micro-emitter arrays promise emissive efficiency with inorganic longevity for next-generation wearable deployments.
LCD commands the established base across industrial procurement. The steepest expansion runs through OLED as LTPO backplanes penetrate premium smartphone and wearable supply chains.
End User:
Cost tier segmentation separates certification-heavy automotive contracts from high-volume consumer electronics procurement with shorter qualification cycles.
- Consumer Electronics:Smartphones, tablets, and portable media players drive the highest unit volumes with aggressive annual refresh cycles. FCC Part 15 electromagnetic emission compliance and EU Ecodesign standby ceilings constrain supplier selection for US and European distribution channels.
- Wearables:Smartwatches and fitness trackers demand sub-300-milliwatt active draw with always-on display capability. Apple's procurement of LTPO oxide backplanes from Samsung Display and LG Display is bifurcating supply chains away from legacy LTPS.
- Automotive:Side-view camera-monitor systems and rear-view displays require sunlight-readable reflective panels with near-zero standby draw for electric vehicle applications.
- Industrial:Handheld terminals and process control monitors prioritize ruggedized enclosures and extended temperature operation over color gamut performance.
Consumer Electronics absorbs the highest unit volumes. Wearables is climbing the fastest as health-monitoring functionality extends device runtime requirements.
Technology:
Supply concentration in East Asian manufacturing clusters favors active matrix architectures, while passive matrix production fragments across smaller specialty fabs.
- Active Matrix:Thin-film transistor backplanes with oxide or LTPS semiconductors enable per-pixel addressing for high-resolution dynamic content. South Korean and Chinese Gen-6 fabs in Seoul, Gumi, and Chengdu concentrate captive capacity for smartphone and tablet applications.
- Flexible Displays:Polyimide substrate technology with thin-film encapsulation enables curved and foldable form factors for premium wearable contracts. Material cost volatility in specialty chemical feedstock markets compresses margin predictability for non-integrated suppliers.
- Passive Matrix:Simplified row-column addressing suits low-resolution indicator panels and simple numeric displays with minimal driver circuitry.
- Digital Signage:Large-format reflective or transflective installations for retail and transportation hubs prioritize sunlight readability over refresh rate performance.
Active Matrix commands the established base across smartphone procurement. Flexible Displays is gaining share fastest as foldable form factors penetrate premium tier contracts.
Application:
Volume scale separates billion-unit smartphone procurement from niche medical and industrial deployments with specialized compliance requirements.
- Smartphones:Flagship devices specify LTPO backplanes with 1-120Hz variable refresh scaling to halve active-mode power versus legacy LTPS. Samsung Electronics and Apple procurement volumes determine foundry allocation priorities in Seoul and Gumi.
- Smart Watches:Always-on display requirements with multi-day battery endurance favor dual-mode architectures combining reflective static states with emissive active modes. Healthcare procurement unbundling in German and Japanese acute care networks is creating specialized distributor channels.
- Tablets:Larger active area multiplies power savings from self-illuminating pixel architectures in educational and enterprise deployments.
- E-Readers:Static text display with minimal refresh requirements sustains E Ink Holdings' dominance in reflective electrophoretic technology.
Smartphones commands the established base. Smart Watches is expanding most quickly as health-monitoring functionality extends runtime specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan prioritize emissive technology performance over unit cost, while procurement teams in India and Southeast Asia weigh reflective panel economics more heavily against battery-life specifications.
China
MIIT enforcement of GB 21520 energy efficiency standards is accelerating domestic substitution of high-drain LCD backlights in computer monitors and televisions. The revised protocol lowers maximum active-mode power thresholds by approximately one-third versus 2015 baselines. Gen-6 flexible OLED fabs in Chengdu and Beijing are expanding captive capacity to serve Xiaomi and Hisense procurement contracts.
South Korea
Seoul and Gumi manufacturing clusters concentrate captive OLED foundry capacity for premium smartphone and smartwatch supply chains. Samsung Display leverages in-house semiconductor backplane expertise to anchor LTPO oxide contracts for Apple and domestic electronics brands. Geopolitical friction periodically disrupts cross-border component flows, creating procurement bottlenecks for non-captive buyers.
Japan
METI industrial policy supports display energy efficiency labeling for consumer electronics entering domestic distribution. Sharp Corporation maintains legacy LCD capacity for industrial handheld terminals while researching micro-emitter architectures. Healthcare procurement unbundling in Tokyo and Osaka acute care networks is creating specialized distributor channels for patient monitor panels.
United States
FCC Part 15 equipment authorization rules constrain electromagnetic emissions from display driver circuits, adding quarters to product launch schedules for non-captive suppliers. California and Texas device OEMs prioritize sub-1-watt idle specifications for wearable deployments. Universal Display Corporation's phosphorescent emitter licensing anchors domestic OLED material supply to East Asian panel fabricators.
Germany
EU Ecodesign Directive standby power ceilings mandate low-power panel selection in electronics entering European distribution channels. German automotive OEMs in Stuttgart and Munich are sourcing sunlight-readable reflective panels for electric vehicle camera-monitor systems. Hospital IT departments in Berlin and Frankfurt unbundle display subsystem specifications from整机 vendor contracts, prioritizing IEC 60601-1-8 alarm compliance.
Low Power Display Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with emissive stack innovators competing against reflective panel specialists for distinct procurement budgets. The market structure concentrates around three strategic tiers: captive OLED foundry operators, flexible substrate fabricators, and electrophoretic technology licensors. Dominant competitive moves include Gen-6 fab capacity expansion in East Asian manufacturing clusters and strategic patent licensing for phosphorescent emitter materials.
Among East Asian display specialists, Samsung Display and BOE Technology Group exemplify the captive foundry archetype, each leveraging in-house semiconductor backplane expertise to anchor premium smartphone and wearable contracts. E Ink Holdings occupies a distinct positioning as the licensor of reflective electrophoretic technology, sustaining high-margin dominance in e-reader applications where color transition speed constraints limit competitive entry. These three entities represent the primary competitive anchors around which procurement negotiations and supply chain configurations organize.
| Leading Market Players |
|---|
| Samsung Display |
| BOE Technology Group |
| LG Display |
| AU Optronics Corporation |
| Visionox Technology |
| Sharp Corporation |
| Universal Display Corporation |
| E Ink Holdings |
| Innolux Corporation |
| Others |
Supply & Pricing Matrix
Gen-6 flexible OLED fab scale economies in Seoul, Gumi, and Chengdu concentrate pricing power among captive foundry operators while compressing margin floors for non-integrated panel suppliers competing for mid-tier wearable contracts. This capacity concentration simultaneously elevates entry barriers for reflective technology specialists and forces price discipline on legacy LCD backlight architectures facing MIIT GB standard compliance costs.
Pricing Analysis
EU Ecodesign Directive standby power ceilings dictate the pricing tier structure across European distribution channels, separating premium LTPO backplane contracts from standard LTPS and economy-grade LCD procurement. Price differentiation rests on certification grade and volume scale, with FCC Part 15 compliance adding cost layers for non-captive suppliers targeting US device OEMs. Cost compression in passive matrix LCD tiers is intensifying because MIIT enforcement accelerates domestic substitution toward lower-drain alternatives. Budget consumer electronics OEMs exhibit highest price sensitivity, while German automotive and Japanese healthcare procurement teams prioritize IEC 60601-1-8 alarm compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes underpin polyimide substrate and thin-film encapsulation chemical feedstock flows to East Asian manufacturing clusters. Supply concentrates in South Korea, China, and Japan for active matrix backplane fabrication, with gallium nitride micro-emitter arrays and phosphorescent emitter materials drawing from US and European specialty chemical suppliers. Single-source vulnerability in Seoul and Gumi captive OLED foundry capacity creates procurement bottlenecks when geopolitical friction disrupts cross-border component flows. Distribution runs through specialized display distributors serving hospital IT departments and direct procurement contracts with flagship smartphone OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from hybrid reflective-emissive architectures that combine E-Ink static states with mini-LED local dimming for medical wearable and industrial handheld applications.
For Market Incumbents: Secure captive semiconductor backplane expertise through targeted hiring of compound semiconductor process engineers in East Asian manufacturing clusters. Deepen upstream control over phosphorescent emitter material licensing to defend margin position against Universal Display Corporation royalty structures. Counter hybrid reflective-emissive entrants by accelerating dual-mode R&D investment for smartwatch always-on display specifications. For New Entrants and Emerging Players: Anchor in India's BIS energy labeling mandate to establish first-mover advantage before local assembly partnerships solidify. Target automotive e-mirror applications in German and US electric vehicle supply chains where sunlight-readable reflective panels face limited incumbent competition. Pursue hospital IT department direct procurement channels in German and Japanese acute care networks as healthcare specifications unbundle from整机 vendor contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reflective electrophoretic technology licensors with defensible patent moats and high-margin e-reader application concentration. Long-term viability hinges on diversification into hybrid architectures and automotive camera-monitor systems. Watch for inflection signals in mini-LED backlight adoption rates among Chinese domestic brands facing retesting costs under revised GB 21520 protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Gen-6 Flexible OLED Capacity Expansion | Captive foundry additions in Chengdu and Beijing serve Xiaomi and Hisense procurement contracts under MIIT enforcement. |
| Phosphorescent Emitter Licensing Agreement | Universal Display Corporation material supply anchors domestic US chemistry to East Asian panel fabricators. |
| Hybrid Reflective-Emissive Product Launch | Dual-mode architectures penetrate medical wearable niches requiring IEC 60601-1-8 alarm compliance. |
| India BIS Certification Investment | Mandatory star ratings for electronic displays create procurement preference for compliant low-power panel suppliers. |
| Automotive E-Mirror Supply Agreement | German OEMs in Stuttgart and Munich source reflective panels for electric vehicle camera-monitor systems. |
Research Methodology
A spread of perspectives from display procurement managers at wearable OEMs, semiconductor process engineers at Gen-6 fabs, healthcare biomedical engineering directors, and automotive Tier 1 supplier quality leads converged on the working assumptions for this analysis. Primary interview insights combined with secondary validation from SEC filings of listed display specialists, MIIT GB standard documentation, EU Ecodesign Directive regulatory texts, and FCC Part 15 equipment authorization databases. Bottom-up panel shipment aggregation and top-down display subsystem value triangulation anchored market size estimates.
Segmentation dimensions modeled span product type, end user concentration, technology architecture, and application vertical across the projection horizon. CAGRs derive from shipment trajectory analysis and value-per-unit evolution in premium versus mass-market tiers. Forecast inputs incorporate LTPO backplane penetration rates in smartphone procurement, E-Ink reflective panel attach rates in e-reader hardware, and mini-LED backlight substitution curves under Chinese energy efficiency enforcement.
Underlying assumptions cover stable polyimide substrate chemical feedstock pricing, continued MIIT GB standard enforcement trajectory, and unimpeded cross-border component flows through East Asian manufacturing clusters, with deviation risk concentrated in geopolitical friction disrupting Seoul and Gumi supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Multimedia Projectors Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
4K VR Displays Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
United States Microdisplay Market
Display Technologies
Display Port Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Collaboration Display Market
Display Technologies
Smart Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Global Portable Monitor Market