
 Projector Screen Market | 2026-2036
Projector Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Projector Screen Market Analysis
Modular screen-and-projector bundling is pivoting procurement patterns across commercial AV channels. Draper leverages its North American manufacturing footprint to sustain short-lead-time contracts for institutional buyers. Elite Screens competes aggressively on price in the portable segment while Grandview Crystal Screen anchors premium fixed-frame distribution through specialized integrators.
A projector screen is an optically treated surface, typically composed of PVC, fiberglass, or woven textile substrates with calibrated gain coefficients between 0.8 and 1.5, engineered to reflect projected light with minimal hot-spotting and color shift for cinema, presentation, or broadcast applications. Fixed frame configurations dominate margin pools in residential channels where acoustic transparency commands premium positioning, while electric motorized variants lead volume growth in corporate and educational retrofit projects. Portable units occupy a mature, price-sensitive tier serving mobile event organizers and temporary classroom deployments.
The US Consumer Product Safety Commission monitors flammability standards for textile-based screen materials deployed in public venues, while California's Proposition 65 disclosure requirements influence substrate chemistry selection for products sold into the state. The FCC's equipment authorization rules shape integration protocols when screens ship with embedded RF control modules for motorized operation. Stakeholders should track evolving state-level chemical restriction frameworks and projector interoperability standards before committing to multi-year platform investments.
Market Dynamics
Hybrid workplace mandates are compressing procurement cycles for motorized electric screens as corporate AV teams consolidate meeting room standards across distributed campuses. China's GB standards for display surface reflectivity are forcing substrate reformulations that ripple through global supply chains.
Growth Catalysts
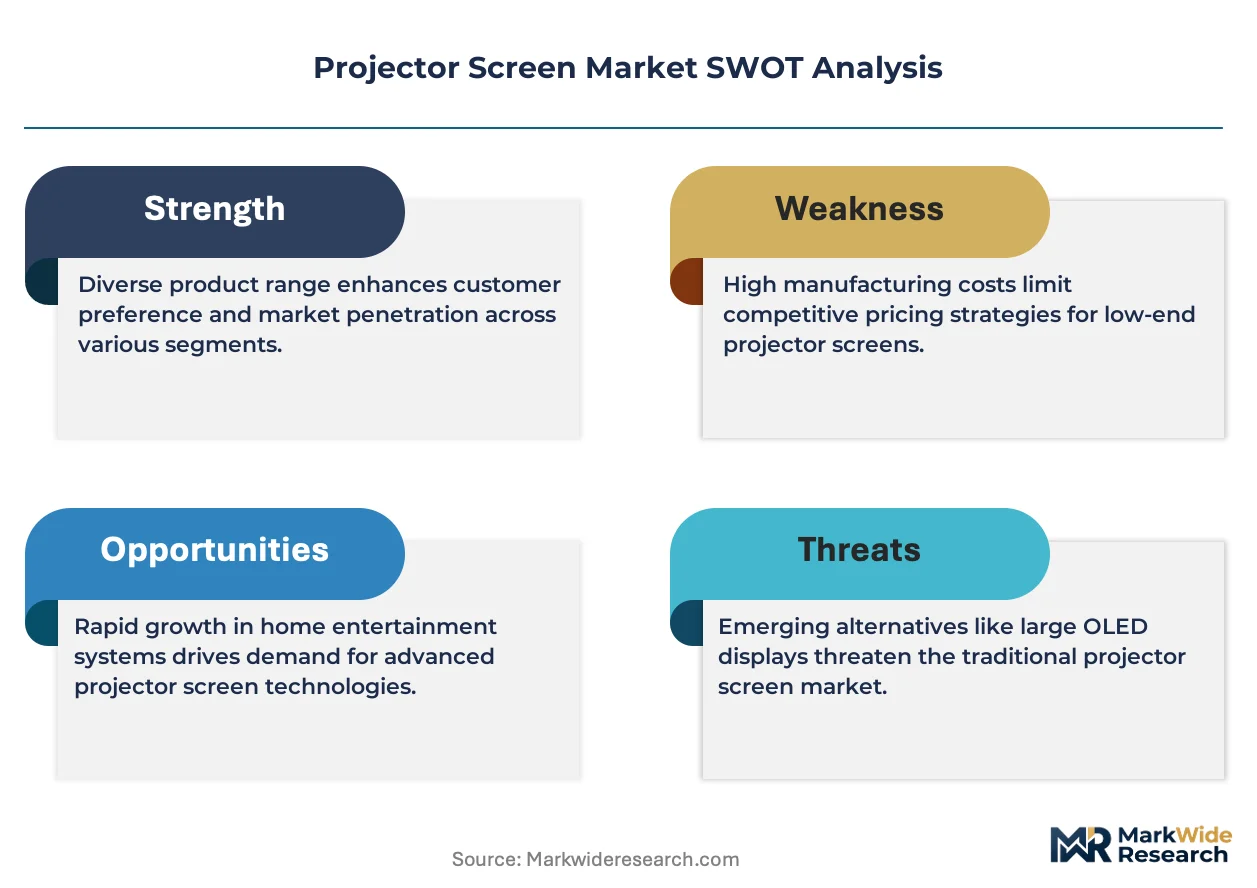
- GB Standards Compliance:China's tightening regulations on display surface reflectivity are compelling manufacturers to upgrade optical coating formulations, creating upgrade demand across institutional channels.
- Hybrid Meeting Infrastructure:Corporate AV buyers are standardizing large-format electric screen deployments across retrofit conference rooms to support video-conferencing equity.
- Acoustic Transparency Premium:Fixed-frame screens with woven textile substrates are capturing margin expansion in residential cinema installations where sound-permeable surfaces command positioning.
Market Restraints
- PVC Price Volatility:Petrochemical feedstock fluctuations are compressing margins on commodity-grade portable screen production, particularly affecting Southeast Asian contract manufacturers.
- Flat-Panel Substitution:Direct-view LED and microLED displays are displacing projection in high-ambient-light corporate lobbies where screen gain coefficients cannot compensate.
- California Proposition 65:Disclosure requirements for phthalate-containing substrates are increasing compliance costs and limiting material sourcing flexibility for products sold into the state.
Strategic Opportunities
- India Higher Education:Central university expansion programs are creating tender opportunities for lecture hall electric screen installations with integrated RF control modules.
- FCC Equipment Authorization:Embedded wireless control protocols are enabling smart building integration contracts where screens synchronize with lighting and HVAC systems.
- Modular Bundling:Projector-and-screen packaged procurement is opening specification influence for screen manufacturers previously excluded from standalone projector decisions.
Industry Challenges
- Optical Calibration Expertise:Shortage of technicians trained in gain coefficient measurement and color temperature matching is delaying custom installation completions.
- Legacy Control Integration:RS-232 and infrared control protocols in existing building automation systems require adapter development for new IP-based screen motors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Projector Screen Market |
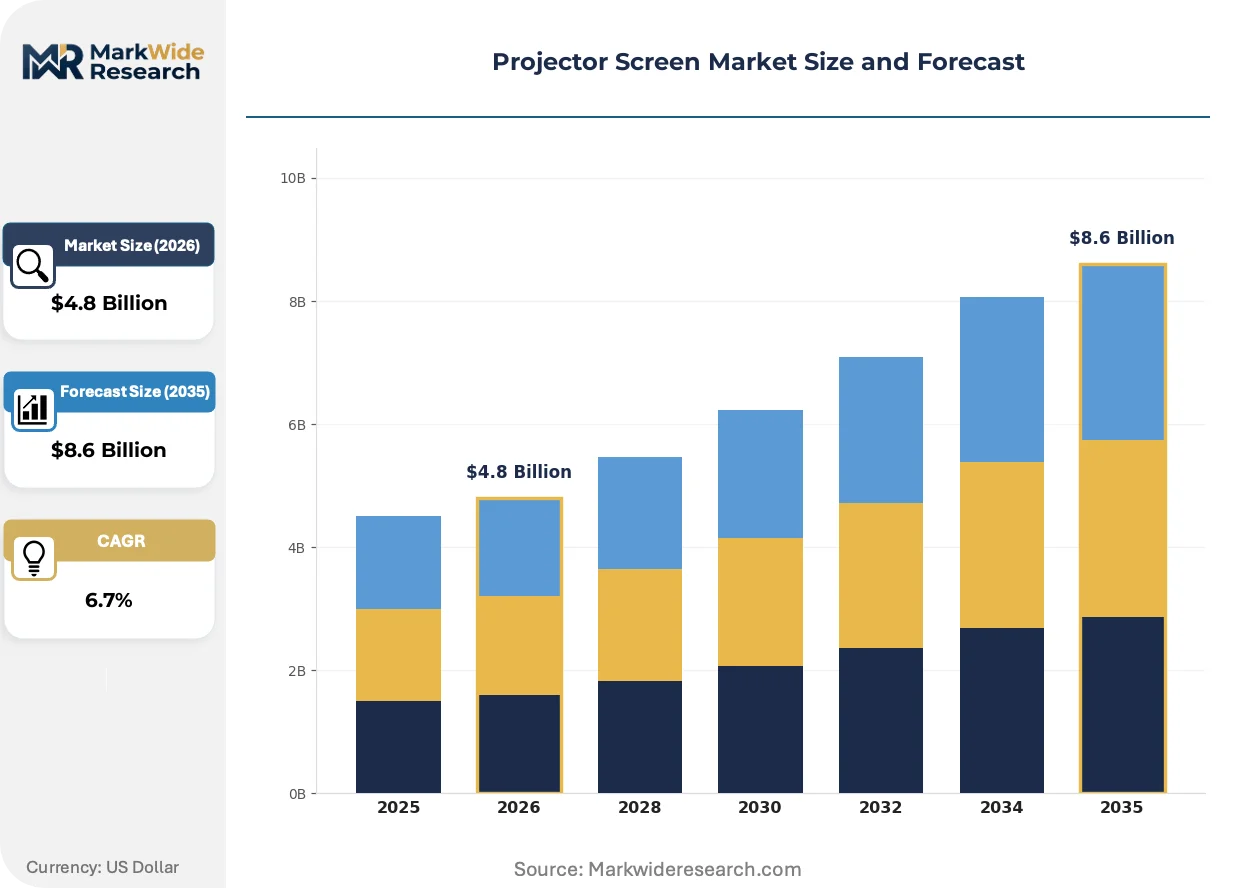
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Frame, Portable, Electric, Manual Technology: LCD, LED, DLP, Laser Application: Home Theater, Educational, Corporate, Outdoor End User: Schools, Businesses, Event Organizers, Individuals |
| Companies Covered | Screen Innovations, Strong MDI, Stewart Filmscreen, Grandview Crystal Screen, Seymour AV, Draper, EPV Screens, Screen Pro, Elite Screens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Projector Screen Market Emerging Trajectories
Active matrix switching and environmental sensing are embedding intelligence directly into screen surfaces, shifting value capture from passive substrates toward integrated AV systems. Manufacturers are repositioning around software-defined gain control and automated deployment protocols.
Tensioned tab-tensioning systems with embedded edge sensors are automating surface flatness calibration in real time during motorized deployment. Higher-education AV departments are specifying these units for lecture halls where thermal drift previously required manual seasonal adjustment. This technology is automating the service revenue model away from periodic maintenance contracts toward predictive replacement schedules.
REACH substance restrictions on perfluorinated compounds are eliminating legacy stain-resistant coatings from European-bound screen textiles, forcing reformulation toward silicone-based alternatives. Manufacturers serving EU integrators are certifying new substrate chemistries through ECHA notification procedures. The fixed-frame residential segment is absorbing these material costs through premium positioning rather than portable price tiers.
Bundled AV-as-a-service contracts are consolidating screen specification authority under managed workplace providers, displacing traditional integrator relationships. Corporate real estate teams in the United States are delegating meeting room standardization to national service providers with preferred vendor lists. This concentration is visible most acutely in Fortune 500 campus rollouts where single-source accountability overrides component-level procurement optimization.
Projector Screen Market Segmentation
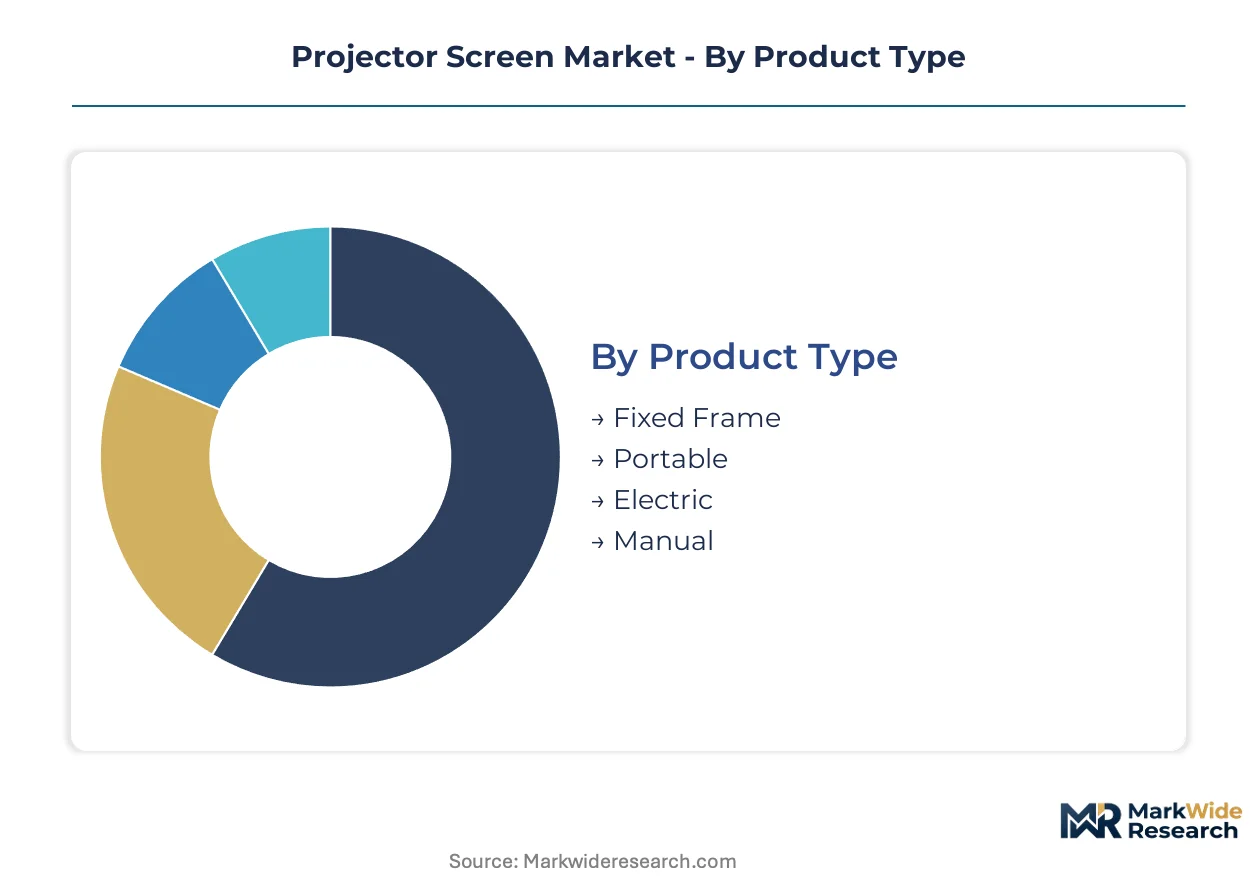
Projector screen procurement patterns diverge sharply between integrated AV installations and standalone deployments. Understanding these structural splits enables manufacturers to align coating formulations, control protocols, and distribution channels with actual purchase behavior rather than assumed category boundaries.
Product Type:
Fixed frame configurations anchor premium residential channels where acoustic transparency and zero-edge aesthetics command positioning, while portable and electric variants serve fundamentally different integration depths across commercial and mobile applications.
- Fixed Frame:Rigid aluminum or steel frames tension woven textile or PVC surfaces with gain coefficients calibrated between 0.8 and 1.3. Demand concentrates in United States residential cinema installations where sound-permeable woven substrates justify premium positioning against flat-panel alternatives.
- Electric:Motorized roller mechanisms with tubular motors and RF or IP control modules deploy into ceiling cavities or wall housings. Corporate AV buyers across distributed United States campuses are standardizing these units for hybrid meeting room retrofits requiring video-conferencing equity.
- Portable:Tripod or floor-rising frames with foldable surfaces prioritize rapid deployment weight targets under 15 kilograms. Event organizers in temporary classroom and mobile presentation circuits drive volume despite compressed margins from PVC feedstock volatility.
- Manual:Spring-roller or pull-down mechanisms without motorization occupy cost-sensitive retrofit tiers in legacy educational facilities. These units face replacement pressure as RF-controlled electric screens decline in unit cost.
Electric screens lead volumes today; fixed frame is gaining share fastest.
Technology:
Projection engine chemistry determines screen surface specifications, with each technology imposing distinct gain, contrast, and ambient light rejection requirements that shape substrate formulation priorities.
- LCD:Liquid crystal panels with high lumen output require matte white surfaces with gain coefficients near 1.0 to prevent hotspot artifacts. Educational procurement in India and Southeast Asia favors this pairing for lecture hall brightness requirements.
- Laser:Solid-state phosphor or RGB laser engines deliver extended color gamuts and 20,000-hour lifespans that justify premium screen investments. United States home theater integrators specify high-contrast gray surfaces with laser systems to enhance black levels.
- LED:Direct-view emissive displays are displacing projection entirely in high-ambient corporate lobbies, constraining screen demand to specialized rear-projection and blended edge cases.
- DLP:Digital micromirror devices with sequential color wheels perform optimally with neutral gain surfaces that preserve color accuracy. Corporate AV refresh cycles in Fortune 500 campuses maintain DLP-screen pairings for reliability.
Laser projection expands most quickly; LCD retains the largest installed base.
Application:
End-use environment dictates surface durability, deployment mechanism, and optical performance specifications, with indoor fixed installations operating on fundamentally different procurement cycles than mobile or weather-exposed deployments.
- Home Theater:Dedicated residential cinema rooms specify fixed-frame acoustic transparent screens with woven textile substrates. United States consumers absorb material cost increases from REACH-compliant coating reformulations through premium positioning.
- Corporate:Meeting room and boardroom deployments prioritize electric motorized screens with building automation integration. Hybrid workplace mandates across United States commercial real estate portfolios are compressing procurement cycles for standardized room configurations.
- Educational:K-12 classrooms and university lecture halls balance durability against replacement budgets. India's central university expansion programs are creating tender opportunities for electric screen installations with integrated RF control.
- Outdoor:Weather-resistant PVC or coated polyester surfaces with reinforced frames serve temporary event and permanent venue applications. These units require specialized edge sealing and UV stabilization that differentiates formulation from indoor grades.
Corporate applications lead volumes today; outdoor is climbing the fastest.
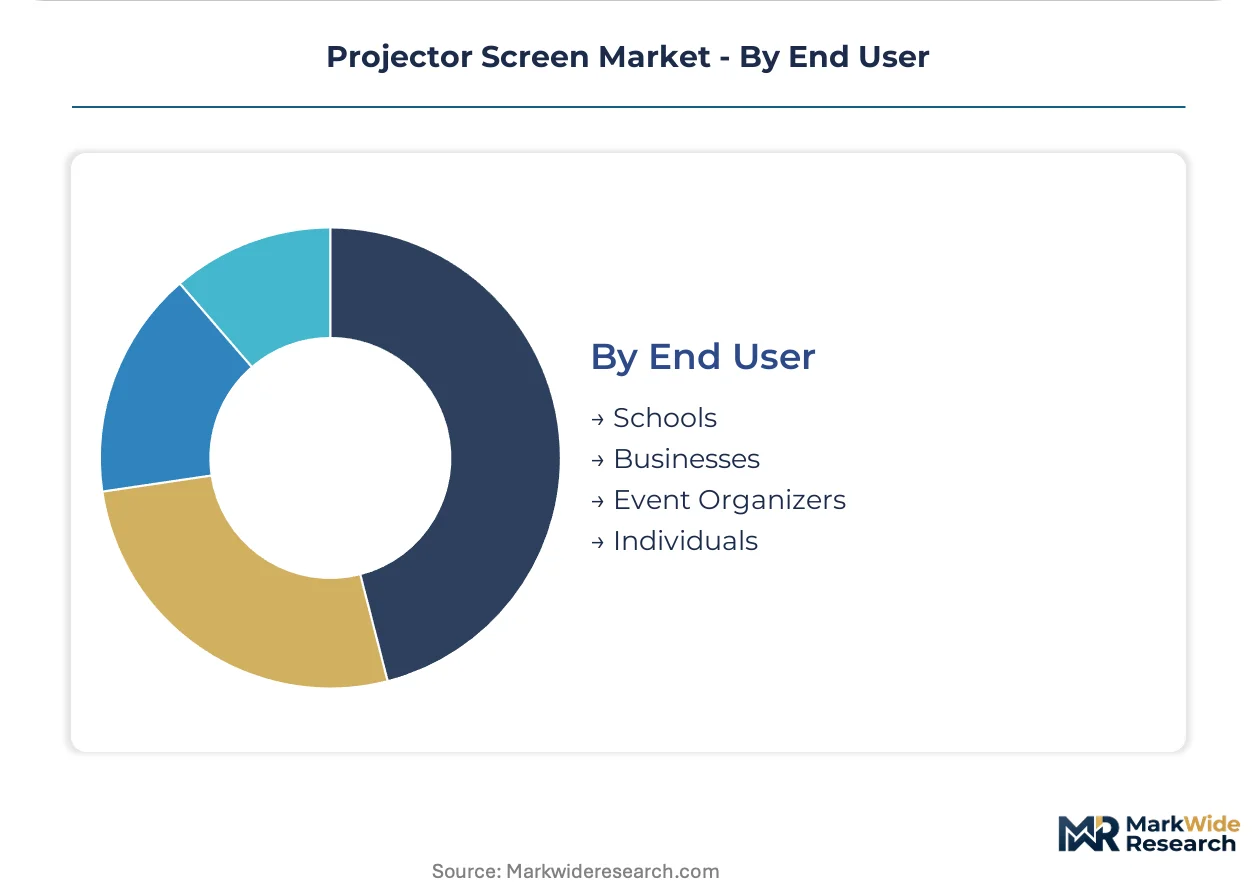
End User:
Purchasing authority and technical specification involvement vary dramatically between institutional procurement departments, individual consumers, and event service providers with distinct integration capabilities.
- Schools:District-level AV coordinators specify standardized electric screen models across multiple campuses. California's Proposition 65 disclosure requirements for phthalate-containing substrates constrain material sourcing flexibility for products sold into the state.
- Businesses:Corporate real estate teams delegate meeting room standardization to national managed workplace providers with preferred vendor lists. This concentration displaces traditional integrator relationships in Fortune 500 rollouts.
- Event Organizers:Rental and staging companies prioritize rapid-deployment portable units with standardized case dimensions for truck packing. Price sensitivity in this channel limits specification of premium tensioned surfaces.
- Individuals:Direct-to-consumer e-commerce channels serve residential purchasers with DIY installation capabilities. Acoustic transparency and zero-edge aesthetics command positioning in this segment despite higher unit costs.
Businesses lead volumes today; schools are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The projector screen industry traces its commercial origins to mid-20th century United States cinema exhibition, where fixed-frame tensioned surfaces first standardized theatrical presentation quality. From this foundation, manufacturing expertise dispersed across North American, European, and Asia-Pacific industrial clusters, each developing distinct specialization in substrate chemistry, motorized mechanisms, or optical coating formulations.
United States
Higher-education institutions in Texas and California are driving electric screen retrofits for hybrid lecture hall deployments. The FCC's equipment authorization rules govern RF control modules integrated into motorized units. Indianapolis and Chicago host concentrated manufacturing operations serving institutional buyers with short-lead-time contracts.
China
GB standards for display surface reflectivity are compelling substrate reformulations across Guangdong and Zhejiang production facilities. The Ministry of Ecology and Environment monitors chemical discharge from coating operations in the Pearl River Delta. Shenzhen-based fabricators are upgrading optical laboratories to certify compliance with tightened gain coefficient tolerances.
Germany
REACH substance restrictions on perfluorinated compounds are eliminating legacy stain-resistant coatings from screen textiles bound for EU integrators. ECHA notification procedures govern new silicone-based alternative certifications. Bavarian industrial clusters near Munich specialize in precision tensioning mechanisms for premium fixed-frame residential installations.
India
Central university expansion programs are creating tender opportunities for lecture hall electric screen installations in Maharashtra and Karnataka. The Bureau of Indian Standards oversees textile flammability specifications for public venue deployments. Hyderabad and Bengaluru host emerging AV integration service providers targeting educational procurement channels.
Japan
Corporate real estate teams in Tokyo and Osaka are standardizing motorized screen configurations for hybrid workplace retrofits. METI guidelines influence building automation integration protocols for IP-controlled deployment systems. Nagoya-area manufacturers supply precision tubular motors for tensioned tab-tensioning mechanisms.
Projector Screen Market Vendor Landscape
Premium-margin players sit above commodity-margin players across optical performance tiers and integration depth. The vendor base stratifies between specialized acoustic-transparent fabricators, volume electric-screen assemblers, and portable-unit contract manufacturers. Three strategic archetypes dominate: North American integrator-captive specialists, Asia-Pacific scale producers, and European premium-craft workshops. Competitive moves center on modular bundling partnerships with projector OEMs and backward integration into substrate coating operations.
Among North American fabricators, Draper Inc. and Stewart Filmscreen occupy positions in the institutional and premium residential tiers respectively, while Elite Screens represents the volume-accessible segment. These three exemplify how geographic manufacturing footprints align with service model differentiation—short-lead-time domestic production versus Asia-Pacific cost optimization versus craft-scale customization.
| Leading Market Players |
|---|
| Screen Innovations |
| Strong MDI |
| Stewart Filmscreen |
| Grandview Crystal Screen |
| Seymour AV |
| Draper |
| EPV Screens |
| Screen Pro |
| Elite Screens |
| Others |
Supply Flow & Price Mechanics
Fortune 500 corporate real estate teams consolidating meeting room standards under national managed workplace providers are anchoring contract-based pricing for electric motorized screens. This buyer concentration shifts negotiation leverage toward volume-scale discounts and away from component-level premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates acoustic-transparent fixed-frame screens from basic electric units and commodity portable tripods. Price differentiation rests on optical coating certification grade and after-sales service bundling. Cost compression in the portable tier is intensifying because PVC feedstock volatility squeezes Southeast Asian contract manufacturers. Event organizers exhibit highest price sensitivity, while United States residential cinema buyers absorb premium positioning for woven textile substrates.
Supply Chain Analysis
Refurbishment flows for motorized screen mechanisms are emerging as China tightens GB standards on display surface reflectivity, forcing substrate reformulation cycles. Manufacturing concentrates in China, the United States, and Germany, with Guangdong fabricators supplying optical coatings, Indianapolis-area plants serving short-lead-time institutional contracts, and Bavarian workshops producing precision tensioning systems. Raw material dependencies draw from petrochemical-based PVC, woven textile substrates, and tubular motor components. Single-source vulnerability in optical coating formulation expertise threatens supply continuity. Distribution runs through specialized AV integrators, direct institutional procurement, and managed workplace provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in acoustic-transparent fixed-frame residential channels where REACH-compliant coating reformulations justify premium absorption, and in smart building integration contracts where embedded RF control modules capture recurring service value.
For Market Incumbents: Lock in specification influence through modular bundling partnerships with projector OEMs, capturing procurement decisions previously reserved for standalone projector vendors. Flat-panel substitution in high-ambient corporate lobbies threatens projection-based revenue streams; counter this by deepening captive supply of optical coating operations to preserve formulation expertise barriers against commodity competitors. For New Entrants and Emerging Players: National managed workplace providers represent the most accessible channel for electric screen penetration, as these consolidating buyers seek second-source alternatives to incumbent vendor lists. India's central university expansion programs offer tender-accessible white space for RF-integrated lecture hall installations. A specification-led go-to-market targeting educational AV coordinators with compliance-ready documentation accelerates procurement cycle entry. For Investors and Strategic Acquirers: Projector OEMs are the most active acquirer in this space, seeking backward integration into screen specification authority to complete bundled system offerings. Long-term viability hinges on substrate chemistry differentiation and software-defined gain control capabilities rather than mechanical motor assembly. Acquisition target archetypes include specialized acoustic-transparent fabricators with ECHA-certified coating portfolios. Monitor GB standards enforcement intensity in Guangdong production clusters as an inflection indicator for upgrade-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Coating Operations | Captures formulation expertise barriers against PVC commodity competitors in Guangdong. |
| Smart Building Integration Partnership | Enables FCC-authorized RF modules to synchronize with lighting and HVAC control systems. |
| REACH-Compliant Coating Certification | Unlocks EU residential premium positioning as ECHA eliminates perfluorinated alternatives. |
| Modular Projector-Screen Bundling | Shifts specification authority from standalone projector decisions to integrated system vendors. |
| India Higher Education Tender Positioning | Captures central university expansion programs in Maharashtra and Karnataka with BIS-compliant documentation. |
Methodological Framework
Multiple input streams — primary interviews with AV integration specialists, corporate real estate technology directors, and educational procurement coordinators; secondary validation through SEC filings, customs trade records, and FCC equipment authorization databases; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Hyperscaler capex disclosures and building automation system vendor reports provided additional demand-side calibration.
Data-stream reconciliation across product type, projection technology, application environment, and end-user purchasing authority dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis rather than single-point extrapolation. Forecast inputs incorporated GB standards compliance timelines, REACH substance restriction phase-outs, and hybrid workplace mandate diffusion patterns across Fortune 500 commercial real estate portfolios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to flat-panel substitution rates in corporate lobbies and petrochemical feedstock volatility affecting PVC substrate costs. Practitioners should monitor GB standards laboratory certification backlogs in Shenzhen and managed workplace provider vendor list consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
LCD Panel Market
Display Technologies
3LCD Projector Market
Display Technologies
Screenless Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Global Transparent Display Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Portable Projector Market
Display Technologies
DLP Projector Market
Display Technologies
E-Paper Display Market
Display Technologies
Global Embedded Display Market
Display Technologies
Foldable Screens Market
Display Technologies
Touch Screen Module Market
Display Technologies
Microdisplay Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market