
 Electronic Measuring Device Market | 2026-2036
Electronic Measuring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Measuring Device Market Analytics
Precision-grade instrumentation is bifurcating the competitive landscape into premium calibration laboratories and cost-optimized field-service tiers. Keysight Technologies leverages deep R&D partnerships with semiconductor foundries to sustain technology leadership in vector network analysis. Tektronix anchors its position through specialized high-bandwidth oscilloscope architectures that dominate aerospace validation protocols.
An electronic measuring device converts physical quantities into quantified electrical signals with specified accuracy classes, typically achieving resolution down to microvolt or micrometer scales depending on sensor architecture; these instruments serve critical functions in quality assurance, process control, and compliance verification across manufacturing environments. Oscilloscope demand concentrates in electronics end-user segments where margin pools sit with multi-channel mixed-signal units, while wireless technology variants represent the fastest-growing architecture as industrial IoT deployments expand remote monitoring capabilities. Multimeter applications span mature industrial maintenance workflows where digital technology has largely displaced analog interfaces.
FDA oversight of medical-grade electronic measuring devices shapes validation requirements for biopotential amplifiers, while FCC Part 15 regulations govern wireless and Bluetooth transmission modules embedded in field instruments. IEC 61010 safety standards dictate insulation ratings and ingress protection levels that determine market access across European and Asian jurisdictions. Stakeholders must monitor evolving cybersecurity mandates for connected measurement infrastructure as regulatory scope expands beyond traditional electromagnetic compatibility into data integrity assurance.
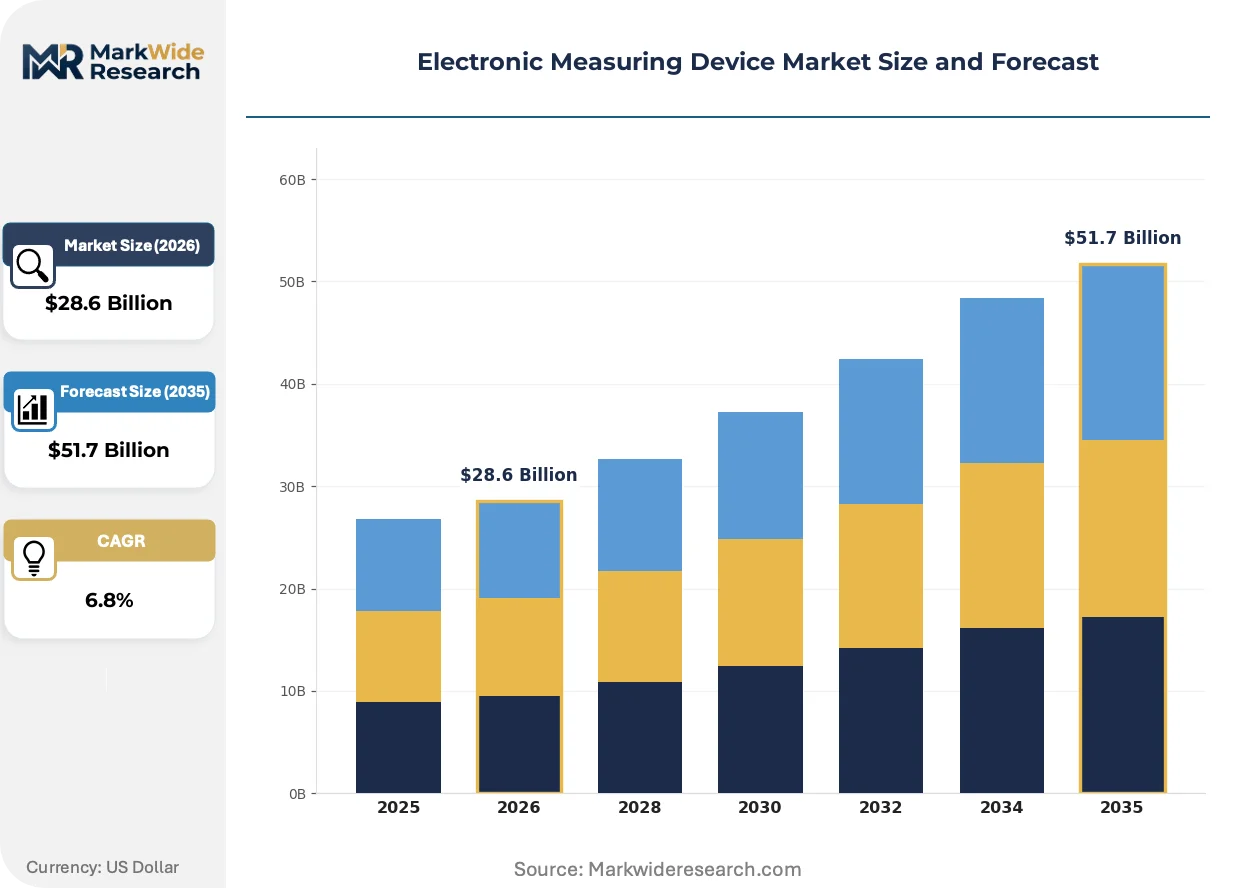
Market Dynamics
Semiconductor fabrication complexity is forcing a recalibration of metrology requirements across the value chain, as Taiwan and South Korean foundries demand sub-nanometer precision in voltage and impedance characterization tools.
Growth Catalysts
- Industrial IoT Deployment:Factory automation corridors in China mandate networked measurement infrastructure for real-time process control, accelerating Bluetooth-enabled multimeter adoption under IEC 61010-1 safety protocols.
- REACH Substance Restrictions:European environmental compliance is phasing out legacy solder and coating materials, compelling instrument manufacturers to redesign probe assemblies and chassis materials.
- Automotive Electrification:German automotive testing clusters require high-bandwidth oscilloscope architectures for power electronics validation, creating sustained demand for multi-channel mixed-signal units.
Market Restraints
- Precision Component Concentration:Specialized ADC and FPGA supply concentrates among Taiwanese and Japanese semiconductor vendors, exposing instrument OEMs to allocation risk during fab capacity constraints.
- Calibration Infrastructure Cost:Primary voltage and resistance standards require climate-controlled laboratory environments with capital intensity that excludes smaller field-service providers from premium tier participation.
- Wireless Module Certification:FCC Part 15 and ETSI EN 300 328 testing protocols for embedded Bluetooth radios extend product development timelines by six to nine months for connected instrument launches.
Strategic Opportunities
- India Industrial Corridors:PLI scheme incentives for electronics manufacturing are attracting contract manufacturers that require localized calibration services and cost-optimized measurement tool procurement.
- Cloud-Native Analytics:Convergence of edge computing architectures with time-synchronized measurement networks enables predictive maintenance models that unbundle hardware from recurring software revenue.
- Medical Device Cybersecurity:FDA premarket guidance on connected diagnostic instruments creates compliance service opportunities for validation of data integrity in biopotential measurement systems.
Industry Challenges
- Metrology Talent Scarcity:RF and microwave measurement expertise concentrates among aging specialist populations, constraining R&D velocity for vector network analyzer development teams.
- Legacy System Interoperability:GPIB and LXI protocol translation requirements complicate integration of new instruments into established aerospace validation test stands with thirty-year equipment lifecycles.
- Multi-Domain Certification Burden:Simultaneous compliance with IEC 61010 electrical safety, ISO 17025 calibration accreditation, and sector-specific FDA or FAA requirements fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Measuring Device Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Calipers, Measuring Tapes Technology: Analog, Digital, Wireless, Bluetooth End User: Industrial, Construction, Automotive, Electronics Measurement Type: Length, Weight, Voltage, Pressure |
| Companies Covered | Keysight Technologies, Tektronix, Fortive, Rohde & Schwarz, Teledyne LeCroy, National Instruments, Fluke Corporation, Yokogawa Electric Corporation, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Measuring Device Market Evolving Landscape
Wireless connectivity protocols are restructuring how measurement data flows from factory floors to enterprise systems, compressing the traditional boundary between field instruments and centralized analytics platforms.
Software-defined radio architectures are displacing discrete hardware signal chains in spectrum analyzers and vector network analyzers. Aerospace validation labs in the US and Germany are adopting these platforms at accelerated procurement cycles. This displacement is compressing hardware refresh intervals while expanding subscription-based feature licensing as the dominant revenue model.
EU AI Act risk classification rules are imposing documentation burdens on measurement instruments with embedded diagnostic algorithms. Industrial automation vendors must now maintain algorithmic transparency logs for smart sensor arrays. European process control segments are responding by segregating AI-enabled and deterministic-only product lines to simplify compliance scope.
Buyers in China's industrial automation corridors are consolidating vendor relationships around full-stack calibration service contracts rather than discrete instrument purchases. Distributors with captive metrology laboratories are capturing margin pools that previously flowed to independent service providers. This pattern is most visible in Jiangsu and Guangdong provinces where electronics contract manufacturers dominate procurement volume.
Electronic Measuring Device Market Segmentation
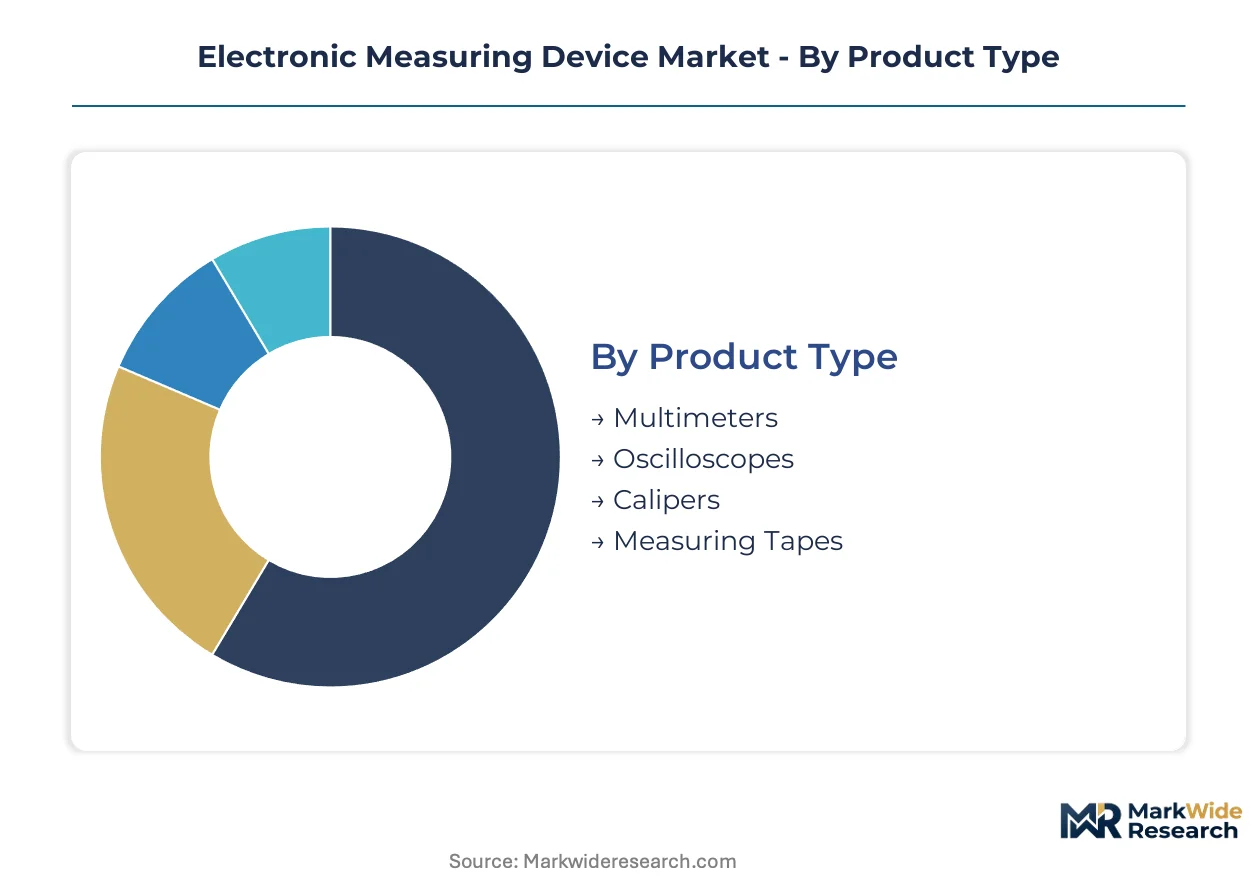
Electronic measuring device segmentation reveals divergent margin structures across product architectures, with semiconductor-grade instrumentation commanding premium pricing while field-service tools compete on procurement efficiency. Technology choices increasingly determine total cost of ownership as wireless-enabled units shift revenue models toward subscription analytics.
Product Type:
Margin pools concentrate in high-precision laboratory instruments where calibration service contracts extend customer lifetime value beyond hardware margins.
- Multimeters:Digital multimeters with true-RMS capability dominate industrial maintenance workflows, displacing analog interfaces. Demand clusters in China's factory automation corridors where IEC 61010-1 safety compliance is mandatory for grid-connected equipment.
- Oscilloscopes:Mixed-signal architectures with multi-channel acquisition serve power electronics validation in German automotive testing clusters. High-bandwidth units for aerospace protocols sustain technology premiums despite compressed hardware refresh cycles.
- Calipers:Digital micrometer-resolution units with data output ports integrate into statistical process control systems. Japanese machine tool manufacturers specify IP54 ingress protection for shop-floor durability.
- Measuring Tapes:Laser-based distance measurement modules with Bluetooth data logging target construction sector productivity tracking. Battery life and drop resistance determine competitive positioning in field applications.
Oscilloscopes hold installed capacity in validation laboratories. Multimeters are rotating up the share rankings through industrial IoT deployment.
Technology:
Cost tier stratification separates deterministic analog architectures from software-defined platforms with embedded analytics capabilities.
- Analog:Legacy needle-display instruments persist in electrical training environments and explosive atmosphere zones where intrinsic safety requirements prohibit digital circuitry. Maintenance budgets in mature industrial facilities sustain residual demand.
- Digital:Microcontroller-based architectures with auto-ranging and data logging dominate commercial procurement. South Korean semiconductor fabs specify 6.5-digit resolution for precision voltage reference verification.
- Wireless:IEEE 802.11-enabled units stream measurement data to enterprise asset management platforms. FCC Part 15 certification timelines extend product development schedules by six to nine months.
- Bluetooth:Low-energy protocols support battery-powered field instruments with smartphone-based visualization. Industrial IoT deployments in Jiangsu and Guangdong provinces are expanding fastest.
Digital technology holds installed capacity across industrial maintenance. Bluetooth is gaining share fastest through connected instrument adoption.
End User:
Application-specific certification requirements fragment procurement patterns across sectors with divergent safety and accuracy mandates.
- Industrial:Process control instrumentation with 4-20mA output loops and HART protocol compatibility serves chemical and petrochemical facilities. EPA emissions monitoring regulations in the US mandate calibrated measurement chains.
- Construction:Ruggedized laser levels and total stations with millimeter-grade accuracy support building information modeling workflows. German engineering contractors specify DIN 18723 angular accuracy standards.
- Automotive:High-voltage isolation and CAN bus integration are required for electric vehicle battery pack testing. NHTSA safety validation protocols drive oscilloscope bandwidth specifications.
- Electronics:Semiconductor wafer probing stations demand sub-picofarad capacitance measurement resolution. Taiwan foundries drive vector network analyzer specification roadmaps.
Industrial end users hold installed capacity in maintenance tool fleets. Electronics is climbing the fastest through semiconductor fabrication expansion.
Measurement Type:
Volume concentration in dimensional measurement contrasts with value concentration in electrical quantities requiring traceable calibration chains.
- Length:Interferometric and encoder-based systems achieve nanometer resolution for semiconductor lithography alignment. Japanese machine tool builders specify JIS B 7440 linear scale accuracy grades.
- Weight:Strain gauge load cells with OIML R60 certification serve legal-for-trade applications in logistics and retail. SAMR metrology licensing in China constrains market access for uncertified suppliers.
- Voltage:Josephson junction primary standards and transfer standards maintain national measurement institute traceability. NIST and PTB calibration services anchor the value chain.
- Pressure:Piezoresistive and capacitive transducers cover ranges from vacuum to 100,000 psi for aerospace and oilfield applications. FAA validation protocols for pitot-static systems specify temperature compensation requirements.
Voltage measurement holds installed capacity in calibration laboratories. Pressure is expanding most quickly through aerospace electrification testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in precision instrumentation tilt toward net imports in emerging manufacturing economies while established fabrication hubs maintain technology leadership through specialized component exports. Currency volatility and logistics costs are reshaping procurement patterns across regional corridors.
United States
Aerospace validation protocols in California and Texas defense corridors sustain demand for high-bandwidth oscilloscope architectures. FAA certification requirements for pitot-static measurement chains constrain supplier qualification timelines. Boston-area research institutions anchor metrology R&D partnerships with semiconductor equipment vendors.
Germany
Automotive electrification testing in Baden-Württemberg and Bavaria drives multi-channel mixed-signal unit procurement. DIN 18723 angular accuracy standards govern construction sector laser level specifications. Stuttgart engineering contractors specify ruggedized total stations for building information modeling workflows.
China
Jiangsu and Guangdong province contract manufacturers consolidate vendor relationships around full-stack calibration service contracts. SAMR metrology licensing constrains market access for uncertified voltage measurement suppliers. Yangtze River Delta semiconductor fabs demand sub-nanometer precision in impedance characterization tools.
South Korea
Memory and logic foundries in Gyeonggi Province specify 6.5-digit resolution for precision voltage reference verification. MFDS medical device regulations shape biopotential amplifier validation requirements for diagnostic instrument exports. Seoul Capital Area industrial automation corridors mandate networked measurement infrastructure under IEC 61010-1 protocols.
Japan
Machine tool builders in Aichi and Kanagawa prefectures specify JIS B 7440 linear scale accuracy grades for encoder-based dimensional systems. METI industrial policy incentivizes domestic production of ADC and FPGA components for instrument OEMs. Osaka-area electronics manufacturers drive digital micrometer adoption with IP54 ingress protection requirements.
Electronic Measuring Device Market Competitive Landscape
Concentration sits with diversified instrumentation conglomerates that span laboratory, field-service, and industrial automation segments through branded product portfolios. The vendor base separates into three strategic archetypes: premium calibration laboratory specialists, cost-optimized field-service suppliers, and full-stack solution providers bundling hardware with captive metrology services. Dominant competitive moves include geographic expansion into India industrial corridors under PLI scheme incentives and technology licensing partnerships for software-defined radio architectures.
Among diversified technology conglomerates, Keysight Technologies and Tektronix exemplify premium-tier positioning through deep R&D partnerships with semiconductor foundries. Rohde & Schwarz occupies a position within the European specialist tier, anchoring RF and microwave measurement expertise that constrains competitive entry in vector network analysis segments.
| Leading Market Players |
|---|
| Keysight Technologies |
| Tektronix |
| Fortive |
| Rohde & Schwarz |
| Teledyne LeCroy |
| National Instruments |
| Fluke Corporation |
| Yokogawa Electric Corporation |
| AMETEK |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day lead times for precision ADC and FPGA components from Taiwanese and Japanese semiconductor vendors concentrate pricing power with upstream suppliers, compressing margins for instrument OEMs while amplifying procurement risk for field-service tier buyers lacking volume scale.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on calibration certification grade and after-sales service bundling, with ISO 17025-accredited laboratory instruments commanding substantial premiums over uncertified field units. Pricing pressure stems from REACH substance restrictions forcing material redesigns in probe assemblies. Contract manufacturers in Jiangsu and Guangdong provinces exhibit highest price sensitivity, while aerospace validation labs show lowest sensitivity due to FAA certification lock-in.
Supply Chain Analysis
Inventory cycles of ninety to one hundred twenty days for specialized voltage reference components expose instrument manufacturers to allocation risk during fab capacity constraints. Component supply concentrates in Taiwan, South Korea, and Japan. Production draws from precision resistors, Josephson junction arrays, and ceramic substrate materials. Single-source vulnerability sits with 6.5-digit ADC suppliers. Distribution runs through authorized distributor networks with captive metrology laboratories capturing service-attached revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication capex cycles position this market for cyclical recovery as Taiwan and South Korean foundry expansions renew demand for sub-nanometer characterization tools.
For Market Incumbents: Fortify calibration service moats by acquiring regional laboratories in India industrial corridors under PLI scheme incentives. Deepen backward integration into FPGA component supply through partnerships with METI-subsidized Japanese semiconductor vendors to offset single-source exposure from Taiwanese suppliers.
For New Entrants and Emerging Players: IEC 61010-1 safety certification fast-tracks market access for Bluetooth-enabled multimeters targeting China's factory automation corridors. White-space concentrates in cloud-native analytics platforms unbundling hardware from subscription revenue. Pursue partnership routes with Jiangsu electronics contract manufacturers consolidating vendor relationships around full-stack service contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor equipment cyclical play because foundry capex intensity correlates directly with metrology tool refresh cycles. Target acquisition archetype: software-defined radio platform specialists with aerospace validation lab relationships. Watch Gyeonggi Province memory fab utilization rates as inflection signal for precision voltage reference demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Captures recurring service revenue from electronics contract manufacturers in Yangtze River Delta clusters. |
| Software-Defined Radio Platform Launch | Compresses hardware refresh intervals while expanding subscription licensing with aerospace validation labs. |
| India PLI Corridor Partnership | Positions for localized procurement from electronics manufacturing services attracted by scheme incentives. |
| Backward Integration into ADC Supply | Reduces allocation risk from concentrated Taiwanese and Japanese semiconductor vendors. |
| Cloud-Native Analytics Development | Enables predictive maintenance models that unbundle hardware margins from recurring software revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC standards documentation, SAMR metrology licensing records, and semiconductor equipment vendor SEC filings. Primary interviews engaged calibration laboratory directors, OEM procurement managers at contract manufacturers, and aftermarket service heads at industrial distributors. Secondary validation drew from customs trade data, foundry capex disclosures, and EPA emissions monitoring regulations. Bottom-up segment sizing triangulates against top-down macroeconomic anchors.
Segmentation dimensions modeled span product type, technology architecture, end-user sector, and measurement quantity across the projection horizon. CAGRs derive from elasticity-adjusted demand curves fitted to historical procurement patterns. Industry-specific forecast inputs include Taiwan Semiconductor Industry Association fab utilization indices and German automotive electrification testing cluster investment pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor fabrication complexity growth and stable IEC 61010 regulatory frameworks; material deviation would warrant model refresh. Revision becomes warranted when Gyeonggi Province memory fab utilization or Jiangsu contract manufacturer consolidation rates cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Reverberation Chambers Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Flow Meter Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market