
 Multi-Function Display Market | 2026-2036
Multi-Function Display Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Function Display Market Outlook
The gap between aerospace-grade multi-function displays and consumer-grade panels is expanding in unit cost, testing rigor, and supply chain qualification. Collins Aerospace leverages vertical integration across glass cockpit architectures to sustain program margins on military contracts. Garmin Ltd anchors the general aviation retrofit segment with certified portable and panel-mount displays. Thales Group competes on head-down and head-up display integration for fighter and transport platforms.
A multi-function display integrates graphical processing, video routing, and sensor fusion into a single panel, typically operating across temperature extremes from minus 40 to plus 70 degrees Celsius with sunlight-readable luminance exceeding 1000 cd/m² for cockpit applications. Its primary purpose is consolidating flight, navigation, engine, and mission data to reduce pilot workload and panel clutter. LCD technology dominates current aerospace and industrial installations due to proven reliability and established supply chains, while OLED panels are penetrating medical imaging and high-end automotive clusters where contrast ratio and response time command priority. Embedded systems integration captures the highest value per unit by combining computing, graphics generation, and display rendering in sealed line-replaceable units.
FAA airworthiness standards and EASA CS-25 certification requirements govern hardware and software development for civil aviation MFDs, while MIL-STD-810 and MIL-STD-461 shape environmental and electromagnetic compatibility testing for defense applications. The EU AI Act and emerging machine-learning interface standards will affect next-generation displays incorporating predictive alerting and automated decision support. Stakeholders must monitor how software-defined display architectures alter hardware refresh cycles and aftermarket service models.
Market Dynamics
The Multi-Function Display Market is being fundamentally restructured by software-defined display architectures that decouple hardware refresh cycles from software certification timelines, compressing development schedules while elevating cybersecurity and DO-178C compliance burdens for suppliers.
Growth Catalysts
- FAA NextGen mandates:Modernized cockpit requirements under NextGen air traffic management are accelerating fleet retrofits with certified MFD units across narrow-body and regional aircraft.
- Defense cockpit modernization:Military upgrade cycles in the United States are expanding procurement of ruggedized MFDs for fighter, transport, and rotary-wing platforms under fixed-wing and rotary-wing avionics programs.
- OLED luminance breakthroughs:Sunlight-readable OLED panels exceeding 1000 cd/m² are penetrating high-contrast applications where response time and black-level performance command specification priority.
Market Restraints
- Indium-tin-oxide supply concentration:Transparent conductor materials for aerospace-grade LCDs face input cost volatility from concentrated East Asian refining capacity.
- DO-178C certification friction:FAA and EASA software standards impose 18-36 month validation timelines that lock development capital and deter new market entrants.
- Projection display substitution:Head-up display systems using waveguide optics are capturing mission-critical flight data presentation in next-generation combat aircraft cockpits.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme and domestic procurement preferences are creating captive demand for locally assembled avionics displays under offset obligations.
- Predictive alerting convergence:Machine-learning interface standards under the EU AI Act are enabling automated decision-support overlays that fuse sensor data with pilot cognitive load management.
- Aftermarket channel digitization:Direct-to-operator spare parts platforms are disintermediating traditional distribution for line-replaceable MFD units in general aviation retrofit segments.
Industry Challenges
- DO-178C software engineer scarcity:Qualified verification specialists capable of artifact generation for Level A criticality systems command premium compensation and extended recruitment cycles.
- Legacy ARINC 429 integration complexity:Newer display architectures must maintain backward compatibility with analog-era databus protocols prevalent in aging commercial and military fleets.
- Hardware-software co-certification timelines:Synchronized validation of sealed line-replaceable units with evolving operating system patches creates recurrent compliance exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Function Display Market |
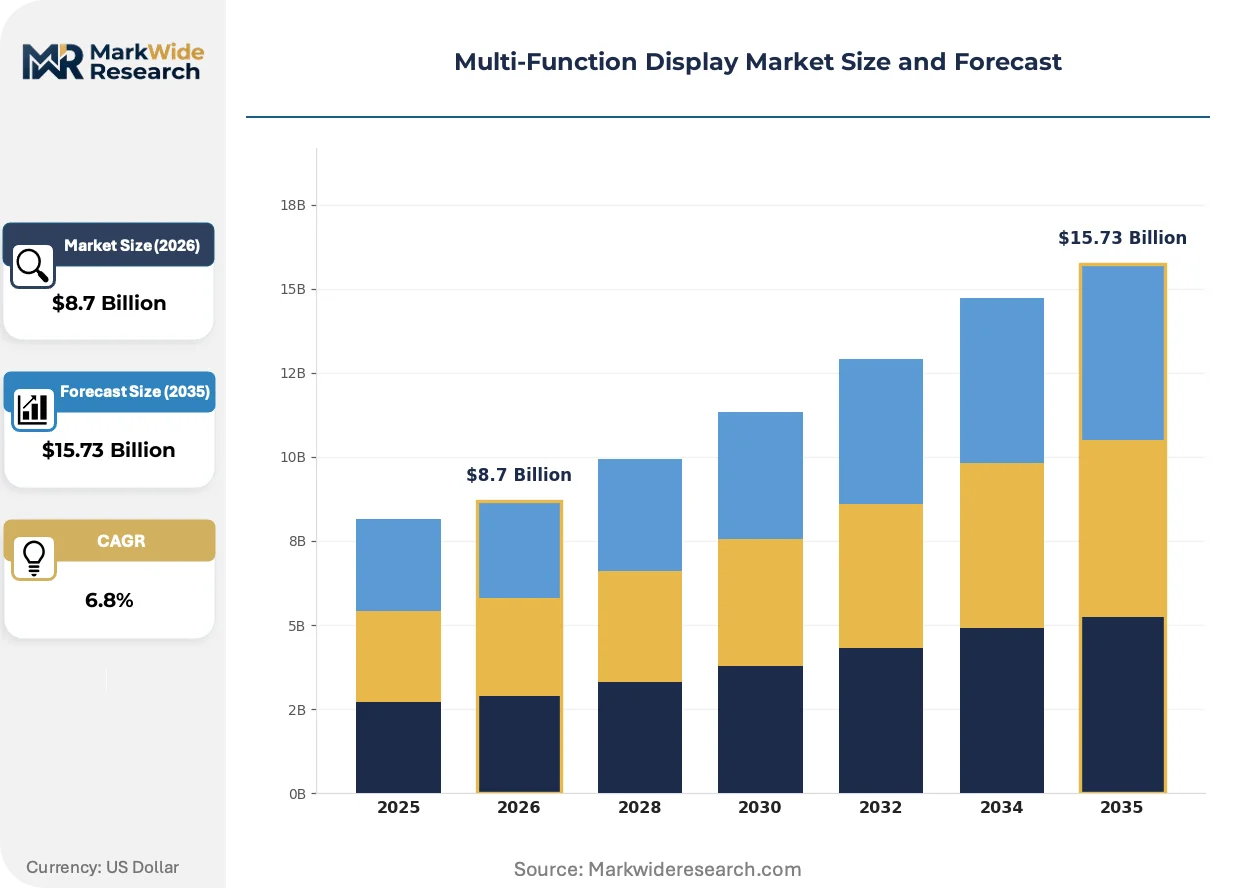
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, QLED Application: Consumer Electronics, Automotive Displays, Industrial Automation, Medical Imaging End User: Households, Commercial Establishments, Healthcare Providers, Educational Institutions Integration Level: Standalone Displays, Embedded Systems, Interactive Displays, Networked Solutions |
| Companies Covered | Elbit Systems, Thales Group, Collins Aerospace, L3Harris, Barco NV, Honeywell Aerospace, BAE Systems, Aspen Avionics, Garmin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Function Display Market Strategic Shifts
Active matrix liquid crystal technology is yielding functional territory to solid-state alternatives while regulatory frameworks accelerate software-centric certification models. Three developments are compressing traditional competitive advantages.
Active-matrix OLED is consolidating high-contrast imaging for medical and premium automotive clusters where grayscale fidelity and motion clarity exceed LCD capability. Cardiology imaging suites and luxury electric vehicle manufacturers are specifying these panels for diagnostic and instrument cluster applications. The technology is consolidating supplier margins in segments where contrast ratio specifications disqualify conventional backlight architectures.
The EU AI Act's risk-classification framework for machine-learning interfaces is mandating explainability standards for predictive alerting systems integrated into next-generation displays. Avionics developers must now document algorithmic decision pathways for automated decision-support functions. Transport-category aircraft and high-end business jet segments are responding by segregating certified baseline software from updatable overlay layers.
Operators are unbundling aftermarket service contracts from initial hardware procurement, compressing supplier recurring revenue streams. Airlines and defense procurement agencies are negotiating discrete software maintenance agreements separate from line-replaceable unit warranties. This pattern is most visible in the United States where military sustainment contracts and commercial fleet management programs are driving the separation.
Multi-Function Display Market Segmentation
Multi-function display procurement splits sharply between standalone panels for retrofit markets and embedded systems for new platform integration. Understanding where computing, graphics generation, and display rendering consolidate versus remain distributed shapes supplier strategy and margin capture across aerospace, automotive, and industrial verticals.
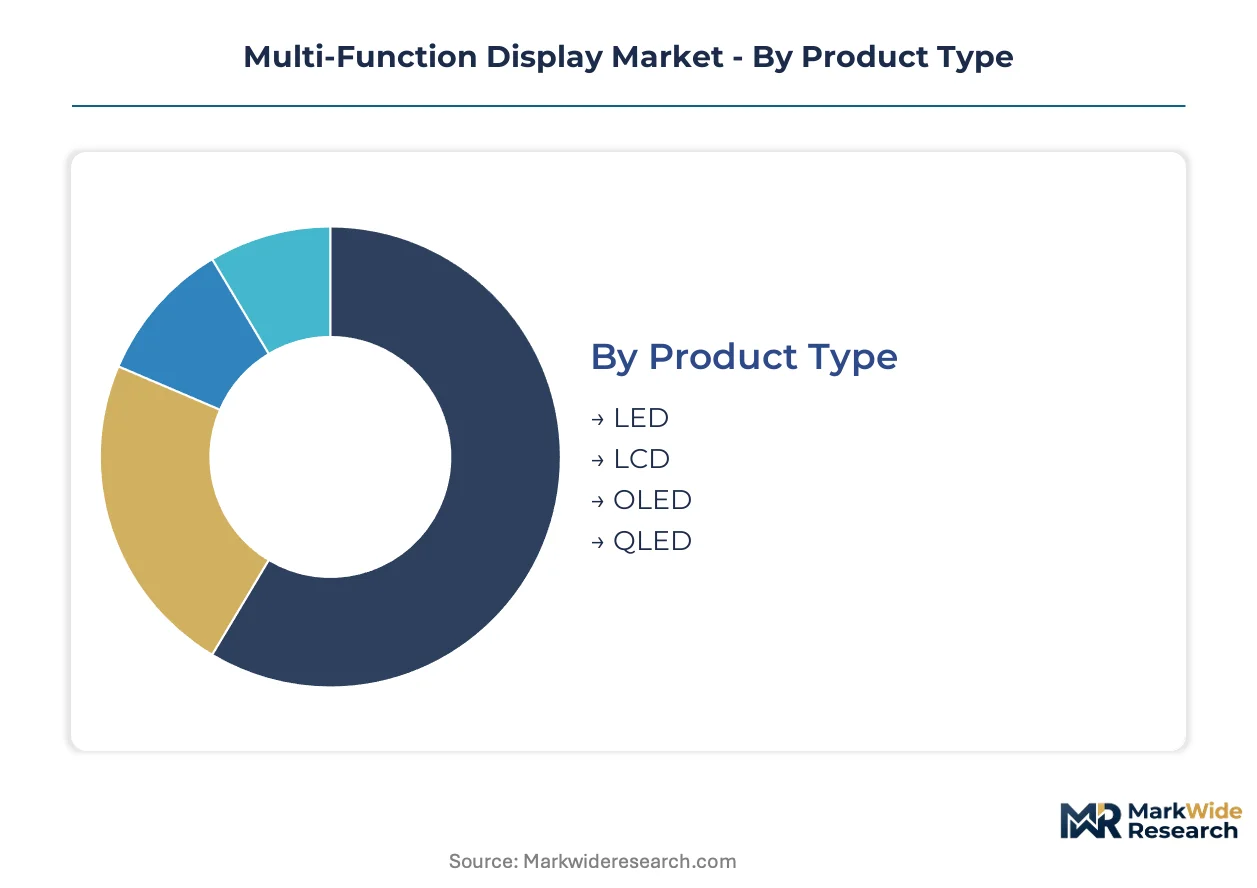
Product Type:
Integration depth varies substantially across display technologies, with some segments dominating sealed line-replaceable units while others serve upgrade and replacement channels.
- LED:Direct-lit and edge-lit LED backlights power the majority of aerospace-grade LCD modules, delivering sunlight-readable luminance exceeding 1000 cd/m² across temperature extremes from minus 40 to plus 70 degrees Celsius. Defense avionics programs in the United States specify LED-backlit panels for cockpit modernization under fixed-wing and rotary-wing upgrade contracts, though indium-tin-oxide supply concentration from East Asian refining capacity creates input cost volatility.
- LCD:Active matrix liquid crystal technology retains functional dominance in aerospace and industrial installations where proven reliability and established supply chains outweigh contrast limitations. FAA-certified installations and EASA CS-25 compliance frameworks favor LCD architectures with decades of airworthiness documentation, even as OLED panels penetrate adjacent segments.
- OLED:Solid-state emissive technology is consolidating high-contrast imaging for medical and premium automotive clusters where grayscale fidelity and response time command specification priority.
- QLED:Quantum dot-enhanced panels serve consumer electronics and high-end automotive instrument clusters demanding expanded color gamut.
Volume placements concentrate in LCD; the faster expansion belongs to OLED.
Application:
End-use requirements fragment across certification intensity, with aerospace and medical applications demanding sealed embedded systems while automotive and consumer segments tolerate modular standalone configurations.
- Consumer Electronics:Smartphones, tablets, and personal computing devices drive massive unit volumes with rapid refresh cycles and minimal regulatory burden. Demand concentrates in East Asian manufacturing clusters where panel fabrication and final assembly co-locate, though consumer-grade specifications disqualify these units from aerospace or medical procurement.
- Automotive Displays:Instrument clusters, center-stack infotainment, and head-up display modules integrate multi-function capabilities with increasing software-defined architectures. OEMs in Germany and Japan specify panels with automotive-grade temperature cycling and electromagnetic compatibility under ECE regulations and JIS standards.
- Industrial Automation:Human-machine interfaces for manufacturing equipment and process control prioritize durability and long-term availability over resolution metrics. Machine builders in the United States and Germany specify panels with extended temperature ranges and resistive touch layers for factory floor deployment.
- Medical Imaging:Diagnostic radiology, surgical navigation, and patient monitoring require grayscale fidelity and DICOM calibration. FDA 510(k) and EMA MDR frameworks govern display performance for primary diagnosis, creating certification barriers that favor established suppliers with quality management systems.
Automotive applications are expanding most quickly; industrial automation retains the largest installed base.
End User:
Procurement authority and technical specification control vary dramatically across customer types, with institutional buyers demanding embedded integration and consumer segments driving standalone replacement markets.
- Households:Individual consumers purchase displays through retail and e-commerce channels with minimal technical specification involvement. Replacement cycles accelerate as software-defined features render hardware obsolete faster than panel failure.
- Commercial Establishments:Corporate procurement departments specify displays for digital signage, conference systems, and control rooms with three-to-five-year service life expectations. Leasing and managed service models are compressing upfront hardware margins in favor of recurring software and maintenance revenue.
- Healthcare Providers:Hospital systems and imaging centers procure under strict regulatory frameworks with total cost of ownership calculations spanning decade-long depreciation schedules. FDA and EMA device regulations mandate traceability and change control that favor embedded systems with sealed software stacks.
- Educational Institutions:K-12 and university procurement prioritizes durability and theft resistance over performance specifications, with bulk purchasing consortia extracting volume discounts from suppliers.
Healthcare providers command the highest unit values; commercial establishments are gaining share fastest.
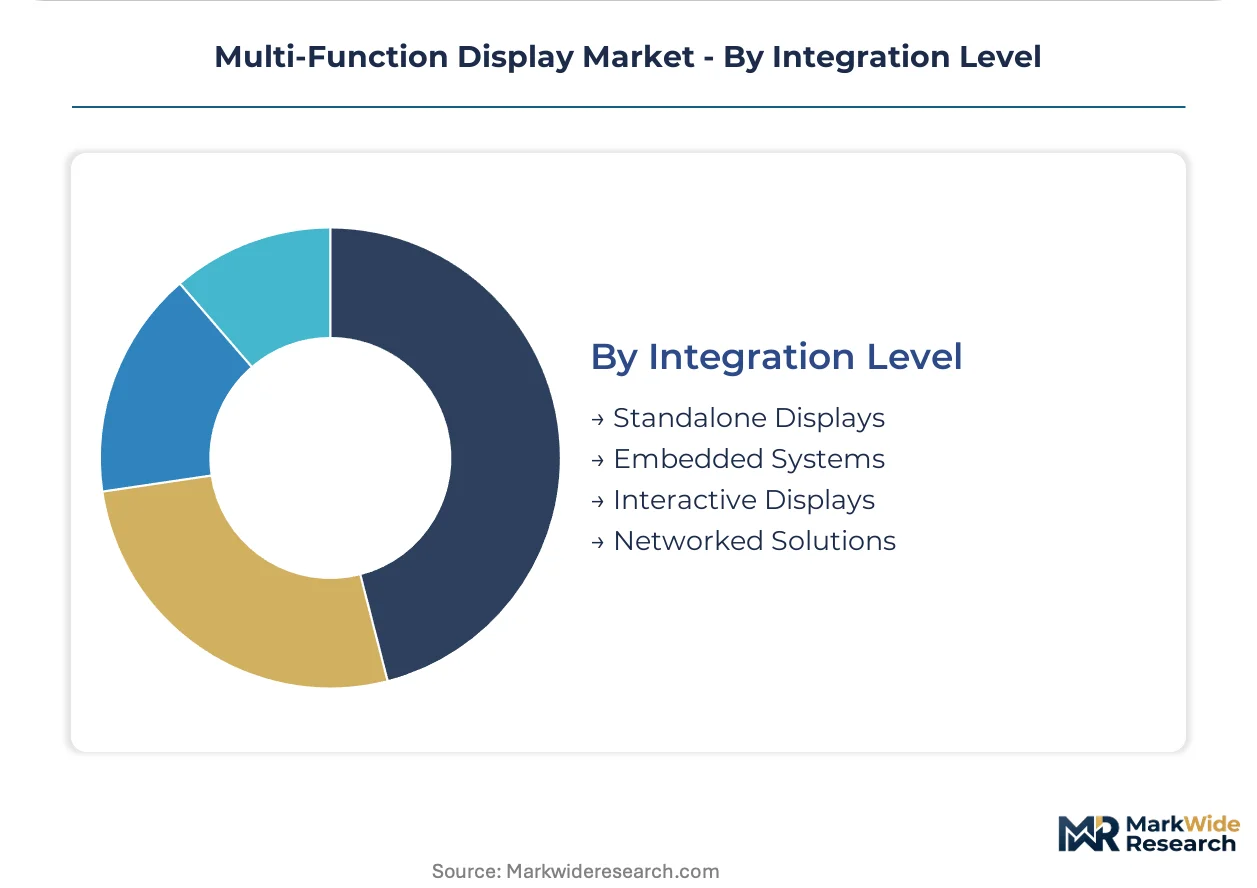
Integration Level:
The architecture of computing and display integration determines certification pathways, aftermarket service models, and supplier margin sustainability across customer segments.
- Standalone Displays:Discrete panels accepting external video signals serve retrofit markets and applications where computing resources remain physically separated. General aviation operators in the United States specify portable and panel-mount units from Garmin for cockpit upgrades without airframe modification.
- Embedded Systems:Sealed line-replaceable units combining graphics generation, video routing, and sensor fusion capture the highest value per unit in aerospace and defense applications. MIL-STD-810 environmental testing and DO-178C software certification impose eighteen-to-thirty-six-month validation timelines that lock development capital and deter new entrants.
- Interactive Displays:Touch-enabled panels with integrated processing serve kiosks, point-of-sale, and collaborative workspace applications where user input replaces peripheral devices.
- Networked Solutions:IP-connected displays with centralized content management and over-the-air update capability are penetrating digital signage and enterprise communication deployments.
Embedded systems dominate aerospace procurement; networked solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Seattle anchors aerospace display engineering with Boeing's commercial and defense avionics procurement driving supplier clustering across Puget Sound. Military upgrade cycles and FAA NextGen mandates concentrate demand in specific national markets with established certification infrastructure and fleet renewal timelines.
United States
Defense avionics programs under fixed-wing and rotary-wing modernization contracts expand procurement of ruggedized MFD units for cockpit upgrades. FAA certification requirements and DO-178C software standards tighten compliance thresholds for civil and military display systems. The Greater Seattle and Dallas-Fort Worth corridors concentrate supplier engineering and integration facilities serving Boeing and Lockheed Martin programs.
France
Thales Group's head-down and head-up display integration for fighter and transport platforms sustains domestic procurement for Dassault Aviation and Airbus Defence. EASA CS-25 certification frameworks govern hardware and software development for civil aviation MFDs alongside military specifications. The Toulouse aerospace cluster hosts display integration facilities for A350 and A400M platforms with embedded systems manufacturing.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify multi-function displays for instrument clusters and center-stack modules under ECE regulations. Industrial automation demand from machine builders prioritizes durability and long-term availability for factory floor deployment. The Munich-Stuttgart corridor concentrates display module assembly for premium automotive and medical imaging applications.
Japan
METI industrial policy supports domestic display panel fabrication for aerospace and automotive qualification under JIS standards. Precision manufacturing clusters in Nagoya and Osaka supply LCD modules for industrial automation and medical imaging with extended temperature specifications. Automotive OEMs integrate multi-function displays for next-generation electric vehicle instrument clusters.
India
The PLI scheme and domestic procurement preferences under offset obligations create captive demand for locally assembled avionics displays. Defense indigenization programs target cockpit modernization for indigenous fighter and helicopter platforms with ruggedized MFD specifications. The Bangalore-Hyderabad corridor concentrates electronics manufacturing services for aerospace subsystem integration.
Multi-Function Display Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity and integration depth. The vendor base stratifies between sealed embedded systems suppliers capturing aerospace-grade value and standalone panel manufacturers serving retrofit markets. Three archetypes dominate: vertically integrated avionics primes, specialized display module fabricators, and software-defined architecture providers. Consolidation pressure operates through program-specific teaming arrangements and captive supply agreements rather than horizontal mergers.
Within the defense avionics tier, Elbit Systems, Thales Group, and Collins Aerospace exemplify the vertically integrated prime archetype. These entities occupy positions spanning glass cockpit architectures with combined hardware-software certification capabilities. Garmin Ltd anchors the general aviation retrofit segment with certified portable and panel-mount displays. L3Harris and BAE Systems sit within the mission systems integration tier where sensor fusion and display rendering consolidate in sealed line-replaceable units. Barco NV and Honeywell Aerospace represent the industrial-aerospace crossover archetype with medical imaging and cockpit display qualifications.
| Leading Market Players |
|---|
| Elbit Systems |
| Thales Group |
| Collins Aerospace |
| L3Harris |
| Barco NV |
| Honeywell Aerospace |
| BAE Systems |
| Aspen Avionics |
| Garmin Ltd |
| Others |
Value Chain & Pricing Dynamics
Defense procurement agencies and commercial airline fleet operators concentrate purchasing authority for multi-function displays, locking contract structures around certified embedded systems with eighteen-to-thirty-six-month validation timelines that elevate price floors and deter spot-market competition.
Pricing Analysis
Value-based pricing anchors on mission-critical uptime and airworthiness certification, with FAA DO-178C Level A software validation and MIL-STD-810 environmental testing commanding substantial premiums over uncertified alternatives. Price differentiation separates sealed line-replaceable units from standalone retrofit panels, with aerospace-grade indium-tin-oxide coated substrates and ruggedized thermal management driving cost stratification. Cost compression in consumer-adjacent segments intensifies as automotive OLED specifications migrate downward, pressuring mid-tier suppliers without captive aerospace certification capabilities. General aviation retrofit operators exhibit highest price sensitivity, while defense primes and transport-category airlines accept extended payback periods for embedded integration.
Supply Chain Analysis
India's PLI scheme and domestic procurement preferences under offset obligations are reshaping sourcing patterns for avionics subsystem assembly, compelling tier-one suppliers to establish captive manufacturing in the Bangalore-Hyderabad corridor. Panel fabrication concentrates in Japan and South Korea under METI industrial policy and precision manufacturing clusters, with indium-tin-oxide refining capacity tethered to East Asian chemical processing infrastructure. Single-source vulnerability in transparent conductor materials exposes aerospace-grade LCD supply to input cost volatility from concentrated refining capacity. Distribution runs through program-specific teaming arrangements with primes like Collins Aerospace and Thales Group rather than open-channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into glass substrate fabrication and software certification capabilities is accelerating as primes seek to capture margin pools previously ceded to specialized component suppliers.
For Market Incumbents: Cement program-specific teaming arrangements with defense procurement agencies before India's PLI scheme matures domestic competition, while deepening captive supply of indium-tin-oxide coated substrates to offset East Asian refining concentration. Prioritize DO-178C verification specialist retention against scarce talent pools threatening development timelines. For New Entrants and Emerging Players: Launch via direct-to-operator spare parts platforms in general aviation retrofit segments where traditional distribution layers remain vulnerable to disintermediation. Target aftermarket digitization white space with certified portable units for Garmin-dominated price tiers, leveraging software-defined architectures to compress hardware refresh cycles without full airframe recertification. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with dual aerospace-medical imaging qualifications and established FDA 510(k) or EASA CS-25 quality management systems. Monitor EU AI Act machine-learning interface standardization as inflection signal for predictive alerting overlay acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Investment | Decouples hardware refresh from DO-178C recertification timelines for Collins Aerospace and Thales programs. |
| Domestic Manufacturing Footprint Expansion | Captures India's PLI scheme incentives for avionics display assembly under offset obligations. |
| Backward Integration into ITO Substrates | Reduces exposure to East Asian refining concentration for aerospace-grade transparent conductors. |
| Predictive Alerting Capability Acquisition | Positions for EU AI Act explainability mandates in automated decision-support overlays. |
| Aftermarket Channel Digitization | Disintermediates traditional distribution for line-replaceable units in Garmin-served retrofit segments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving avionics program managers, DO-178C verification specialists, airline fleet procurement directors, and defense offset compliance officers. FAA certification databases, EASA CS-25 type certificate records, and MIL-STD-810 test documentation supplemented customs import-export data for display module trade flows. Bottom-up unit economics for embedded systems and standalone panels were triangulated against top-down aerospace and defense procurement budget allocations.
Segment-level modeling tracked product type across LED, LCD, OLED, and QLED technologies; application across aerospace, automotive, industrial automation, and medical imaging; and integration level across standalone, embedded, interactive, and networked configurations. Deployment model, certification tier, and regional procurement authority shaped the analytical framework across the projection horizon. CAGRs derived from installed base replacement cycles, fleet renewal timelines, and defense modernization program phasing without year-specific anchoring. Indium-tin-oxide supply concentration and DO-178C engineer scarcity served as industry-specific demand and supply-side constraints.
Regulatory timeline acceleration, defense budget reallocation, and OLED luminance breakthroughs beyond aerospace qualification thresholds are the dominant revision risks for multi-function display demand projections. Forecasts reflect documented assumptions regarding certification pathway durations and procurement contract structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
IGZO Display Market
Display Technologies
OLED Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Global Transparent Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Smartphone Display Market
Display Technologies
Smart Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Commercial Display Market
Display Technologies
Flexible OLED Market
Display Technologies
Digital Holographic Display Market
Display Technologies
4K Technology Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Global Wearable Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Touch Screen Display Market