
 Residential Furnaces Market | 2026-2036
Residential Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Furnaces Market Analysis
High-efficiency AFUE ratings above 95% is bifurcating the residential furnaces landscape into premium replacement and entry-level new-construction tiers. Carrier Global Corporation leverages its Infinity modulating systems to dominate the high-end retrofit channel across North America. Rheem Manufacturing Company anchors its position through captive distribution and contractor loyalty programs in the replacement segment. Daikin Industries, Ltd. competes on variable-speed heat exchanger technology imported from its Osaka R&D center.
A residential furnace is a forced-air or hydronic heating appliance that combusts natural gas, propane, oil, or uses electric resistance to generate thermal energy, with efficiency measured by Annual Fuel Utilization Efficiency percentage and output capacity rated in BTUs per hour, designed to distribute warmed air or water throughout single-family and multi-family dwellings. Natural gas furnaces occupy the largest installed base due to pipeline infrastructure density and lower therm costs versus electric resistance heating. Modulating heat exchanger types represent the fastest-growing configuration as builders and homeowners prioritize steady temperature control and reduced cycling losses over single-stage equipment. Smart thermostat pairings are emerging as a margin pool where equipment manufacturers bundle connected controls to capture recurring service revenue.
The US Department of Energy sets federal minimum efficiency standards under EPCA authority, while the EPA regulates combustion emissions through its wood heater and air quality programs, and state-level stretch codes in California and Washington push AFUE requirements beyond federal floors. Local utility rebate programs administered by entities such as Xcel Energy and Duke Energy condition incentive eligibility on ENERGY STAR certification, steering consumer selection toward qualified models. Stakeholders must monitor how electrification mandates in new construction jurisdictions reshape fuel-type demand and whether gas infrastructure moratoriums expand beyond current municipal boundaries.
Market Dynamics
The US Department of Energy's escalating AFUE minimums are compressing replacement cycles and forcing manufacturers to abandon single-stage architectures in favor of modulating systems, fundamentally restructuring how equipment is specified across new construction and retrofit channels.
Growth Catalysts
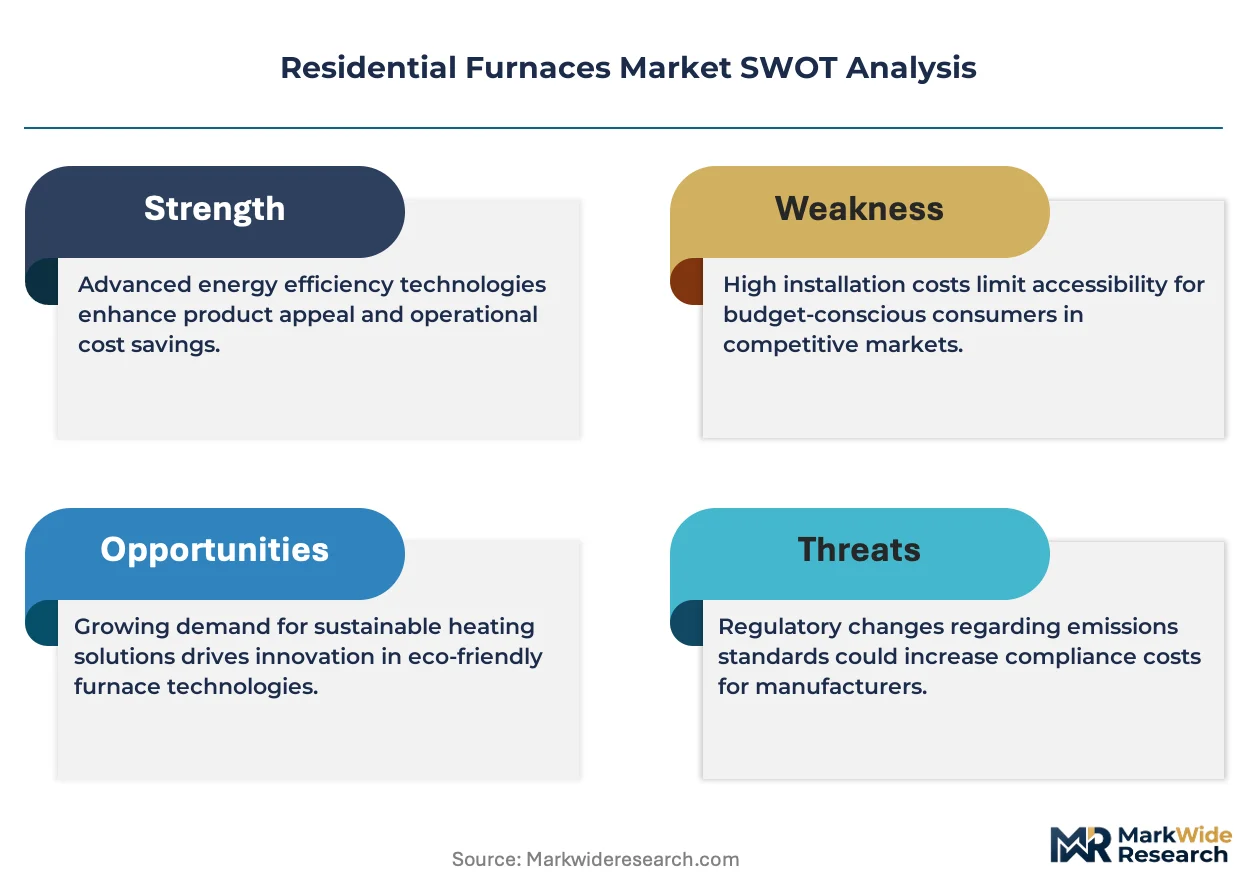
- Stretch code proliferation:California and Washington state-level mandates are pushing AFUE floors beyond federal standards, compelling equipment turnover in coastal housing markets.
- Sun Belt migration:Population inflows into Texas, Florida, and Arizona are accelerating new housing starts and attendant HVAC infrastructure deployment.
- Variable-speed heat exchangers:This technology category is capturing specification preference as builders prioritize thermal consistency and reduced cycling losses.
Market Restraints
- Copper and steel input volatility:Heat exchanger fabrication costs fluctuate with commodity metal pricing, compressing margin stability for OEMs.
- Licensed installer scarcity:The certified technician pipeline constrains replacement velocity in markets where electrification retrofits compete for labor.
- Electric heat pump substitution:Air-source and geothermal systems are capturing share in jurisdictions with gas infrastructure moratoriums.
Strategic Opportunities
- Smart thermostat bundling:Equipment manufacturers are capturing recurring service revenue by pairing connected controls with furnace sales.
- Utility rebate arbitrage:Xcel Energy and Duke Energy incentive programs condition eligibility on ENERGY STAR certification, steering consumer selection.
- Modulating system retrofits:The replacement segment offers white space for premium efficiency upgrades in aging single-family housing stock.
Industry Challenges
- Certification timeline compression:EPA combustion emissions testing and DOE efficiency verification are extending product launch windows.
- Legacy control integration:Variable-speed furnaces require proprietary thermostat protocols, complicating interoperability with third-party smart home systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Furnaces Market |
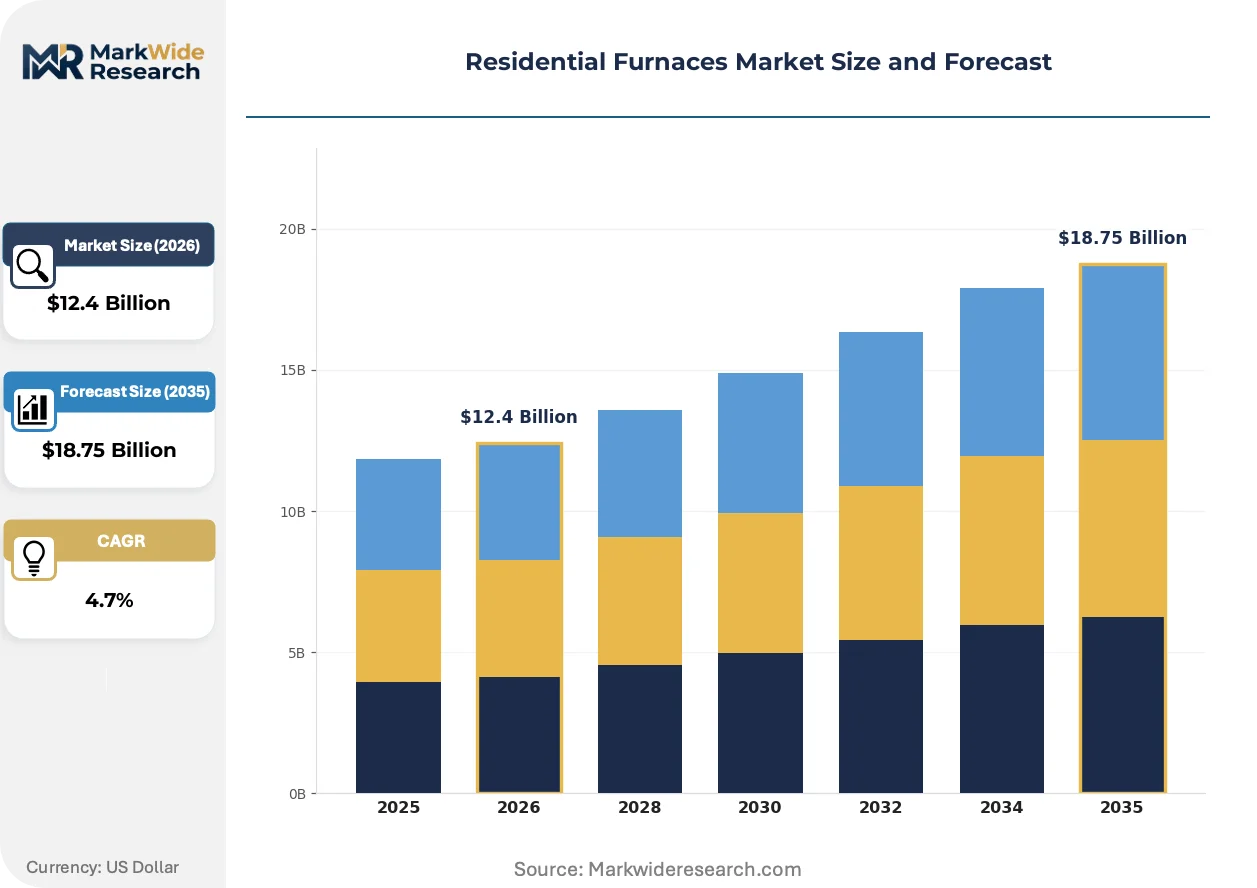
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Natural Gas, Propane, Electric, Oil Heat Exchanger Type: Single Stage, Two Stage, Modulating, Direct Vent Installation Type: Forced Air, Hydronic, Radiant, Wall-Mounted Thermostat Type: Smart, Programmable, Manual, Wireless |
| Companies Covered | Carrier Global Corporation, Lennox International Inc., Trane Technologies plc, Goodman Manufacturing, Rheem Manufacturing Company, Bryant Heating & Cooling Systems, Johnson Controls, Daikin Industries, Ltd., American Standard Heating & Air Conditioning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Furnaces Market Emerging Trajectories
Equipment architecture is converging around connectivity and modulation, with manufacturers racing to embed intelligence that captures aftermarket service revenue while regulatory pressure accelerates obsolescence of single-stage designs.
Condensing heat exchanger technology is miniaturizing secondary surface area into compact cabinet footprints without sacrificing latent heat recovery efficiency. Production homebuilders in the Sun Belt are specifying these reduced-form-factor units to preserve attic and closet space in smaller lot footprints. This dimensional compression is miniaturizing mechanical room requirements and enabling tighter HVAC integration with compact building envelopes.
The EPA's combustion emissions protocols are tightening particulate and carbon monoxide thresholds for fossil-fuel heating appliances. Equipment manufacturers are responding with sealed combustion designs and direct-vent configurations that isolate burner operation from indoor air. High-altitude installations in Rocky Mountain states face the steepest compliance burden as oxygen-derated combustion requires recalibrated fuel-air mixtures.
Homeowner specification behavior is fragmenting between new construction and replacement channels. Builders prioritize first-cost minimization and installation speed, while retrofit buyers emphasize operating cost reduction and comfort consistency. This bifurcation is forcing manufacturers to maintain dual product architectures—streamlined single-stage lines for tract housing and feature-rich modulating systems for the replacement segment—with channel-specific distribution strategies most visible in Texas and Florida markets.
Residential Furnaces Market Segmentation
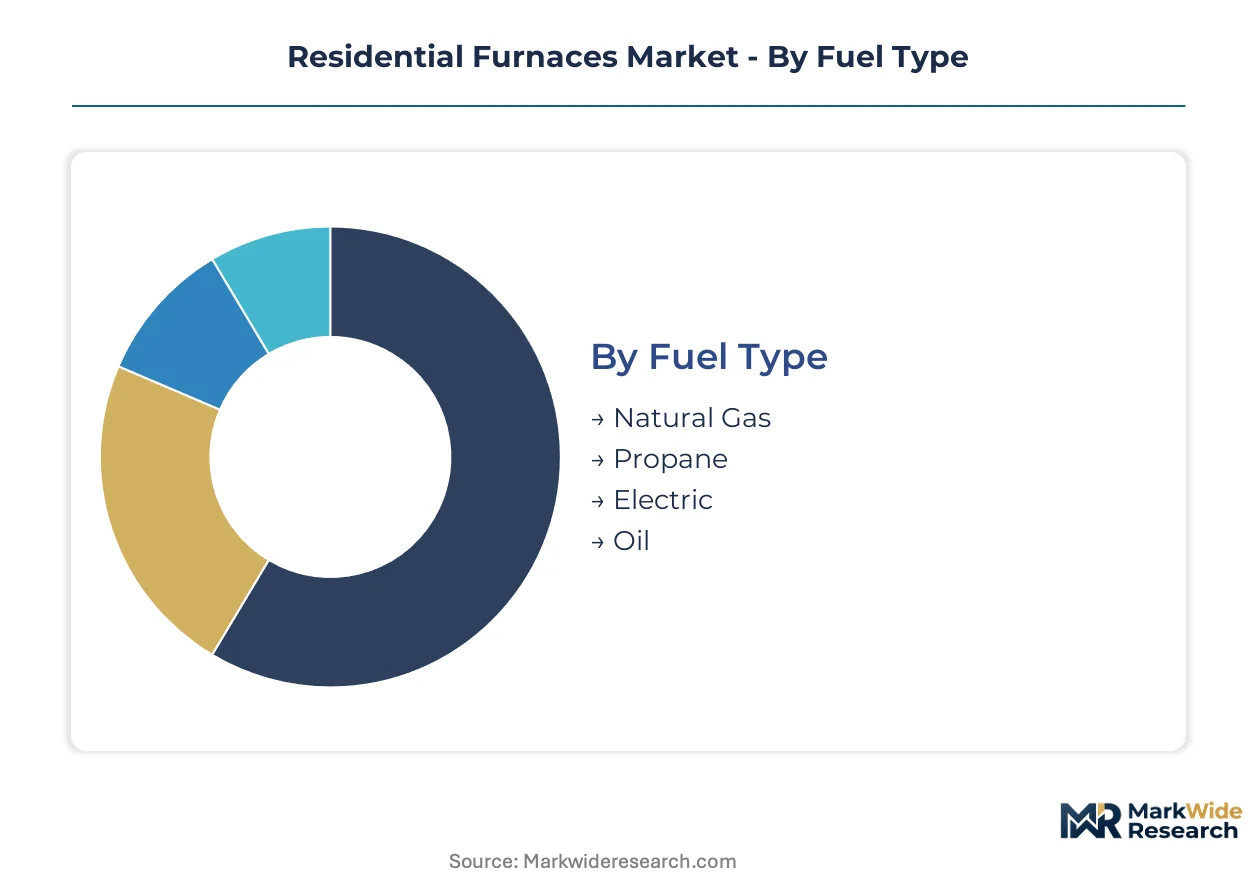
Residential furnace segmentation reveals how equipment specifications diverge between new construction and replacement channels. Builders prioritize first-cost minimization and installation speed, while retrofit buyers emphasize operating cost reduction and comfort consistency. Channel-specific demand patterns force manufacturers to maintain dual product architectures with differentiated distribution strategies.
Fuel Type:
Natural gas dominates the replacement channel through existing pipeline infrastructure, while electric resistance captures specification share in jurisdictions with gas infrastructure moratoriums. Propane and oil serve rural markets where pipeline density is insufficient.
- Natural Gas:Combusts pipeline-delivered methane through sealed combustion chambers with AFUE ratings typically ranging from 80% to 98.5%. Demand concentrates in the US Sun Belt states where population migration drives new housing starts and HVAC infrastructure buildout, though electrification mandates in California and Washington are compressing specification share in coastal markets.
- Electric:Converts electrical resistance into thermal energy through heating elements without combustion emissions or venting requirements. Electric furnaces are capturing specification preference in jurisdictions with gas infrastructure moratoriums, particularly in new construction segments where builders face electrification mandates.
- Propane:Liquefied petroleum gas combustion system requiring on-site storage tanks and periodic fuel delivery. Rural markets without natural gas pipeline access rely on propane as the primary fossil fuel alternative.
- Oil:Fuel oil combustion with higher BTU content per gallon but requiring more complex burner maintenance and fuel storage infrastructure. Northeastern US markets with legacy oil heating infrastructure maintain residual demand.
Natural gas dominates installed base. Electric is where expansion concentrates in electrification-mandated jurisdictions.
Heat Exchanger Type:
Modulating systems command premium pricing in the replacement channel while single-stage units minimize first cost for production homebuilders. Two-stage configurations bridge the gap with mid-tier positioning.
- Modulating:Variable-output heat exchanger adjusts flame intensity across a continuous range from 40% to 100% capacity, eliminating temperature swings and reducing cycling losses. The US Department of Energy's escalating AFUE minimums are compressing replacement cycles and forcing manufacturers to abandon single-stage architectures in favor of modulating systems.
- Single Stage:Fixed-output burner operates at full capacity whenever heating demand exceeds thermostat setpoint, creating temperature fluctuations and higher cycling frequency. Production homebuilders in Texas and Florida specify these units to minimize first cost in tract housing developments.
- Two Stage:Dual-output burner operates at reduced capacity during moderate heating loads and full capacity during peak demand periods. This configuration offers intermediate efficiency and comfort at moderate price points.
- Direct Vent:Sealed combustion system draws intake air from outside and exhausts combustion gases through a dedicated vent pipe, isolating burner operation from indoor air quality. The EPA's tightening particulate and carbon monoxide thresholds are accelerating specification of direct vent configurations.
Single-stage equipment retains volume leadership in new construction. Modulating systems are climbing the fastest in the replacement segment.
Installation Type:
Forced air systems align with North American ducted infrastructure standards, while hydronic configurations serve radiant floor applications and European-influenced building designs.
- Forced Air:Blower-driven distribution through sheet metal ductwork delivers heated air to conditioned spaces via floor, wall, or ceiling registers. This configuration represents the dominant installation type in US residential construction due to compatibility with central air conditioning integration.
- Hydronic:Water or glycol solution circulates through baseboard radiators, radiant floor tubing, or fan coil units to distribute thermal energy. High-end residential retrofits and custom home markets specify hydronic systems for superior thermal comfort and zoning flexibility.
- Radiant:Infrared heat emission from heated floors, walls, or ceiling panels warms surfaces and occupants directly rather than heating air. Luxury residential segments in cold climate zones prioritize radiant installations for draft-free comfort.
- Wall-Mounted:Compact unit installation on exterior walls eliminates floor space requirements and simplifies venting through direct exterior penetration. Space-constrained multifamily housing and accessory dwelling units drive specification of wall-mounted configurations.
Forced air captures the largest installed base. Hydronic is gaining share fastest in premium custom home segments.
Thermostat Type:
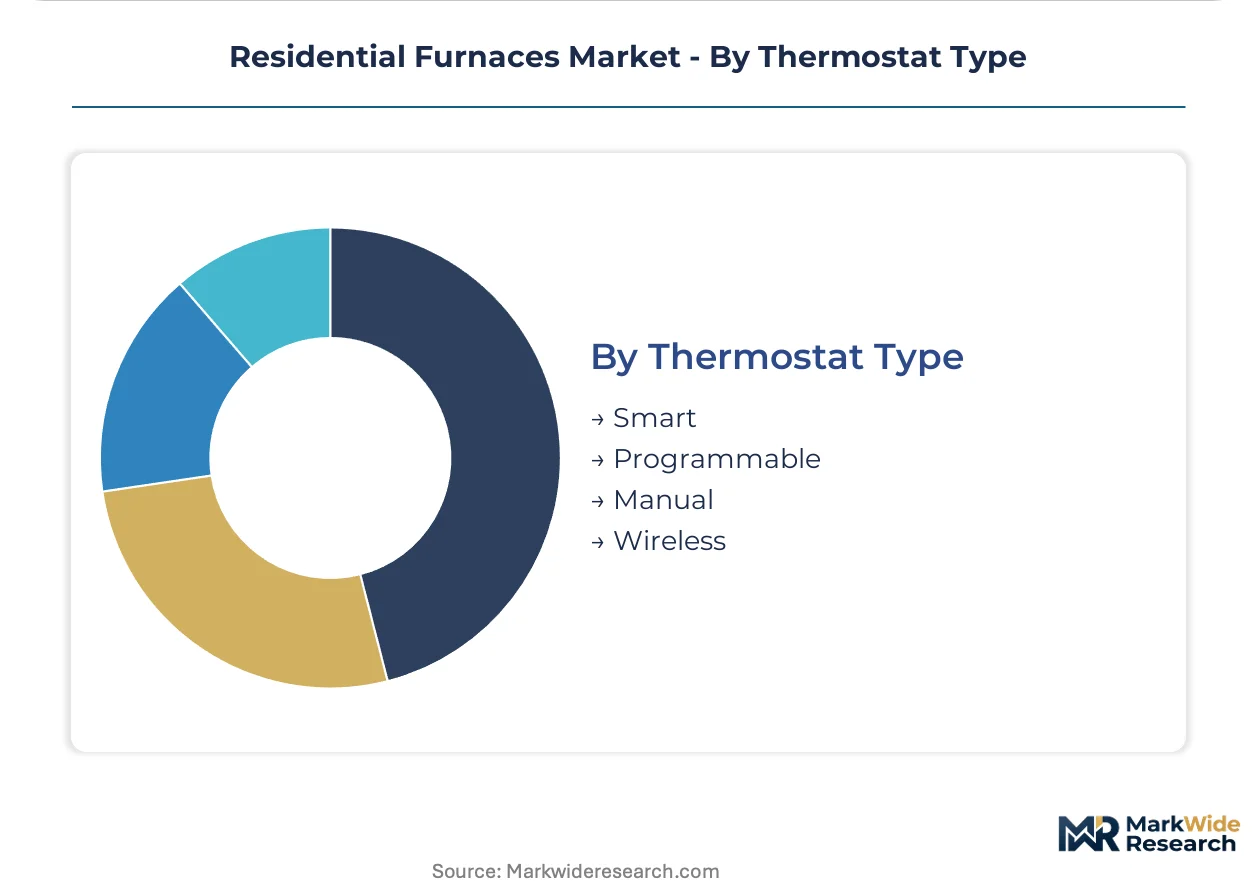
Smart thermostat pairings are emerging as a margin pool where equipment manufacturers bundle connected controls to capture recurring service revenue.
- Smart:WiFi-enabled control with machine learning algorithms, geofencing, remote access, and utility demand response integration. Equipment manufacturers are capturing recurring service revenue by pairing connected controls with furnace sales, particularly in the replacement channel.
- Programmable:Time-based temperature scheduling with multiple daily setpoints to reduce energy consumption during unoccupied periods. Utility rebate programs condition incentive eligibility on programmable or smart thermostat pairing.
- Manual:Basic temperature dial or digital display with single setpoint control and no scheduling capability. Entry-level new construction specifications prioritize manual thermostats to minimize first cost.
- Wireless:Battery-powered control communicating via RF or proprietary protocols to furnace-mounted receiver, eliminating hardwired control runs. Retrofit applications and historic home renovations specify wireless configurations to avoid invasive wiring.
Programmable thermostats dominate current installed base. Smart controls are where manufacturer margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Sun Belt migration corridors exhibit low price elasticity as housing starts outpace installer capacity, while replacement buyers in legacy heating markets show high sensitivity to first-cost differentials between single-stage and modulating equipment.
United States
Texas, Florida, and Arizona housing starts are accelerating HVAC infrastructure deployment as population migration strains mechanical contractor availability. The US Department of Energy's escalating AFUE minimums under EPCA authority are compressing replacement cycles nationwide. The Dallas-Fort Worth metroplex is seeing specification-grade furnace installations expand across production homebuilder developments.
Canada
Cold climate heating loads and natural gas pipeline density sustain demand for high-efficiency condensing furnaces in Ontario and Alberta residential construction. Natural Resources Canada's ENERGY STAR certification requirements condition federal rebate eligibility on minimum efficiency thresholds. The Greater Toronto Area is experiencing premium modulating system retrofits in aging suburban housing stock.
Germany
Building energy efficiency regulations under the Buildings Energy Act are accelerating heat pump substitution in new construction, though gas-fired condensing boilers retain replacement share in existing building stock. The KBA and federal building codes are tightening emissions thresholds for fossil fuel heating appliances. The Rhine-Ruhr industrial corridor maintains residual furnace demand through building renovation cycles.
China
Urban residential heating infrastructure expansion in northern provinces sustains gas-fired boiler demand despite national dual carbon goals prioritizing electrification. MIIT efficiency standards and GB certification requirements are raising minimum performance thresholds for domestic equipment. The Beijing-Tianjin-Hebei region is implementing coal-to-gas conversion programs that displace legacy heating with condensing furnace technology.
Japan
Space-constrained urban housing and high electricity costs sustain gas-fired heating demand in Tokyo and Osaka metropolitan areas. METI energy efficiency labeling programs and JIS standards are driving specification toward condensing heat exchanger configurations. The Kanto region is seeing hybrid gas-electric heating systems capture share in multifamily residential developments.
Residential Furnaces Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with modulating system specialists commanding premium positioning while scale manufacturers dominate tract housing specifications through streamlined single-stage portfolios. The vendor base clusters around three strategic tiers: integrated HVAC conglomerates with captive distribution, specialized heating equipment manufacturers with regional contractor loyalty, and Asian industrial groups leveraging component manufacturing scale. Consolidation pressure is intensifying as regulatory compliance costs favor entities with internal testing and certification capabilities. Competitive moves center on smart thermostat bundling to capture recurring service revenue and vertical integration into heat exchanger fabrication to buffer commodity metal volatility.
Within the integrated HVAC tier, Carrier Global Corporation, Trane Technologies plc, and Daikin Industries, Ltd. represent the dominant archetype of multi-product climate control specialists with global manufacturing footprints and proprietary distribution networks. These entities occupy positions where regulatory compliance scale and R&D centralization create defensive moats against regional competitors. Rheem Manufacturing Company and Lennox International Inc. exemplify the heating-focused specialist model with concentrated contractor relationships in North American replacement channels. Goodman Manufacturing anchors the cost-optimized new construction segment where specification-grade volume and installation speed drive procurement decisions.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Lennox International Inc. |
| Trane Technologies plc |
| Goodman Manufacturing |
| Rheem Manufacturing Company |
| Bryant Heating & Cooling Systems |
| Johnson Controls |
| Daikin Industries, Ltd. |
| American Standard Heating & Air Conditioning |
| Others |
Supply Flow & Price Mechanics
Variable-speed motor substitution for single-stage blowers is simultaneously redrawing component sourcing maps toward Mexico and compressing margin structures for OEMs locked into legacy Asian supply contracts. This dual displacement forces manufacturers to rebalance landed cost equations against regional assembly proximity as steel and copper volatility intensifies.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers now drive lifetime customer value more than initial equipment margins. Three-tier pricing structure across premium modulating systems, mid-grade two-stage units, and economy single-stage lines separates retrofit buyers from production homebuilder procurement. Pricing pressure stems from certified technician scarcity inflating installation costs passed through to end users. Replacement channel buyers exhibit lowest price sensitivity, prioritizing AFUE ratings and comfort consistency over first-cost minimization.
Supply Chain Analysis
Mexico and China anchor heat exchanger fabrication and blower motor assembly respectively, with Vietnam emerging as an alternative for sheet metal stamping operations. Copper tubing, cold-rolled steel, and rare-earth magnet materials feed from Chilean mining operations, domestic US mills, and Chinese processing facilities. Tariff exposure on Chinese-sourced electronics creates margin vulnerability for smart thermostat-integrated furnace lines. Distribution runs through captive dealer networks, wholesale HVAC distributors, and direct-to-contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential furnaces market sits at a replacement-cycle upswing driven by DOE efficiency mandate compression, favoring manufacturers with modulating system portfolios and certified distribution networks.
For Market Incumbents: Secure backward integration into heat exchanger fabrication to buffer copper and steel volatility while capturing margin from captive component supply. Deepen contractor loyalty programs in Sun Belt replacement corridors where electrification retrofits compete for scarce installation labor. Defend against heat pump substitution by bundling smart thermostat recurring revenue streams that lock in long-term service relationships. For New Entrants and Emerging Players: Remote diagnostics and predictive maintenance service layers represent underexploited white space where incumbents under-serve aging housing stock. Target the premium retrofit segment in Texas and Florida metropolitan areas where homeowner specification behavior prioritizes operating cost reduction. Pursue utility rebate program certification as the primary go-to-market credential, conditioning eligibility on ENERGY STAR partnership and regional incentive alignment. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors scaled entities with internal EPA testing capabilities and multi-state distribution licenses. Long-term viability hinges on electrification-mandate resilience and gas infrastructure moratorium geography exposure. Monitor state-level stretch code adoption velocity as the signal indicating replacement cycle acceleration or deferral.| Strategic Initiative | Industry Significance |
|---|---|
| Modulating System Platform Expansion | Captures DOE AFUE mandate compression while displacing single-stage legacy inventory. |
| Smart Thermostat Integration Partnership | Creates recurring service revenue streams through Xcel Energy and Duke Energy demand response programs. |
| Heat Exchanger Fabrication Backward Integration | Buffers margin volatility from Chilean copper and domestic steel commodity pricing swings. |
| Utility Rebate Program Certification Investment | Conditions ENERGY STAR eligibility on manufacturer participation in state-level incentive administration. |
| Sun Belt Distribution Network Densification | Aligns installer capacity with Texas and Florida housing start velocity straining mechanical contractor availability. |
Methodological Framework
Initial hypotheses were tested against primary input from HVAC contractor operations managers, OEM procurement directors, utility rebate program administrators, and residential homebuilder specification teams, then refined against secondary validation. Bottom-up equipment shipment data from EPA certification filings and DOE compliance databases combined with top-down housing start projections from Census Bureau construction statistics. Trade flow analysis from customs records and distributor inventory disclosures completed the triangulation architecture.
Variance decomposition across fuel type, heat exchanger configuration, installation channel, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segmented volume trajectories and price-band migration patterns across the projection horizon. Modeled inputs incorporated AFUE standard escalation timelines, electrification mandate jurisdiction mapping, and Sun Belt population migration velocity.
Forecasts assume regulatory continuity in DOE EPCA authority and state-level stretch code regimes; material policy shifts would require re-modeling. Specific risks include gas infrastructure moratorium expansion, heat pump substitution acceleration, and copper-steel commodity price spikes beyond historical bands. Recalibration cycles align with material shifts in efficiency standard enforcement timelines and utility incentive program renewals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
China Commercial HVAC Market