
 Roofing and Insulation Market | 2026-2036
Roofing and Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing and Insulation Market Analytics
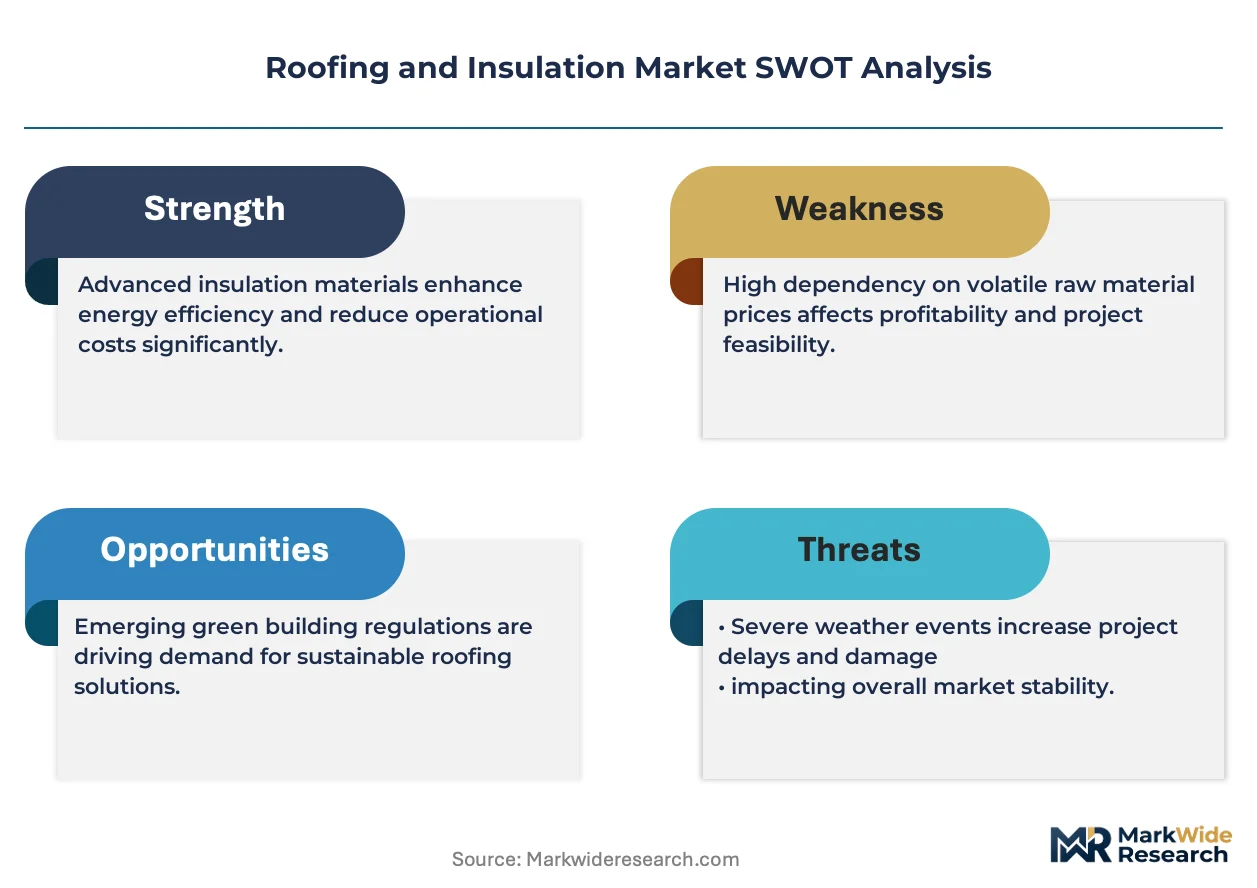
Skilled roofing installer availability is rotating toward shortage in mature construction economies, constraining project velocity and pushing wages upward. Owens Corning leverages its integrated fiberglass supply chain to buffer labor-driven cost inflation. Saint-Gobain anchors European production networks through captive mineral wool capacity. Kingspan Group specializes in insulated panel systems that reduce on-site labor hours per square meter.
Roofing and insulation encompasses weatherproof envelope systems and thermal barrier materials engineered to ASTM C1363 thermal resistance standards and IECC air-leakage thresholds, serving primarily to regulate building energy consumption and prevent moisture intrusion. Metal roofing and membrane systems lead commercial new construction due to lifecycle cost advantages and solar-ready compatibility. Retrofitting applications across residential stock show the fastest trajectory as energy audits and green financing unlock homeowner spending on attic and wall insulation upgrades.
US jurisdictions enforce IECC and ASHRAE standards through local building departments, while the EU F-Gas Regulation and Energy Performance of Buildings Directive constrain blowing-agent chemistry and mandate nearly zero-energy new construction. California Title 24 and Germany's Building Energy Act tighten envelope requirements in parallel, forcing manufacturers to recertify product lines. Stakeholders must monitor code harmonization momentum between federal minimums and accelerating state-level stretch codes.
Market Dynamics
Retrofit-driven demand is compressing project timelines and forcing manufacturers to recalibrate distribution toward contractor-direct channels rather than traditional two-step distribution. Labor scarcity in installation trades is amplifying this pressure, creating a structural bottleneck that favors prefabricated envelope solutions.
Growth Catalysts
- California Title 24 envelope mandates:The state's triennial energy code updates are compelling commercial building owners to accelerate roof replacement cycles ahead of compliance deadlines.
- Green financing instruments:Property-assessed clean energy (PACE) programs and green mortgage products are unlocking homeowner capital for attic and wall insulation retrofits.
- Mineral wool fire performance:Non-combustible insulation materials are gaining specification share in high-rise residential and healthcare construction.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane foam manufacturers face margin compression from benzene and methylene diphenyl diisocyanate price swings.
- EU F-Gas Regulation constraints:Blowing-agent chemistry restrictions are forcing reformulation of extruded polystyrene and spray foam product lines.
- Silicone sealant substitution:Advanced tape and membrane technologies are capturing share in low-slope commercial roofing detail applications.
Strategic Opportunities
- Germany's Building Energy Act (GEG):Nearly zero-energy building mandates for new construction are expanding demand for integrated roof-and-wall systems.
- Building-integrated photovoltaics convergence:Roofing manufacturers partnering with solar module producers can capture envelope-to-generation value chains.
- Pro contractor direct channels:Digital platforms connecting manufacturers to certified installers are disintermediating traditional distribution.
Industry Challenges
- Certified installer pipeline gaps:Spray polyurethane foam and single-ply membrane application require specialized training that vocational programs are not producing at replacement rates.
- ASTM C1363 thermal resistance testing:Extended laboratory certification timelines for new product formulations are delaying commercialization by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing and Insulation Market |
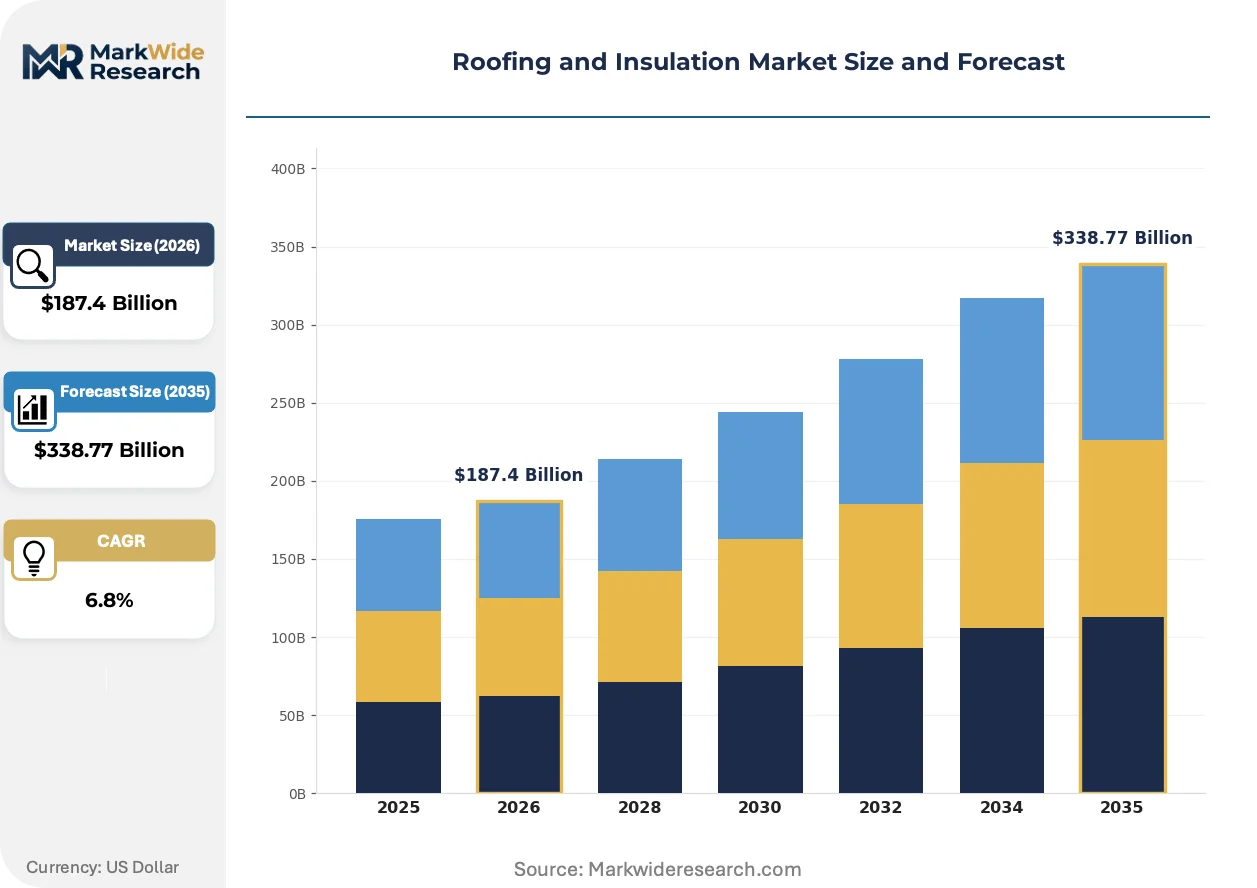
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shingles, Tiles, Metal, Membranes Material: Asphalt, Wood, PVC, Rubber Application: Residential, Commercial, Industrial, Agricultural Installation Method: New Construction, Retrofitting, Maintenance, Repair |
| Companies Covered | Owens Corning, Saint-Gobain, Kingspan Group, ROCKWOOL International, Knauf Insulation, Johns Manville, BASF, Carlisle Companies, Etex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing and Insulation Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to reshape product portfolios. Manufacturers are pivoting toward bio-based and recycled-content formulations while digital tools compress specification-to-installation workflows.
Polyisocyanurate (polyiso) rigid board insulation is supplanting extruded polystyrene in commercial roofing assemblies due to superior R-value per inch and compatibility with adhered membrane systems. Large-scale warehouse and distribution center developers are specifying polyiso for flat roof builds to maximize interior clear height. This transition is compressing demand for legacy polystyrene products and forcing producers to pivot toward below-grade and cavity wall applications.
REACH chemical registration requirements in Europe are tightening disclosure obligations for flame retardants and blowing agents used in plastic foam insulation. Manufacturers must submit comprehensive toxicity dossiers for substances of very high concern, adding compliance costs and reformulation cycles. The insulation segment is responding by accelerating mineral wool and bio-based polyurethane alternatives in continental European product portfolios.
Building owners are consolidating envelope procurement under single-source contractors who assume design-build responsibility for roof, wall, and insulation systems. This shift is displacing fragmented bidding processes where architects specified materials and general contractors sourced labor separately. Germany and the Netherlands show the most advanced adoption of integrated envelope contracting, driven by liability consolidation and warranty alignment preferences.
Roofing and Insulation Market Segmentation
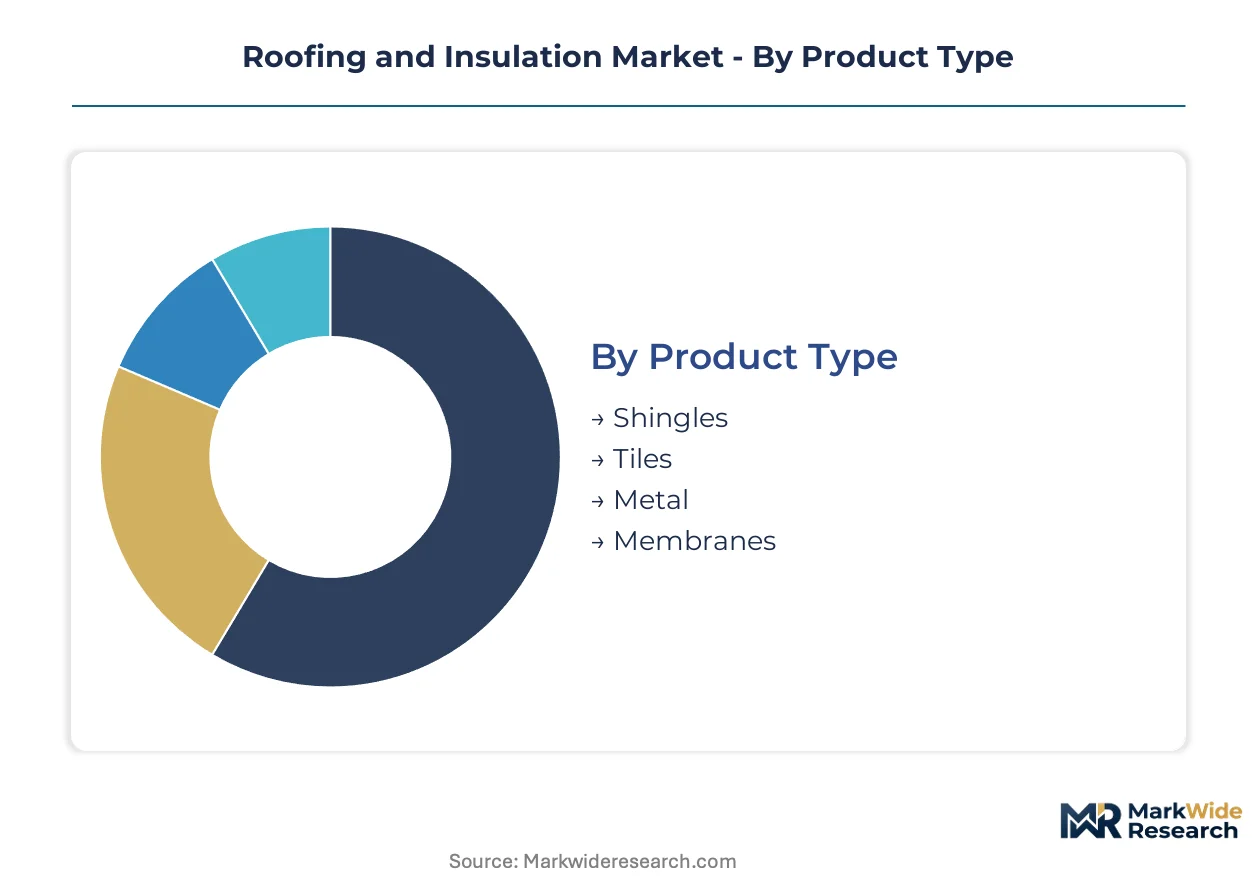
Segmentation in roofing and insulation determines specification pathways, procurement channels, and margin profiles. Product type and material composition dictate whether sales flow through distributor networks or direct-to-contractor platforms. Application and installation method segments reveal where labor scarcity and code compliance create pricing power.
Product Type:
Channel mix varies sharply across roofing systems, with membranes and metal panels favoring direct contractor relationships while shingles and tiles move through traditional two-step distribution.
- Shingles:Fiberglass-reinforced asphalt composition dominates residential replacement cycles. Big-box retailers and specialty distributors capture homeowner-driven demand in the US and Canada, though contractor-direct volume is climbing fastest.
- Membranes:TPO, EPDM, and PVC single-ply systems specified for flat commercial assemblies. Demand concentrates in warehouse and distribution center construction across Germany, the Netherlands, and Texas, driven by solar-ready roof requirements and accelerated depreciation schedules.
- Tiles:Clay and concrete products serving Mediterranean and Spanish Colonial architectural preferences. California and Florida sub-regions anchor specification, with clay imports from Spain and Mexico supplying premium residential segments.
- Metal:Standing seam and corrugated profiles specified for lifecycle cost advantages. Agricultural and industrial end-uses in the US Midwest and Australian rural markets favor metal for durability and fire resistance.
Shingles dominate installed base. Membranes are where expansion concentrates.
Material:
Cost tier stratification separates commodity feedstocks from performance-engineered compounds, with asphalt and PVC anchoring volume tiers and rubber commanding premium positioning.
- Asphalt:Saturated fiberglass mat core with ceramic granule surfacing constitutes the lowest-cost roofing envelope material. Residential re-roofing in the US Southeast and Midwest consumes the majority of production, constrained by petrochemical price volatility.
- PVC:Thermoplastic membrane formulation offering chemical resistance and weldable seams. Industrial facilities in Germany's chemical corridor and US Gulf Coast petrochemical plants specify PVC for spill containment and membrane longevity.
- Wood:Cedar shakes and shingles serving high-end residential and historic preservation segments. Pacific Northwest supply chains from British Columbia and Washington State feed niche demand in coastal California and New England markets.
- Rubber:EPDM and synthetic rubber compounds delivering cold-temperature flexibility and UV stability. Commercial flat roof applications in northern US states and Canadian provinces favor rubber for thermal cycling performance.
Asphalt and PVC together anchor volume tiers. Rubber is gaining share fastest in premium commercial specifications.
Application:
Customer type and project scale determine specification authority, with commercial and industrial segments consolidating procurement under single-source envelope contractors.
- Commercial:Office, retail, and hospitality buildings requiring integrated roof-wall systems. Germany and the Netherlands show advanced adoption of design-build envelope contracting, displacing fragmented architect-GC bidding.
- Residential:Single-family and multifamily housing stock driving retrofit insulation demand. PACE financing and green mortgage products in California and New York are unlocking homeowner capital for attic and wall upgrades.
- Industrial:Manufacturing and logistics facilities prioritizing clear height and thermal performance. Large-scale warehouse developers in Texas, Ohio, and Pennsylvania are specifying polyiso insulation to maximize interior volume.
- Agricultural:Barns, storage facilities, and livestock structures requiring cost-effective weather protection. US Midwest and Australian rural markets favor metal roofing for durability and low maintenance.
Commercial applications dominate specification value. Residential retrofits are climbing the fastest.
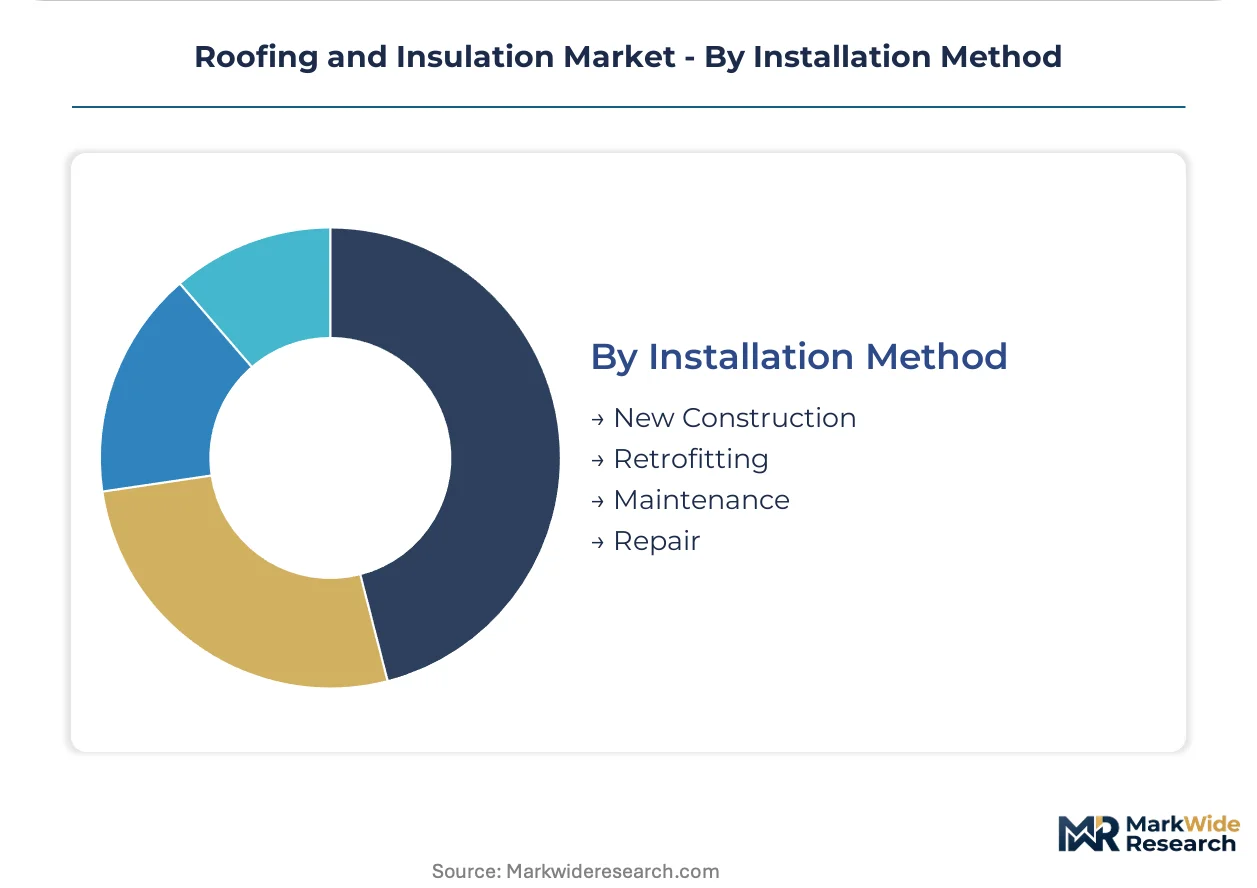
Installation Method:
Maturity and margin profiles diverge across project types, with new construction offering scale economies and retrofitting capturing scarcity premiums from labor constraints.
- Retrofitting:Energy-efficiency upgrades to existing building envelopes. Germany's Building Energy Act and California Title 24 are compelling building owners to accelerate roof replacement and insulation installation ahead of compliance deadlines.
- New Construction:Greenfield development with integrated envelope specification. Nearly zero-energy building mandates in Germany and stretch codes in California are expanding demand for high-R-value roof and wall assemblies.
- Repair:Storm damage and leak remediation requiring rapid response. Hurricane exposure in Florida and Gulf Coast states generates seasonal demand spikes, with insurance claim processing dictating contractor selection.
- Maintenance:Preventive inspection and membrane preservation extending asset life. Commercial property managers in the US Northeast and Midwest are adopting predictive maintenance contracts to defer capital replacement.
New construction anchors manufacturer volume. Retrofitting is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power through nearly zero-energy building mandates, while the United States extracts scarcity premiums from installer labor shortages in high-compliance states.
United States
California Title 24 triennial updates and Florida hurricane exposure drive specification intensity. The EPA enforces refrigerant phase-downs under AIM Act authority affecting foam blowing agents. Dallas-Fort Worth warehouse construction concentrates polyiso demand from logistics developers maximizing clear height.
Germany
The Building Energy Act (GEG) mandates envelope performance thresholds that accelerate roof replacement cycles. REACH chemical registration through ECHA constrains legacy flame retardant formulations. The Rhine-Ruhr industrial corridor anchors mineral wool production networks serving Benelux export markets.
China
Urban renewal programs in tier-one cities and dual carbon policy targets stimulate retrofit insulation demand. The Ministry of Ecology and Environment (MEE) enforces GB standards for building energy efficiency. The Yangtze River Delta manufacturing cluster supplies prefabricated envelope systems to Southeast Asian infrastructure projects.
India
Smart Cities Mission and PMAY-Urban housing drives commercial envelope specification growth. The Bureau of Indian Standards (BIS) certifies thermal insulation materials under IS codes. Gujarat's chemical corridor hosts expanded polyol production feeding domestic polyurethane foam manufacturers.
United Kingdom
Net-zero 2050 commitments and MEES regulations compel commercial property envelope upgrades. The Building Safety Regulator enforces post-Grenfell fire performance standards for high-rise cladding. Greater Manchester's retrofit acceleration zone channels green finance into social housing insulation programs.
Roofing and Insulation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated material suppliers commanding specification authority while regional fabricators compete on installation velocity. The market structures around three tiers: multinational chemical-material conglomerates with captive feedstock positions, specialized envelope system integrators with design-build capabilities, and regional contractors with installer certification networks. Dominant competitive moves include backward integration into mineral wool and fiberglass feedstocks, plus digital platform investments that disintermediate traditional distribution.
Among integrated material suppliers, Owens Corning and Saint-Gobain exemplify archetypes with captive fiberglass and mineral wool capacity respectively. Kingspan Group occupies a position within the system-integrator tier, specializing in factory-engineered panels that compress on-site labor requirements. These three anchors represent divergent strategic paths: feedstock control, manufacturing scale, and labor substitution through prefabrication.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| Kingspan Group |
| ROCKWOOL International |
| Knauf Insulation |
| Johns Manville |
| BASF |
| Carlisle Companies |
| Etex Group |
| Others |
Value Network & Pricing Analysis
REACH chemical registration through ECHA gates both supplier qualification and price differentiation simultaneously, forcing reformulation investments that stratify cost tiers while excluding uncertified producers from EU project specifications. ASTM C1363 thermal resistance certification creates parallel entry barriers in North America, where accredited testing extends commercialization timelines and concentrates pricing power among incumbent laboratories.
Pricing Analysis
Configured-to-order pricing for integrated roof-and-wall systems commands premiums of 15-25 percent above standard membrane or board insulation transactions, reflecting design-build liability consolidation and warranty alignment. Three-tier pricing structure across premium, standard, and economy levels stratifies by fire-performance certification and R-value density, with mineral wool and polyiso anchoring the premium tier. Cost compression in commodity asphalt shingles is intensifying because petrochemical feedstock volatility and distributor inventory carrying costs squeeze producer margins. Residential retrofit homeowners exhibit highest price sensitivity, while commercial warehouse developers prioritize lifecycle cost over first cost.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and Baltic Sea route disruptions have amplified inbound logistics costs for clay tile imports from Spain and mineral wool feedstock from Scandinavian producers. Manufacturing gravity centers on Germany, China, and the United States, with the Rhine-Ruhr corridor anchoring European mineral wool production and the Yangtze River Delta supplying prefabricated envelope systems. Raw material dependencies span benzene and methylene diphenyl diisocyanate for polyurethane foams, fiberglass mat for asphalt shingles, and bauxite-derived alumina for ceramic granules. Single-source vulnerability concentrates in blowing-agent chemistry constrained by EU F-Gas Regulation phase-downs. Distribution runs through contractor-direct digital platforms that disintermediate traditional two-step building material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retrofit-driven demand acceleration across aging building stock in North America and Europe signals early-cycle expansion, with green financing instruments unlocking homeowner capital penetration previously constrained by upfront cost barriers.
For Market Incumbents: Compound specification authority through captive mineral wool or fiberglass feedstock positions that buffer petrochemical volatility, while accelerating certified installer network investments to defend against labor-scarcity-driven prefabrication entrants. Prioritize backward integration into blowing-agent alternatives ahead of F-Gas Regulation tightening. For New Entrants and Emerging Players: Anchor in residential retrofit aggregation platforms that consolidate fragmented homeowner demand into contractor-scalable project pipelines, targeting attic and wall insulation upgrades in California and New York where PACE financing penetration remains below 15 percent. Pursue white-label partnerships with regional distributors lacking digital specification tools. For Investors and Strategic Acquirers: California Title 24 triennial tightening and Germany's Building Energy Act enforcement reshape the acquisition landscape toward envelope system integrators with design-build capabilities and certified installation networks. Long-term viability over the coming decade hinges on regulatory compliance velocity rather than manufacturing scale alone. Target acquisition archetypes: regional contractors with EPA Section 608-certified technician pipelines. Monitor ASTM C1363 accreditation backlogs as inflection indicator for product commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool Feedstock | Saint-Gobain's captive rock wool supply buffers ECHA REACH compliance costs against reformulation cycles. |
| Certified Installer Network Expansion | Contractor-direct platforms reduce project velocity constraints from labor scarcity in high-compliance states. |
| Prefabricated Panel System Manufacturing | Kingspan's factory-engineered assemblies compress on-site labor hours per square meter in German construction. |
| Green Financing Partnership Development | PACE program alignments unlock homeowner capital for attic retrofits ahead of California Title 24 deadlines. |
| Bio-Based Polyurethane Formulation Investment | BASF's plant-derived polyol alternatives anticipate REACH flame retardant disclosure tightening. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and national building code adoption records, combining structured interviews with roofing contractors, envelope system procurement managers at logistics developers, and technical directors at insulation manufacturers. Bottom-up project pipeline tracking across Dallas-Fort Worth, Rhine-Ruhr, and Yangtze River Delta construction markets triangulates against top-down material consumption estimates derived from petrochemical feedstock demand indicators.
Segmentation dimensions modeled span product type, material composition, application category, and installation method across the projection horizon, with additional granularity on fire-performance certification tiers and solar-ready membrane compatibility. CAGRs derive from regression analysis of historical replacement cycle data against regulatory compliance deadline clustering, incorporating polyiso R-value substitution rates and mineral wool specification share gains in high-rise residential construction.
Decision-makers should treat outputs as directional under assumptions of continued green financing instrument availability and stable petrochemical feedstock supply; material deviation in either would warrant model refresh. Specific risk factors include F-Gas Regulation acceleration, installer training program funding cuts, and hurricane season severity affecting Florida repair demand seasonality. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Building Asphalt Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Low-E Construction Glass Market
Building Materials
India Cement Market
Building Materials
Thin Brick Market
Building Materials
Cement Tiles Market
Building Materials
Foam Bricks Market
Building Materials
Stone Adhesive Market
Building Materials
Aluminum Door and Window Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Natural Stone Slab Market
Building Materials
China Cement Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Composite Rebar Market
Building Materials
Concrete Blocks and Bricks Market