
 North America Rainwater Harvesting Market | 2026-2036
North America Rainwater Harvesting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rainwater Harvesting Market Intelligence
LEED v4.1 certification for water efficiency is rotating market access toward suppliers with documented third-party validation. Watts Water Technologies leverages its plumbing heritage to anchor specification relationships with municipal engineers. Roth North America sustains competitive positioning through its tank manufacturing scale across Midwest distribution nodes. Bushman differentiates via rotational molding expertise that controls polymer thickness tolerances in above-ground cisterns.
Rainwater harvesting captures, stores, and treats precipitation from impervious surfaces for subsequent non-potable or potable reuse, typically incorporating first-flush diverters, sediment filtration, and UV or chlorine disinfection to meet applicable water quality standards. The primary purpose centers on reducing municipal water withdrawals, attenuating stormwater runoff volumes, and providing drought-resilient supply for irrigation, cooling towers, and toilet flushing. Above ground systems dominate residential and light commercial installations where excavation costs prove prohibitive, while below ground systems command premium positioning in urban commercial projects with strict setback requirements. Pumped systems represent the fastest-growing configuration as pressure-demand fixtures displace gravity-fed designs in multi-story buildings. Storage tanks concentrate the largest component margin pool due to material specialization in polyethylene, fiberglass, and concrete composites.
The EPA administers stormwater permitting under the Clean Water Act NPDES framework, while state plumbing boards in California, Texas, and Arizona maintain jurisdiction over cross-connection control and potable reuse approvals. The International Plumbing Code and Uniform Plumbing Code adoption variations across jurisdictions create compliance fragmentation that favors multi-state contractors with licensed engineering capacity. Stakeholders must monitor emerging state-level mandates for rainwater harvesting in new commercial construction as drought adaptation policies harden building code requirements.
Market Dynamics
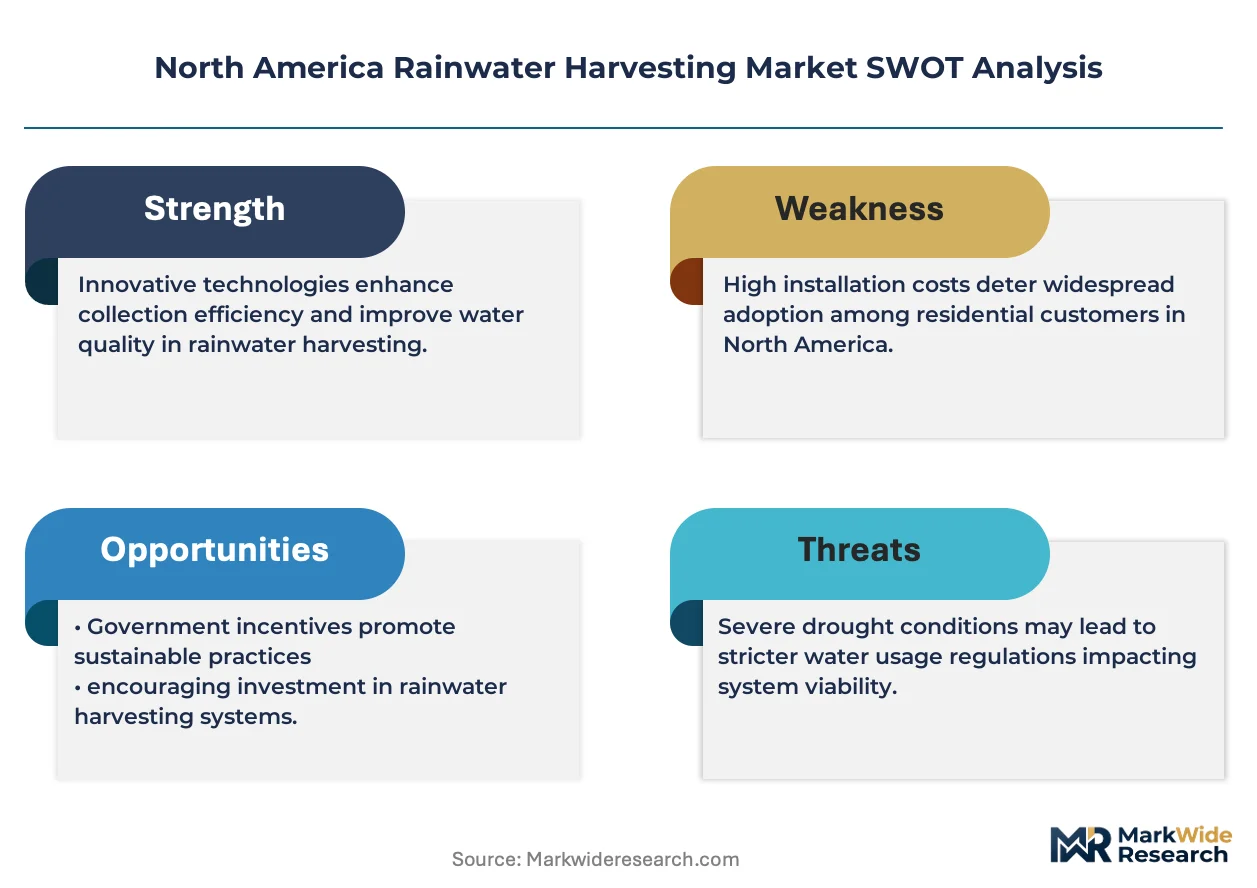
Municipal water managers across the southwestern United States are expanding non-potable water portfolios to reduce aquifer depletion, while EPA stormwater regulations and state-level plumbing code amendments accelerate system approvals. This structural pressure concentrates demand in Texas, California, and Arizona where drought declarations persist.
Growth Catalysts
- EPA NPDES Permitting:Stormwater discharge regulations under the Clean Water Act mandate runoff volume reduction, creating compliance-driven installation mandates for commercial properties in urban watersheds.
- Texas Senate Bill 55:Property tax exemptions for rainwater harvesting equipment lower total cost of ownership for residential and agricultural adopters across drought-prone counties.
- Rotational Molding:Advances in polyethylene tank manufacturing reduce wall-thickness variability, extending cistern service life and improving warranty terms for above-ground residential systems.
Market Restraints
- Cross-Connection Control:State plumbing board jurisdiction over potable reuse approvals creates multi-jurisdictional compliance fragmentation, extending project timelines.
- Excavation Cost Volatility:Below-ground system deployment faces input cost pressure from construction labor and equipment rental markets, compressing margins on commercial urban projects.
- Municipal Water Subsidies:Artificially suppressed potable water rates in legacy service territories reduce payback period attractiveness for capital-intensive harvesting investments.
Strategic Opportunities
- California Title 24 Amendments:Emerging mandates for rainwater harvesting in new commercial construction harden building code requirements, creating specification lock-in for pre-approved system designers.
- Cooling Tower Integration:Data center operators in water-stressed regions seek alternative supply for evaporative cooling, opening industrial-scale demand beyond traditional irrigation and toilet-flushing applications.
- IoT Sensor Convergence:Remote tank-level monitoring combined with predictive maintenance algorithms enables service-contract revenue models that displace equipment-only sales.
Industry Challenges
- Licensed Engineering Capacity:Multi-state contractors with cross-connection control certification remain scarce relative to permit application volume, creating project backlog bottlenecks.
- First-Flush Diverter Standardization:Absence of unified performance testing protocols for contaminant separation devices forces redundant validation across IPC and UPC adoption jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rainwater Harvesting Market |
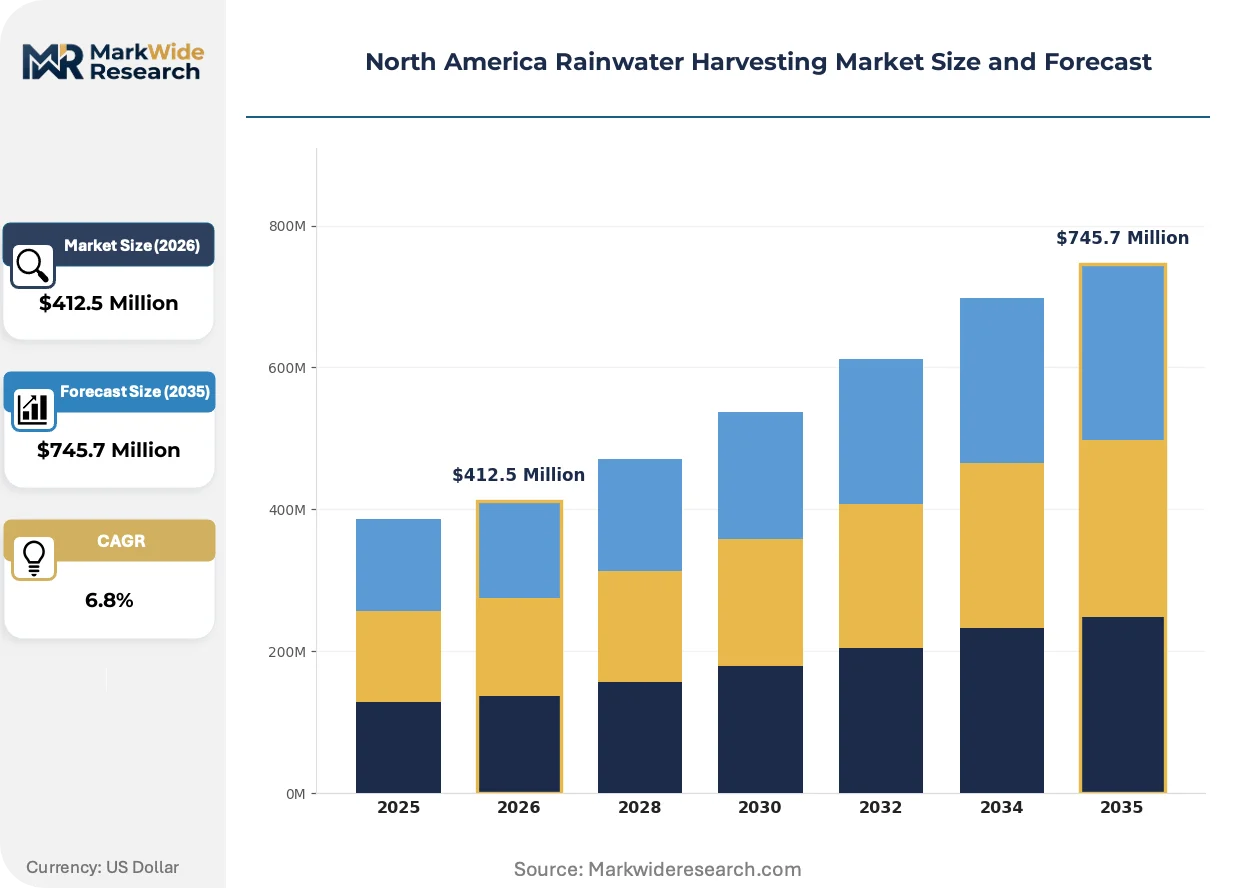
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Above Ground Systems, Below Ground Systems, Gravity Systems, Pumped Systems Application: Agricultural Irrigation, Residential Use, Commercial Use, Industrial Use Component: Storage Tanks, Filtration Systems, Pumps, Gutter Systems Installation Method: DIY Installation, Professional Installation, Modular Systems, Custom Solutions |
| Companies Covered | Watts Water Technologies, Roth North America, Bushman, The Water Harvesting Solutions (Wahaso), The RainCatcher Inc., Rainwater Management Solutions, Stormsaver, Kingspan Group, Graf Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rainwater Harvesting Market Strategic Shifts & Innovations
Technology convergence and regulatory tightening are reshaping competitive positioning across the rainwater harvesting value chain. Suppliers must now integrate smart monitoring, advanced materials, and compliance documentation to maintain specification access.
Smart pressure-demand pumping systems with variable-frequency drives are decomposing the historical dominance of gravity-fed designs in multi-story commercial buildings. Facility managers in Arizona and California office towers specify these configurations to meet fixture pressure requirements without elevated tank placement. The technology is decomposing traditional architectural constraints on system placement, enabling below-ground storage in dense urban sites.
California's Senate Bill 606 and subsequent drought contingency planning requirements impose municipal water use efficiency targets that cascade into building-level harvesting mandates. Local water districts now require documentation of non-potable supply sources for new commercial permits above threshold square footages. Multi-family residential developers in Los Angeles and San Diego metropolitan areas respond by pre-plumbing cisterns to avoid future retrofit costs.
Specification decisions increasingly rotate toward suppliers with documented third-party validation for water efficiency credits. LEED v4.1 certification requirements filter tank and filtration vendors based on independent performance testing rather than manufacturer claims alone. Municipal engineers in Texas and Arizona municipal water departments prioritize these pre-validated systems to reduce liability exposure on public projects.
North America Rainwater Harvesting Market Segmentation
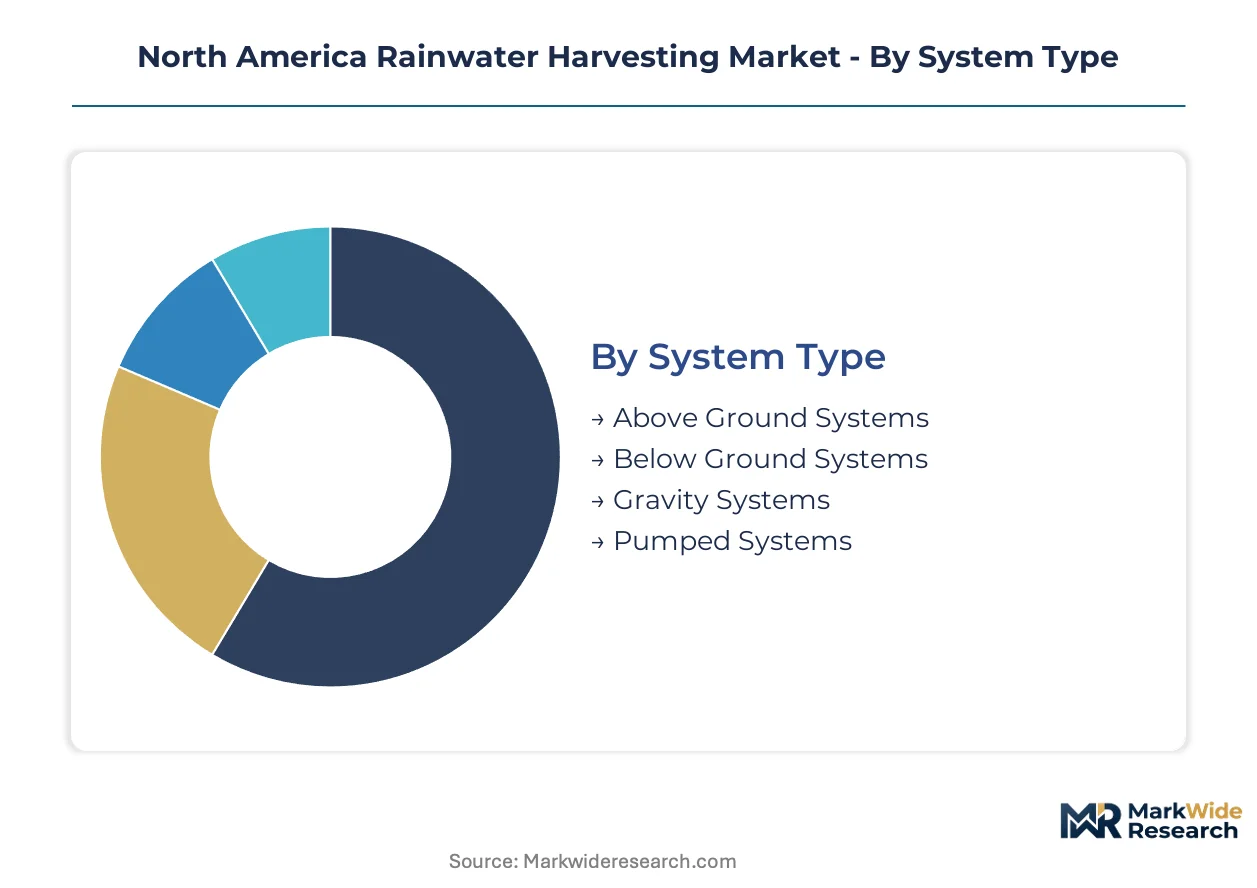
Rainwater harvesting equipment flows through distinct specification channels depending on system complexity and regulatory exposure. Segmentation reveals where margin pools concentrate and which configurations face procurement friction.
System Type:
Above ground and pumped configurations dominate residential retail channels, while below ground and gravity systems route through municipal engineering specifications and commercial contractors.
- Above Ground Systems:Polyethylene cisterns with rotational-molded construction deliver 20-30 year service life in residential and light commercial settings. Texas and Arizona homeowners favor these for irrigation and toilet flushing where excavation costs prove prohibitive and drought declarations persist.
- Pumped Systems:Variable-frequency drive pressure-demand configurations enable multi-story building integration without elevated tank placement. California office towers and Arizona commercial developments specify these to meet fixture pressure requirements while maintaining below-ground storage in dense urban sites with strict setback requirements.
- Below Ground Systems:Concrete composite and fiberglass reinforced tanks serve urban commercial projects where aesthetic and space constraints demand concealed installation.
- Gravity Systems:Simple roof-to-cistern-to-outlet designs retain niche positioning in rural agricultural and remote residential applications with minimal pressure requirements.
By volume, above ground systems lead. By growth pace, pumped systems are expanding most quickly.
Application:
Cost tier stratification separates capital-intensive industrial deployments from price-sensitive residential adoption, with commercial and agricultural segments occupying intermediate positions.
- Commercial Use:Office buildings, retail centers, and institutional facilities integrate harvesting for cooling towers, toilet flushing, and landscape irrigation under LEED v4.1 water efficiency mandates. California Title 24 amendments and municipal water district requirements in Los Angeles and San Diego metropolitan areas harden specification demand.
- Residential Use:Single-family and multi-family installations concentrate in Texas, California, and Arizona where property tax exemptions and drought contingency planning reduce payback periods. Texas Senate Bill 55 equipment exemptions lower total cost of ownership across drought-prone counties.
- Agricultural Irrigation:Ranch and farm operations deploy large-capacity cisterns for livestock watering and crop irrigation in water-stressed regions with unreliable municipal supply.
- Industrial Use:Data center operators in southwestern states seek alternative supply for evaporative cooling, opening demand beyond traditional non-potable applications.
Agricultural irrigation retains the largest installed base. Commercial use is climbing the fastest.
Component:
Supply concentration in polymer and fiberglass manufacturing shapes margin distribution across the value chain, with storage and filtration commanding premium positioning.
- Storage Tanks:Polyethylene, fiberglass, and concrete composite vessels concentrate the largest component margin pool due to material specialization and rotational molding expertise requirements. Wall-thickness tolerance control determines warranty terms and specification access.
- Filtration Systems:Sediment filtration, first-flush diverters, and UV or chlorine disinfection units ensure water quality compliance for non-potable and potable reuse applications. Absence of unified performance testing protocols forces redundant validation across IPC and UPC adoption jurisdictions.
- Pumps:Pressure-demand and variable-frequency drive configurations enable multi-story integration and smart monitoring convergence.
- Gutter Systems:Roof collection infrastructure represents the lowest-margin, most commoditized segment with minimal technology differentiation.
Storage tanks lead by revenue contribution. Filtration systems are gaining share fastest on regulatory tightening.
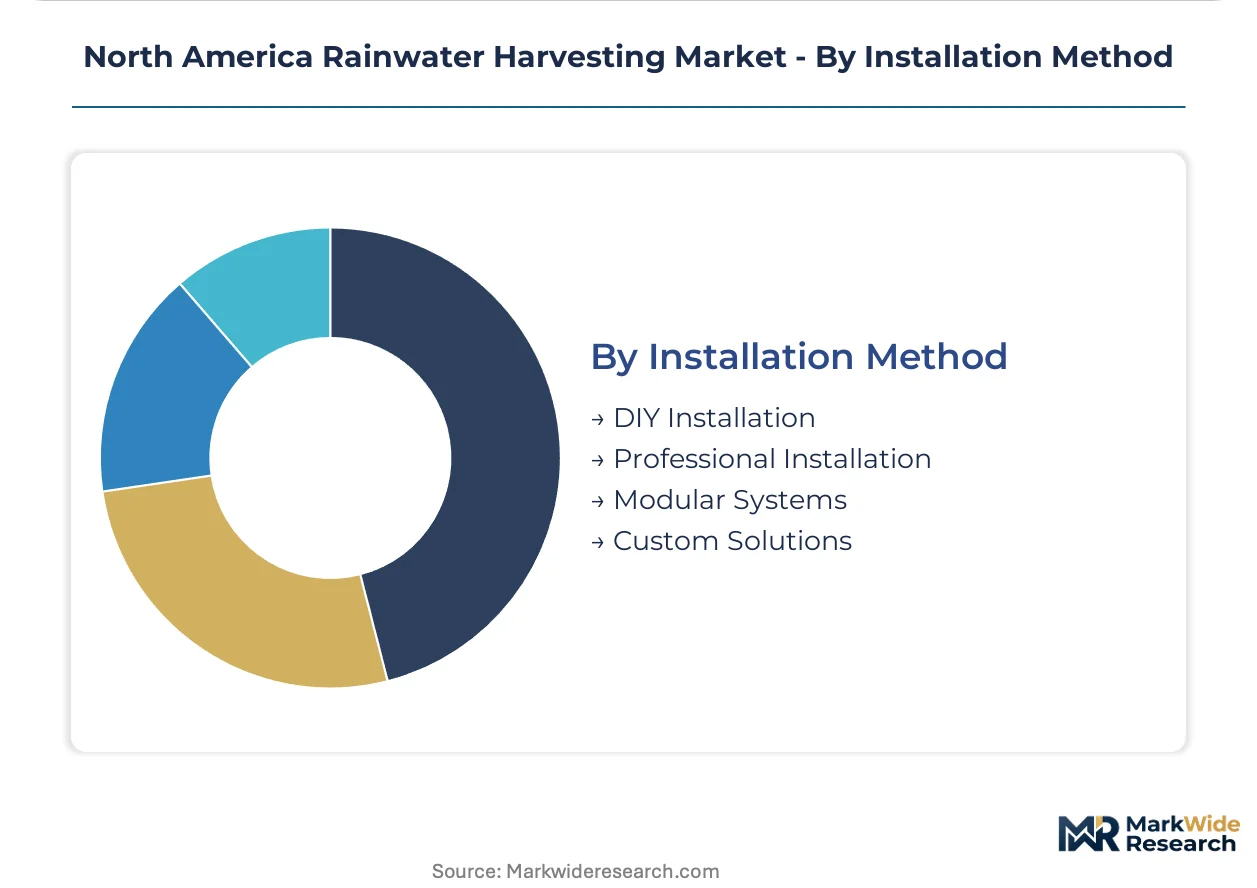
Installation Method:
Customer type and project scale determine whether procurement flows through retail DIY channels, licensed contractor networks, or integrated design-build firms.
- Professional Installation:Municipal and commercial projects require licensed engineering capacity for cross-connection control certification and multi-jurisdictional compliance. Scarcity of certified contractors relative to permit application volume creates project backlog bottlenecks in Texas, California, and Arizona.
- Modular Systems:Pre-engineered tank, pump, and filtration packages reduce design complexity for mid-scale commercial and multi-family residential developments. Pre-plumbing strategies in California avoid future retrofit costs under emerging building code mandates.
- DIY Installation:Residential above-ground systems in rural and suburban markets bypass contractor margins where plumbing code enforcement remains limited.
- Custom Solutions:Large-scale industrial and institutional projects demand site-specific engineering for cooling tower integration and high-volume storage requirements.
Professional installation dominates project value. Modular systems show the steepest expansion trajectory on standardization benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water managers and commercial property developers concentrate procurement authority across the southwestern United States, with Texas, California, and Arizona generating the dominant share of system specifications. State plumbing boards and EPA regional offices shape compliance pathways that favor contractors with multi-jurisdictional engineering capacity.
Southwestern United States
Texas Senate Bill 55 property tax exemptions lower total cost of ownership for residential and agricultural adopters across drought-prone counties. The Texas Commission on Environmental Quality coordinates with municipal water districts to streamline cross-connection control approvals. Dallas-Fort Worth and Houston metropolitan areas concentrate demand for above-ground cisterns in suburban residential developments.
California
Title 24 building code amendments impose municipal water use efficiency targets that cascade into harvesting mandates for new commercial construction above threshold square footages. The State Water Resources Control Board administers drought contingency planning requirements that harden specification demand. Los Angeles and San Diego metropolitan developers pre-plumb cisterns to avoid future retrofit costs under emerging mandates.
Arizona
Office towers and commercial developments in Phoenix and Tucson specify pumped systems with variable-frequency drives to meet fixture pressure requirements without elevated tank placement. The Arizona Department of Environmental Quality maintains jurisdiction over stormwater discharge permits under EPA-delegated NPDES authority. Maricopa County concentrates specification activity for below-ground storage in dense urban sites with strict setback requirements.
Canada
Municipal water infrastructure renewal programs in Ontario and British Columbia create specification pathways for commercial harvesting integration in institutional buildings. Health Canada and provincial environment ministries coordinate on non-potable water quality guidelines for cross-connection control. Toronto and Vancouver metropolitan areas concentrate demand for modular pre-engineered systems in multi-family residential developments.
North America Rainwater Harvesting Market Key Industry Players
Player mix skews toward plumbing heritage conglomerates and rotational molding specialists with material science capabilities. Market structure exhibits moderate consolidation around specification relationships with municipal engineers and commercial contractors. Two strategic archetypes dominate: integrated water infrastructure suppliers leveraging distribution scale, and polymer fabrication specialists controlling tank manufacturing tolerances. Competitive moves concentrate on portfolio diversification into smart monitoring convergence and geographic expansion through licensed contractor networks.
Within the integrated infrastructure tier, Watts Water Technologies and Roth North America occupy positions anchored by specification relationships with municipal engineering departments. Bushman exemplifies the rotational molding specialist archetype, with manufacturing expertise in polyethylene cistern fabrication. Wahaso and RainCatcher Inc. sit within the design-build contractor segment, where licensed engineering capacity for cross-connection control certification creates scarcity value relative to permit application volume.
| Leading Market Players |
|---|
| Watts Water Technologies |
| Roth North America |
| Bushman |
| The Water Harvesting Solutions (Wahaso) |
| The RainCatcher Inc. |
| Rainwater Management Solutions |
| Stormsaver |
| Kingspan Group |
| Graf Group |
| Others |
Cost & Logistics Intelligence
Rotational molding of high-density polyethylene replacing fiberglass in above-ground cisterns is redrawing supply geography toward Texas and Ohio polymer hubs while compressing per-unit manufacturing costs for residential system tiers. This material substitution simultaneously concentrates procurement leverage among tank fabricators with captive extrusion capacity and erodes margin buffers for distributors dependent on imported composite vessels.
Pricing Analysis
Cost-plus contracts indexed to resin commodity benchmarks dominate procurement between municipal engineering departments and integrated system suppliers across the southwestern United States. Price differentiation hinges on NSF/ANSI 61 certification tier and after-sales service bundling, with premium positioning commanding specification access for potable reuse applications. Cost compression in standard residential tiers intensifies as Chinese polyethylene imports undercut domestic rotational molding on price. Agricultural buyers exhibit highest price sensitivity due to seasonal cash flow constraints, while data center operators demonstrate lowest sensitivity given cooling tower downtime costs.
Supply Chain Analysis
Strategic stockpiling of resin feedstock prevails over just-in-time approaches among tank manufacturers hedging against polyethylene price volatility from Gulf Coast petrochemical disruptions. Supply concentrates in the United States, Canada, and Mexico under USMCA provisions, with raw material dependencies spanning HDPE resin, UV stabilizer additives, and pump variable-frequency drive components. Tariff exposure on Chinese filtration assemblies creates single-source vulnerability for sediment separation devices. Distribution runs through municipal engineering specification channels for commercial projects and big-box retail networks for residential above-ground systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rainwater harvesting incumbents face substitution defense against municipal greywater recycling infrastructure, which offers comparable non-potable supply with lower storage capital requirements in dense urban sites.
For Market Incumbents: Consolidate specification relationships with Texas and California municipal water districts through pre-engineered modular system portfolios that reduce engineering review cycles. Deepen backward integration into rotational molding capacity to defend margin position against resin price volatility and Chinese import competition. Prioritize cross-connection control certification investments to capture scarce licensed contractor capacity before permit application backlogs widen further. For New Entrants and Emerging Players: Anchor in Arizona commercial pumped system installations where variable-frequency drive expertise remains undersupplied relative to Phoenix and Tucson office tower development pipelines. Target data center cooling tower integration as the most penetrable industrial application beyond traditional irrigation and toilet flushing. Pursue design-build contractor licensing in multiple jurisdictions to circumvent specification friction from fragmented plumbing code adoption. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors rotational molding specialists with documented third-party validation and captive distribution networks. Long-term viability rests on regulatory tightening in drought-stressed states hardening building code mandates into specification lock-in. Watch California Title 24 amendment implementation velocity as the inflection signal for commercial demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Integration | Remote tank monitoring enables recurring service revenue displacing equipment-only sales. |
| Backward Integration into Rotational Molding | Captive polyethylene fabrication controls wall-thickness tolerances and warranty exposure. |
| Multi-Jurisdictional Contractor Licensing | Cross-connection certification scarcity creates bottleneck value in permit-heavy markets. |
| Cooling Tower System Design | Data center evaporative cooling opens industrial-scale demand beyond traditional applications. |
| Third-Party Validation Investment | LEED v4.1 and NSF certification filters specification access toward pre-validated suppliers. |
Research Approach
Cross-validation between primary interviews with municipal water managers, commercial contractors, and rotational molding plant managers and secondary validation through EPA NPDES permitting databases, state plumbing board filings, and USGS water use reports anchors the qualitative findings. The analysis draws from bottom-up equipment shipment tracking and top-down municipal capital expenditure triangulation across the southwestern United States and Canadian provincial markets.
Sensitivity analysis around resin price volatility, drought declaration frequency, and building code amendment timelines informs the analytical framework across the projection horizon. Segmentation dimensions span system type, application tier, component category, and installation method, with CAGRs derived from equipment replacement cycles and regulatory mandate implementation schedules. Forecast inputs incorporate municipal water rate trajectories and commercial construction permit pipelines.
Decision-makers should treat outputs as directional under base assumptions of continued drought contingency planning and stable USMCA polymer trade flows; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EPA stormwater enforcement intensity and state-level potable reuse approval pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Septic Tanks Market