
 Asia-Pacific Facade Market | 2026-2036
Asia-Pacific Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Facade Market Outlook
Market Context with Strategic Players
Commercial tower construction is restructuring procurement priorities across the Asia-Pacific facade sector. Saint-Gobain leverages its glass technology leadership to anchor premium specification channels in high-rise markets. Lindner Group KG sustains manufacturing scale advantages across modular cladding systems for institutional and mixed-use projects. Leo Fab Asia specializes in metal facade fabrication, competing on customization depth for architect-driven developments.
Technical Definition and Structural Segments
A facade constitutes the exterior envelope system of a building, integrating structural support, weather resistance, thermal barriers, and aesthetic cladding through assemblies of glass, metal, composite panels, or wood substrates engineered to precise performance coefficients. Its primary commercial purpose is to mediate between interior environmental control and external conditions while defining architectural identity. Glass and composite materials command the fastest growth trajectories as thermal insulation and sustainability functionality requirements tighten across building codes. Metal retains margin concentration in bespoke commercial applications where acoustic performance and durability premiums justify higher specification costs.
Regulatory Framework and Outlook
China's MEE enforces dual carbon compliance timelines that directly mandate envelope efficiency upgrades, while India's BIS certification protocols for curtain wall systems create non-tariff barriers that filter supplier participation. Japan's METI building energy standards and South Korea's MFDS-adjacent construction material safety frameworks add layered compliance complexity for cross-border component sourcing. Stakeholders must monitor regulatory divergence between national energy codes and material certification reciprocity agreements to optimize manufacturing footprint decisions.
Market Dynamics
China's dual carbon mandate from the MEE is compressing specification timelines across the Asia-Pacific facade sector, forcing developers to pre-certify envelope systems before groundbreaking. This regulatory acceleration is redrawing competitive boundaries between domestic and cross-border suppliers.
Growth Catalysts
- India's urban renewal programs:Commercial tower construction in Mumbai and Bangalore is generating procurement volume for advanced curtain wall assemblies. State-level development authorities are bundling facade performance into project approvals.
- MEE dual carbon compliance:China's envelope efficiency mandates are pulling high-performance glazing and thermal break systems into mainstream specification channels. Manufacturers with certified low-carbon product lines are securing preferred supplier status.
- Photovoltaic integration:Building-integrated photovoltaics are penetrating mixed-use developments across Southeast Asia. Solar glass facade systems are capturing specification share from conventional cladding in premium commercial segments.
Market Restraints
- Aluminum input volatility:Primary aluminum price swings are compressing margin stability for metal facade fabricators serving mid-market commercial projects. Hedging costs are transferring into tender pricing.
- BIS certification barriers:India's curtain wall system approval protocols are filtering out smaller regional suppliers without testing laboratory partnerships. Compliance timelines are extending project procurement cycles.
- Technical glass supply concentration:High-performance coated glass production concentrates among limited East Asian manufacturers. Geographic supply clustering is amplifying logistics risk for Indian and Southeast Asian projects.
Strategic Opportunities
- Vietnam's industrial corridor expansion:Manufacturing facility construction in Bac Ninh and Hai Phong is generating demand for modular cladding systems. Foreign direct investment flows are accelerating specification upgrades.
- Retrofit application white space:Existing commercial building energy audits in Japan and South Korea are opening envelope replacement cycles. Aging tower stock is creating aftermarket demand for high-performance retrofit assemblies.
- Prefabrication technology convergence:Digital fabrication and off-site manufacturing are compressing installation timelines for complex geometric facades. Architect-driven developments are rewarding suppliers with integrated design-to-install capabilities.
Industry Challenges
- Facade engineering talent scarcity:Computational design and thermal modeling expertise is concentrating among specialist consultancies. Project developers are facing extended recruitment cycles for envelope system engineers.
- Multi-jurisdiction certification complexity:Cross-border projects must reconcile Japan's METI standards with China's GB codes and India's BIS protocols. Parallel testing requirements are inflating product development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Facade Market |
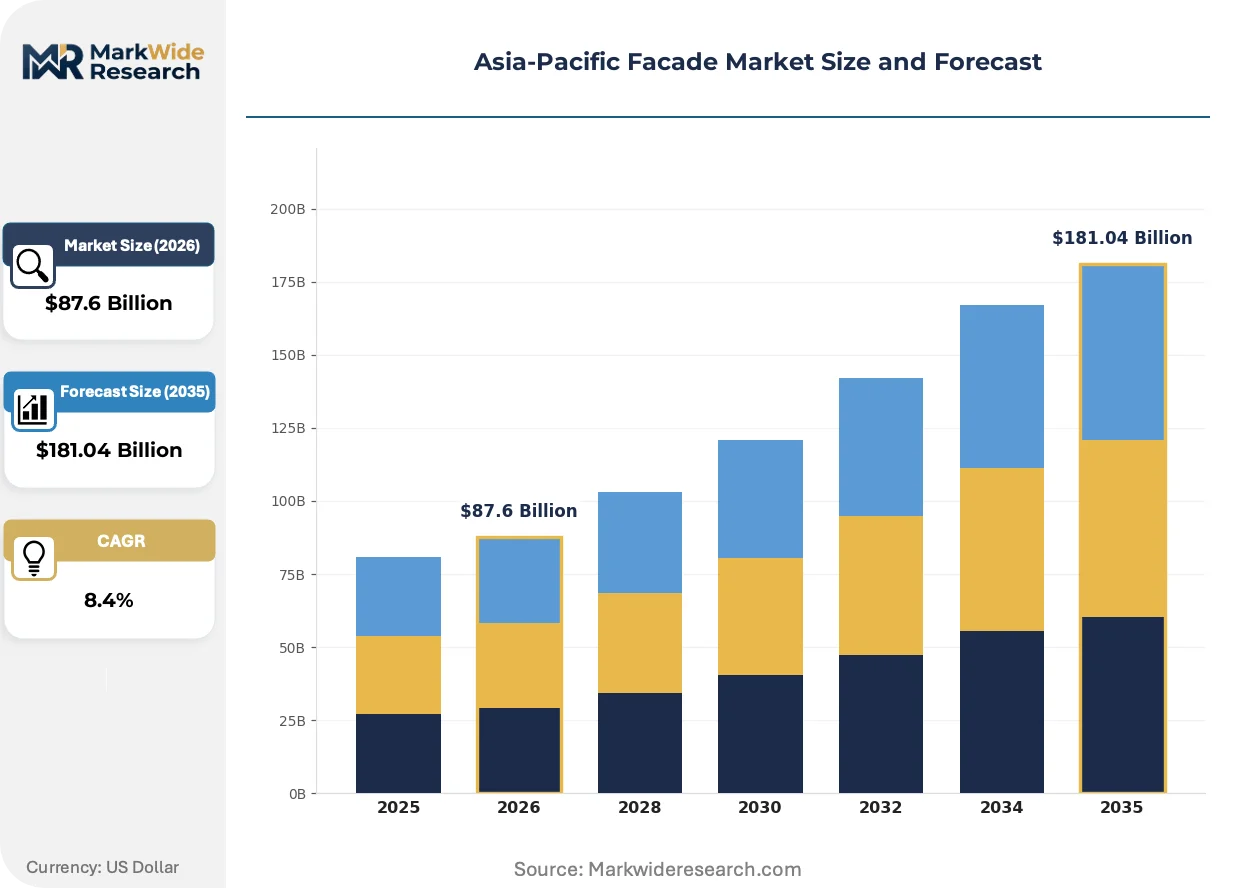
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Metal, Wood, Composite Building Type: Commercial, Residential, Institutional, Mixed-Use Installation Type: New Construction, Renovation, Retrofitting, Prefabricated Functionality: Thermal Insulation, Aesthetic Appeal, Acoustic Performance, Sustainability |
| Companies Covered | KASKAL CO., LTD., Lee Wall Cladding & Roofing Pte. Ltd., Leo Fab Asia, Lindner Group KG, Saint-Gobain, AGL Façade Systems Pte. Ltd., Aluplex India Pvt Ltd, Axis Facades, Benson Curtain Wall, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Facade Market Strategic Shifts
Digital fabrication and climate-responsive materials are rewriting specification logic across the Asia-Pacific facade sector. Architects and developers are prioritizing envelope systems that merge energy performance with adaptive functionality.
Electrochromic glazing is rewriting daylight management in high-rise commercial towers. Premium office developers in Singapore and Sydney are specifying tunable tint systems to reduce HVAC load. The technology is compressing the trade-off between glazing ratios and thermal performance that previously constrained facade design.
China's MEE is tightening embodied carbon disclosure requirements for construction materials. Project developers must now document cradle-to-gate emissions for envelope system components. Glass and aluminum suppliers with verified Environmental Product Declarations are securing specification preference in Beijing and Shanghai commercial towers.
Integrated project delivery models are displacing traditional design-bid-build sequences for complex facade systems. Developer-consultant-fabricator consortiums are assuming single-point accountability for envelope performance. This consolidation is most visible in Australia's mixed-use megaprojects and Japan's commercial redevelopment zones.
Asia-Pacific Facade Market Segmentation
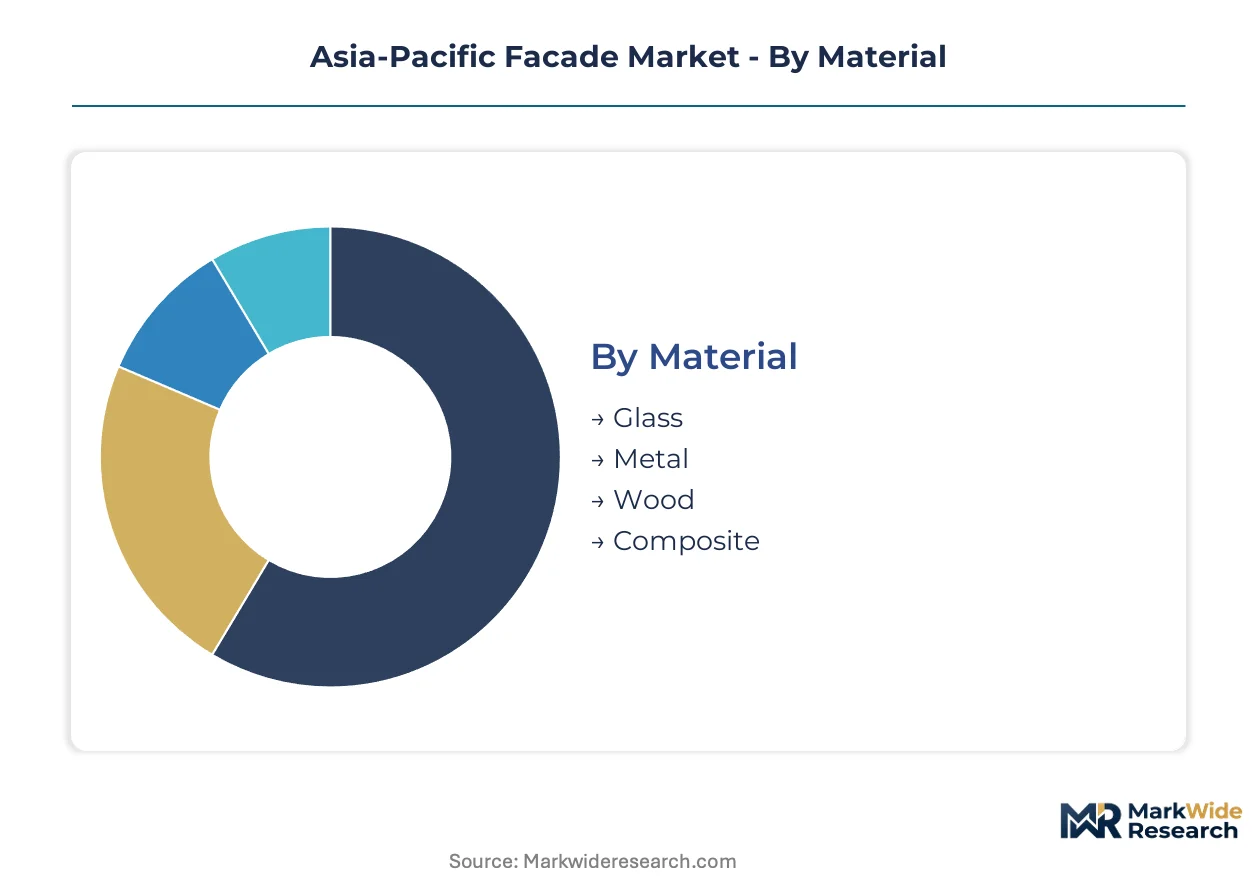
Facade procurement patterns across the Asia-Pacific region diverge sharply by material performance, building typology, and installation methodology. Specification decisions cascade through energy code compliance, architectural intent, and project delivery models.
Material:
Glass commands volume leadership in high-rise commercial towers, while metal and composite materials capture premium specification tiers in architect-driven developments.
- Glass:High-performance coated and laminated assemblies dominate curtain wall specifications for commercial towers in Shanghai, Singapore, and Sydney. China's MEE dual carbon mandates are accelerating low-emissivity and solar control glazing adoption across mainstream projects.
- Metal:Aluminum and steel cladding systems deliver acoustic dampening and durability premiums for airports, hospitals, and institutional complexes. India's BIS certification protocols are filtering supplier participation in government-backed urban renewal schemes.
- Wood:Engineered timber facades serve boutique commercial and residential segments where biophilic design commands specification premiums.
- Composite:Fiber-reinforced polymer and aluminum composite panels balance weight reduction with thermal performance for geometrically complex envelopes.
Today's leader: Glass. Tomorrow's challenger: Composite.
Building Type:
Commercial towers generate procurement volume, while mixed-use developments integrate performance requirements across multiple occupancy types.
- Commercial:Office towers and retail complexes drive specification for high-performance glazing and unitized curtain wall systems. Mumbai and Bangalore commercial construction is reshaping procurement timelines for advanced envelope assemblies.
- Mixed-Use:Integrated residential-office-hotel developments in Southeast Asia mandate facade systems that mediate conflicting thermal and acoustic performance requirements across zones.
- Residential:High-rise apartment towers in Vietnam and the Philippines prioritize cost-efficient cladding with baseline thermal insulation compliance.
- Institutional:Airports, convention centers, and healthcare facilities specify metal and composite systems for durability and maintenance access.
Commercial towers anchor current procurement volume. Mixed-use developments are climbing the fastest as urban densification accelerates across Southeast Asian megacities.
Installation Type:
New construction absorbs capacity, while prefabrication and retrofitting are compressing project timelines and opening aftermarket revenue streams.
- New Construction:Ground-up commercial and mixed-use projects in India, Vietnam, and Indonesia drive volume demand for conventional stick-built and unitized curtain wall installation.
- Prefabricated:Off-site manufactured facade modules are reducing site labor requirements and quality variability for complex geometric envelopes in Japan and Australia.
- Renovation:Envelope replacement cycles for aging commercial stock in Tokyo and Seoul are creating demand for high-performance retrofit assemblies.
- Retrofitting:Energy audit-driven facade upgrades in South Korea's commercial building stock are opening specification channels for secondary glazing and external insulation systems.
New construction maintains procurement dominance. Prefabricated installation is gaining share fastest as digital fabrication capabilities mature across regional manufacturing bases.
Functionality:
Thermal insulation anchors code compliance, while sustainability and acoustic performance differentiate premium specification tiers.
- Thermal Insulation:High-performance thermal break systems and low-conductivity glazing assemblies are mandatory for China's GB energy code compliance and India's ECBC adoption in commercial towers.
- Sustainability:Embodied carbon disclosure requirements under China's MEE and Australia's NABERS frameworks are pulling Environmental Product Declaration-certified materials into specification channels.
- Aesthetic Appeal:Architect-driven developments in Singapore and Sydney prioritize custom metal panel geometries and electrochromic glazing for signature visual identity.
- Acoustic Performance:Laminated glass and insulated metal panel systems serve airports, elevated transit corridors, and dense urban residential towers in Hong Kong and Bangkok.
Thermal insulation anchors regulatory compliance. Sustainability functionality is expanding most quickly as carbon accounting integrates into procurement evaluation frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting facade manufacturing investment toward jurisdictions with streamlined certification pathways and lower embodied carbon compliance costs. China's MEE mandates and India's BIS protocols are creating divergent cost-of-compliance landscapes that reshape cross-border supplier positioning.
China
Dual carbon enforcement from the MEE is compressing specification timelines for envelope efficiency upgrades. GB energy code revisions mandate thermal break performance thresholds that filter supplier participation in Beijing and Shanghai commercial towers. Yangtze River Delta manufacturing clusters are consolidating high-performance glazing capacity to serve domestic megaproject demand.
India
Urban renewal programs in Mumbai and Bangalore are generating procurement volume for advanced curtain wall assemblies. BIS certification protocols for curtain wall systems create non-tariff barriers that extend project procurement cycles. Maharashtra and Karnataka state development authorities are bundling facade performance metrics into commercial tower approvals.
Japan
Commercial building energy audits in Tokyo are opening envelope replacement cycles for aging tower stock. METI building energy standards mandate thermal performance disclosure that pulls high-performance retrofit assemblies into specification channels. Kanto region redevelopment zones are integrating prefabricated facade modules to compress installation timelines.
Vietnam
Industrial corridor expansion in Bac Ninh and Hai Phong is generating demand for modular cladding systems. Foreign direct investment flows from manufacturing facility construction are accelerating specification upgrades. Northern Vietnam manufacturing clusters are attracting regional fabrication capacity to serve Southeast Asian mixed-use developments.
South Korea
Energy audit-driven facade upgrades in Seoul's commercial building stock are creating aftermarket demand for secondary glazing systems. MFDS-adjacent construction material safety frameworks add compliance complexity for cross-border component sourcing. Busan-Ulsan industrial zones are developing digital fabrication capabilities for complex geometric envelopes.
Asia-Pacific Facade Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers scale regional fabrication footprints to compress logistics costs and certification timelines. The vendor base stratifies across three tiers: multinational material suppliers with certified low-carbon product lines, mid-scale regional fabricators with BIS or GB testing laboratory partnerships, and specialist metalwork contractors serving architect-driven developments. Strategic archetypes include scale-driven manufacturers pursuing manufacturing footprint consolidation and technology-integrated players combining digital fabrication with design-to-install capabilities. Competitive moves center on backward integration into high-performance glass and aluminum supply and geographic expansion into Vietnam and Indonesia production corridors.
Among European-origin multinationals, Saint-Gobain and Lindner Group KG exemplify scale-driven archetypes with manufacturing breadth across premium specification channels. Leo Fab Asia occupies a position within the specialist fabrication tier, competing on customization depth for metal facade assemblies in architect-driven developments. These three anchors represent divergent strategic postures: certified product line breadth, modular system manufacturing scale, and bespoke metalwork customization respectively.
| Leading Market Players |
|---|
| KASKAL CO., LTD. |
| Lee Wall Cladding & Roofing Pte. Ltd. |
| Leo Fab Asia |
| Lindner Group KG |
| Saint-Gobain |
| AGL Façade Systems Pte. Ltd. |
| Aluplex India Pvt Ltd |
| Axis Facades |
| Benson Curtain Wall |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between MEE-compliant low-carbon systems and uncertified commodity alternatives manifests in divergent margin structures and sourcing footprints across the Asia-Pacific facade sector. Premium specification channels reward verified Environmental Product Declarations with pricing power, while mid-market procurement compresses supplier margins through aluminum spot-price exposure and extended BIS testing timelines.
Pricing Analysis
Distributor markups of 12-18% separate certified high-performance glazing from direct-to-developer contract pricing for modular cladding systems. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance coefficients, BIS/GB certification status, and after-sales installation bundling. Cost compression in mid-market metal facade tiers is intensifying because primary aluminum volatility transfers hedging expenses into tender submissions. Government-backed urban renewal authorities in India exhibit highest price sensitivity, while Singapore premium office developers prioritize performance over unit cost.
Supply Chain Analysis
Skilled facade engineering labor scarcity in Vietnam and Indonesia is constraining modular manufacturing scale-up despite foreign direct investment inflows. High-performance coated glass production concentrates in China, South Korea, and Japan, while aluminum extrusion and composite panel fabrication clusters in Thailand and Malaysia. Raw material dependencies span primary aluminum ingot, soda-lime silica glass, and thermoplastic interlayers. Single-source vulnerability for electrochromic glazing intellectual property amplifies procurement risk for architect-driven developments. Distribution runs through regional fabricator networks with project-direct OEM relationships for megaproject volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MEE compliance costs and India's BIS certification timelines creates manufacturing relocation incentives for envelope system suppliers seeking margin preservation.
For Market Incumbents: Cement preferred supplier status in Beijing and Shanghai commercial towers through captive low-carbon glass supply and pre-certified thermal break product lines. Defend against emerging Vietnamese fabricators by locking long-term offtake agreements with Yangtze River Delta glazing manufacturers. Prioritize backward integration into aluminum extrusion to buffer primary metal volatility. For New Entrants and Emerging Players: Enter via Vietnam's Bac Ninh industrial corridor to capture manufacturing facility construction demand for modular cladding systems. Target retrofit application white space in Tokyo and Seoul commercial tower stock where energy audit mandates drive envelope replacement cycles. Lead with digital fabrication capabilities to compress design-to-install timelines for complex geometric facades. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional fabricators possessing BIS laboratory partnerships and GB certification pathways that multinational material suppliers lack. Five-to-ten year viability hinges on manufacturing footprint consolidation across Southeast Asian production corridors. Watch for MEE embodied carbon disclosure expansion into provincial tier-two cities as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of primary metal insulates margin compression from LME volatility in mid-market tiers. |
| Prefabrication Technology Investment | Digital fabrication capabilities compress installation timelines for Japan's Kanto redevelopment zone projects. |
| BIS Laboratory Partnership Acquisition | Testing infrastructure ownership accelerates curtain wall approval cycles for Maharashtra urban renewal schemes. |
| Environmental Product Declaration Certification | Verified cradle-to-gate emissions documentation secures specification preference under China's MEE mandates. |
| Vietnam Manufacturing Footprint Expansion | Bac Ninh and Hai Phong clusters reduce logistics costs for Southeast Asian mixed-use development procurement. |
Study Parameters
Bottom-up commercial tower and mixed-use development modeling reconciled against top-down high-performance glazing and metal cladding capacity tracking forms the analytical core of this study. Primary interviews with facade engineering consultants, curtain wall procurement managers at state development authorities, BIS certification laboratory directors, and METI energy code compliance officers combined with secondary validation from customs trade data, GB energy code revision filings, MEE policy circulars, and project development databases. Triangulation between supply-side manufacturing surveys and demand-side specification tracking ensures cross-validation.
Historical trendline analysis of envelope system procurement volumes and thermal performance code adoption patterns informed projection framework construction across material type, building typology, installation methodology, and functionality segmentation. Modeled dimensions span glass-metal-composite-wood material splits, commercial-mixed-use-residential-institutional end-use categories, new construction-prefabricated-renovation-retrofit installation types, and thermal-sustainability-aesthetic-acoustic functionality tiers. CAGRs derive from regression analysis of specification intensity against regulatory compliance deadlines and urban densification rates. Industry-specific forecast inputs include MEE dual carbon enforcement phase-in schedules and BIS testing laboratory capacity expansion plans.
The model holds under stable regulatory enforcement timelines and aluminum price band assumptions; deviation in MEE provincial expansion pace or primary metal supply disruption would shift specification channel dynamics. Forecasts reflect documented assumptions regarding certification reciprocity agreements and foreign direct investment flows into Vietnamese manufacturing corridors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
France Architectural Coatings Market
Building Materials
Natural Stone Market
Building Materials
Basalt Rock Market
Building Materials
North America Engineered Stone Market
Building Materials
Timber Frames Market
Building Materials
Roofing and Insulation Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Pozzolana Cement Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
GRC Cladding Market
Building Materials
United States White Cement Market