
 Concrete Market | 2026-2036
Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Market Intelligence
Aftermarket service revenue in concrete supply is fragmenting as producers compete on logistics reliability and pour-site technical support rather than commodity tonnage alone. Holcim Group leverages its global batch-plant network to sustain just-in-time delivery contracts across metropolitan zones. Heidelberg Materials anchors European market presence through clinker-substitution R&D and circular material integration. CEMEX competes on digital fleet routing that compresses ready-mix dispatch windows in dense urban corridors.
Concrete is a composite construction material comprising cementitious binder, coarse and fine aggregates, water, and chemical admixtures, typically achieving compressive strengths from 20 MPa in standard mixes to over 150 MPa in ultra-high performance formulations; its primary purpose is to provide structural load-bearing capacity in buildings, transportation networks, and civil infrastructure. Ready-mix concrete dominates volume flows due to batch-plant proximity to urban job sites, though ultra-high performance concrete captures disproportionate margin pools in bridge deck repairs and seismic retrofit applications. Precast concrete segments accelerate as off-site fabrication reduces on-site labor exposure and weather dependency for government and developer end users.
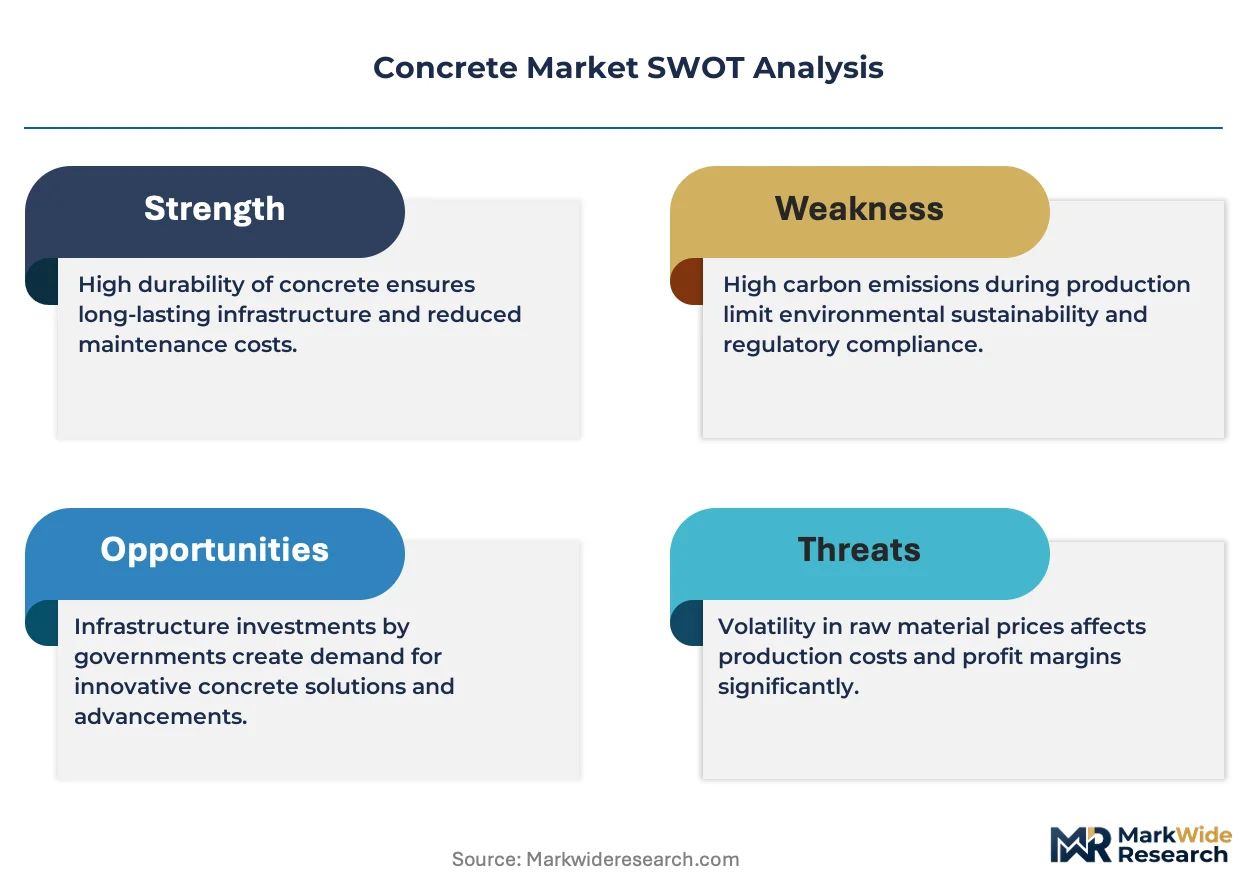
EPA emissions standards in the United States and the EU Green Deal's carbon-border adjustment mechanisms are tightening permissible CO₂ per ton of cementitious product, compelling producers to invest in alternative binders and carbon capture retrofitting at kiln facilities. India's Bureau of Indian Standards enforces mandatory concrete grade certifications for government infrastructure tenders, shaping procurement specifications across state public works departments. Stakeholders must monitor regulatory divergence between carbon-accounting frameworks as compliance costs fragment competitive positioning across export-exposed supply chains.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are forcing wholesale reformulation of cementitious binders across member states, compressing margins for conventional Portland cement while rewarding clinker-substituted alternatives with preferential procurement access.
Growth Catalysts
- Urbanization corridors:Southeast Asian metropolitan zones are scaling specification-grade concrete procurement as residential towers and transit nodes absorb bulk cementitious volumes.
- EU Green Deal enforcement:Carbon-border adjustment mechanisms are redirecting import flows toward low-clinker producers with verified environmental product declarations.
- Geopolymer binders:Industrial waste-stream activation is displacing conventional cement in precast applications where curing time flexibility permits alternative chemistry.
Market Restraints
- Clinker supply concentration:Kiln capacity clusters in China and India expose importers to freight volatility and currency fluctuation risk.
- Limestone calcination emissions:Process chemistry limits CO₂ reduction potential regardless of fuel switching or efficiency gains.
- Steel-fiber reinforcement:Ultra-high performance formulations face substitution pressure from engineered polymer composites in seismic retrofit segments.
Strategic Opportunities
- Carbon capture retrofitting:Post-combustion amine scrubbing at European kiln facilities qualifies producers for green procurement tenders under EU taxonomy alignment.
- Off-site precast fabrication:Government and developer end users are migrating volume to factory-cast elements that compress project schedules and reduce labor exposure.
- India's Bureau of Indian Standards certification:Mandatory concrete grade enforcement for infrastructure tenders creates premium positioning for accredited batch-plant operators.
Industry Challenges
- Mix-design engineering talent:Formulation expertise for low-carbon binders concentrates among senior technical staff approaching retirement without structured knowledge transfer.
- Batch-plant reconfiguration:Silo additions for supplementary cementitious materials demand capital deployment amid compressed return-on-investment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Market |
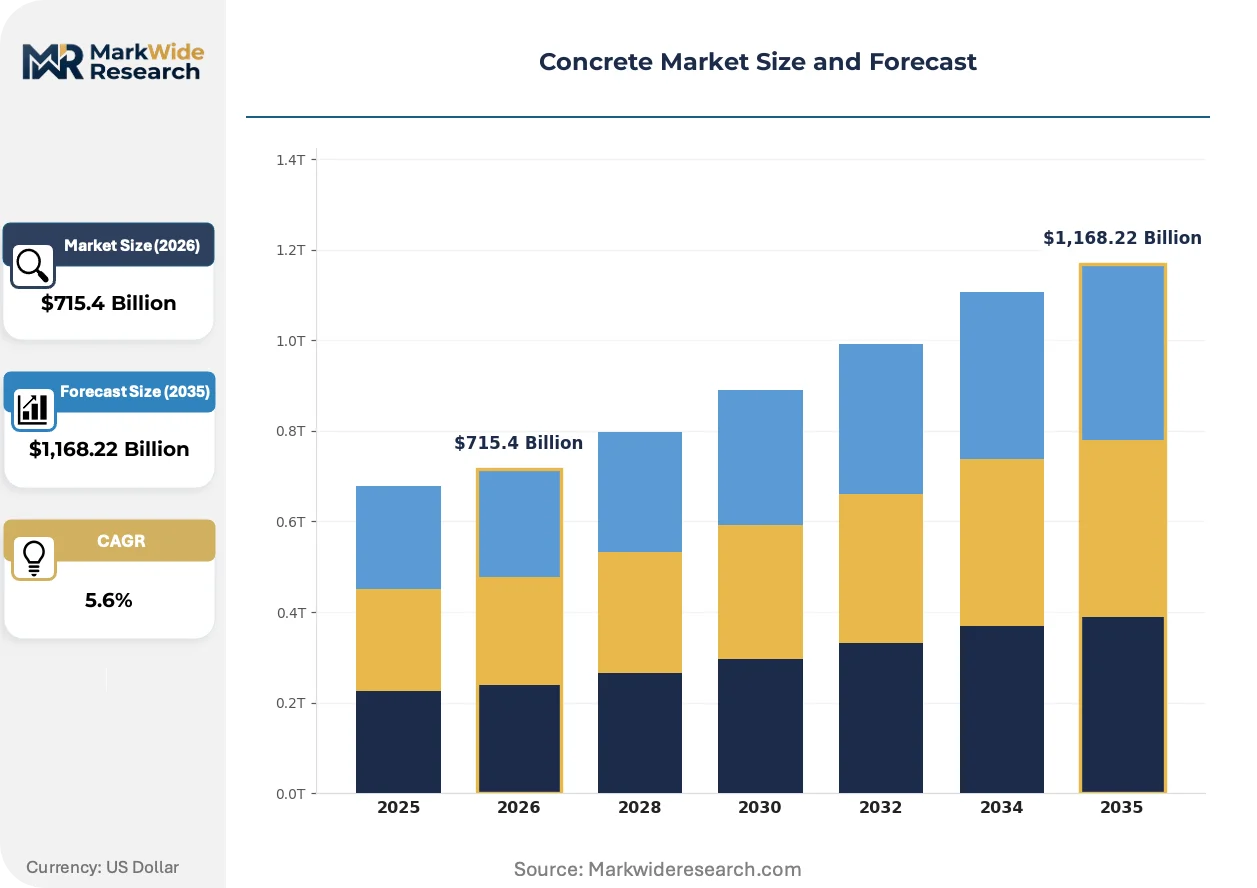
| Market Size in 2026 | $715.4 Billion |
| Market Size in 2035 | $1,168.22 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Ready-Mix Concrete, Precast Concrete, Ultra-High Performance Concrete Application: Building, Road Construction, Infrastructure, Agricultural End User: Contractors, Developers, Government, Residential Builders Distribution Channel: Direct Sales, Retail, Distributors, Online Sales |
| Companies Covered | CRH plc, TAS Concrete Construction, Baker Concrete Construction, Lithko Contracting, Kent Companies, Holcim Group, Heidelberg Materials, Concrete Strategies, CEMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Market Strategic Shifts & Innovations
Digital fleet routing and real-time slump monitoring are compressing ready-mix dispatch windows, while carbon-accounting software penetrates specification workflows as a non-negotiable tender requirement.
Carbonated concrete curing is rendering obsolete conventional steam-curing protocols in precast yards. Infrastructure contractors in Germany and the Netherlands are specifying carbon-negative surface layers for bridge decks and tunnel linings. This technology is rendering obsolete the carbon-intensity benchmarks that previously governed green procurement scoring.
The EU Green Deal's carbon-border adjustment mechanisms are tightening permissible CO₂ per ton of cementitious product. European producers must now document lifecycle emissions across Scope 1, 2, and 3 categories to maintain import access. Ready-mix segments in France and Belgium are responding with clinker-substitution rates exceeding fifty percent in certified low-carbon product lines.
Specification-grade buyers are consolidating procurement around producers with verified environmental product declarations and just-in-time delivery track records. Commodity spot purchasing is yielding to multi-year framework agreements that embed technical support and carbon-accounting transparency. India's National Capital Region exhibits this pattern most acutely, where metro rail and smart-city authorities pre-qualify batch-plant operators based on integrated digital traceability systems.
Concrete Market Segmentation
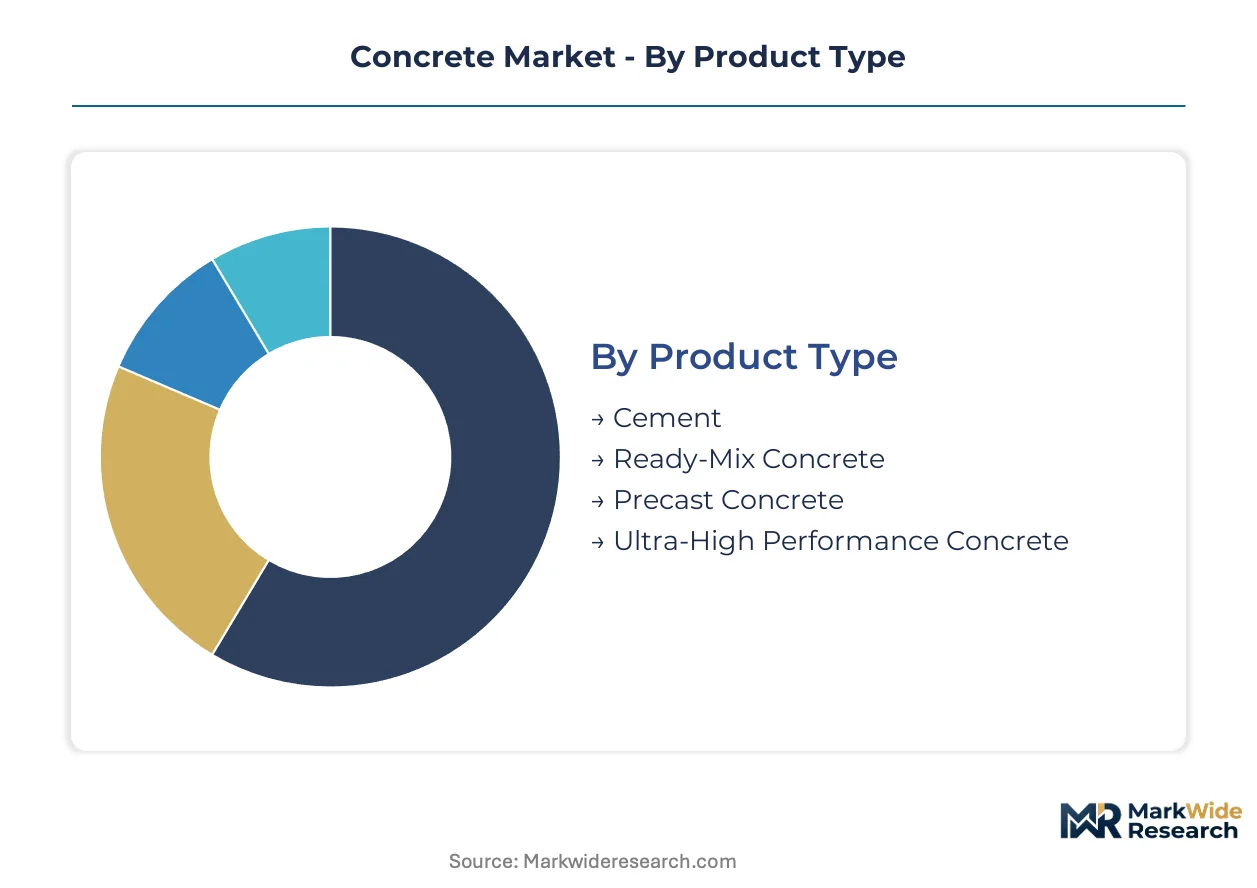
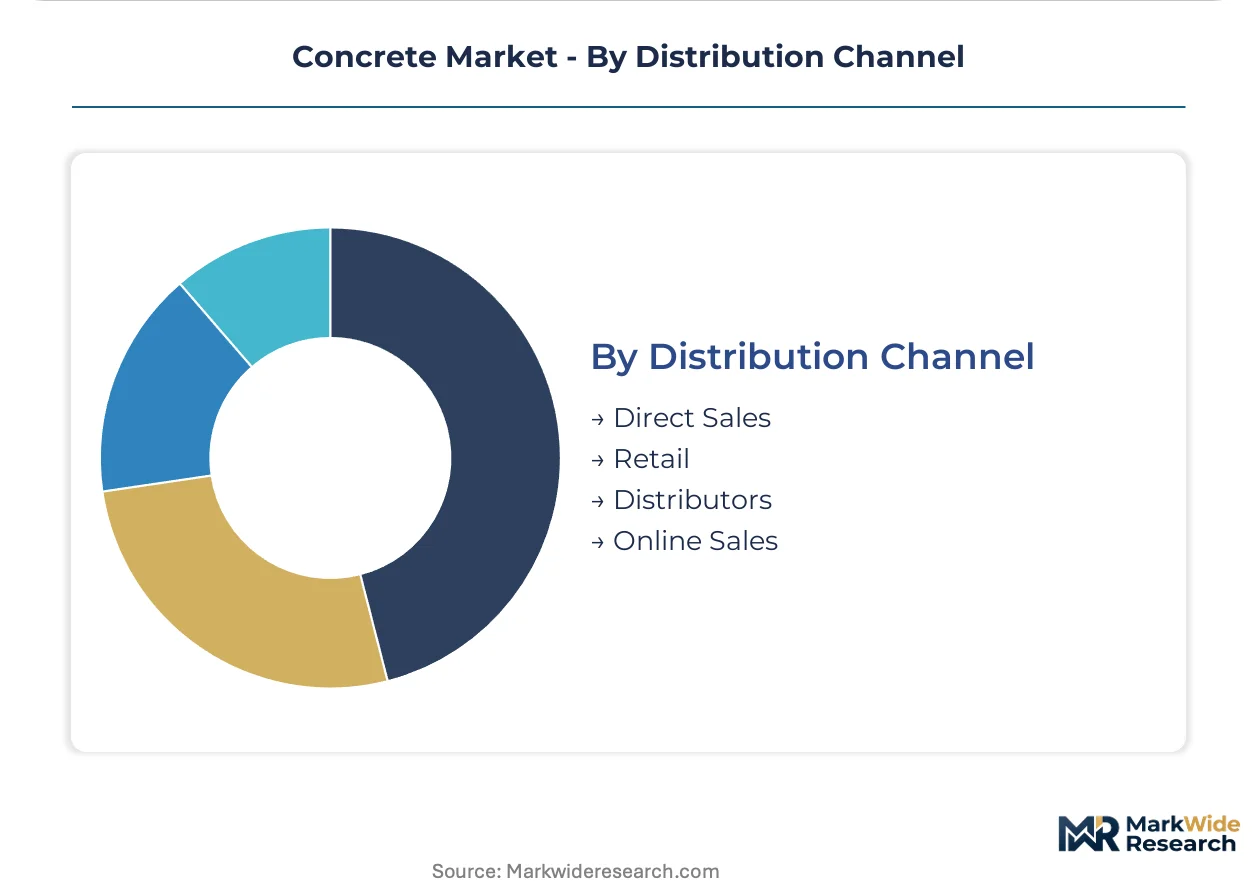
Concrete market segmentation reveals distinct margin profiles and procurement patterns across product formulations and delivery channels. Understanding these divisions exposes where capital is concentrating and which specifications command pricing power.
Product Type:
Use-case spectrum spans commodity-grade bulk pours to engineered formulations demanding specialized batch-plant capabilities and technical certification.
- Ready-Mix Concrete:Factory-blended at batch plants near urban job sites with slump-controlled workability and just-in-time delivery logistics. Demand concentrates in India's National Capital Region metro rail corridors and Southeast Asian residential tower clusters where pour-site reliability outweighs per-ton premiums.
- Cement:The foundational binder comprising Portland clinker and supplementary cementitious materials, subject to EU Green Deal embodied carbon thresholds and BIS grade certifications in Indian government tenders. Kiln capacity concentration in China and India exposes importers to freight volatility and currency fluctuation risk.
- Precast Concrete:Factory-cast elements curing under controlled conditions before transport to construction sites.
- Ultra-High Performance Concrete:Fiber-reinforced formulations achieving compressive strengths exceeding 150 MPa for bridge deck repairs and seismic retrofits.
The dominant share belongs to Ready-Mix Concrete, while Precast Concrete is closing the gap fastest.
Application:
Volume distribution tracks infrastructure investment cycles and regulatory enforcement intensity across metropolitan zones and agricultural hinterlands.
- Infrastructure:Metro rail, smart-city utilities, and transit nodes absorbing bulk cementitious volumes with mandatory grade certifications and carbon-accounting transparency. India's Bureau of Indian Standards enforcement and EU Green Deal procurement rules reshape competitive access.
- Building:Vertical construction spanning residential towers and commercial complexes where specification-grade procurement is scaling in Southeast Asian urbanization corridors.
- Road Construction:Pavement and highway segments requiring high-volume, lower-specification pours with compressed margin profiles.
- Agricultural:Silos, irrigation structures, and farm buildings with seasonal demand patterns and distributed geography.
Infrastructure commands the largest volume commitment, though Building applications are expanding most quickly.
End User:
Procurement sophistication varies sharply between public tender compliance requirements and private developer speed-to-market priorities.
- Government:Public works departments and infrastructure authorities mandating BIS certifications, environmental product declarations, and integrated digital traceability systems. EU member states add carbon-border adjustment documentation and EU taxonomy alignment.
- Contractors:Pour-site operators valuing logistics reliability and technical support over commodity tonnage alone.
- Developers:Private project sponsors migrating volume to off-site precast fabrication to compress schedules and reduce labor exposure.
- Residential Builders:Smaller-scale purchasers scaling specification-grade procurement as urbanization accelerates in Southeast Asian metropolitan zones.
Government tenders anchor volume stability, while Developers are gaining share fastest through precast migration.
Distribution Channel:
Channel selection reflects shipment scale, urgency tolerance, and technical support requirements across project types.
- Direct Sales:Producer-to-contractor relationships for large infrastructure frameworks embedding multi-year technical support and carbon-accounting transparency. Holcim Group and Heidelberg Materials leverage global batch-plant networks for just-in-time delivery contracts.
- Distributors:Regional intermediaries aggregating smaller contractor demand and managing inventory for rural and secondary market access.
- Retail:Bagged cement and small-batch ready-mix for residential repair and minor construction.
- Online Sales:Digital platforms for specification comparison and order placement, currently marginal in concrete's logistics-intensive delivery model.
Direct Sales retains the dominant position, though Distributors are climbing the fastest as secondary market penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's National Capital Region exhibit the lowest price elasticity, absorbing specification-grade premiums for metro rail and smart-city tenders, while Southeast Asian residential builders remain highly sensitive to per-ton fluctuations amid volatile clinker import costs.
United States
EPA emissions standards are compressing margins for conventional Portland cement producers across Texas and California infrastructure corridors. The Inflation Reduction Act's clean manufacturing tax credits are redirecting capital toward carbon capture retrofitting at kiln facilities in the Mountain West. Houston's petrochemical cluster is emerging as a testbed for geopolymer binder formulations using industrial waste streams.
Germany
The EU Green Deal's carbon-border adjustment mechanisms are forcing clinker-substitution rates above fifty percent in ready-mix product lines across the Rhine-Ruhr industrial belt. REACH compliance documentation and EU taxonomy alignment now gate access to federal infrastructure tenders. Bavaria's precast fabrication yards are pioneering carbonated concrete curing protocols that eliminate steam-curing emissions.
India
Bureau of Indian Standards grade certifications are mandatory for all government infrastructure procurement, creating premium positioning for accredited batch-plant operators in Maharashtra and Gujarat. The National Capital Region's metro rail authority pre-qualifies suppliers based on integrated digital traceability systems. Tamil Nadu's smart-city projects are scaling specification-grade concrete volumes faster than any other sub-region.
China
Dual carbon goals and MIIT industrial efficiency mandates are accelerating kiln capacity consolidation in Shandong and Jiangsu provinces. GB standards enforcement is tightening permissible CO₂ per ton of cementitious product in the Yangtze River Delta. The Pearl River Delta's urban rail expansion is absorbing bulk cementitious volumes with minimal price sensitivity.
United Arab Emirates
MOHAP and municipal building codes are embedding embodied carbon thresholds into Dubai and Abu Dhabi megaproject specifications. Low-clinker concrete with verified environmental product declarations commands preferential access to government developer frameworks. The Emirates' precast fabrication sector is migrating volume to off-site production to compress project schedules and reduce labor exposure.
Concrete Market Key Industry Players
Vertically integrated multinational cement producers and regional batch-plant operators split the market between scale-driven commodity flows and specification-grade service contracts. The vendor base concentrates around three strategic archetypes: global kiln-and-network players with carbon-capture R&D pipelines, metropolitan logistics specialists competing on just-in-time delivery windows, and precast fabricators capturing margin through off-site quality control. Dominant competitive moves include clinker-substitution R&D partnerships and batch-plant network expansion into secondary urban corridors.
Among global kiln-and-network players, Holcim Group, Heidelberg Materials, and CEMEX occupy positions that exemplify divergent strategic vectors. Holcim Group represents the metropolitan logistics archetype through its batch-plant proximity to dense urban job sites. Heidelberg Materials anchors the European low-carbon transition through its clinker-substitution research positioning. CEMEX exemplifies digital integration across dispatch and fleet routing functions. Regional contractors including CRH plc, Baker Concrete Construction, and Lithko Contracting sit within the specification-grade service tier, competing on pour-site technical support rather than commodity tonnage alone.
| Leading Market Players |
|---|
| CRH plc |
| TAS Concrete Construction |
| Baker Concrete Construction |
| Lithko Contracting |
| Kent Companies |
| Holcim Group |
| Heidelberg Materials |
| Concrete Strategies |
| CEMEX |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Shandong and Jiangsu kiln clusters is compressing clinker export pricing while forcing Southeast Asian importers into longer-term offtake contracts to secure volume certainty. This utilization dynamic rewards integrated producers with captive limestone reserves and punishes merchant traders exposed to freight volatility and currency fluctuation.
Pricing Analysis
Aftermarket service revenue from pour-site technical support and just-in-time delivery contracts now drives lifetime value more than commodity tonnage. Three-tier pricing structure across specification-grade, certified-standard, and bulk-economy levels separates government infrastructure tenders from residential spot purchases. Cost compression in bulk ready-mix is intensifying because clinker-substitution R&D has narrowed performance gaps between conventional and low-carbon formulations. Government buyers in India's National Capital Region exhibit the lowest price sensitivity, absorbing premiums for BIS-certified grades, while Southeast Asian residential builders remain highly elastic to per-ton fluctuations.
Supply Chain Analysis
Tariff exposure between China and key import markets dominates supply chain risk planning for merchant clinker traders. Kiln capacity concentrates in China, India, and Vietnam, drawing from limestone deposits, petroleum coke fuel, and supplementary cementitious material feedstocks. Single-source vulnerability persists for European importers dependent on Yangtze River Delta clinker flows subject to carbon-border adjustment documentation requirements. Distribution runs through producer-direct framework agreements for infrastructure volumes and regional distributor networks for secondary market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Concrete market fragmentation is accelerating as EU Green Deal procurement rules and BIS certification mandates create specialized niches for low-carbon formulation expertise and digital traceability capabilities.
For Market Incumbents: Harden defensive positioning through backward integration into supplementary cementitious material sources and carbon capture retrofitting at kiln facilities. Clinker-substitution R&D partnerships with industrial waste-stream suppliers represent the priority capability investment. Batch-plant network expansion into India's secondary urban corridors protects against price erosion in saturated metropolitan zones.
For New Entrants and Emerging Players: Pursue white-space opportunities in geopolymer binder formulation for precast applications where curing time flexibility permits alternative chemistry. India's Tamil Nadu smart-city corridor offers the most penetrable geography for accredited new operators. A go-to-market angle anchored to verified environmental product declarations and integrated digital traceability systems unlocks government tender access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among metropolitan logistics specialists with multi-year just-in-time delivery contracts embedding technical support. Long-term viability over the next decade favors acquisition targets with clinker-substitution R&D pipelines and EU taxonomy alignment documentation. Watch for inflection signals in carbon-accounting software penetration across specification workflows.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinker-Substitution R&D Partnership | EU Green Deal thresholds favor low-carbon formulations with verified environmental product declarations. |
| Carbon Capture Retrofitting | Post-combustion amine scrubbing qualifies producers for green procurement tenders under EU taxonomy. |
| Batch-Plant Network Expansion | Proximity to India's National Capital Region metro corridors secures just-in-time delivery contracts. |
| Digital Traceability System Integration | BIS certification and smart-city pre-qualification requirements mandate integrated tracking platforms. |
| Off-Site Precast Fabrication Capacity | Government and developer migration to factory-cast elements compresses project schedules and labor exposure. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with batch-plant operators, infrastructure procurement officers, and technical R&D directors; and secondary validation through customs/trade data, SEC filings of listed producers, Bureau of Indian Standards certification databases, and EU environmental product declaration registries. Bottom-up volume modeling across product types and applications triangulated against top-down macro construction spending indicators.
Forecast inputs span ready-mix, precast, and ultra-high performance formulations across infrastructure, building, and road construction applications, with end-user segmentation by government, contractor, developer, and residential builder archetypes. CAGRs were derived from regression analysis of historical volume-price relationships and projected regulatory enforcement intensity. Industry-specific inputs include clinker-substitution rate trajectories and carbon-border adjustment mechanism implementation schedules.
Sensitivities concentrate around EU Green Deal threshold revisions, BIS certification mandate expansion, and geopolymer binder commercialization timelines. Forecasts reflect documented assumptions on regulatory enforcement consistency and construction investment cycle continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United States Architectural Coatings Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Germany Architectural Coatings Market
Building Materials
India Concealed Cistern Market
Building Materials
Qatar Cement Market
Building Materials
Building and Construction Sheets Market
Building Materials
Europe Cement Market
Building Materials
France Architectural Coatings Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
US Facade Market
Building Materials
Block Paving Market
Building Materials
Long Steel Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Natural Stone Slab Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market