
 Mechanical Auger Boring Machine Market | 2026-2036
Mechanical Auger Boring Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Auger Boring Machine Market Insights
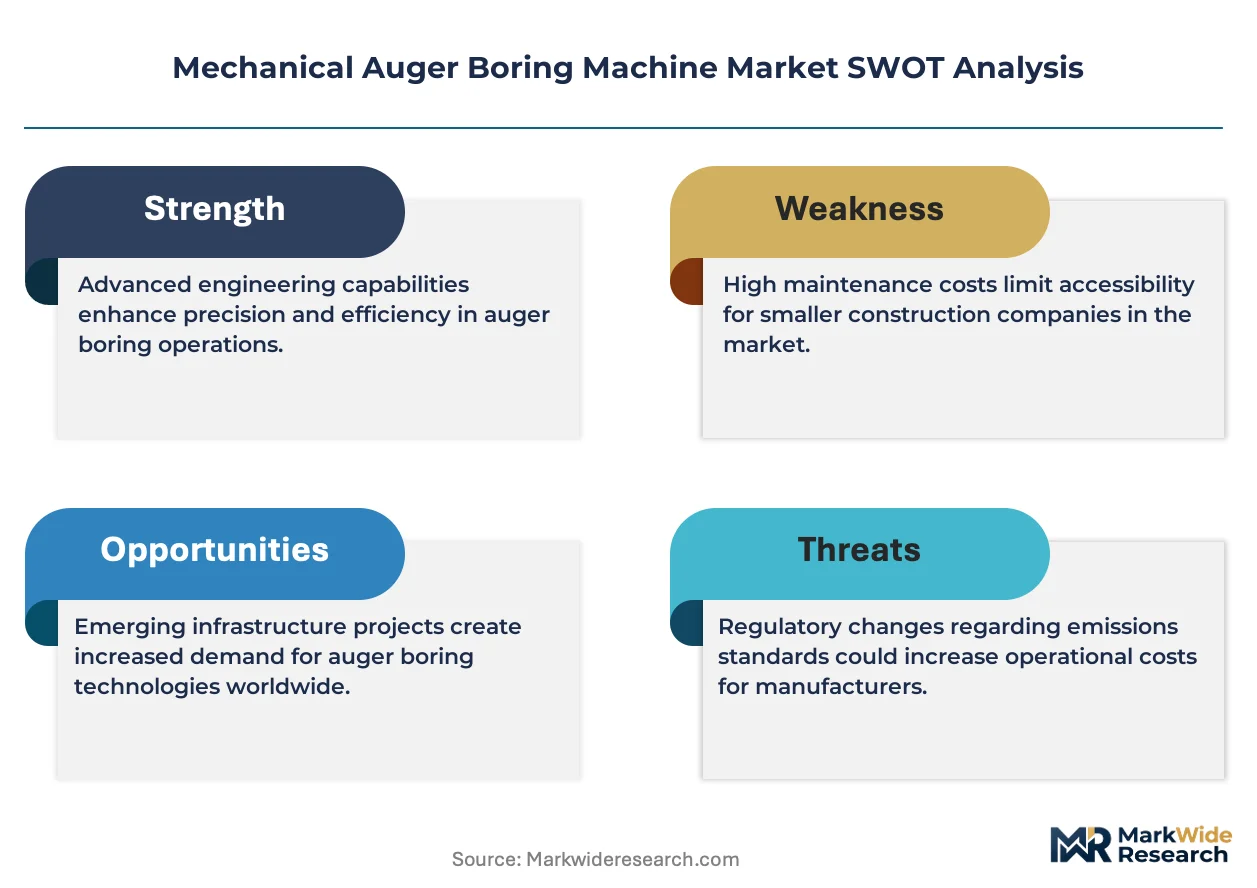
North American utility infrastructure renewal is reshaping competitive dynamics for auger boring equipment. Bauer Maschinen GmbH leverages its German engineering heritage to dominate high-torque hydraulic system design. Vermeer Corporation anchors its position through an extensive dealer network spanning Midwestern states. The Robbins Company specializes in custom-built machines for hard-rock conditions, differentiating its portfolio from standard utility-grade offerings.
A mechanical auger boring machine is a trenchless excavation device that employs a helical screw blade to remove soil while advancing a casing pipe through the ground, typically achieving diameters from 100 mm to 1,500 mm with torque ratings exceeding 500,000 Nm in heavy-duty configurations. Its primary purpose is installing underground utilities without surface disruption in urban environments where open-cut excavation proves impractical or prohibited. Hydraulic machine types command the largest installed base due to their superior power-to-weight ratios in continuous-duty municipal contracts. Horizontal directional drilling technology leads technology adoption among gas transmission applications, while pipe jacking maintains structural importance in deep sewer installations where line and grade precision matters most.
EPA enforcement of the Lead and Copper Rule revisions directly shapes equipment demand timelines for water pipeline contractors across the United States. OSHA excavation safety standards and state-level one-call regulations collectively determine operational compliance costs and training requirements for construction contractors deploying these machines. Stakeholders must monitor how federal infrastructure funding allocation rhythms interact with manufacturer order backlogs to time capital deployment decisions effectively.
Market Dynamics
EPA enforcement of lead service line replacement mandates is compressing municipal procurement cycles and forcing contractors to prioritize trenchless installation speed over equipment versatility, fundamentally restructuring how boring machine fleets are specified and deployed.
Growth Catalysts
- Lead and Copper Rule Revisions:EPA mandates across the United States are accelerating water infrastructure replacement timelines, forcing municipal contractors to expand trenchless equipment fleets to meet compliance deadlines without surface disruption.
- Combined Sewer Overflow Remediation:Aging infrastructure in the American Midwest requires systematic rehabilitation, concentrating demand for auger boring systems capable of precise line-and-grade installation in dense urban corridors.
- Torque Density Improvements:Hydraulic system advances enabling 500,000+ Nm output in compact footprints are allowing contractors to tackle previously inaccessible soil conditions with smaller crew sizes and reduced mobilization costs.
Market Restraints
- Steel Alloy Price Volatility:Casing pipe and cutting tool feedstock costs fluctuate with commodity markets, compressing project margins for contractors locked into fixed-bid municipal contracts with limited escalation clauses.
- Specialized Component Concentration:High-pressure hydraulic pump assemblies and precision gearboxes rely on concentrated supply from German and Japanese manufacturing clusters, exposing fleet operators to extended lead times during supply disruptions.
- Horizontal Directional Drilling Substitution:HDD technology continues capturing share in gas transmission applications where steering flexibility outweighs the structural advantages of cased auger installation.
Strategic Opportunities
- Smart City Underground Conduit:Fiber-optic and electric vehicle charging backhaul requirements in mid-sized American municipalities are creating new application segments beyond traditional water and sewer markets.
- Bipartisan Infrastructure Law Flow-Through:Federal funding allocation mechanisms are creating sustained multi-year procurement visibility that equipment financiers can underwrite with greater confidence than historical municipal budgeting cycles permitted.
- Telematics-Enabled Fleet Management:Integration of real-time torque monitoring and predictive maintenance algorithms is virtualizing traditional equipment specification processes, allowing rental and lease channels to penetrate contractor fleets previously committed to ownership.
Industry Challenges
- Certified Operator Scarcity:OSHA excavation safety standards and state one-call compliance requirements demand specialized training that outpaces vocational program output, constraining fleet utilization rates even where equipment is available.
- Legacy System Integration:Municipal asset management databases rarely interface with modern boring machine telemetry, forcing contractors to maintain parallel documentation systems that increase administrative overhead and error rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Auger Boring Machine Market |
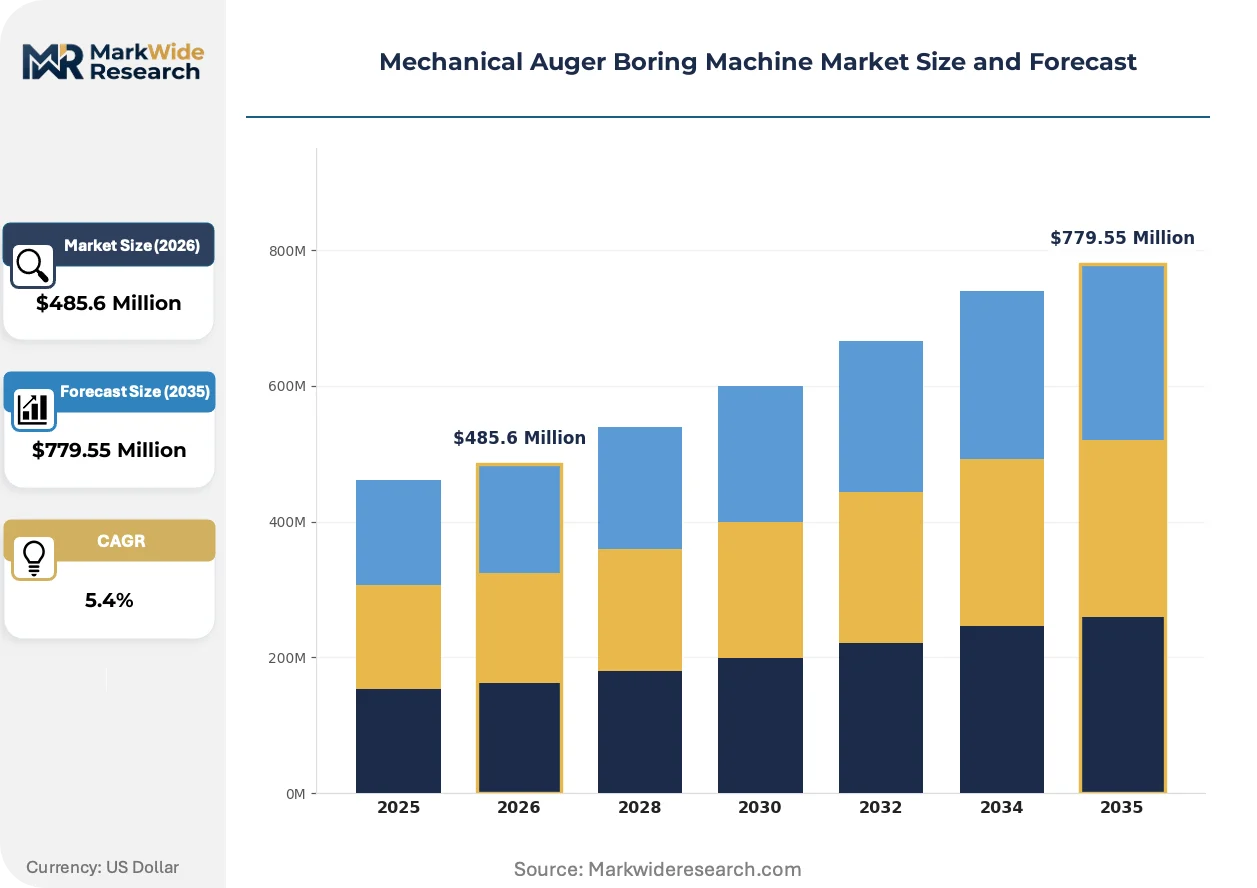
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $779.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Hydraulic, Pneumatic, Electric, Diesel Technology: Horizontal Directional Drilling, Microtunneling, Pipe Jacking, Impact Moling Application: Water Pipeline Installation, Gas Transmission, Telecommunication Conduits, Sewage Systems End User: Construction Contractors, Utility Operators, Municipal Corporations, Engineering Firms |
| Companies Covered | The Robbins Company, Bauer Maschinen GmbH, Soilmec, XCMG, Barbco Inc., Vermeer Corporation, Ditch Witch, Casagrande, Michael Byrne Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Auger Boring Machine Market Trends and Innovations
Digital instrumentation and predictive analytics are virtualizing equipment performance optimization, while regulatory pressure and procurement model evolution are simultaneously reshaping how contractors acquire and deploy trenchless installation assets.
Downhole sensor arrays combined with machine learning torque signature analysis are virtualizing traditional geotechnical investigation workflows. Midwestern municipal contractors deploying these systems report reduced pilot bore failure rates and faster soil condition adaptation. The technology is compressing project timelines by enabling real-time cutter head adjustment without surface excavation verification.
EPA enforcement timelines for lead service line replacement are hardening municipal procurement specifications toward continuous-duty hydraulic configurations with documented mean-time-between-failure metrics. Contractors responding to these requirements are prioritizing equipment with modular hydraulic circuits that permit field serviceability over integrated designs with superior theoretical efficiency. Water pipeline specialists in Michigan and Illinois report specification rejections for machines lacking telematics-enabled maintenance logging.
Rental channel penetration is accelerating among regional contractors seeking to align fleet capacity with episodic federal funding waves rather than maintaining owned equipment through demand troughs. Equipment lessors in Ohio and Indiana are expanding auger boring inventories specifically configured for EPA-mandated lead line replacement diameters. The shift is compressing traditional manufacturer-dealer-direct sales cycles and forcing OEMs to develop asset residual value forecasting capabilities previously unnecessary in their commercial models.
Mechanical Auger Boring Machine Market Segmentation
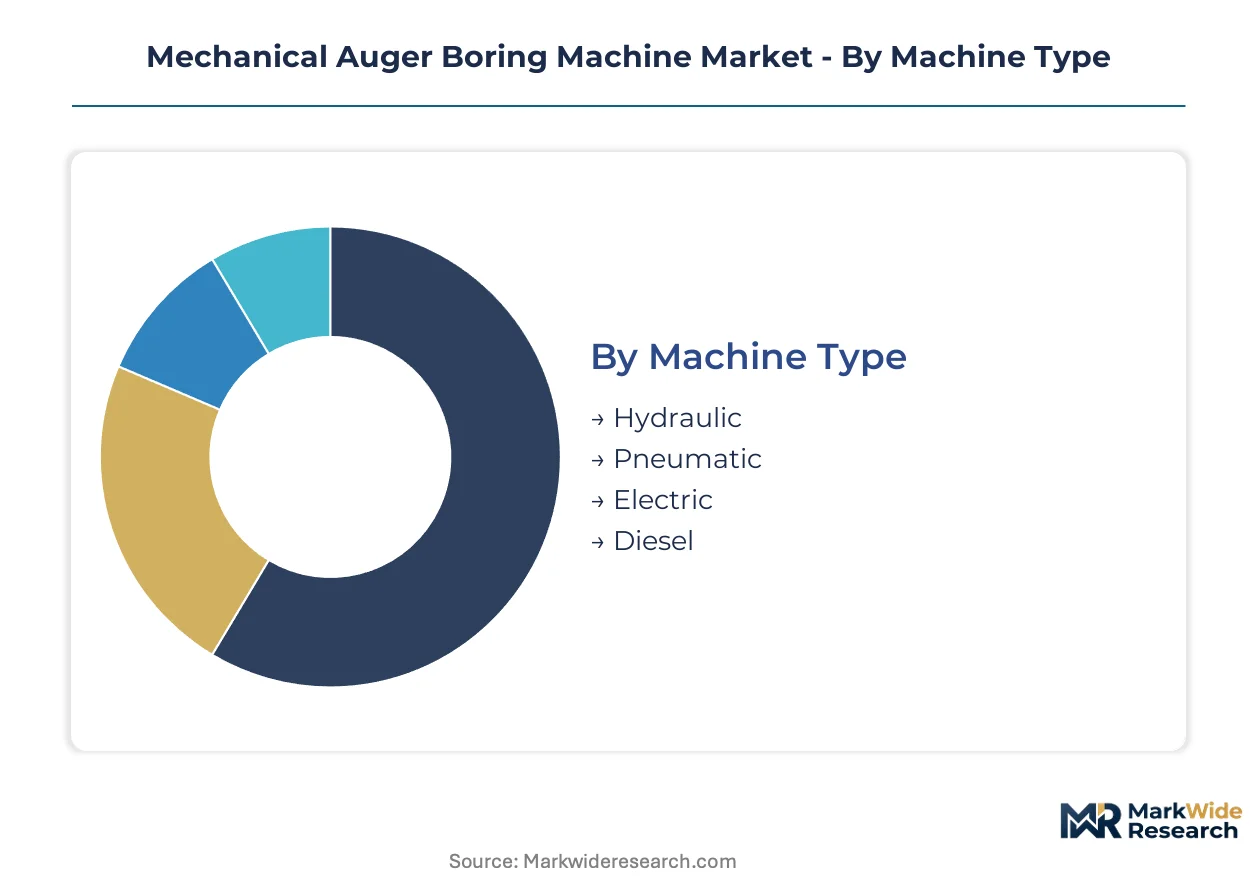
Mechanical auger boring equipment serves divergent operational requirements across torque density, mobility constraints, and underground precision demands. Segment-specific procurement patterns reflect how municipal contractors balance EPA compliance deadlines against soil condition variability and crew certification availability.
Machine Type:
The use-case spectrum spans continuous-duty municipal contracts requiring sustained hydraulic output through compact electric units suited for noise-restricted urban corridors.
- Hydraulic:These systems deploy high-pressure pump assemblies generating torque outputs exceeding 500,000 Nm in heavy-duty configurations. Demand concentrates in Michigan and Illinois water pipeline replacement contracts where EPA Lead and Copper Rule enforcement mandates continuous-duty reliability with documented mean-time-between-failure metrics.
- Diesel:Self-contained power units eliminate external generator dependencies for remote site mobilization. Adoption accelerates in Ohio and Indiana where federal funding waves create episodic demand spikes that rental fleet operators must service without grid infrastructure.
- Pneumatic:Compressed-air systems serve specialized applications in volatile gas environments where ignition risk constrains internal combustion alternatives.
- Electric:Battery and grid-tethered configurations address urban noise ordinances and emissions restrictions in dense metropolitan construction zones.
Established volume favors hydraulic configurations; emerging adoption favors electric systems as municipal sustainability procurement criteria harden.
Technology:
Cost tier differentiation separates precision-grade line-and-grade systems from steerable alternatives optimized for geological adaptability.
- Pipe Jacking:This method advances precast concrete or steel casing through reaction against a jacking pit structure, maintaining millimeter-grade elevation control across extended drives. Demand clusters in Chicago and Cleveland combined sewer overflow remediation where aging brick interceptors require systematic rehabilitation without surface disruption.
- Horizontal Directional Drilling:Steerable drill heads with mud motor assemblies enable curved trajectories beneath obstacles. Gas transmission contractors in Pennsylvania and Texas favor this flexibility for river crossings and existing utility avoidance despite cased auger's structural advantages.
- Microtunneling:Remote-controlled slurry systems with laser guidance serve gravity sewer applications demanding absolute precision at diameters below 1,000 mm.
- Impact Moling:Pneumatic percussive tools displace soil without spoil removal for small-diameter conduit placement across soft ground conditions.
Precision-critical applications favor pipe jacking; route-flexibility requirements favor horizontal directional drilling.
Application:
Customer type concentration varies by infrastructure asset class and regulatory enforcement timeline intensity.
- Water Pipeline Installation:Lead service line replacement mandates across EPA-designated priority municipalities drive specification standardization toward telematics-enabled hydraulic machines with maintenance logging capabilities. Procurement timelines compress as compliance deadlines approach.
- Sewage Systems:Combined sewer overflow consent decree requirements in Midwestern legacy cities sustain demand for precise line-and-grade installation in dense corridors with shallow bedrock.
- Gas Transmission:FERC-regulated pipeline integrity management programs favor horizontal directional drilling for mainline construction where steering flexibility outweighs cased installation economics.
- Telecommunication Conduits:Fiber-optic backhaul and electric vehicle charging infrastructure create emerging demand segments in mid-sized municipalities beyond traditional utility markets.
Regulatory enforcement intensity favors water pipeline installation; infrastructure modernization cycles favor sewage system applications.
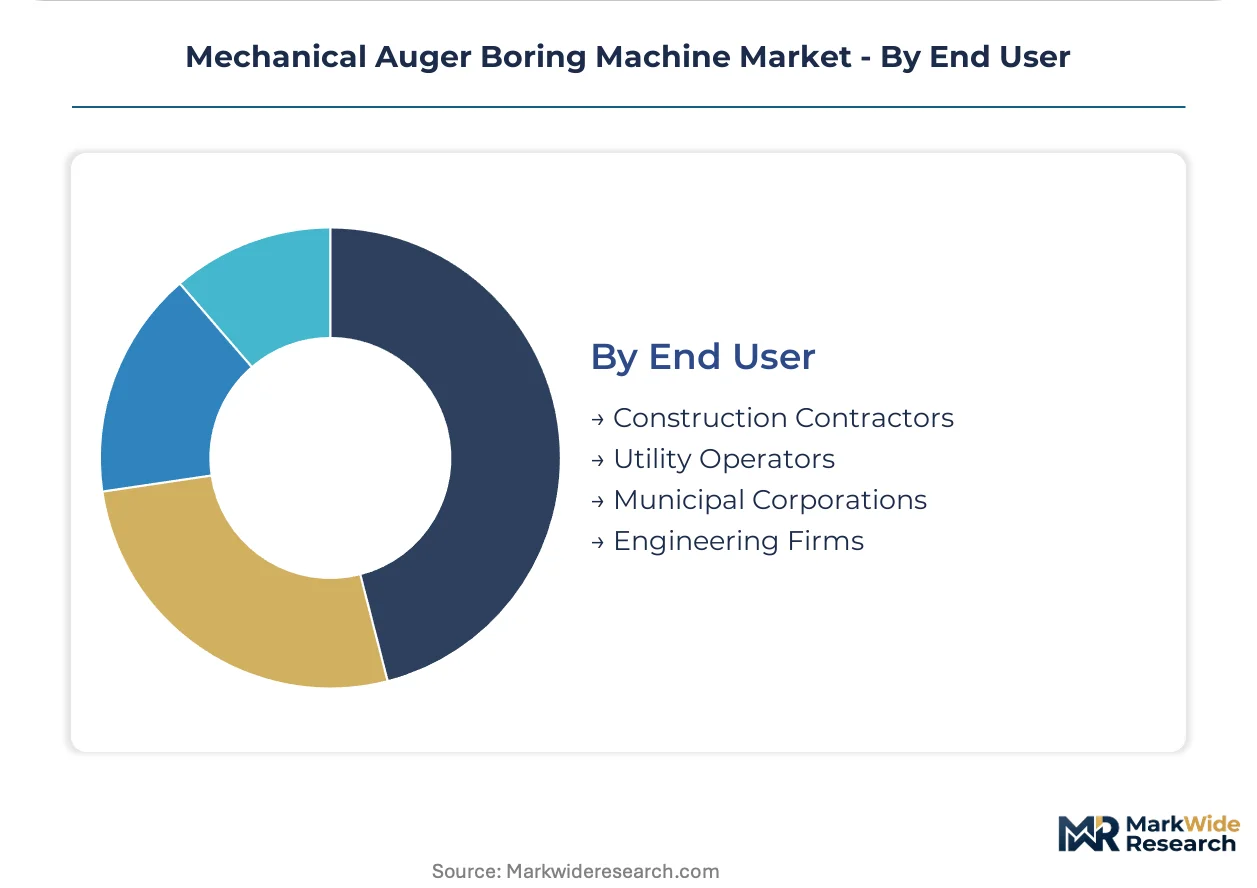
End User:
Volume scale and margin structure diverge between fleet-owning contractors and asset-light municipal procurement entities.
- Construction Contractors:Regional trenchless specialists in Ohio, Indiana, and Michigan maintain owned or leased equipment fleets scaled to federal funding wave timing. OSHA excavation safety certification requirements and state one-call compliance training constrain operator availability even where capital equipment is accessible.
- Municipal Corporations:Direct equipment ownership concentrates in larger cities with internal public works departments capable of maintaining specialized maintenance capabilities.
- Utility Operators:Water and gas distribution entities prioritize equipment standardization across multi-state service territories to simplify parts logistics and technician training.
- Engineering Firms:Design-build contractors deploy project-specific equipment configurations aligned with geotechnical risk profiles rather than maintaining permanent fleets.
Procurement flexibility favors construction contractors; standardization economics favor utility operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature infrastructure markets prioritizing regulatory compliance and emerging economies expanding utility networks from lower baselines. Equipment specification standards reflect these divergent priorities.
United States
EPA Lead and Copper Rule enforcement compresses municipal procurement cycles for water pipeline replacement across Michigan, Illinois, and Ohio. Federal Bipartisan Infrastructure Law funding creates sustained multi-year demand visibility for trenchless contractors. Chicago and Cleveland combined sewer overflow remediation concentrates demand for precise line-and-grade installation systems.
Germany
High-torque hydraulic engineering heritage supports specialized component manufacturing clusters supplying global OEMs. REACH chemical compliance and machinery safety directives shape equipment export specifications. Baden-Württemberg precision gearbox manufacturers face extended order backlogs from international utility infrastructure programs.
China
Urban rail transit expansion and utility corridor densification drive adoption of compact electric boring configurations in noise-restricted metropolitan zones. GB standards for construction machinery safety and MIIT industrial equipment certification govern domestic procurement. Yangtze River Delta municipal contractors deploy trenchless methods for subway utility relocation projects.
India
Smart Cities Mission underground conduit requirements create emerging demand beyond traditional water and sewer applications. BIS certification mandates and CEA electrical safety standards regulate equipment import and deployment. Maharashtra and Gujarat infrastructure contractors expand trenchless fleet capacity for metro utility corridor construction.
Japan
Aging water infrastructure replacement and seismic resilience upgrades sustain specialized microtunneling equipment demand. METI energy efficiency standards and JIS construction machinery specifications influence equipment design priorities. Tokyo and Osaka metropolitan contractors prioritize compact electric systems for dense urban corridor work.
Mechanical Auger Boring Machine Market Competitive Landscape
Capability concentration sits with German and Japanese engineering specialists; scale advantage sits with diversified construction equipment conglomerates. The vendor base organizes around three strategic archetypes: precision component specialists, integrated trenchless solution providers, and regional fabrication houses serving price-sensitive procurement. Dominant competitive moves include technology licensing partnerships for torque density improvements and geographic expansion through distributor network consolidation.
Among German engineering specialists, Bauer Maschinen GmbH exemplifies the high-torque hydraulic system archetype, while The Robbins Company occupies a position within custom hard-rock machine fabrication. Vermeer Corporation anchors the integrated solution provider tier with extensive Midwestern dealer coverage. These three represent divergent strategic postures within a market segmenting between premium specification compliance and fleet standardization economics.
| Leading Market Players |
|---|
| The Robbins Company |
| Bauer Maschinen GmbH |
| Soilmec |
| XCMG |
| Barbco Inc. |
| Vermeer Corporation |
| Ditch Witch |
| Casagrande |
| Michael Byrne Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Extended order backlogs at Baden-Württemberg precision gearbox manufacturers signal undercapacity in critical hydraulic component supply, compelling OEMs to accept longer lead times and prioritize contract security over unit cost negotiation in fleet procurement cycles.
Pricing Analysis
Long-term offtake agreements dominate municipal contractor procurement as EPA compliance deadlines compress equipment availability windows. Three-tier pricing structure across premium, standard, and economy levels differentiates machines by telematics capability and documented mean-time-between-failure metrics. Cost compression in mid-tier hydraulic configurations is intensifying because steel alloy feedstock volatility erodes fixed-bid project margins. Regional rental fleet operators in Ohio and Indiana exhibit highest price sensitivity, while utility operators with multi-state standardization programs prioritize specification compliance over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for high-pressure hydraulic pump assemblies. Manufacturing concentration in Germany, Japan, and China feeds global OEM demand for precision gearboxes and cutting tool alloys. Raw material dependencies on specialty steel alloys, high-pressure seals, and electronic sensor arrays create vulnerability to commodity price swings. Distribution runs through manufacturer-authorized dealer networks with regional service capabilities, though rental channel expansion is compressing traditional sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified operator scarcity constrains fleet utilization rates even where capital equipment is physically available, creating a bottleneck that favors stakeholders who can secure training pipeline access or automate crew requirements through telematics-enabled machines.
For Market Incumbents: Insulate position by deepening backward integration into hydraulic component supply and expanding certified technician training partnerships with Midwestern vocational programs. Horizontal directional drilling substitution in gas transmission applications threatens auger boring volume in that segment; counter by emphasizing cased installation structural advantages in water pipeline specifications where EPA mandates enforce line-and-grade precision. For New Entrants and Emerging Players: Establish a beachhead in electric compact boring configurations for noise-restricted urban corridors where municipal sustainability procurement criteria are hardening. Fiber-optic and electric vehicle charging backhaul applications in mid-sized American municipalities represent the most penetrable white space beyond traditional water and sewer markets. Partner with equipment lessors to bypass capital-intensive dealer network buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-enabled fleet management platforms that virtualize traditional equipment specification processes. Long-term viability over the projection horizon rests on acquisition targets with modular hydraulic circuit designs permitting field serviceability. Watch for inflection signals in federal infrastructure funding allocation rhythms that precede manufacturer order backlog expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time torque monitoring compresses project timelines for Michigan and Illinois contractors facing EPA deadlines. |
| Backward Integration into Hydraulic Components | In-house production of high-pressure pump assemblies reduces exposure to German and Japanese supply concentration. |
| Rental Channel Expansion | Equipment lessors in Ohio and Indiana align fleet capacity with episodic federal funding waves. |
| Certified Operator Training Partnership | Vocational program linkages address OSHA excavation safety compliance constraints limiting crew availability. |
| Electric Configuration Development | Battery and grid-tethered systems satisfy municipal sustainability procurement criteria in dense metropolitan zones. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment fleet managers, municipal procurement officers, trenchless contracting executives, and aftermarket service heads; and secondary validation through SEC 10-K filings of construction equipment manufacturers, EPA enforcement action databases, federal infrastructure funding allocation records, and municipal contract award registries. Bottom-up equipment unit demand estimates triangulated against top-down market value reconstructions.
Forecast inputs include machine type segmentation by power configuration, technology differentiation by precision requirements, application clustering by regulatory enforcement intensity, and end-user categorization by fleet ownership models. CAGRs were derived through slope analysis of historical procurement patterns projected across the analysis window, with specific weighting for Bipartisan Infrastructure Law funding flow-through timing and EPA Lead and Copper Rule compliance phase schedules.
Sensitivities concentrate around steel alloy commodity price volatility, German and Japanese component supply disruptions, and federal funding reallocation rhythms. Forecasts reflect documented assumptions about municipal budgeting cycles and manufacturer capacity expansion plans. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Automatic Slack Adjusters Market