
 Solid State Lasers Market | 2026-2036
Solid State Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Lasers Market Analytics
Fiber gain media is expanding its share against traditional crystal hosts in solid state architectures, cutting thermal management costs and extending service intervals. Coherent Inc. leverages vertical integration across crystal growth and resonator assembly to control cost structures. IPG Photonics anchors high-power fiber laser production with captive diode manufacturing in the United States. Jenoptik AG specializes in precision optics and beam delivery systems for semiconductor lithography applications.
Solid state lasers employ crystalline or glass host materials doped with rare-earth ions such as neodymium or ytterbium, pumped by diode arrays or flashlamps to produce coherent output from ultraviolet through mid-infrared wavelengths, serving precision material processing and scientific instrumentation. Fiber Lasers capture the dominant value share due to superior wall-plug efficiency and maintenance profiles in metal cutting operations. Q-Switched systems lead defense rangefinding and lidar applications where short pulse energy delivers target discrimination. Ultrafast technology posts the fastest expansion as electronics manufacturers adopt femtosecond sources for transparent material micromachining of display glass and sapphire substrates.
FDA device classification rules govern medical laser systems sold in the United States, while CE marking under the EU Machinery Directive shapes product compliance for industrial equipment across European member states. ISO 11553 safety standards for laser processing machines influence design requirements and limit market access for non-compliant suppliers. Stakeholders must monitor evolving export control frameworks affecting defense-linked wavelengths and power thresholds.
Market Dynamics
Fiber gain media is displacing bulk crystal architectures across industrial cutting applications, compressing thermal management costs and extending maintenance intervals in metal fabrication clusters. This substrate transition concentrates procurement leverage among diode array suppliers with captive crystal growth capabilities.
Growth Catalysts
- EU Machinery Directive CE marking:Stricter safety compliance requirements under the directive are accelerating equipment replacement cycles in German precision manufacturing clusters.
- Dermatology surgical equipment:Aesthetic medicine clinics are upgrading to solid state systems for vascular lesion treatment and tattoo removal procedures.
- Ytterbium-doped fiber:Superior wall-plug efficiency in high-power cutting operations is driving adoption across automotive sheet metal processing lines.
Market Restraints
- Rare-earth oxide supply concentration:Neodymium and ytterbium refining capacity clusters in China's Jiangxi and Inner Mongolia regions, exposing downstream laser manufacturers to export quota volatility.
- Flashlamp replacement cost structure:Legacy crystal systems require periodic arc lamp replacement, creating lifetime cost disadvantages against diode-pumped fiber alternatives.
- ISO 11553 compliance friction:Laser processing machine safety standards impose design certification timelines that delay market entry for non-integrated suppliers lacking in-house testing facilities.
Strategic Opportunities
- India PLI scheme for capital goods:Production-linked incentive frameworks for precision manufacturing equipment create localized assembly advantages for fiber laser system integrators.
- Femtosecond micromachining:Transparent material processing of sapphire substrates and display glass is opening new revenue streams in consumer electronics supply chains.
- Defense wavelength export controls:Evolving dual-use technology frameworks are creating captive demand for domestically sourced rangefinding and lidar systems in allied nations.
Industry Challenges
- Resonator alignment technician scarcity:Precision optics assembly requires specialized cleanroom skills that outpace vocational training program output in manufacturing hubs.
- Multi-kilowatt system integration complexity:Combining fiber modules into coherent beam delivery architectures demands thermal and optical engineering capabilities that strain mid-tier system houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Lasers Market |
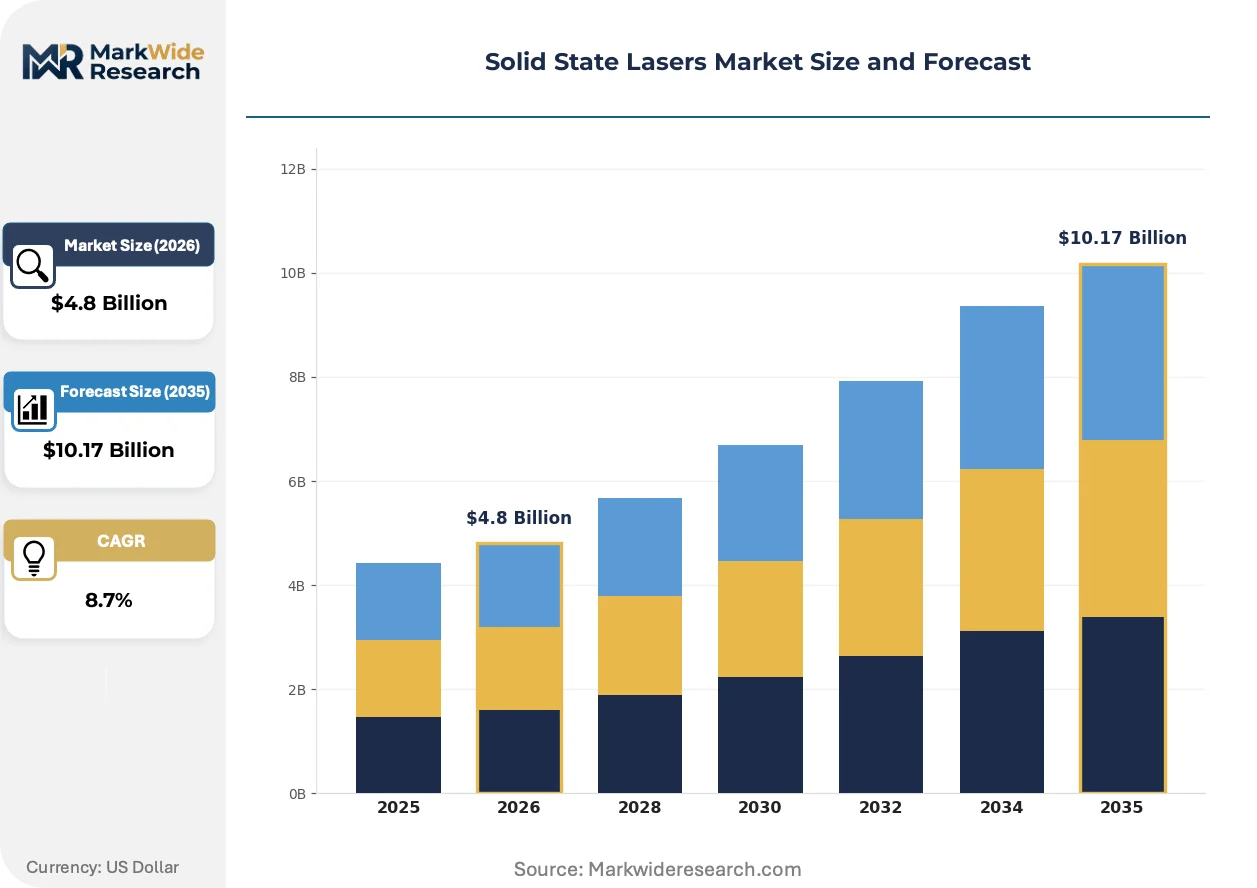
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode-Pumped Lasers, Lamp-Pumped Lasers, Fiber Lasers, Semiconductor Lasers Application: Industrial Cutting, Medical Procedures, Defense & Security, Research & Development Technology: Q-Switched, Continuous Wave, Mode-Locked, Ultrafast End User: Aerospace, Electronics, Medical, Manufacturing |
| Companies Covered | Coherent Inc., IPG Photonics, Jenoptik AG, TRUMPF, Han's Laser Technology Industry Group Co. Ltd., Lumentum Operations LLC, Hamamatsu Photonics K.K., nLIGHT Inc., CrystaLaser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Lasers Market Evolving Landscape
Active beam shaping and real-time power modulation are compressing the gap between raw laser output and application-specific process windows. Equipment suppliers are embedding sensors and control firmware that transform hardware into closed-loop manufacturing tools.
Thin-disk laser architecture is modularizing around standardized pump diode and cooling sub-assemblies. Automotive OEMs in Stuttgart and Munich are adopting these systems for battery tray welding at production scales that previously required multiple discrete machines. The technology is modularizing capital deployment by allowing end-users to scale power through additive head configurations rather than full system replacement.
REACH substance restrictions on chromium compounds used in crystal host manufacturing are forcing suppliers to qualify alternative dopant matrices. The regulation is compressing qualified supplier lists for neodymium-doped YAG boules. European lithography equipment manufacturers are accelerating qualification timelines for synthetic garnet alternatives to maintain CE marking compliance.
Service contract unbundling is separating hardware ownership from uptime guarantees in metal cutting operations. Tier-one fabricators in the Ruhr industrial region are adopting per-minute laser availability agreements that shift maintenance liability to OEM service arms. This model is concentrating aftermarket revenue with vertically integrated suppliers possessing regional spare parts depots and field engineering networks.
Solid State Lasers Market Segmentation
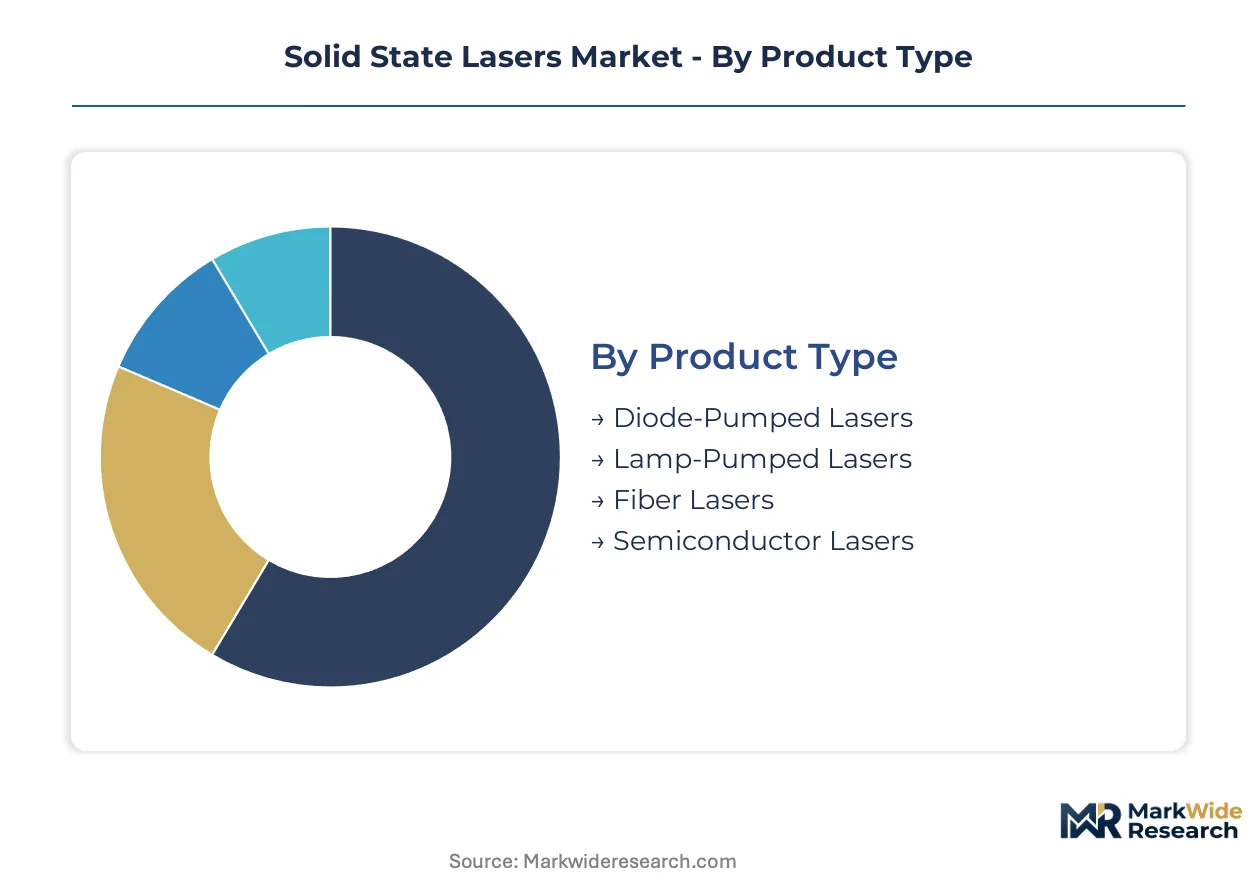
Solid state laser architectures fragment across gain media, pumping mechanisms, and pulse characteristics that dictate thermal budgets and maintenance cycles. Procurement patterns diverge sharply between precision manufacturing clusters seeking wall-plug efficiency and medical installations prioritizing regulatory compliance.
Product Type:
Diode array supply chains concentrate among crystal growth specialists with captive boule production, compressing procurement leverage for system integrators lacking backward integration.
- Diode-Pumped Lasers:These systems employ semiconductor diode arrays to excite neodymium-doped or ytterbium-doped gain media, eliminating flashlamp replacement cycles. Demand concentrates in German precision manufacturing clusters where TRUMPF and Jenoptik anchor production networks, driven by CE marking compliance timelines under EU Machinery Directive requirements.
- Fiber Lasers:Ytterbium-doped silica fiber gain media deliver superior beam quality and thermal management through distributed heat dissipation. Automotive sheet metal processing lines in Stuttgart and Munich are standardizing on these architectures, compressing lifetime operating costs against legacy crystal alternatives.
- Lamp-Pumped Lasers:Legacy arc lamp excitation of bulk crystal hosts persists in installed base maintenance.
- Semiconductor Lasers:Direct bandgap emission devices serve pumping and direct application roles.
Today's leader: Fiber Lasers. Tomorrow's challenger: Diode-Pumped Lasers.
Application:
End-use requirements diverge across pulse energy specifications, wavelength stability tolerances, and regulatory certification burdens that reshape supplier qualification timelines.
- Industrial Cutting:Multi-kilowatt fiber systems with active beam shaping capabilities dominate automotive and aerospace fabrication. Metal processing clusters in the Ruhr region are adopting per-minute availability contracts that shift maintenance liability to OEM service arms.
- Medical Procedures:FDA device classification rules govern dermatology and ophthalmology system deployments in the United States, while CE marking under EU MDR shapes European equipment procurement. Aesthetic medicine clinics are upgrading solid state platforms for vascular lesion treatment and tattoo removal.
- Defense & Security:Q-Switched architectures serve rangefinding and lidar applications where short pulse discrimination matters.
- Research & Development:Scientific instrumentation demands wavelength tunability and pulse control precision.
Industrial Cutting commands current procurement volume. Medical Procedures is climbing the fastest as aesthetic medicine capital expenditure accelerates.
Technology:
Pulse generation mechanisms determine peak power handling, thermal cycling tolerance, and resonator complexity that strain technician availability in manufacturing hubs.
- Ultrafast:Femtosecond pulse duration enables transparent material micromachining of sapphire substrates and display glass without thermal diffusion damage. Electronics manufacturers in consumer display supply chains are driving steepest expansion trajectory as device miniaturization demands precision ablation.
- Q-Switched:Nanosecond pulse storage and dumping architectures deliver high peak power for target discrimination. Defense rangefinding systems in allied nations are creating captive demand under evolving dual-use export control frameworks.
- Continuous Wave:Steady-state emission suits welding and heat treatment applications.
- Mode-Locked:Ultrashort pulse trains serve spectroscopy and precision measurement instrumentation.
Ultrafast technology is gaining share fastest. Q-Switched retains defense revenue concentration.
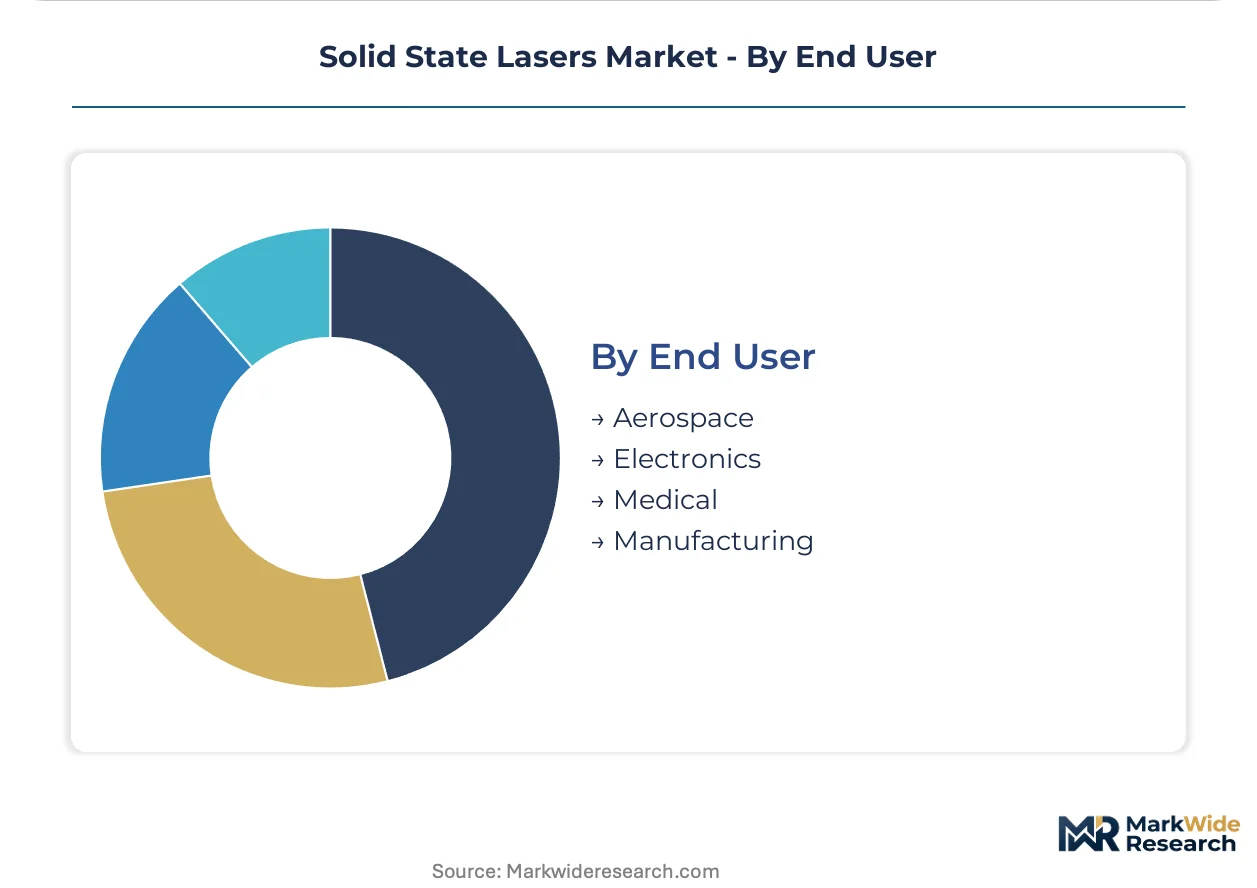
End User:
Customer verticals impose distinct certification requirements, uptime specifications, and service contract structures that fragment supplier pricing power.
- Manufacturing:Tier-one fabricators concentrate procurement among vertically integrated suppliers with regional spare parts depots and field engineering networks. Battery tray welding adoption in Stuttgart automotive OEMs is modularizing capital deployment through additive head configurations.
- Electronics:Display glass and semiconductor substrate processing demands femtosecond precision. REACH substance restrictions on chromium compounds in crystal hosts are compressing qualified supplier lists for lithography equipment manufacturers.
- Medical:Dermatology and ophthalmology clinics upgrade surgical equipment under FDA and CE marking compliance pathways.
- Aerospace:Structural welding and additive manufacturing applications prioritize beam stability.
Manufacturing anchors current system shipments. Electronics represents the fastest-growing trajectory as transparent material processing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters anchor solid state laser demand through automotive battery tray welding and sheet metal processing lines. CE marking compliance under the EU Machinery Directive accelerates equipment replacement cycles across Stuttgart and Munich industrial corridors. Fiber laser architectures displace legacy crystal systems as fabricators seek wall-plug efficiency gains.
United States
FDA device classification rules govern dermatology and ophthalmology system deployments in aesthetic medicine clinics. The Inflation Reduction Act's domestic manufacturing incentives support diode array production expansion. Detroit automotive clusters adopt multi-kilowatt fiber systems for EV battery assembly lines.
Germany
TRUMPF and Jenoptik anchor precision manufacturing networks serving automotive OEMs in Baden-Württemberg. REACH substance restrictions on chromium compounds compress qualified supplier lists for neodymium-doped YAG boules. Ruhr industrial region fabricators shift to per-minute laser availability contracts with OEM service arms.
China
Rare-earth oxide refining capacity concentrates in Jiangxi and Inner Mongolia regions, exposing downstream manufacturers to export quota volatility. GB standards and MIIT industrial policy shape domestic laser equipment certification pathways. Yangtze River Delta electronics manufacturers drive femtosecond micromachining demand for display glass processing.
Japan
Hamamatsu Photonics K.K. and precision optics specialists serve semiconductor lithography equipment supply chains under METI industrial guidance. JIS standards influence resonator assembly quality protocols. Kanto region cleanroom facilities face technician scarcity for precision optics alignment operations.
India
Production-linked incentive schemes for capital goods create localized assembly advantages for fiber laser system integrators. BIS certification requirements shape import compliance timelines for industrial processing equipment. Gujarat and Maharashtra manufacturing hubs upgrade metal cutting infrastructure under national precision manufacturing initiatives.
Solid State Lasers Market Competitive Landscape
Global majors compete with regional champions across diode array supply and resonator assembly capabilities. The vendor base stratifies between vertically integrated crystal growth specialists and modular system integrators lacking backward integration. Three archetypes dominate: captive diode manufacturers controlling thermal management subsystems, precision optics houses specializing in beam delivery, and diversified industrial laser platforms serving multiple end-use verticals. Consolidation pressure intensifies through strategic partnerships for rare-earth supply security and geographic expansion into PLI-enabled manufacturing jurisdictions.
Among German-anchored industrial laser platforms, TRUMPF and Jenoptik AG exemplify the vertically integrated archetype with in-house crystal growth and resonator assembly capabilities. IPG Photonics represents the captive diode manufacturing model with US-based production of pump arrays and fiber gain media. Coherent Inc. occupies a position spanning multiple technology vectors through control of boule production and resonator integration. These three entities anchor competitive positioning across automotive, medical, and electronics manufacturing verticals.
| Leading Market Players |
|---|
| Coherent Inc. |
| IPG Photonics |
| Jenoptik AG |
| TRUMPF |
| Han's Laser Technology Industry Group Co. Ltd. |
| Lumentum Operations LLC |
| Hamamatsu Photonics K.K. |
| nLIGHT Inc. |
| CrystaLaser |
| Others |
Value Network & Pricing Analysis
German automotive OEM procurement clusters concentrate demand for multi-kilowatt fiber laser systems, locking in contract-based long-term offtake agreements that bundle hardware ownership with per-minute availability guarantees. This buyer concentration compresses pricing power toward vertically integrated suppliers with captive diode manufacturing and regional service depots.
Pricing Analysis
Rare-earth oxide feedstock volatility passes through to system pricing, with ytterbium and neodymium cost swings absorbed differentially across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates TRUMPF and IPG Photonics at the top from modular system integrators lacking backward integration. Pricing pressure stems from flashlamp-to-diode-pump substitution cycles that shorten replacement revenue windows. Tier-one fabricators in the Ruhr region exhibit lowest price sensitivity due to uptime guarantee dependencies, while mid-tier metal processors in India drive hardest bargain on capital equipment.
Supply Chain Analysis
Single-source vulnerability sits with China's Jiangxi and Inner Mongolia regions, where neodymium and ytterbium refining capacity concentrates under export quota administration. Downstream laser manufacturing draws from Japanese precision optics specialists, German resonator assembly houses, and US-based diode array fabrication. Tariff exposure runs through rare-earth oxide trade corridors and CE marking compliance friction for non-integrated suppliers. Distribution runs through OEM direct sales arms for large fabricators and regional system integrators for mid-market metal processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solid state lasers market compounds steadily as femtosecond micromachining penetrates consumer electronics supply chains, creating durable replacement demand beyond industrial metal cutting cycles.
For Market Incumbents: Anticipate diode-pump technology obsolescence risk in legacy crystal system maintenance revenue streams. Defend position by deepening backward integration into rare-earth oxide supply through offtake agreements with Chinese refiners, and by certifying synthetic garnet alternatives under REACH substance restrictions before competitor qualification timelines close. For New Entrants and Emerging Players: India's PLI scheme for capital goods opens a window for localized fiber laser assembly without full backward integration burden. Target Gujarat and Maharashtra manufacturing hubs with standard-power cutting systems priced below TRUMPF service contract bundling. Pursue femtosecond micromachining white space in Yangtze River Delta display glass processing, where electronics manufacturers prioritize precision over brand heritage. For Investors and Strategic Acquirers: Precision manufacturing OEMs are the most active acquirer in this space, seeking captive laser supply for battery tray welding and sheet metal fabrication. Target mid-tier system houses with resonator assembly capabilities but lacking diode manufacturing. Watch for MIIT industrial policy shifts in China that restrict rare-earth oxide export quotas as the signal for supply chain restructuring and geographic diversification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Supply | Captive ytterbium oxide sourcing insulates TRUMPF and IPG Photonics from Jiangxi export quota volatility. |
| Synthetic Garnet Qualification | CE marking compliance under REACH chromium restrictions secures lithography equipment supplier status for European optics houses. |
| Per-Minute Availability Contract Expansion | Service unbundling concentrates aftermarket revenue with OEMs possessing Ruhr region field engineering networks. |
| Femtosecond Micromachining Platform Launch | Transparent material processing of sapphire substrates opens display glass revenue streams in consumer electronics supply chains. |
| PLI-Enabled Localized Assembly | India's capital goods incentive framework creates cost advantages for fiber laser system integrators in Gujarat manufacturing hubs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant engineers, OEM procurement teams, aftermarket service heads, and biomedical engineers at dermatology clinics with secondary validation. Bottom-up demand modeling drew from SEC 10-K filings, EU Machinery Directive compliance databases, customs trade records for rare-earth oxide shipments, and hospital procurement databases for medical laser systems. Top-down market sizing triangulated against IEA industrial energy consumption patterns and automotive production cluster data.
Segment-weighting distributed value across fiber laser, diode-pumped, and lamp-pumped architectures, then across industrial cutting, medical procedures, defense applications, and research instrumentation end-uses. Technology trajectories for ultrafast, Q-Switched, continuous wave, and mode-locked pulse mechanisms informed adoption curve assumptions. CAGRs derived from installed base replacement cycles, femtosecond micromachining penetration rates in electronics manufacturing, and CE marking compliance-driven equipment refresh timelines in German precision manufacturing clusters.
Revisions become necessary when rare-earth oxide export quotas tighten beyond historical volatility bands, when REACH substance restrictions expand to additional dopant matrices, or when defense wavelength export controls fragment allied nation procurement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Imaging Market
Optics
Optical Sensing Market
Optics
Electro Optics Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Anomaloscope Market
Optics
Glass Scintillator Market
Optics
Collimating Lens Market
Optics
Lasers Market
Optics
Germanium Lens Market
Optics
Fiber Optic Connectivity Market
Optics
Plastic Lens Market
Optics
Fiber Optics Market
Optics
Smart Vision Systems Market
Optics
Optical Microscope Market
Optics
Europe Smart Glass Market
Optics
Interchangeable Lens Market