
 Photonics Market | 2026-2036
Photonics Market Size, Share, and Industry Trends Forecast 2026-2036
Photonics Market Intelligence
Project finance for captive semiconductor foundries is narrowing the competitive aperture in photonics manufacturing. Coherent Corp. leverages vertical integration across laser diode and optical component fabrication to sustain margin structures. IPG Photonics Corporation anchors its position through in-house production of specialty optical fibers and pump diodes. Hamamatsu Photonics K.K. competes via R&D intensity in photodetector architectures for medical and industrial imaging.
Photonics encompasses the generation, manipulation, and detection of light through components operating across wavelengths from ultraviolet to infrared, with semiconductor lasers achieving wall-plug efficiencies exceeding sixty percent in industrial cutting applications. Its primary commercial purpose centers on transmitting, processing, and sensing optical signals in systems where electronic bandwidth or precision falls short. Lasers command the largest value pool in product type segmentation, driven by fiber laser penetration in materials processing and solid-state architectures in medical device manufacturing. Fiber optics within technology segmentation is displacing copper in data center interconnects, while biophotonics in application segmentation represents the fastest-growing demand vector as fluorescence microscopy and flow cytometry expand in clinical diagnostics.
FDA device clearance pathways shape product development timelines for photonics-enabled medical equipment in the United States, while REACH compliance in Europe constrains material selection for optical coatings and semiconductor substrates. The FCC's spectrum allocation decisions directly influence demand for tunable lasers and dense wavelength division multiplexing components in telecommunications infrastructure. Stakeholders must monitor how quantum dot regulatory classification evolves across jurisdictions, as this determines whether emerging display and sensing applications face pharmaceutical-grade or consumer-electronics compliance burdens.
Market Dynamics
Semiconductor laser efficiency gains are compressing cost-per-watt thresholds across industrial and telecommunications applications, forcing component suppliers to restructure fabrication footprints or surrender margin to integrated systems houses.
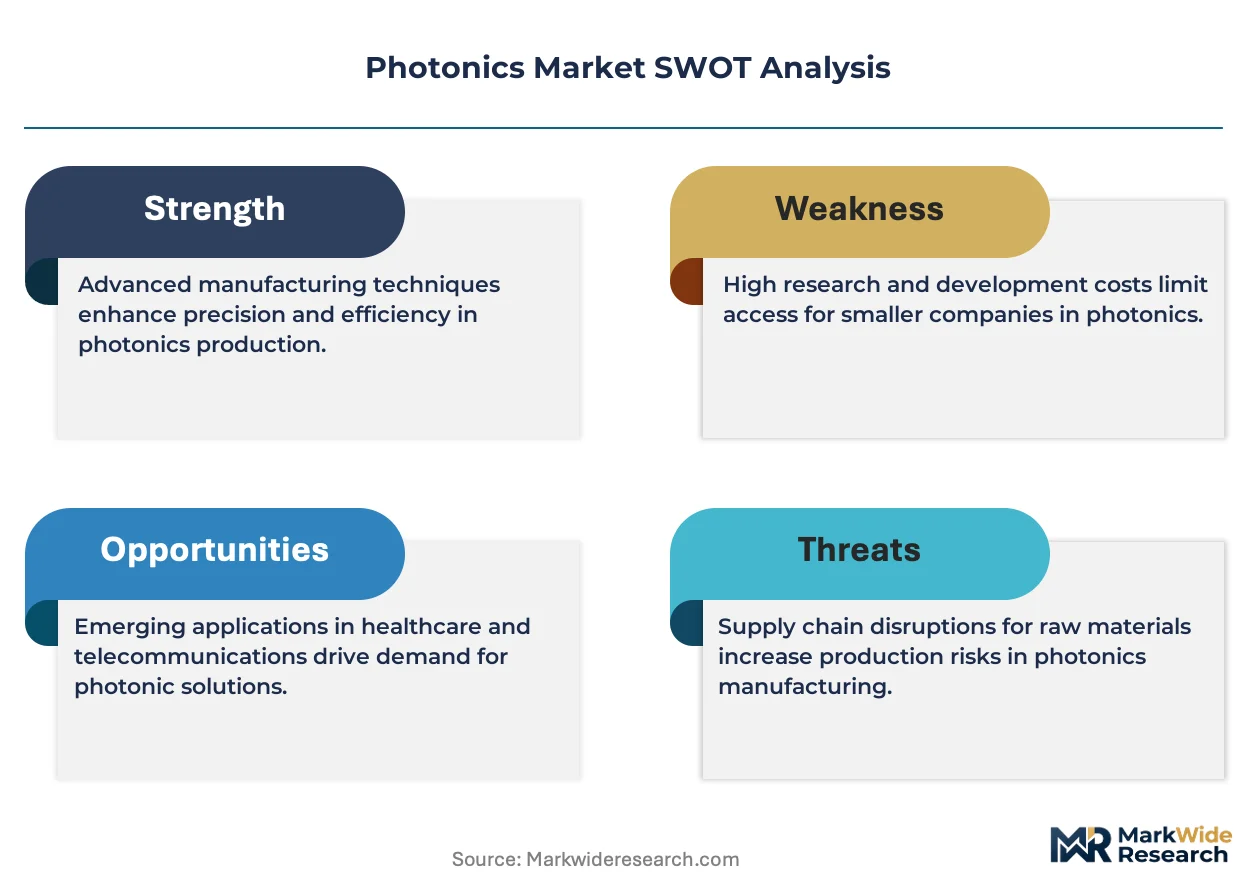
Growth Catalysts
- FCC spectrum auctions:Dense wavelength division multiplexing component demand accelerates as carriers expand fiber-to-the-home infrastructure across United States metropolitan corridors.
- Quantum dot fabrication:Advances in colloidal synthesis methods are reducing defect densities in display and sensing architectures, opening volume manufacturing pathways previously blocked by yield constraints.
- China consumer electronics:Domestic manufacturing clusters for smartphones and wearables consume photonic subassemblies at scale, pulling upstream laser diode and photodetector capacity toward Shenzhen and Chengdu industrial zones.
Market Restraints
- Rare earth supply concentration:Neodymium and ytterbium refining capacity clusters in Chinese Inner Mongolia, exposing fiber laser manufacturers to export quota volatility and price spikes.
- REACH substance restrictions:Cadmium and lead limitations in optical coatings force reformulation of quantum dot compositions, extending R&D timelines for European market access.
- Copper interconnect persistence:Short-reach data center applications under 10 meters retain copper cabling for cost reasons, capping optical transceiver penetration in hyperscale server farms.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor and display manufacturing attract photonics component suppliers to establish packaging and test facilities in Gujarat and Tamil Nadu.
- Biophotonics diagnostics:Fluorescence lifetime imaging and Raman spectroscopy systems penetrate pathology workflows, creating demand for compact, solid-state excitation sources.
- Lidar automotive integration:1550-nanometer fiber laser architectures displace 905-nanometer diode systems in autonomous vehicle perception stacks, favoring eye-safe power scaling.
Industry Challenges
- Specialized photonics workforce:Shortages in integrated photonics design and packaging engineering constrain foundry expansion timelines in Germany and Japan.
- FDA 510(k) clearance cycles:Photonics-enabled surgical and diagnostic devices face 12-18 month regulatory review periods, compressing product launch windows against competitive pressure.
- Heterogeneous integration complexity:Co-packaging of lasers, modulators, and detectors onto silicon photonics platforms demands precision alignment tolerances below 100 nanometers, challenging high-volume automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photonics Market |
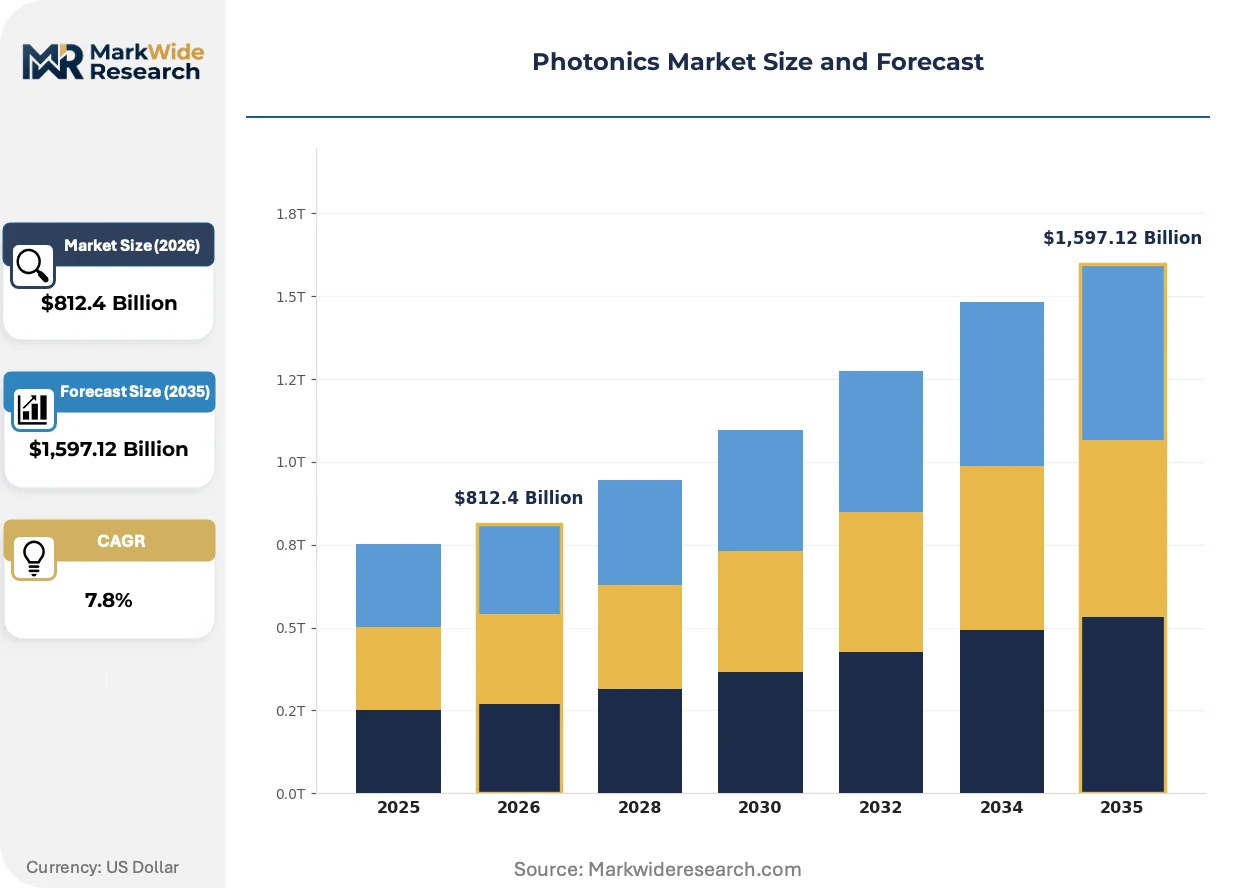
| Market Size in 2026 | $812.4 Billion |
| Market Size in 2035 | $1,597.12 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Components, Lasers, Photodetectors, Optical Fiber, Imaging Systems Technology: Semiconductor Lasers, Fiber Optics, Waveguides, Quantum Dots, Nonlinear Optics Application: Telecommunications, Consumer Electronics, Defense Systems, Environmental Monitoring, Biophotonics End User: Research Institutes, Manufacturing Facilities, Telecommunications Providers, Aerospace Companies, Medical Device Manufacturers |
| Companies Covered | Coherent Corp., Cisco Systems, Inc., Hamamatsu Photonics K.K., IPG Photonics Corporation, Lumentum Operations LLC, Intel Corporation, TRUMPF, Infinera Corporation, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photonics Market Strategic Shifts & Innovations
Silicon photonics manufacturing economics are rewriting competitive boundaries between discrete component suppliers and integrated platform providers, with implications stretching from transceiver architecture to foundry service models.
Thin-film lithium niobate modulators are collapsing power consumption and bandwidth-distance product limitations that constrained traditional silicon photonics platforms. Cloud data center operators in Oregon and Virginia deploy these devices in 800-gigabit coherent transceivers, enabling single-wavelength transmission across 120-kilometer spans without amplification.
REACH authorization requirements for perfluorinated substances are compelling optical coating suppliers to reformulate anti-reflection and high-reflection stacks using fluorine-free deposition chemistries. German precision optics houses accelerate vacuum evaporation process redevelopment to maintain CE marking eligibility for industrial laser systems exported throughout the European Union.
Hyperscale buyers now mandate open-line disaggregation specifications for optical transport equipment, unbundling transceiver procurement from switch and router chassis purchases. This procurement model shift fragments supplier relationships across North American cloud campuses, where direct transceiver sourcing from Asian module houses bypasses traditional systems integrator channels.
Photonics Market Segmentation
Photonics procurement patterns diverge sharply across segment boundaries. Component selection criteria vary by application criticality, with medical and defense buyers demanding traceable supply chains while consumer electronics prioritizes cost-per-unit scaling.
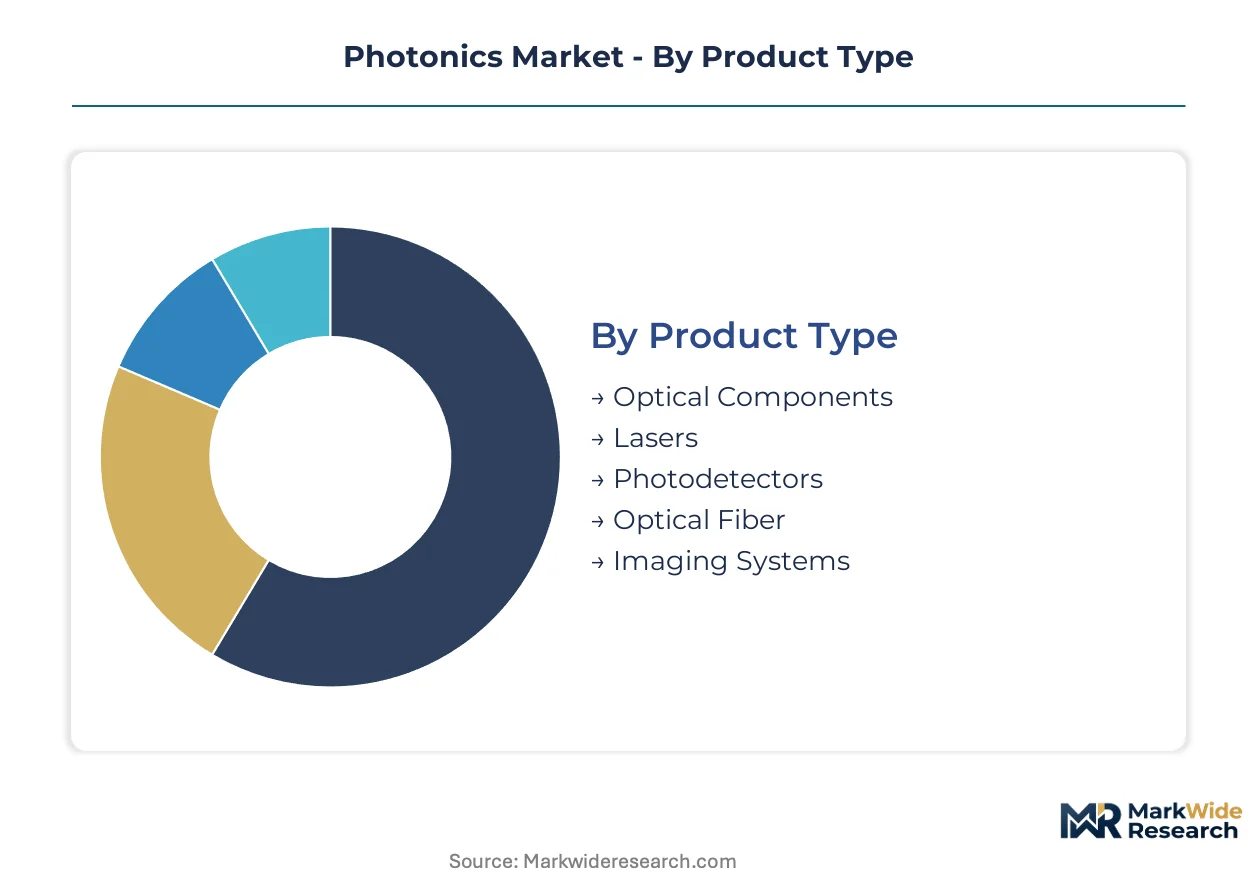
Product Type:
After-sales service intensity tracks directly with product complexity and failure modes. Lasers require field calibration and fiber coupling maintenance, while passive optical components need minimal post-installation support.
- Lasers:Solid-state and fiber architectures dominate industrial materials processing. German automotive suppliers and Japanese precision toolmakers absorb high-power fiber lasers for cutting and welding operations, with wall-plug efficiency gains compressing operating costs.
- Optical Components:Lenses, filters, and beam splitters form the functional core of imaging and sensing systems. Shenzhen consumer electronics clusters pull molded glass and polymer optics at volume, though coating durability remains a quality differentiator against low-cost competitors.
- Photodetectors:Avalanche photodiodes and CMOS sensors convert optical signals to electrical outputs for telecommunications and medical imaging.
- Optical Fiber:Single-mode and multimode silica fibers transmit data across submarine cables and data center interconnects.
- Imaging Systems:Microscopy and endoscopy platforms integrate illumination, optics, and detection into clinical and industrial inspection workflows.
Lasers hold the largest share; momentum sits with imaging systems.
Technology:
Technology selection hinges on wavelength precision, power scaling, and integration compatibility with existing electronic systems. Semiconductor processes dominate volume manufacturing, while emerging materials target performance thresholds silicon cannot reach.
- Semiconductor Lasers:Edge-emitting and vertical-cavity surface-emitting diodes enable optical communications and sensing. FCC spectrum allocations in United States metropolitan corridors accelerate tunable laser deployment for dense wavelength division multiplexing infrastructure.
- Fiber Optics:All-fiber architectures eliminate free-space alignment in telecommunications and laser systems. Submarine cable projects linking Virginia and Oregon data centers to Asian exchange points consume specialty fiber at scale.
- Waveguides:Silicon photonics and lithium niobate platforms confine and route light on-chip for transceiver miniaturization.
- Quantum Dots:Colloidal synthesis methods are reducing defect densities in display and sensing applications.
- Nonlinear Optics:Frequency conversion crystals and optical parametric amplifiers extend accessible wavelength ranges for spectroscopy and materials research.
Semiconductor lasers command current revenue; quantum dots are climbing the fastest.
Application:
Application segmentation reveals divergent buyer power and contract structures. Telecommunications carriers negotiate multi-year supply agreements, while biophotonics purchasers face fragmented procurement through hospital systems and research institutions.
- Telecommunications:Optical transport, access networks, and data center interconnects consume transceivers, amplifiers, and switching components. Carrier consolidation in United States markets concentrates purchasing power among fewer buyers, squeezing component margins.
- Biophotonics:Fluorescence microscopy, flow cytometry, and laser surgery systems drive demand for compact, stable light sources. FDA 510(k) clearance pathways in the United States shape product development timelines for photonics-enabled diagnostic equipment.
- Consumer Electronics:Smartphones, wearables, and displays integrate VCSELs for sensing and miniaturized projectors for augmented reality.
- Defense Systems:Rangefinders, target designators, and free-space optical communications require hardened components with radiation tolerance.
- Environmental Monitoring:Lidar and spectroscopic sensors track atmospheric composition and industrial emissions.
Telecommunications retains the largest share; biophotonics shows the steepest expansion trajectory.
End User:
End user categories reflect distinct technical specifications, certification requirements, and procurement cycles. Medical device manufacturers face the longest validation timelines, while telecommunications providers prioritize supply security and volume pricing.
- Telecommunications Providers:Tier-1 carriers and regional operators deploy optical infrastructure for backbone, metro, and access networks. Open-line disaggregation specifications from hyperscale buyers in Oregon and Virginia fragment traditional supplier relationships.
- Medical Device Manufacturers:Surgical laser systems and diagnostic imaging platforms demand component traceability and biocompatibility certification. FDA device clearance pathways constrain material selection and extend development cycles for photonics-integrated equipment.
- Manufacturing Facilities:Industrial laser systems cut, weld, and mark metals and polymers across automotive and electronics production lines.
- Research Institutes:National laboratories and university facilities prototype novel photonic architectures and characterize advanced materials.
- Aerospace Companies:Satellite communications and sensing payloads require radiation-hardened components with extended operational lifetimes.
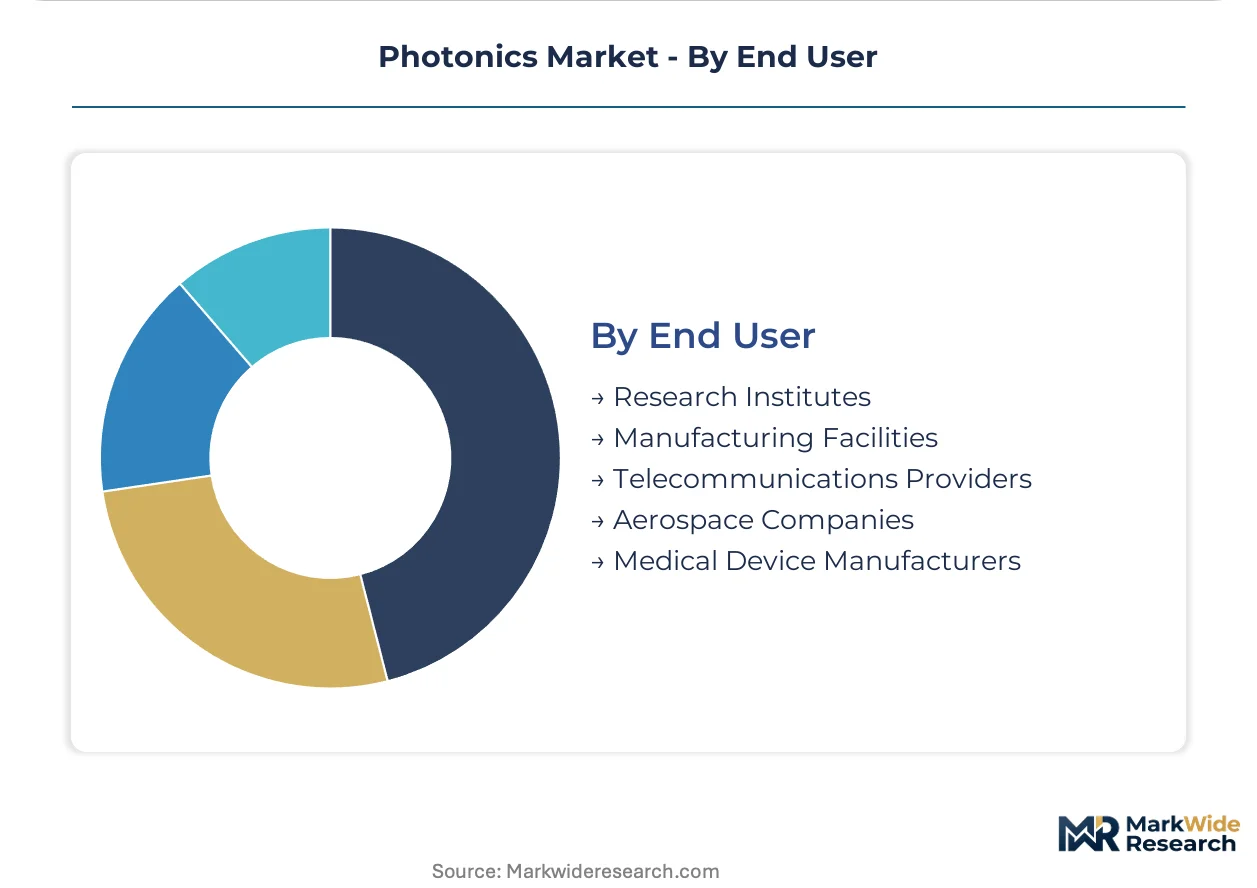
Telecommunications providers dominate procurement volume; medical device manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in photonics components tilt toward surplus in manufacturing-intensive economies while R&D-heavy markets run structural deficits in finished systems. Trade flows concentrate laser diodes and optical fibers from East Asian fabrication centers toward European and North American integration facilities.
United States
Quantum dot fabrication advances in research corridors drive upstream materials demand. FDA device clearance pathways shape development timelines for photonics-enabled diagnostic equipment. Oregon and Virginia data center clusters consume specialty optical fibers and coherent transceivers at scale for cloud infrastructure expansion.
Germany
Automotive suppliers and precision toolmakers absorb high-power fiber lasers for manufacturing operations. REACH compliance constrains material selection for optical coatings and semiconductor substrates. Bavarian and North Rhine-Westphalian industrial zones anchor laser system integration and photonics R&D intensity.
China
Domestic consumer electronics manufacturing corridors pull photonic subassemblies for smartphones and wearables. MIIT spectrum allocation decisions influence demand for optical communications components. Shenzhen and Chengdu industrial zones concentrate laser diode packaging and photodetector assembly capacity.
Japan
Telecommunications infrastructure deployment accelerates semiconductor laser adoption in fiber-to-the-home networks. METI industrial policy supports photonics manufacturing competitiveness. Hamamatsu and Nagoya industrial clusters specialize in photodetector architectures for medical and industrial imaging applications.
India
Production-linked incentives for semiconductor and display manufacturing attract component suppliers to establish packaging facilities. BIS certification requirements shape product qualification timelines for domestic market access. Gujarat and Tamil Nadu industrial corridors emerge as photonics assembly and test locations.
Photonics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in a structure that rewards captive fabrication capabilities. The vendor base organizes around three archetypes: vertically integrated laser houses controlling diode and fiber production, modular optical component suppliers serving multiple end-markets, and silicon photonics foundries offering co-packaging services. Consolidation pressures favor M&A activity among mid-scale fiber laser manufacturers, while capacity expansion concentrates in Asian packaging corridors.
Among US-based platform providers, Coherent Corp. and Cisco Systems, Inc. exemplify the integrated systems archetype. IPG Photonics Corporation occupies a position within the specialty fiber and pump diode tier. Hamamatsu Photonics K.K. anchors the photodetector specialization segment. These named entities represent competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Coherent Corp. |
| Cisco Systems, Inc. |
| Hamamatsu Photonics K.K. |
| IPG Photonics Corporation |
| Lumentum Operations LLC |
| Intel Corporation |
| TRUMPF |
| Infinera Corporation |
| Corning Incorporated |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container routes carry rare-earth-doped optical fibers and laser diode assemblies whose freight cost volatility feeds directly into tiered pricing spreads between premium-certified and economy-grade photonic components.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across high-power fiber laser procurement. Pricing stratifies across premium, standard, and economy tiers based on wall-plug efficiency certification and REACH-compliant coating specifications. Cost compression in economy-tier pump diodes is intensifying because Chinese packaging houses are scaling colloidal quantum dot capacity. Medical device manufacturers exhibit the lowest price sensitivity due to FDA-mandated traceability requirements, while consumer electronics assemblers in Shenzhen drive aggressive per-unit negotiation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for dense wavelength division multiplexing components. Neodymium and ytterbium refining capacity concentrates in Chinese Inner Mongolia, South Korean specialty fiber drawing feeds transceiver assembly, and German precision optics houses supply coated substrates for industrial laser systems. The supply chain rests on single-source vulnerability for rare-earth element purification. Distribution runs through direct procurement channels from Asian module houses to North American hyperscale data center operators, bypassing traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics manufacturing economics are disrupting component procurement patterns, with thin-film lithium niobate modulators collapsing power-bandwidth tradeoffs that previously locked buyers into incumbent platforms.
For Market Incumbents: Entrench captive fiber drawing and diode fabrication capabilities to defend margin structures against modular Asian competitors. Accelerate in-house production of specialty optical fibers and pump diodes to offset rare-earth supply concentration risk. Prioritize R&D intensity in photodetector architectures for FDA-cleared medical imaging workflows.
For New Entrants and Emerging Players: Biophotonics diagnostics workflows in European hospital systems represent the most penetrable entry point for solid-state excitation sources. Quantum dot display applications in automotive heads-up displays offer second-mover advantage as colloidal synthesis yields improve. Pursue open-line disaggregation procurement relationships with Oregon and Virginia hyperscale operators rather than traditional systems integrator channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized photonics divisions lacking silicon photonics co-packaging capabilities. Position portfolios for sustained demand across telecommunications infrastructure replacement cycles and biophotonics clinical adoption curves. Monitor FCC spectrum auction schedules as inflection indicators for tunable laser and DWDM component demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Secures ytterbium and neodymium supply chains against Chinese export quota volatility for fiber laser manufacturers. |
| Silicon Photonics Co-Packaging Partnership | Enables precision alignment below 100 nanometers for 800-gigabit coherent transceiver miniaturization at Oregon hyperscale campuses. |
| FDA 510(k) Clearance Pathway Investment | Accelerates product launch windows for photonics-enabled surgical and diagnostic devices against 12-18 month regulatory review cycles. |
| India PLI Scheme Facility Establishment | Captures production-linked incentives for semiconductor packaging in Gujarat and Tamil Nadu industrial corridors. |
| REACH-Compliant Coating Reformulation | Maintains CE marking eligibility for industrial laser systems exported throughout the European Union under fluorine-free deposition chemistries. |
Research Approach
Operator-level perspectives from photonics foundry engineers, telecommunications carrier procurement directors, medical device regulatory affairs leads, and industrial laser system integrators anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings of listed optical component suppliers, FCC spectrum allocation dockets, FDA 510(k) clearance databases, and ECHA REACH authorization registers. Bottom-up segmentation modeling and top-down macroeconomic anchoring provided cross-verification.
Scenario-bracketing around rare-earth supply disruptions and quantum dot yield improvements framed the projection horizon across product type, technology, application, and end-user dimensions. CAGRs derived from installed base turnover rates, carrier capex cycle timing, and clinical diagnostics adoption curves. Forecast inputs included fiber-to-the-home deployment schedules in Japan and Germany, and hyperscale data center interconnect upgrade patterns in Virginia and Oregon.
Practitioners should monitor FCC spectrum auction outcomes, REACH substance restriction amendments, and MIIT industrial policy shifts for early signals of demand inflection or supply constraint. Forecasts reflect documented assumptions about carrier consolidation patterns and quantum dot regulatory classification evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Laser Transmitter Market
Optics
Germanium Lens Market
Optics
Smartphone Camera Lenses Market
Optics
Fiber Optic Connectivity Market
Optics
Sports Optics Market
Optics
Excimer Laser Market
Optics
Optical Lens for Mobile Phone Market
Optics
Fiber Optic Receiver Market
Optics
Interchangeable Lens Market
Optics
Fiber Optic Preform Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Optical Telescope Market
Optics
Acrylic Lenses Market
Optics
Fiber Optic Amplifier Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Plastic Lens Market