
 Smart Glass Market | 2026-2036
Smart Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Glass Market Intelligence
Aftermarket service revenue from calibration and tint-control system maintenance is narrowing as manufacturers embed longer-life electrochromic layers and self-diagnostic firmware. Saint-Gobain S.A. leverages its integrated float-glass and coating facilities to control raw material throughput from silica to finished smart panels. Gentex Corporation dominates automotive dimmable mirror technology, sustaining its position through captive relationships with North American and European OEM assembly lines. AGC Inc. competes aggressively in Asian commercial building projects, extending its SPD film partnerships into airport and high-speed rail glazing contracts.
Smart glass refers to electrically active glazing that modulates light transmission, thermal transmittance, or opacity in response to voltage, temperature, or ambient light stimuli, typically achieving visible light transmittance swings between 5% and 70% depending on activation state. Electrochromic devices employ tungsten-oxide-based thin films with lithium-ion conductor interlayers, while suspended particle device (SPD) technology uses rod-shaped nanoparticles aligned within a polymer matrix under electric field influence to deliver sub-second switching speeds for automotive and aerospace visibility management. The application dimension shows commercial buildings capturing the dominant share of retrofit activity as facility managers prioritize daylight harvesting and HVAC load reduction, whereas automotive OEM demand concentrates in premium sunroof and side-window configurations where electrochromic performance justifies unit cost premiums. Technology segmentation reveals liquid crystal approaches holding mature positions in privacy glass for interior partitions, while nano-coating innovations are gaining traction in residential retrofits where film-based application avoids full pane replacement.
The U.S. Department of Energy enforces thermal performance benchmarks through building energy codes that effectively mandate dynamic glazing in federal and large commercial structures, while the EU Green Deal's renovation wave targets carbon-neutral building stocks by requiring advanced facade systems in major renovation cycles. China's MIIT promotes domestic smart material production through GB standards alignment and dual carbon goals that pressure provincial construction bureaus to specify energy-responsive envelopes. Stakeholders must monitor how regulatory stringency divergence between North American prescriptive codes and European performance-based frameworks reshapes product certification burdens and regional manufacturing location decisions.
Market Dynamics
Automotive OEMs are consolidating electrochromic and SPD glazing specifications across premium vehicle lines, compressing supplier qualification cycles and forcing coating specialists to co-locate near assembly clusters.
Growth Catalysts
- EU Green Deal renovation wave:The EU Green Deal mandates carbon-neutral building stocks through advanced facade systems in major renovation cycles, accelerating dynamic glazing adoption across commercial retrofits.
- Electrochromic film advances:Tungsten-oxide thin films with lithium-ion interlayers now achieve sub-60-second switching speeds, expanding addressable applications beyond sunroofs into side windows.
- China MIIT dual carbon goals:Provincial construction bureaus face pressure to specify energy-responsive envelopes under GB standards alignment, concentrating demand in smart city infrastructure clusters.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor supply chains concentrate in East Asian refineries, exposing electrochromic manufacturers to price volatility and geopolitical disruption.
- Liquid crystal performance ceiling:Privacy glass applications face technical limitations in visible light transmittance range and switching speed compared to SPD alternatives.
- US DOE code fragmentation:Prescriptive thermal performance benchmarks vary across state jurisdictions, multiplying certification burdens for multi-state building projects.
Strategic Opportunities
- Residential retrofit film channels:Nano-coating innovations enable film-based application without full pane replacement, opening underpenetrated single-family housing markets.
- Airport and rail glazing contracts:SPD film partnerships extend into transportation infrastructure where daylight management and thermal control justify premium specifications.
- Self-diagnostic firmware integration:Embedded tint-control intelligence reduces aftermarket service dependency while creating recurring software revenue streams.
Industry Challenges
- Electrochromic layer deposition expertise:Thin-film coating specialists with vacuum deposition experience remain scarce, constraining capacity expansion timelines.
- OEM qualification cycle compression:Automotive safety glass certification requires 18-24 month validation protocols that conflict with platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Glass Market |
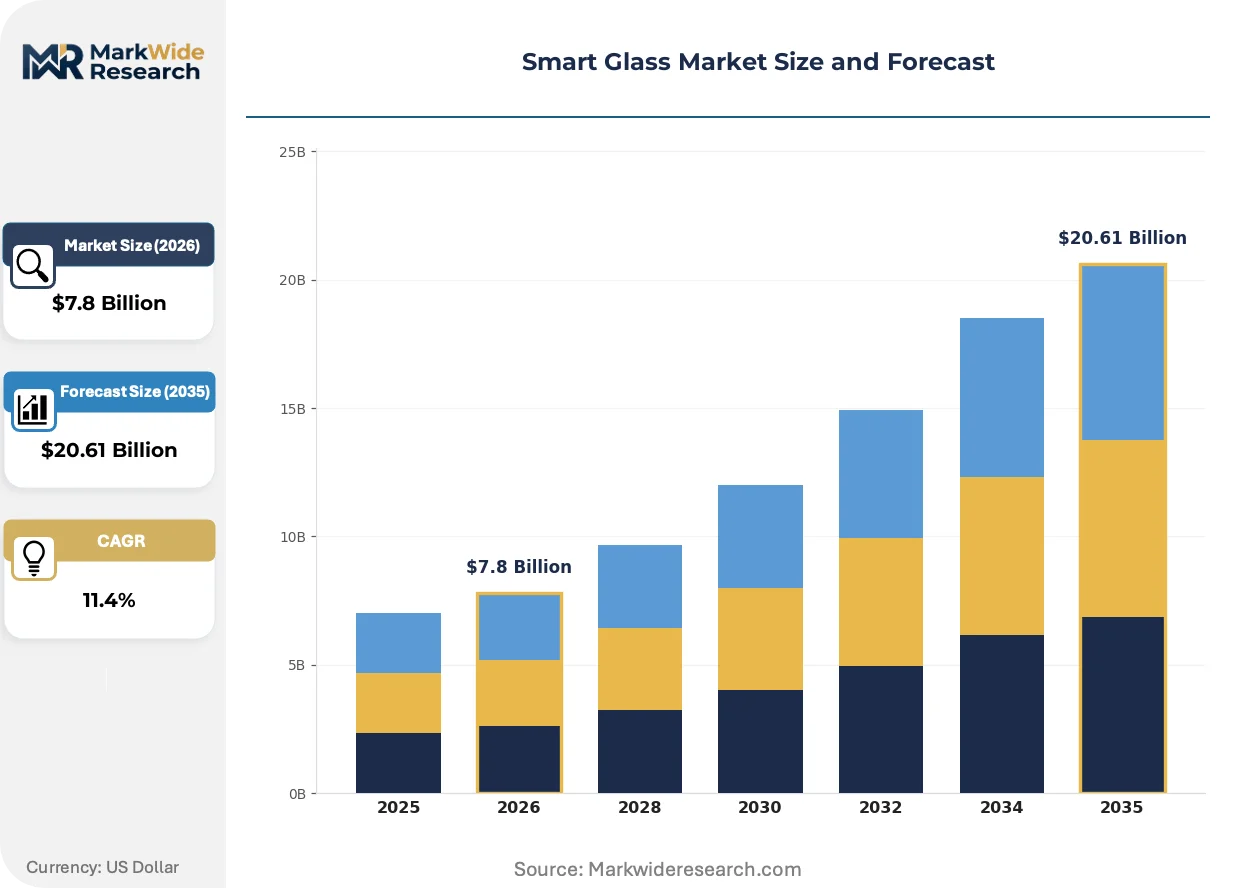
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic, Thermochromic, Photochromic, SPD Application: Automotive, Residential, Commercial, Aerospace Technology: Smart Tint, Liquid Crystal, Nano-coating, Magneto-optic End User: Construction, Automotive OEMs, Facility Management, Retail |
| Companies Covered | Saint-Gobain S.A., AGC Inc., Gentex Corporation, Corning Incorporated, View Inc., Nippon Sheet Glass Co., Ltd., Guardian Industries, Research Frontiers Inc., Gauzy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Glass Market Strategic Shifts & Innovations
Technology convergence between automotive glazing specifications and commercial building energy codes is compressing product development cycles and forcing modular platform architectures.
Perovskite-based electrochromic materials are rendering obsolete traditional tungsten-oxide systems in architectural applications. Large-format glass processors in Germany and South Korea are piloting these materials for curtain wall installations. The structural consequence is rendering obsolete legacy sputtering equipment investments as solution-processed coatings enable roll-to-roll manufacturing.
REACH restrictions on chromium compounds are forcing reformulation of electrochromic counter-electrode materials across European manufacturing. The industrial consequence is accelerating non-toxic alternative development in tungsten-nickel-oxide composites. Commercial building retrofit segments face the steepest compliance costs, driving preference for pre-certified imported modules.
Facility managers are consolidating glazing procurement under energy-service company contracts that bundle dynamic glass with HVAC optimization. This displaces traditional material-only purchasing through general contractors. The model is most visible in US federal building portfolios where the IRA efficiency incentives require integrated envelope-performance guarantees.
Smart Glass Market Segmentation
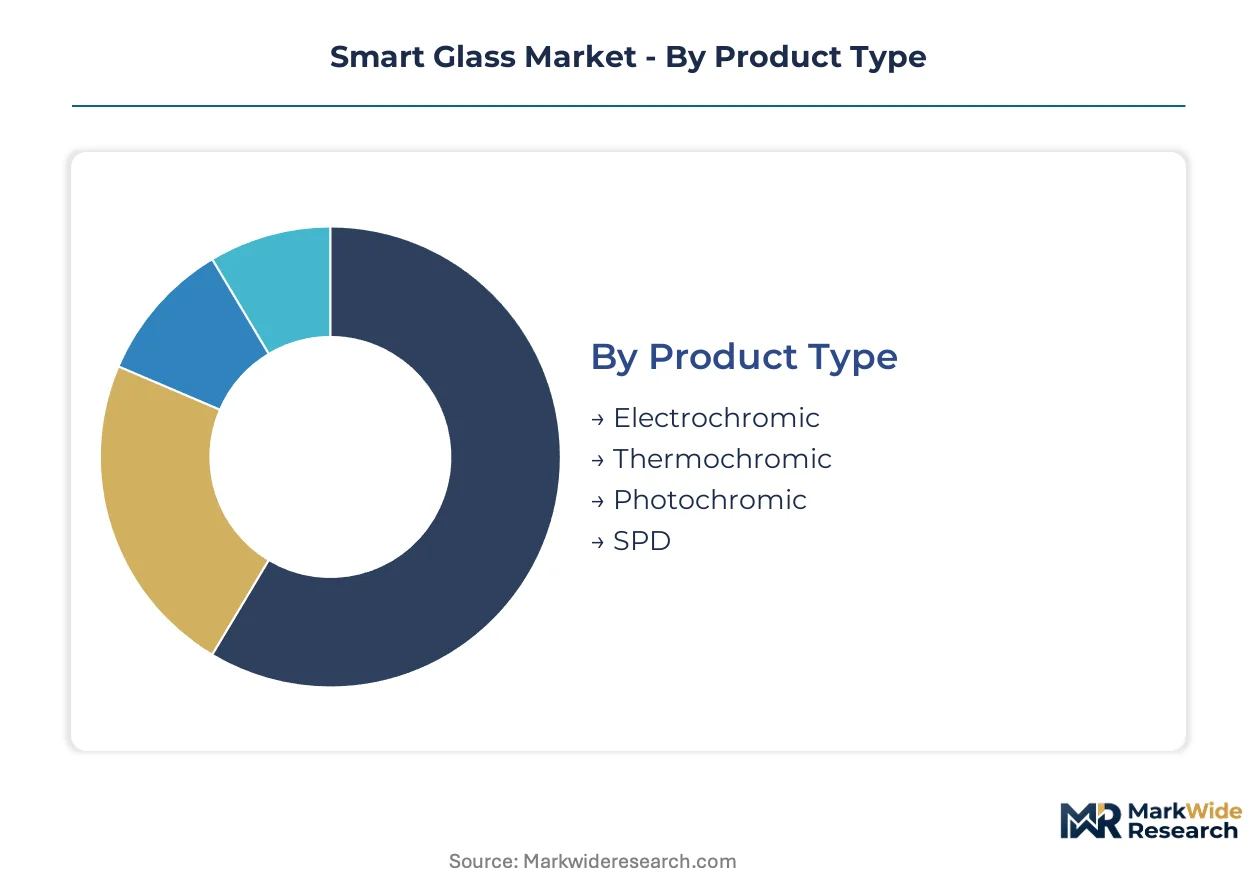
Technology-platform diversity in smart glass creates distinct value capture profiles across electrochromic thin-film specialists and SPD polymer integrators. Application fragmentation between automotive glazing certification cycles and commercial building retrofit timelines demands differentiated go-to-market architectures.
Product Type:
Cost tier stratification separates premium electrochromic systems from commodity photochromic alternatives, with switching performance and lifetime durability driving price positioning.
- Electrochromic:Tungsten-oxide thin films with lithium-ion conductor interlayers modulate visible light transmittance through electrochemical redox reactions. Demand concentrates in premium automotive sunroofs and side windows where Gentex and Saint-Gobain supply North American and European OEM assembly clusters under multi-year platform contracts.
- SPD:Rod-shaped nanoparticles suspended in polymer matrices align under electric fields to achieve sub-second switching speeds. AGC Inc. dominates airport and high-speed rail glazing contracts across Asian infrastructure projects where daylight glare management commands specification premiums.
- Thermochromic:Temperature-responsive vanadium-dioxide coatings passively modulate solar heat gain without electrical infrastructure.
- Photochromic:Silver-halide microcrystals embedded in glass substrates darken under UV exposure for residential skylight retrofits.
Electrochromic holds installed capacity. SPD is rotating up the share rankings.
Application:
Volume concentration patterns diverge sharply between automotive OEM qualification protocols and commercial building energy-service procurement models.
- Commercial:Facility managers bundle dynamic glazing with HVAC optimization under energy-service company contracts that displace traditional general contractor purchasing. US federal building portfolios concentrate demand through IRA efficiency incentives requiring integrated envelope-performance guarantees from Saint-Gobain and AGC installation partners.
- Automotive:OEMs consolidate electrochromic and SPD specifications across premium vehicle lines, compressing supplier qualification cycles to 18-24 month validation protocols. Rearview mirror dimming from Gentex sustains captive relationships with North American assembly plants.
- Residential:Single-family retrofits adopt nano-coating film applications avoiding full pane replacement costs.
- Aerospace:Cabin window systems prioritize SPD sub-second response for passenger comfort on long-haul routes.
Commercial captures retrofit volume. Automotive is climbing the fastest on new platform penetration.
Technology:
Maturity gradients separate liquid crystal privacy glass installations from emerging magneto-optic research platforms still in laboratory validation.
- Liquid Crystal:Polymer-dispersed liquid crystal films switch between transparent and opaque states for interior partition privacy. Office fit-out contractors in Germany and South Korea specify these systems for open-plan workspace reconfigurations where instant visual privacy justifies per-square-meter premiums over traditional blinds.
- Smart Tint:User-controlled opacity layers integrate with building management systems for automated daylight harvesting algorithms.
- Nano-coating:Solution-processed roll-to-roll manufacturing enables residential retrofit channels without glass fabricator involvement.
- Magneto-optic:Faraday-effect materials remain confined to specialized optical isolation applications with limited architectural relevance.
Liquid Crystal holds mature installed base. Nano-coating is gaining share fastest through bypass distribution.
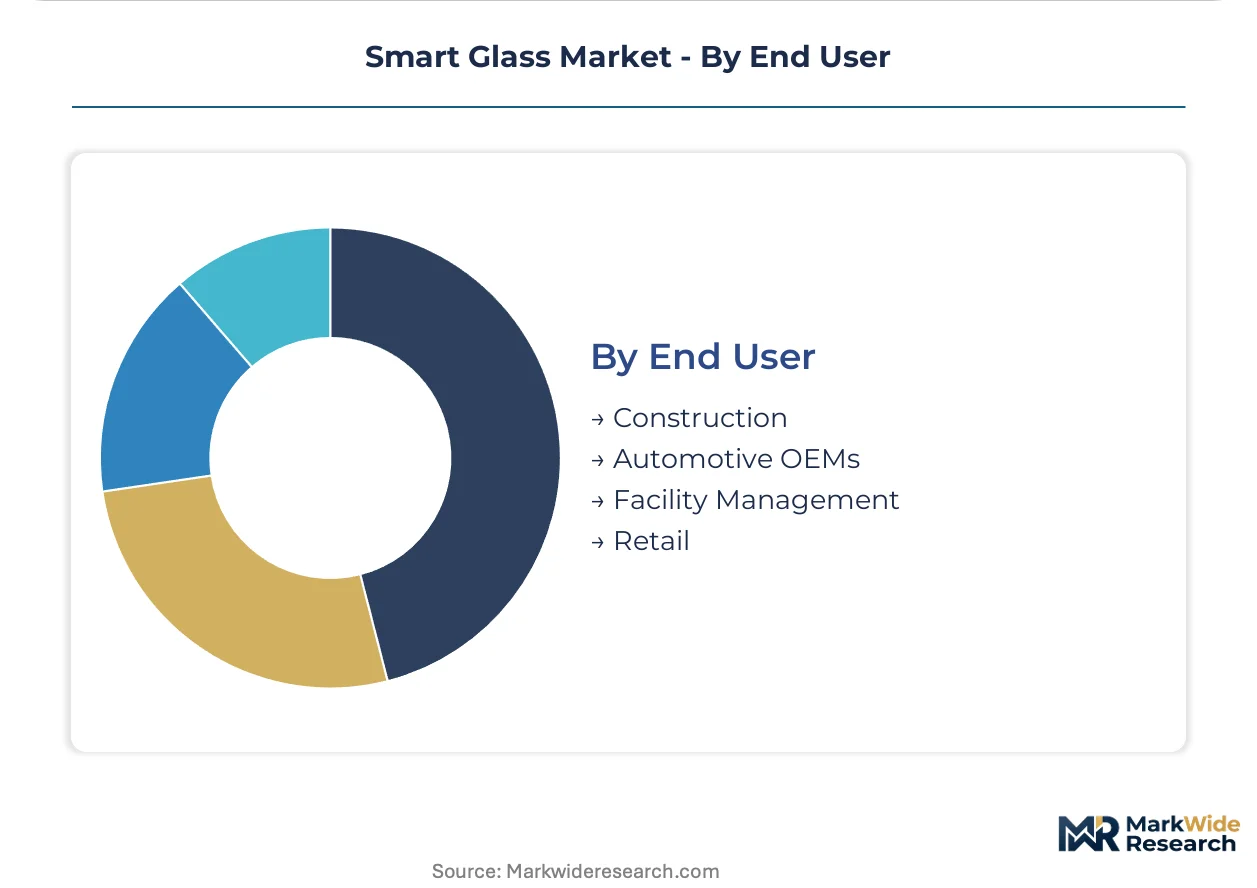
End User:
Customer type determines procurement authority concentration, from construction general contractors to captive automotive supply chains.
- Construction:General contractors and glazing subcontractors specify smart glass for new commercial builds under performance-based facade contracts. China's provincial construction bureaus face MIIT dual carbon pressure to specify energy-responsive envelopes in smart city infrastructure clusters.
- Automotive OEMs:Vehicle manufacturers integrate electrochromic sunroofs and mirrors through direct supplier development programs with coating specialists.
- Facility Management:Building operators procure retrofits through energy-service performance contracts bundling glazing with HVAC optimization.
- Retail:Display case and storefront applications prioritize switchable privacy for merchandise security during off-hours.
Construction holds project pipeline volume. Facility Management is rotating up the share rankings on retrofit acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate lowest price elasticity for premium electrochromic specifications, while residential retrofit segments in India and Southeast Asia remain acutely sensitive to per-square-meter costs. Facility managers in the United States occupy a middle position, accepting moderate premiums for energy-service bundled procurement.
United States
Federal building portfolios and premium automotive assembly lines concentrate demand for electrochromic sunroofs and dynamic facades. The IRA efficiency incentives mandate integrated envelope-performance guarantees for retrofit contracts. Detroit and Austin manufacturing clusters host OEM qualification programs with coating specialists supplying North American vehicle platforms.
Germany
Curtain wall installations in commercial retrofits and premium automotive OEM specifications drive demand for large-format electrochromic panels. The EU Green Deal renovation wave enforces carbon-neutral building stock targets through advanced facade system mandates. Stuttgart and Munich industrial corridors concentrate vacuum deposition expertise for thin-film coating production.
China
Smart city infrastructure clusters and high-speed rail glazing contracts absorb SPD film volumes for daylight management applications. MIIT dual carbon goals pressure provincial construction bureaus to specify energy-responsive envelopes under GB standards alignment. Yangtze River Delta manufacturing bases integrate float-glass and coating facilities for domestic supply chain control.
South Korea
Roll-to-roll manufacturing pilots for perovskite-based electrochromic materials target architectural curtain wall exports. METI-aligned technology partnerships accelerate solution-processed coating development. Seoul-Incheon industrial complexes host pilot lines displacing legacy sputtering equipment investments.
Japan
Interior partition privacy glass for office fit-out contractors sustains liquid crystal film demand. JIS standards alignment governs building material certification for energy-responsive envelope specifications. Osaka-Kobe manufacturing clusters supply polymer-dispersed liquid crystal systems for workspace reconfiguration projects.
Smart Glass Market Key Industry Players
Capability concentration sits with thin-film coating specialists possessing vacuum deposition expertise; scale advantage sits with integrated glass fabricators controlling raw material throughput from silica to finished panels. The market structure tiers between premium electrochromic system providers and commodity film applicators serving residential retrofits. Three archetypes dominate: captive automotive suppliers with OEM-locked qualification cycles, architectural glass integrators with energy-service contracting capabilities, and nano-coating innovators bypassing traditional fabricator channels. Competitive moves center on co-location near automotive assembly clusters and strategic partnerships with rail and airport infrastructure developers.
Within the integrated glass fabricator tier, Saint-Gobain S.A. and AGC Inc. occupy positions exemplifying upstream control over float-glass and coating facilities. Gentex Corporation represents the captive automotive supplier archetype with sustained OEM relationships. These three companies anchor the competitive structure while nano-coating specialists and SPD film integrators challenge traditional channel economics through bypass distribution models.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| AGC Inc. |
| Gentex Corporation |
| Corning Incorporated |
| View Inc. |
| Nippon Sheet Glass Co., Ltd. |
| Guardian Industries |
| Research Frontiers Inc. |
| Gauzy Ltd |
| Others |
Cost & Logistics Intelligence
East Asian indium tin oxide refineries concentrate transparent conductor supply, anchoring margin capture downstream at electrochromic device manufacturers and integrated glass fabricators who convert raw material throughput into finished smart panels.
Pricing Analysis
Aftermarket service contracts for calibration and tint-control system maintenance drive lifetime value capture as manufacturers embed longer-life electrochromic layers and self-diagnostic firmware. Three-tier pricing structure across premium electrochromic, standard SPD, and economy photochromic levels separates automotive OEM specifications from commercial retrofit film channels. Cost compression in residential retrofit segments intensifies as nano-coating innovations enable film-based application without full pane replacement. Facility managers under energy-service company contracts demonstrate lowest price sensitivity, while single-family housing markets in emerging economies remain most acutely responsive to per-square-meter costs.
Supply Chain Analysis
Silica sand and soda ash feedstock availability centers on float-glass manufacturing clusters in China, Germany, and the United States. Vacuum deposition equipment and lithium-ion conductor interlayers draw from Japanese and South Korean precision component suppliers. Single-source vulnerability in East Asian transparent conductor refineries exposes electrochromic manufacturers to geopolitical disruption and price volatility. Distribution runs through captive automotive supply chains and energy-service company procurement networks that bundle glazing with HVAC optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs consolidating electrochromic and SPD specifications across premium vehicle lines, compressing supplier qualification cycles and forcing coating specialists into co-location concessions.
For Market Incumbents: Pre-empt nano-coating challengers by embedding self-diagnostic firmware that reduces aftermarket service dependency while creating recurring software revenue streams. Extend captive relationships with North American and European OEM assembly lines through qualification cycle co-investment. Deepen upstream control over float-glass and coating facilities to defend margin position against film-based bypass distribution.
For New Entrants and Emerging Players: Build out residential retrofit channels where nano-coating innovations enable film-based application without full pane replacement costs. Target single-family housing markets in Southeast Asia and India where per-square-meter price sensitivity has blocked traditional electrochromic penetration. Pursue airport and high-speed rail infrastructure contracts where SPD film specifications for daylight glare management command premium positioning.
For Investors and Strategic Acquirers: Capital is best deployed toward thin-film coating specialists with vacuum deposition expertise and established OEM qualification relationships. Long-term viability hinges on exposure to automotive platform standardization and commercial building energy-service contracting. Watch for inflection signals in perovskite-based electrochromic material pilots displacing legacy tungsten-oxide systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-location Near Assembly Clusters | Compressed OEM qualification cycles force coating specialists to locate within logistics reach of Detroit and Stuttgart manufacturing corridors. |
| Self-Diagnostic Firmware Integration | Embedded tint-control intelligence reduces aftermarket service dependency while creating recurring software revenue streams for Gentex and Saint-Gobain. |
| SPD Film Partnership Extension | AGC Inc. leverages airport and high-speed rail contracts to establish daylight management specifications in Asian infrastructure projects. |
| Perovskite Material Piloting | Large-format processors in Germany and South Korea test solution-processed coatings that displace legacy sputtering equipment investments. |
| Energy-Service Contracting Capability | Facility managers consolidate glazing procurement under bundled HVAC optimization contracts displacing traditional general contractor purchasing. |
Research Approach
A spread of perspectives from automotive OEM platform engineers, commercial facility managers, thin-film coating specialists, and energy-service company procurement leads converged on the working assumptions shaping this analysis. Primary fieldwork with glass fabricator R&D directors and SPD film integrators combined with secondary validation from SEC 10-K filings, customs and trade data, and building energy code documentation. Bottom-up segment sizing across technology platforms and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance modeling tracked electrochromic thin-film capacity expansion against automotive sunroof specification rates and commercial building retrofit pipelines across the analysis window. Segmentation dimensions included technology type, application vertical, end-user procurement authority, and regional regulatory framework. CAGRs derived from fitted growth curves applied to base-year sizing, stress-tested against MIIT dual carbon enforcement trajectories and EU Green Deal renovation wave implementation.
Stress conditions across indium tin oxide price volatility, OEM platform launch delays, and REACH reformulation compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about switching speed improvements and film lifetime durability. Cross-checking against IEA building efficiency deployment data and national vehicle production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Picosecond Lasers Market
Optics
Polymeric Optical Fiber Market
Optics
Optical Sensing Market
Optics
Europe Smart Glass Market
Optics
Single-Mode Optical Fiber Market
Optics
3D Optical Microscope Market
Optics
Smart Vision Systems Market
Optics
Beam Expanders Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Fiber Optic Connectivity Market
Optics
Photonics Market
Optics
Fiber Optic Cable Market
Optics
Optical Receivers Market
Optics
Asia Pacific Fiber Optics Market
Optics
Collimating Lens Market
Optics
Fiber Optic Development Tools Market