
 X-Ray Microscopes Market | 2026-2036
X-Ray Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Microscopes Market Analytics
Multi-source procurement for precision optics and detector arrays is pivoting toward captive supply agreements as lead times extend. Bruker Corporation leverages its superconducting detector technology to anchor high-resolution installations at synchrotron facilities. Carl Zeiss Microscopy dominates the semiconductor metrology segment with proprietary objective lens designs. Rigaku Corporation specializes in rotating-anode X-ray sources that sustain throughput in industrial quality-control labs.
X-ray microscopes employ focused X-ray radiation to achieve non-destructive three-dimensional imaging at sub-50 nanometer resolution, utilizing zone-plate optics or capillary condensers to concentrate broadband or monochromatic beams onto specimens for tomographic reconstruction. The instruments serve semiconductor failure analysis, battery electrode characterization, and biological soft-tissue imaging without sectioning artifacts. Transmission X-Ray Microscopes occupy the mature core of installed bases where synchrotron access subsidizes capital costs for academic users. Scanning X-Ray Microscopes are capturing the fastest expansion in semiconductor inspection as foundries demand wafer-level defect mapping with 3D spatial resolution. Computed Tomography technology concentrates margin pools in industrial manufacturing where inline process control commands premium service contracts.
FDA quality-system regulations and EU MDR conformity requirements shape validation protocols for healthcare and diagnostic deployments, while ISO 9001 and IEC 61010 standards govern electrical safety and measurement traceability in laboratory environments. Japan's METI funds domestic X-ray optics development through national laboratory partnerships, reinforcing JIS-compliant supply chains for export markets. Stakeholders must monitor foundry capital expenditure cycles and synchrotron beamline construction timelines to align capacity planning with demand pulses.
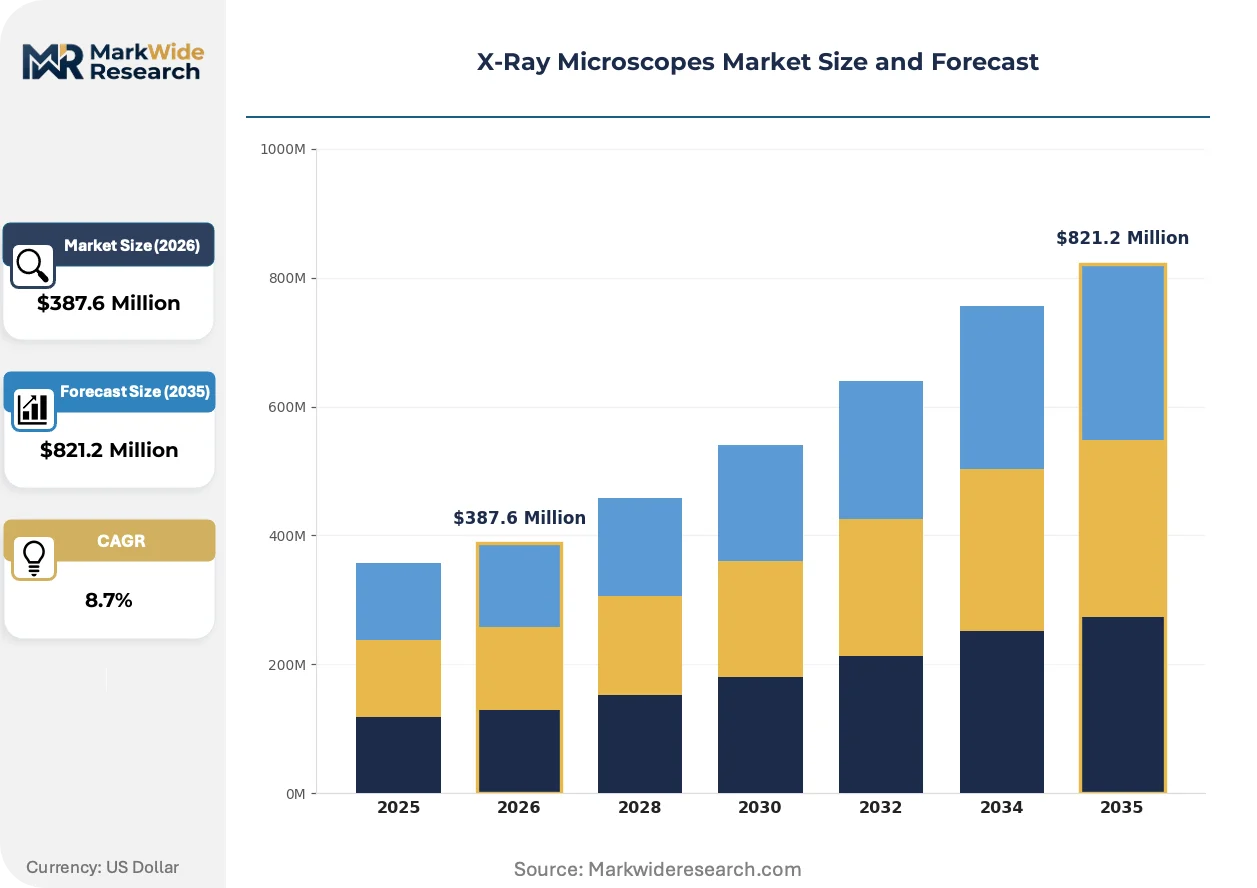
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are compressing defect-detection tolerances below 10 nanometers, forcing metrology suppliers to synchronize roadmap acceleration with capital expenditure cycles at TSMC and Samsung Electronics.
Growth Catalysts
- Sub-10nm node migration:Taiwan and South Korean foundries are expanding inline X-ray inspection stations to catch buried voids and overlay errors at advanced logic nodes.
- EU MDR validation mandates:Healthcare imaging systems face tightened conformity assessment pathways, creating replacement demand for ISO 13485-certified laboratory configurations.
- Battery electrode characterization:Solid-state battery developers in Japan and Germany require non-destructive 3D microstructure mapping to validate dendrite suppression in ceramic electrolytes.
Market Restraints
- Zone-plate fabrication chokepoints:Single-source suppliers in Germany and Japan control Fresnel zone-plate lithography for sub-30nm resolution, concentrating optical component risk.
- Synchrotron access dependency:Academic users in the United States and Europe remain tethered to DOE and ESRF beamline schedules, capping throughput for transmission X-ray microscopy workflows.
- Helium scarcity:Cryogenic detector cooling relies on helium-3 and helium-4 supplies from Qatar and Russia, exposing operating cost volatility to geopolitical export controls.
Strategic Opportunities
- Laboratory-scale CT penetration:Industrial manufacturers in the United States and Germany are displacing destructive cross-sectioning with desktop computed tomography for additive manufacturing qualification.
- Dual-use export licensing:Japan's METI and the United States Bureau of Industry and Security are streamlining deemed export approvals for X-ray optics co-development with allied research consortia.
- Soft-tissue imaging protocols:Cryo-electron microscopy centers at NIH-funded institutions are adding correlative X-ray tomography for hydrated biological specimens without dehydration artifacts.
Industry Challenges
- Detector array calibration expertise:Direct-illumination sCMOS and hybrid pixel array maintenance requires specialized field engineers concentrated at synchrotron facilities and OEM headquarters.
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k) and EU MDR technical documentation preparation extends product launch cycles by 18-24 months for healthcare-targeted systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Microscopes Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission X-Ray Microscopes, Scanning X-Ray Microscopes, High-Resolution X-Ray Microscopes, Soft X-Ray Microscopes Application: Materials Science, Biology, Nanotechnology, Semiconductor Inspection End User: Academic Institutions, Research Laboratories, Industrial Manufacturing, Healthcare Facilities Technology: Computed Tomography, Phase Contrast Imaging, X-Ray Diffraction, Fluorescence Microscopy |
| Companies Covered | Carl Zeiss Microscopy, Bruker Corporation, Rigaku Corporation, Thermo Fisher Scientific, HORIBA Scientific, Matsusada Precision, Nikon Metrology, JEOL Ltd, TESCAN ORSAY HOLDING, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Microscopes Market Evolving Landscape
Zone-plate fabrication advances and detector cooling architectures are compressing the resolution-throughput tradeoff, enabling laboratory-scale instruments to replicate synchrotron-grade performance for semiconductor and materials science end-users.
Ptychographic reconstruction algorithms are unifying phase-retrieval and tomographic inversion into single-scan workflows. Battery materials researchers at German Fraunhofer institutes are adopting these methods to map lithium-ion concentration gradients across electrode thicknesses. The convergence is unifying previously separate hardware investments into unified platform architectures, reducing capital duplication for industrial quality-control labs.
The FDA's updated guidance on computational radiography quality systems is mandating traceable calibration protocols for quantitative density reconstruction. Medical device manufacturers must now document detector linearity across the full dynamic range, extending validation timelines but raising barrier-to-entry for non-specialized entrants. Dental and orthopedic implant segments are responding by consolidating supplier relationships with ISO 17025-accredited service providers.
Service unbundling is fragmenting traditional capital-plus-maintenance contracts into subscription-based uptime guarantees. Semiconductor fabs in Taiwan are negotiating performance-linked pricing where detector replacement and zone-plate refurbishment are bundled into per-wafer-inspected fees. This model is most visible in Hsinchu and Taichung Science Parks, where foundries prioritize operational expenditure flexibility over upfront capital commitments.
X-Ray Microscopes Market Segmentation
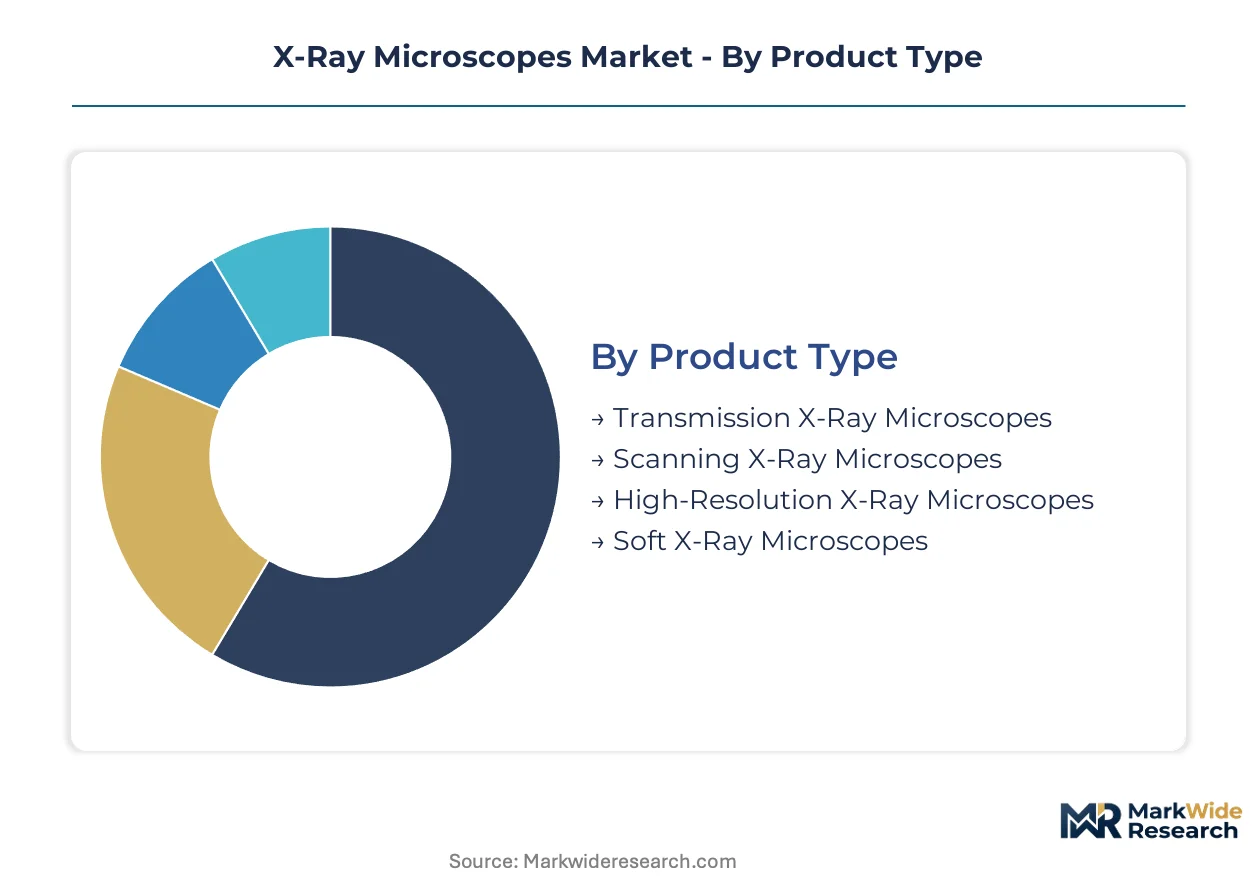
X-ray microscope segmentation reflects divergent technical requirements across synchrotron facilities, semiconductor fabs, and clinical laboratories. Supply chain configuration for zone-plate optics and detector arrays concentrates differently by product architecture and end-use environment.
Product Type:
Zone-plate fabrication capabilities concentrate in German and Japanese suppliers, creating divergent availability for resolution classes.
- Transmission X-Ray Microscopes:These instruments utilize full-field imaging through zone-plate optics to capture projection radiographs at sub-50nm resolution. Demand concentrates at synchrotron facilities in France, Germany, and the United States where DOE and ESRF beamlines subsidize capital costs for academic users. Beamline scheduling constraints limit throughput for high-volume industrial workflows.
- Scanning X-Ray Microscopes:Raster-scanning focused beams through capillary condensers enables 3D tomographic reconstruction with elemental specificity. Foundries in Taiwan and South Korea deploy these systems for wafer-level defect mapping below 10nm nodes, synchronizing procurement with TSMC and Samsung capital expenditure cycles. Ptychographic reconstruction algorithms are compressing scan times for battery electrode characterization.
- High-Resolution X-Ray Microscopes:Laboratory-scale instruments replicate synchrotron-grade performance through superconducting detector arrays. Industrial manufacturers in Germany adopt desktop configurations for additive manufacturing qualification.
- Soft X-Ray Microscopes:Water-window wavelength operation enables hydrated biological specimen imaging without dehydration artifacts. NIH-funded cryo-EM centers in the United States add correlative capabilities.
Today's leader: Scanning X-Ray Microscopes. Tomorrow's challenger: High-Resolution X-Ray Microscopes.
Application:
End-use requirements fragment across destructive versus non-destructive inspection protocols and regulatory validation pathways.
- Semiconductor Inspection:Inline process control demands sub-10nm defect detection for buried voids and overlay errors at advanced logic nodes. Taiwan and South Korean foundries expand metrology budgets fastest, prioritizing throughput over resolution for high-volume manufacturing.
- Materials Science:Battery researchers at German Fraunhofer institutes map lithium-ion concentration gradients across electrode thicknesses using phase-retrieval tomography. Solid-state electrolyte validation drives dendrite suppression studies in Japan and Germany.
- Biology:Soft-tissue imaging without sectioning artifacts attracts hydrated specimen protocols at synchrotron biology beamlines.
- Nanotechnology:Characterization of nanostructured catalysts and quantum materials occupies academic installations with flexible beamline access.
Semiconductor Inspection commands premium pricing. Materials Science shows steepest expansion trajectory among research applications.
End User:
Procurement authority and validation requirements diverge sharply across institutional funding mechanisms.
- Industrial Manufacturing:Capital-plus-maintenance contracts fragment into subscription-based uptime guarantees in Taiwan's Hsinchu Science Park. Foundries negotiate per-wafer-inspected pricing bundling detector replacement and zone-plate refurbishment.
- Academic Institutions:Synchrotron access dependency in the United States and Europe caps throughput for transmission microscopy workflows. DOE and ESRF beamline schedules determine experimental capacity.
- Research Laboratories:ISO 17025-accredited service providers consolidate supplier relationships for dental and orthopedic implant segments under FDA computational radiography guidance.
- Healthcare Facilities:EU MDR and FDA device-quality standards tighten validation requirements for diagnostic imaging systems. ISO 13485-certified configurations face 18-24 month certification timelines.
Industrial Manufacturing leads equipment revenue. Healthcare Facilities face longest procurement cycles but highest replacement premiums.
Technology:
Detector cooling architectures and reconstruction algorithm maturity stratify platform investment requirements.
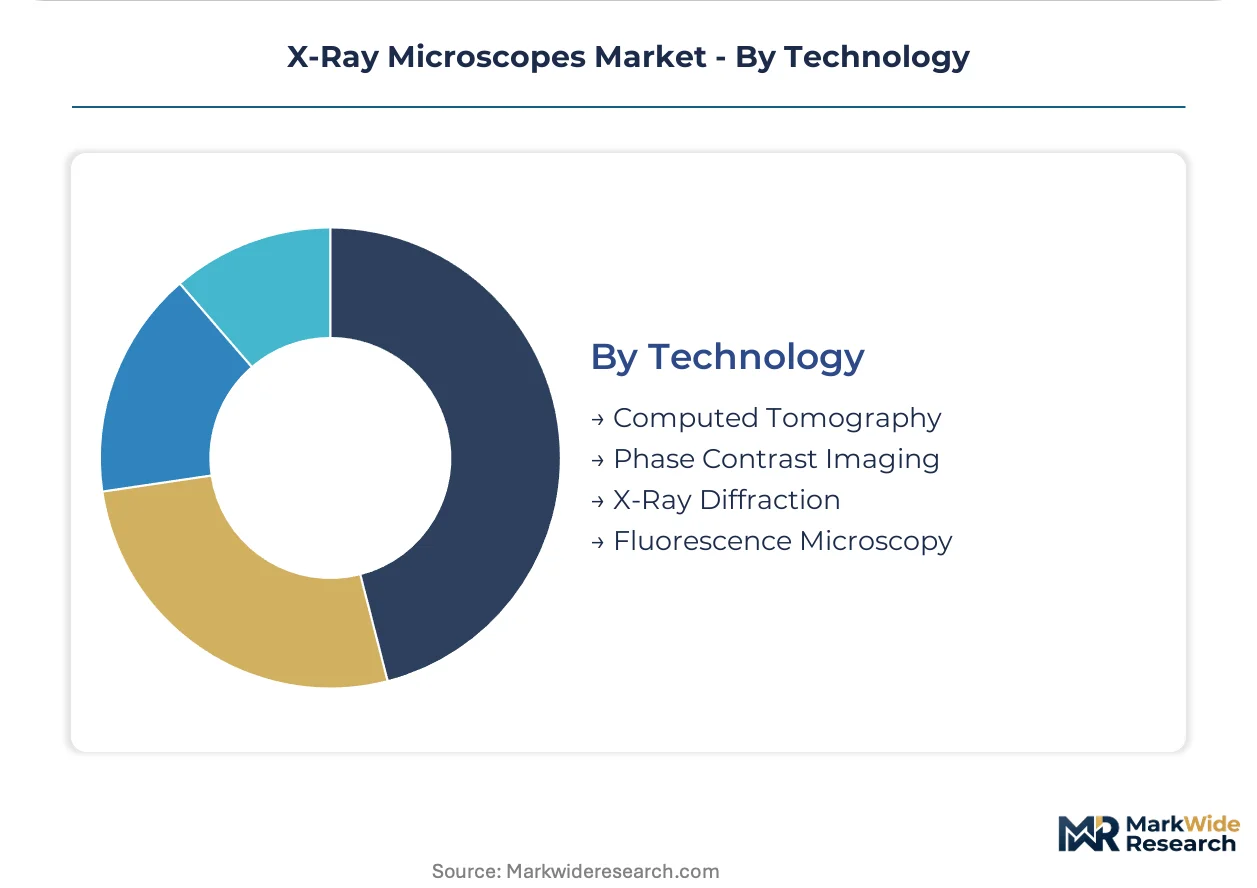
- Computed Tomography:Inline process control commands premium service contracts in industrial manufacturing. Desktop CT displaces destructive cross-sectioning for additive manufacturing qualification in the United States and Germany.
- Phase Contrast Imaging:Ptychographic reconstruction unifies phase-retrieval and tomographic inversion into single-scan workflows. Battery materials researchers adopt these methods for electrode microstructure mapping.
- X-Ray Diffraction:Crystallographic analysis complements tomographic reconstruction for stress and phase identification in metallic components.
- Fluorescence Microscopy:Elemental mapping capabilities serve environmental and geological specimen analysis with trace-element sensitivity.
Computed Tomography dominates installed base value. Phase Contrast Imaging gains share fastest through algorithm-hardware convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors semiconductor metrology procurement, synchronizing equipment cycles with TSMC and Samsung Electronics capital expenditure timelines. Foundries in Taiwan and South Korea compress defect-detection tolerances below 10 nanometers, reshaping regional demand patterns for high-resolution inspection systems.
United States
DOE-funded synchrotron facilities in California and Illinois subsidize academic access for transmission X-ray microscopy workflows. FDA computational radiography guidance mandates traceable calibration protocols for quantitative density reconstruction in medical device manufacturing. Boston and San Diego clusters concentrate battery materials research using ptychographic phase-retrieval tomography for electrode characterization.
Germany
Fraunhofer institutes map lithium-ion concentration gradients across solid-state battery electrodes using laboratory-scale computed tomography. EU MDR conformity assessment pathways tighten validation requirements for diagnostic imaging systems exported to member states. Munich and Stuttgart industrial zones adopt desktop CT configurations for additive manufacturing qualification, displacing destructive cross-sectioning protocols.
Japan
METI funds domestic X-ray optics development through national laboratory partnerships, reinforcing JIS-compliant supply chains for export markets. Solid-state electrolyte validation drives dendrite suppression studies at materials science centers in Tsukuba and Osaka. Cryogenic detector cooling architectures depend on helium-3 and helium-4 supply chains exposed to geopolitical export control volatility.
South Korea
Samsung Electronics and SK Hynix expand inline inspection stations for sub-10nm node migration at Pyeongtaek and Yongin fabrication complexes. MFDS medical device regulations align with international standards for healthcare imaging system validation. Government semiconductor subsidies accelerate metrology budget expansion for wafer-level defect mapping with three-dimensional spatial resolution.
Taiwan
TSMC capital expenditure cycles determine procurement timing for scanning X-ray microscopes at Taichung and Tainan Science Parks. Foundries negotiate per-wafer-inspected pricing models bundling detector replacement and zone-plate refurbishment into operational expenditure structures. National Synchrotron Radiation Research Center beamline access supports academic-industrial collaboration on advanced packaging failure analysis.
X-Ray Microscopes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue laboratory-scale configurations replicating synchrotron-grade performance. The vendor base stratifies across three archetypes: precision optics specialists controlling Fresnel zone-plate lithography, detector array integrators with superconducting cooling architectures, and full-platform assemblers bundling hardware with algorithmic reconstruction software. Competitive positioning depends on captive supply agreements for optical components and subscription-based uptime guarantee contracts displacing traditional capital-plus-maintenance structures.
Among German and Japanese precision optics fabricators, Carl Zeiss Microscopy and Rigaku Corporation exemplify the optics-specialist archetype through their geographic concentration in established manufacturing clusters. Bruker Corporation represents the detector-technology tier with its superconducting sensor capabilities. These three anchors demonstrate how regional supply chain configuration shapes competitive differentiation in high-resolution imaging markets.
| Leading Market Players |
|---|
| Carl Zeiss Microscopy |
| Bruker Corporation |
| Rigaku Corporation |
| Thermo Fisher Scientific |
| HORIBA Scientific |
| Matsusada Precision |
| Nikon Metrology |
| JEOL Ltd |
| TESCAN ORSAY HOLDING |
| Others |
Value Network & Pricing Analysis
Per-wafer-inspected pricing models at Taiwan's Hsinchu Science Park are forcing OEMs to absorb zone-plate refurbishment costs into operational expenditure structures, compressing margins on hardware sales while expanding service revenue pools.
Pricing Analysis
Input-cost pass-through from helium-4 supply volatility and Fresnel zone-plate lithography bottlenecks is intensifying pricing pressure at the premium tier. Three-tier pricing structure across synchrotron-grade, laboratory-scale, and desktop configurations separates resolution performance classes. Cost compression in entry-level CT systems reflects detector array commoditization from South Korean suppliers. Semiconductor fabs exhibit lowest price sensitivity due to capital expenditure flexibility, while academic institutions dependent on DOE beamline subsidies face procurement freezes when federal budgets tighten.
Supply Chain Analysis
Specialized optical fabrication workforce availability in Jena and Osaka anchors zone-plate production, constraining throughput expansion for sub-30nm resolution classes. Manufacturing concentrates in Germany, Japan, and the United States for precision optics, with detector array assembly in South Korea and the United States. Cryogenic cooling architectures draw from helium-3 and helium-4 supply chains exposed to Qatari and Russian export restrictions. Single-source vulnerability in Fresnel lithography equipment creates chokepoint risk. Distribution runs through direct OEM sales for semiconductor fabs and synchrotron facilities, with regional service partners handling academic and healthcare installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on algorithm-hardware convergence compressing service delivery costs, alongside foundry demand for subscription-based uptime guarantees displacing capital-intensive procurement.
For Market Incumbents: To counter ptychographic algorithm commoditization by software-only entrants, lock in captive supply agreements for German and Japanese zone-plate fabricators while expanding superconducting detector refurbishment capacity at Taiwan service hubs. Prioritize ISO 13485 certification investments to capture healthcare replacement cycles under EU MDR tightening. For New Entrants and Emerging Players: Battery materials research laboratories in Germany and Japan represent the most penetrable buyer archetype, underserved by legacy synchrotron-dependent workflows. Target desktop CT configurations for additive manufacturing qualification in Stuttgart and Munich industrial zones. Lead with phase-retrieval software licensing bundled with third-party hardware to bypass capital-intensive detector development. For Investors and Strategic Acquirers: Asymmetric upside sits with laboratory-scale platform assemblers bridging synchrotron-grade performance to industrial manufacturing budgets. Five-to-ten year viability favors firms with backward integration into zone-plate fabrication or superconducting cooling architectures. Watch for TSMC capital expenditure cycle inflections as demand pulse indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Zone-Plate Fabrication Backward Integration | Captive supply of Fresnel optics from Jena or Osaka facilities secures resolution roadmap control against single-source risk. |
| Subscription-Based Uptime Guarantee Launch | Per-wafer-inspected pricing at Hsinchu Science Park aligns OEM revenue with foundry operational expenditure preferences. |
| Ptychographic Algorithm Platform Integration | Single-scan phase-retrieval workflows at Fraunhofer institutes reduce capital duplication for battery electrode characterization. |
| ISO 13485 Certification Pathway Completion | FDA computational radiography guidance mandates traceable calibration protocols for diagnostic imaging system replacements. |
| Helium-4 Recycling Infrastructure Partnership | Qatari supply exposure necessitates closed-loop cooling architectures to stabilize detector operating cost volatility. |
Research Methodology
Bottom-up semiconductor metrology demand modeling reconciled against top-down X-ray optics supply tracking forms the analytical core of this study. Primary interviews with foundry process control engineers, synchrotron beamline scientists, biomedical imaging procurement managers, and battery materials research directors combined with secondary validation from FDA 510(k) filings, DOE facility user statistics, METI technology roadmaps, and EU MDR conformity assessment databases. Triangulation across installation base audits and capital expenditure disclosure analysis ensures cross-verification of demand pulses.
Historical trendline analysis of TSMC and Samsung Electronics equipment procurement cycles established baseline growth patterns across the projection horizon. Segmentation modeling spans product architecture, application vertical, end-user funding mechanism, and detector cooling technology dimensions. CAGRs derive from regression analysis of beamline construction timelines, foundry node migration schedules, and regulatory certification backlog data.
Underlying measurement precision varies by segment; semiconductor inspection and synchrotron facility deployments carry tighter precision than dispersed academic installations. Forecasts reflect documented assumptions regarding helium supply stability, zone-plate fabrication yield rates, and foundry capital expenditure continuity. Material deviation in EU MDR enforcement intensity or DOE beamline operating schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Automotive 3D Imaging Market
Imaging
Photo Kiosk Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Digital Image Processing Market
Imaging
Phosphor Screen Scanner Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Event Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
Digital Microscope Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Machine Vision System and Services Market
Imaging
Global Digital Binoculars Market
Imaging
Specific Imaging Solution Market
Imaging
Hyperspectral Imaging Camera Market