
 Optical Sensing Market | 2026-2036
Optical Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Sensing Market Analysis
Healthcare provider procurement is rotating toward diagnostic imaging and wearable monitoring platforms, displacing traditional industrial buyers as the fastest-growing demand archetype. Sony Group Corporation leverages its CMOS image sensor foundry scale to dominate medical and automotive supply chains. Hamamatsu Photonics K.K. sustains leadership in photomultiplier tubes and high-sensitivity detectors for precision instrumentation. ams-OSRAM AG specializes in miniaturized spectral sensing modules that anchor next-generation consumer health devices.
Optical sensing encompasses systems that detect, measure, and interpret light-based signals across ultraviolet through infrared wavelengths, typically resolving parameters such as intensity, phase, or polarization with nanometer-scale precision in interferometric configurations. These platforms serve industrial and commercial functions spanning non-contact dimensional inspection, biochemical assay readout, and autonomous navigation obstacle detection. Image sensors occupy the largest revenue pool due to smartphone and automotive camera ubiquity, while Lidar technology represents the fastest-expanding segment as robotaxi and advanced driver-assistance deployments multiply. Fiber optic sensors retain entrenched positions in structural health monitoring and oilfield distributed temperature sensing where electromagnetic immunity proves decisive.
FDA digital health pre-certification and EU MDR device classification impose validation burdens that favor established suppliers with quality management infrastructure. EPA emissions monitoring mandates and OSHA machine guarding standards amplify demand for photoelectric proximity sensors in North American manufacturing. Stakeholders must calibrate R&D portfolios against divergent regional compliance timelines while tracking automotive OEM qualification shifts toward solid-state Lidar architectures.
Market Dynamics
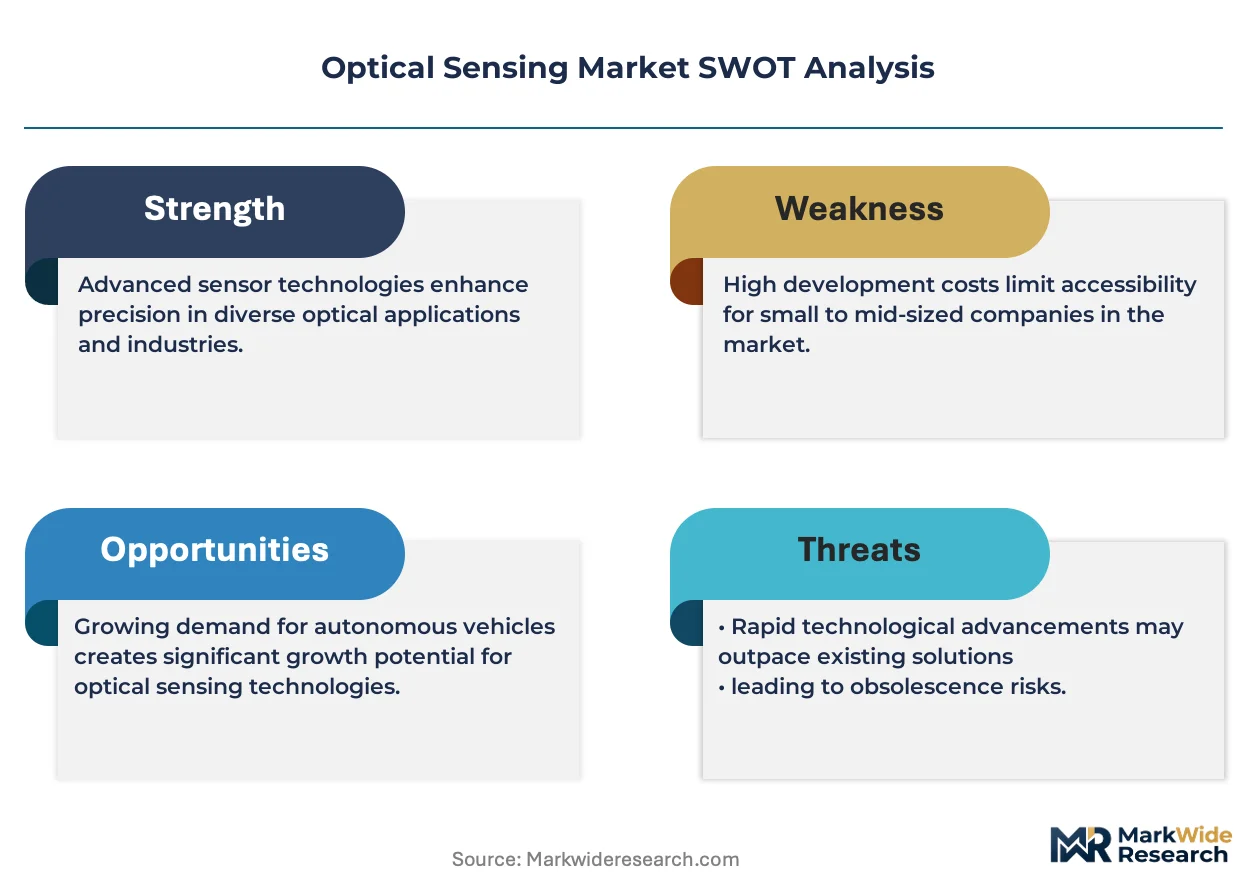
Solid-state Lidar architectures are compressing qualification timelines for automotive OEMs while FDA digital health pre-certification pathways restructure supplier selection criteria for diagnostic platforms.
Growth Catalysts
- EU AI Act compliance mandates:Medical device manufacturers accelerate sensor-integrated diagnostic platform development to meet conformity assessment requirements for AI-enabled imaging systems.
- Automotive safety clusters in Germany:Robotaxi deployments and ADAS penetration concentrate procurement demand for photoelectric and time-of-flight systems around Stuttgart and Munich engineering hubs.
- Fiber optic sensing:Distributed temperature and strain monitoring applications expand in oilfield infrastructure and civil engineering where electromagnetic immunity overrides electrical alternatives.
Market Restraints
- Indium gallium arsenide wafer supply:Near-infrared detector production faces input concentration from limited foundry capacity in East Asian supply chains.
- EU MDR device classification:Extended clinical evaluation and notified body review timelines delay market entry for novel optical diagnostic platforms.
- Cost structure of precision interferometry:Nanometer-scale measurement systems require stabilized optical benches and vibration isolation that inflate capital expenditure thresholds for industrial buyers.
Strategic Opportunities
- Consumer health wearables:Miniaturized spectral sensing modules anchor next-generation hydration and glucose monitoring devices for direct-to-consumer channels.
- US EPA emissions monitoring:Continuous opacity and particulate measurement mandates expand addressable market for UV-Vis absorption photometers at power generation and cement production facilities.
- Photonics-electronics convergence:Silicon photonics integration with CMOS readout circuits enables wafer-scale manufacturing economics for coherent optical transceivers and sensing arrays.
Industry Challenges
- Specialized optomechanical engineering talent:Precision lens design and freeform fabrication expertise concentrates in legacy optics hubs, constraining scaling for emerging sensor developers.
- FDA 510(k) predicate device matching:Novel optical diagnostic modalities struggle to establish substantial equivalence pathways, prolonging regulatory submission preparation.
- Legacy manufacturing equipment integration:Inline inspection systems must interface with established PLC and SCADA architectures without disrupting throughput-calibrated production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Sensing Market |
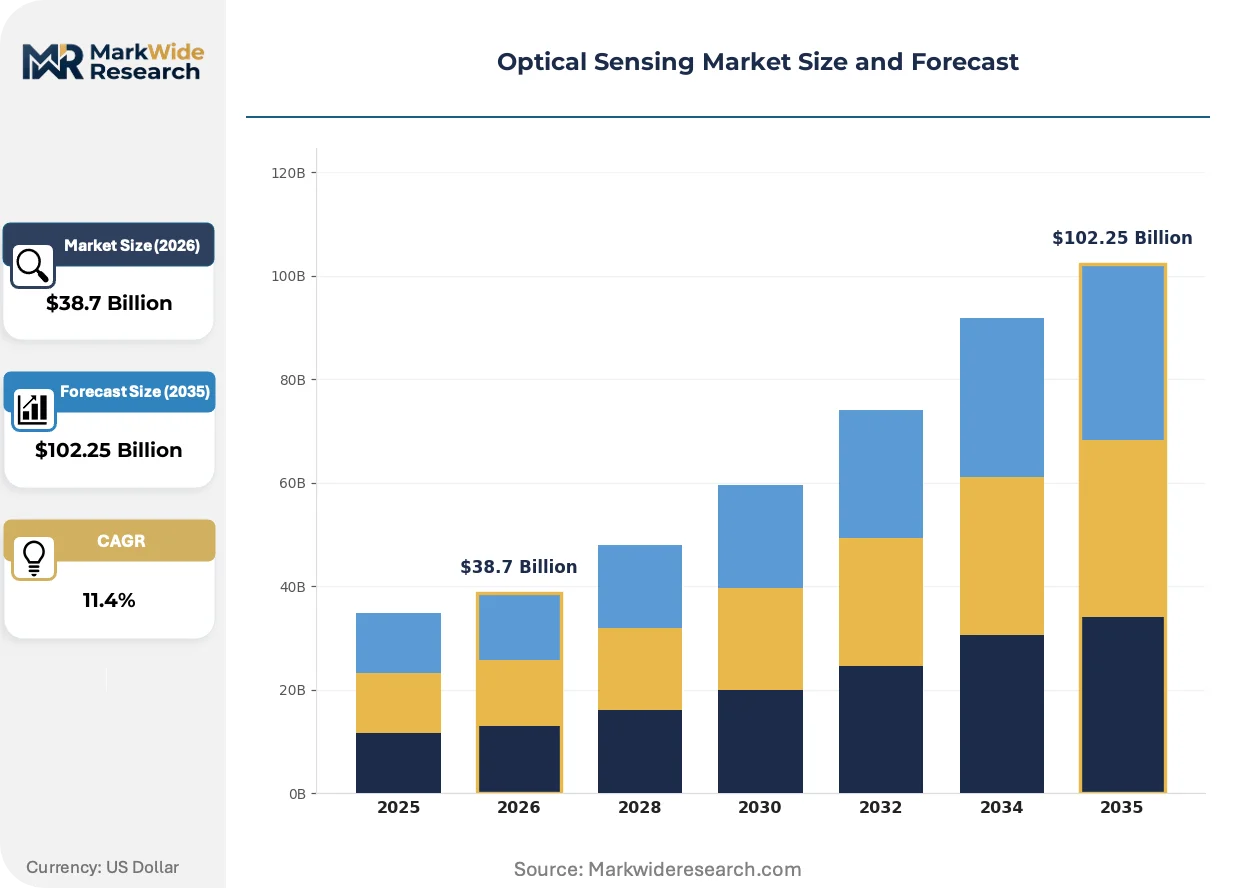
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Sensors, Photoelectric Sensors, Image Sensors, Laser Sensors Technology: Interferometry, Tomography, Spectroscopy, Lidar Application: Environmental Monitoring, Healthcare Diagnostics, Industrial Automation, Automotive Safety End User: Healthcare Providers, Manufacturing Firms, Energy Companies, Research Institutions |
| Companies Covered | Sony Group Corporation, Samsung Electronics, Hamamatsu Photonics K.K., STMicroelectronics N.V., Texas Instruments Incorporated, ams-OSRAM AG, Analog Devices, Inc., Broadcom Inc., ROHM Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Sensing Market Emerging Trajectories
Photonic system architectures are fragmenting across performance-optimized versus cost-optimized design philosophies, forcing component suppliers to recalibrate process technology roadmaps.
Solid-state beam steering is bifurcating the Lidar supply base. Microelectromechanical mirrors and optical phased arrays eliminate mechanical rotation mechanisms. Automotive Tier-1 suppliers are dual-sourcing flash and scanning architectures to hedge qualification risk. The technology is bifurcating contract manufacturer capabilities between precision optomechanical assembly and semiconductor wafer processing.
EU MDR Annex XVI expansion reclassifies certain wellness devices with diagnostic claims as medical devices. Optical sensors for pulse oximetry and blood pressure estimation now require notified body certification. German notified bodies report extended queue lengths, compressing effective market access windows for 2025-2026 product launches.
Hospital procurement consortia are consolidating imaging equipment purchasing across integrated delivery networks. Capital equipment committees now mandate interoperability with existing PACS infrastructure and predictive maintenance service agreements. This concentration is most visible in US academic medical centers where procurement volume shifts toward multi-year sole-source arrangements with established modality suppliers.
Optical Sensing Market Segmentation
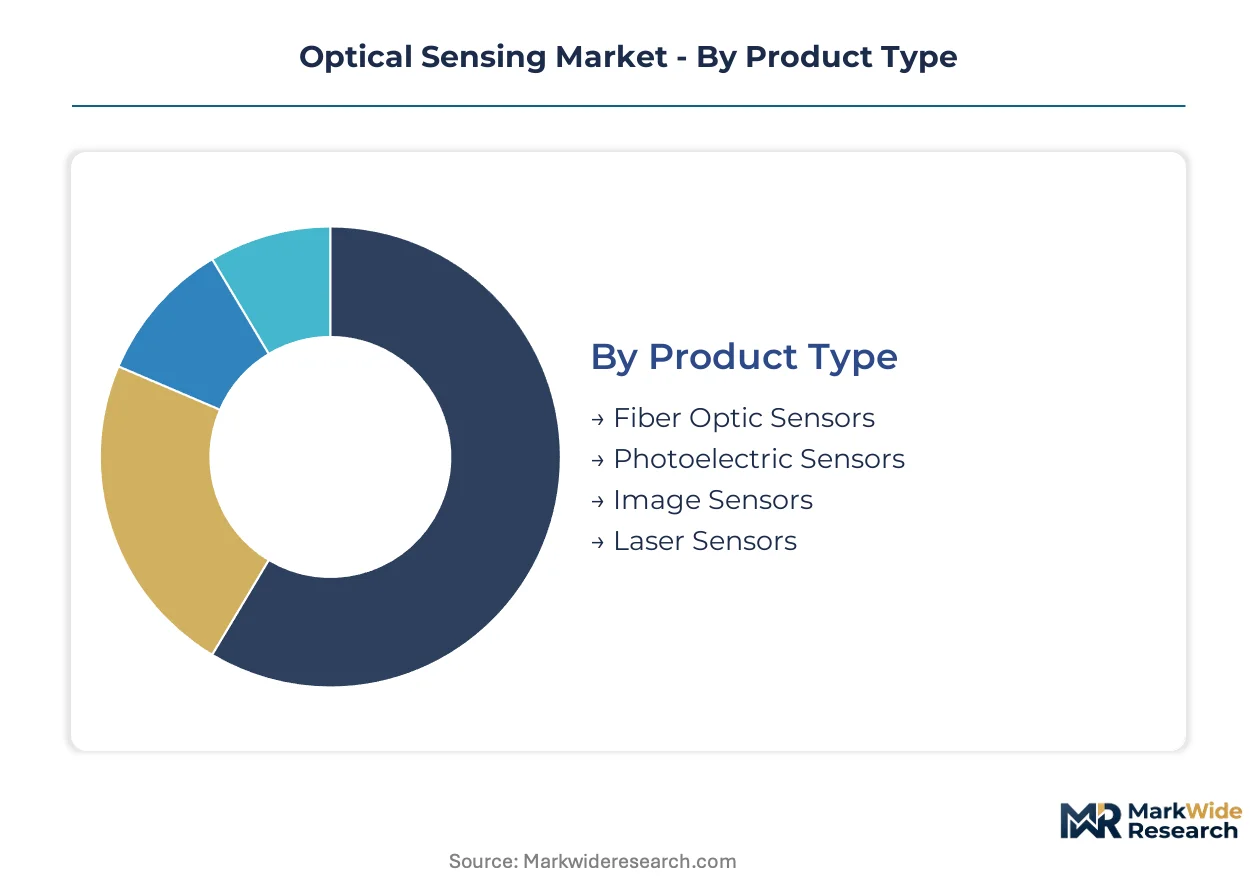
Optical sensing procurement patterns diverge sharply across product architectures and end-use contexts. Healthcare diagnostics and automotive safety clusters concentrate demand in distinct technology configurations with incompatible qualification timelines.
Product Type:
Image sensors and photoelectric systems anchor domestic manufacturing bases in Japan and South Korea, while fiber optic and laser sensor production concentrates in export-oriented German and US facilities.
- Image Sensors:CMOS architectures dominate smartphone and automotive camera integration with sub-micron pixel pitch scaling. Demand concentrates in Stuttgart automotive safety clusters and Shenzhen consumer electronics manufacturing, driven by ADAS camera module qualification programs and FDA digital health imaging pre-certification pathways.
- Photoelectric Sensors:Through-beam and retro-reflective configurations resolve object presence and distance in industrial automation environments. German manufacturing firms and US automotive stamping plants drive procurement, constrained by OSHA machine guarding standard compliance costs and EU machinery directive safety integrity requirements.
- Fiber Optic Sensors:Distributed temperature and strain monitoring leverages electromagnetic immunity for oilfield infrastructure. Energy companies in Texas and North Sea operations specify these for subsea pipeline monitoring.
- Laser Sensors:Time-of-flight and triangulation architectures enable precision dimensional inspection. Industrial automation integrators in Bavaria and Michigan deploy these for inline quality verification.
Image sensors hold the largest share; momentum sits with laser sensors as solid-state architectures compress automotive qualification timelines.
Technology:
Cost tier stratification separates laboratory-grade precision systems from volume-manufactured automotive components, with interferometry and spectroscopy commanding premium positioning against commoditized Lidar modules.
- Lidar:Solid-state beam steering via optical phased arrays and microelectromechanical mirrors eliminates mechanical rotation. Robotaxi deployments in California and Arizona concentrate procurement demand, though Indium gallium arsenide wafer supply constraints from East Asian foundries limit near-infrared detector scaling.
- Interferometry:Nanometer-scale displacement measurement requires stabilized optical benches and active vibration isolation. Precision instrumentation manufacturers in Germany and Switzerland serve semiconductor lithography and gravitational wave detection applications, facing capital expenditure thresholds that constrain industrial buyer adoption.
- Spectroscopy:UV-Vis and infrared absorption platforms enable chemical composition analysis. US EPA emissions monitoring mandates at power generation facilities expand addressable market for continuous opacity measurement systems.
- Tomography:Optical coherence and diffuse optical techniques reconstruct three-dimensional tissue or material structure. Healthcare providers in US academic medical centers integrate these with existing PACS infrastructure under multi-year procurement agreements.
Interferometry commands premium pricing; Lidar represents the steepest expansion trajectory as solid-state architectures displace mechanical scanning.
Application:
Volume concentration favors automotive safety and industrial automation, while margin capture concentrates in healthcare diagnostics where FDA 510(k) predicate device matching extends regulatory timelines.
- Automotive Safety:ADAS and autonomous navigation systems fuse camera, Lidar, and radar inputs for obstacle detection. German engineering hubs around Munich and Stuttgart concentrate Tier-1 supplier procurement, with dual-sourcing strategies hedging flash versus scanning Lidar qualification risk.
- Healthcare Diagnostics:Wearable monitoring and imaging platforms integrate spectral and interferometric sensing. EU MDR Annex XVI reclassification of wellness devices with diagnostic claims compresses market access windows as German notified bodies report extended queue lengths.
- Industrial Automation:Inline inspection and machine positioning systems deploy photoelectric and laser sensors. Manufacturing firms in the US Midwest and German Ruhr region specify these for PLC and SCADA integration without production line disruption.
- Environmental Monitoring:Continuous emissions and water quality measurement leverages UV-Vis photometry and fiber optic distributed sensing. EPA mandates and EU Green Deal reporting requirements structure procurement specifications.
Automotive safety holds the largest share; healthcare diagnostics is climbing the fastest as procurement rotates toward diagnostic imaging platforms.
End User:
Customer type determines procurement modality, with healthcare providers consolidating through integrated delivery networks while energy companies specify long-service-life configurations for remote infrastructure.
- Healthcare Providers:Hospital procurement consortia consolidate imaging equipment purchasing across integrated delivery networks. US academic medical centers mandate interoperability with existing infrastructure and predictive maintenance agreements, shifting volume toward established modality suppliers.
- Manufacturing Firms:Capital equipment committees evaluate total cost of ownership across sensor lifecycle. German automotive OEMs and US metalworking operations prioritize qualification speed and legacy equipment integration.
- Energy Companies:Oilfield operators and power utilities specify distributed fiber optic sensing for subsea and high-voltage environments where electromagnetic immunity overrides electrical alternatives.
- Research Institutions:National laboratories and university physics departments procure precision interferometric systems for fundamental measurement applications, tolerating extended lead times for custom configurations.
Manufacturing firms hold the largest share; healthcare providers are gaining share fastest as procurement consolidates around sensor-integrated diagnostic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Berlin high-speed rail corridor and North Sea-Baltic pipeline interconnects position Germany as the logistics backbone for European optical component distribution. Dense fiber optic trunk lines radiating from Frankfurt's internet exchange underpin data-intensive sensing applications across the continent.
United States
Silicon Valley venture deployment and Detroit automotive engineering clusters drive Lidar and CMOS sensor procurement. FDA digital health pre-certification pathways restructure supplier selection for diagnostic platforms. Austin and Phoenix semiconductor fabs anchor photonics-electronics convergence manufacturing.
Germany
Stuttgart automotive safety clusters and Munich robotaxi engineering hubs concentrate demand for solid-state Lidar and time-of-flight systems. EU AI Act compliance mandates accelerate sensor-integrated diagnostic platform development. Ruhr region industrial automation integrators deploy photoelectric sensors for PLC-compatible inline inspection.
Japan
Tokyo-Osaka precision manufacturing corridor and Hamamatsu photonics cluster sustain leadership in photomultiplier tubes and high-sensitivity detectors. METI technology roadmaps prioritize silicon photonics integration. Sendai semiconductor foundries supply CMOS image sensors for medical and automotive supply chains.
China
Yangtze River Delta consumer electronics manufacturing and Shenzhen hardware ecosystem absorb image sensor volume for smartphone integration. NMPA medical device classification and dual carbon goals structure environmental monitoring procurement. Beijing-Tianjin-Hebei corridor concentrates Lidar assembly for domestic robotaxi deployments.
South Korea
Seoul Capital Area display panel fabs and Busan-Ulsan automotive component clusters drive photoelectric sensor demand. MFDS digital health guidance shapes wearable monitoring platform certification. Samsung Electronics and SK Hynix foundry capacity anchors CMOS sensor supply for Asia-Pacific smartphone OEMs.
Optical Sensing Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base stratifies between scale-driven CMOS foundry operators and precision instrumentation boutiques. Three archetypes dominate: semiconductor conglomerates with captive sensor divisions, pure-play photonics component suppliers, and diversified industrial electronics groups. Competitive moves concentrate on strategic partnerships for automotive qualification and backward integration into specialized wafer processing.
Among Japan-based precision instrumentation specialists, Hamamatsu Photonics K.K. exemplifies the high-sensitivity detector archetype, while Sony Group Corporation occupies a position representing scale-driven CMOS image sensor supply. German-listed ams-OSRAM AG sits within the miniaturized spectral sensing module tier, anchoring consumer health device integration strategies. These three entities represent distinct competitive vectors: foundry scale, precision measurement heritage, and photonics miniaturization expertise.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Samsung Electronics |
| Hamamatsu Photonics K.K. |
| STMicroelectronics N.V. |
| Texas Instruments Incorporated |
| ams-OSRAM AG |
| Analog Devices, Inc. |
| Broadcom Inc. |
| ROHM Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
FDA digital health pre-certification and EU MDR device classification simultaneously gate supply qualification and create price differentiation between certified and uncertified sensor tiers. Automotive OEMs in Germany pay premiums for solid-state Lidar modules that compress qualification timelines, while industrial buyers in the US Midwest negotiate volume discounts on photoelectric sensors for PLC-integrated machine guarding.
Pricing Analysis
Volume-discount tiering separates automotive OEM procurement from industrial automation spot purchasing. Pricing stratifies across FDA-cleared medical grade, automotive-qualified industrial grade, and uncertified consumer tiers. Cost compression in CMOS image sensors intensifies as smartphone OEMs consolidate around Sony and Samsung foundry supply. Healthcare providers exhibit lowest price sensitivity due to reimbursement-anchored procurement, while metalworking operations in the US Rust Belt drive hardest bargain on photoelectric proximity systems.
Supply Chain Analysis
Inbound logistics costs from East Asian foundries to Stuttgart automotive clusters hinge on Rotterdam port throughput and Rhine barge availability. Indium gallium arsenide wafer supply draws from limited East Asian foundry capacity, while CMOS sensor fabrication centers on Japan and South Korea. Single-source vulnerability concentrates in near-infrared detector substrates. Distribution runs through Frankfurt's logistics hub for European industrial automation integrators and through Shenzhen's hardware ecosystem for consumer electronics volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment. FDA 510(k) predicate device matching and EU MDR notified body queue positions create switching costs that protect incumbent revenue streams.
For Market Incumbents: Secure backward integration into specialized wafer processing to hedge Indium gallium arsenide supply concentration. Lock multi-year sole-source agreements with US academic medical centers before hospital procurement consortia complete vendor consolidation. Threat: Silicon photonics startups eroding CMOS sensor margins through wafer-scale integration. For New Entrants and Emerging Players: Anchor in US EPA emissions monitoring mandates for UV-Vis photometry, where established suppliers lack dedicated product lines. Target continuous opacity measurement at power generation facilities as the most penetrable application. Go-to-market angle: bundled predictive maintenance service agreements that incumbent photonics boutiques cannot match. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across silicon photonics sub-segments as CMOS foundries absorb photonics-electronics convergence manufacturing. Long-term viability favors platforms with captive hospital system relationships and automotive Tier-1 qualification track records. Acquisition target archetype: precision interferometry boutiques with gravitational wave or semiconductor lithography reference customers. Signal to watch: German notified body queue length compression as EU MDR Annex XVI reclassification wave peaks.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Lidar Qualification | Automotive OEMs in Stuttgart and Munich compress validation timelines for robotaxi deployment. |
| FDA Digital Health Pre-Certification | Sensor-integrated diagnostic platforms secure streamlined pathways for AI-enabled imaging systems. |
| Silicon Photonics Integration | Wafer-scale manufacturing economics enable coherent optical transceiver cost reduction for sensing arrays. |
| EU MDR Annex XVI Compliance | Wellness device reclassification forces optical sensor manufacturers into notified body certification queues. |
| Hospital Procurement Consolidation | Integrated delivery networks shift imaging equipment volume toward multi-year sole-source arrangements. |
Methodological Framework
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, Tier-1 automotive supplier procurement leads, and industrial automation integrators anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EU MDR notified body registration databases, SEC 10-K disclosures of listed photonics suppliers, and IHS Markit vehicle production data. Bottom-up segment sizing triangulated against top-down macroeconomic absorption models.
Sensitivity analysis tested forecast robustness across automotive Lidar penetration scenarios and healthcare diagnostic imaging replacement cycles. Segmentation dimensions modeled include product architecture, technology tier, application context, and end-user procurement modality. CAGRs derived from regression against historical adoption curves in adjacent sensor markets, with inputs from semiconductor capital expenditure cycles and regulatory approval velocity.
Decision-makers should treat outputs as directional under assumptions of stable EU AI Act implementation timelines and continued automotive OEM dual-sourcing behavior; material deviation would warrant model refresh. Specific risks include Indium gallium arsenide supply disruption, German notified body capacity constraints, and FDA predicate device matching failures for novel optical modalities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Lasers Market
Optics
Fiber Optic Connectivity Market
Optics
Fiber Optics Market
Optics
Interchangeable Lens Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Smart Vision Systems Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Fiber Optic Preform Market
Optics
Middle East and Africa Tunable Laser Market
Optics
MEMS Mirrors Market
Optics
Optical Imaging Market
Optics
Picosecond Lasers Market
Optics
Photonic Crystals Market
Optics
Fiber Optic Amplifier Market
Optics
Fiber Optic Switch Market
Optics
Collimating Lens Market