
 EUV Pellicle Market | 2026-2036
EUV Pellicle Market Size, Share, and Industry Trends Forecast 2026-2036
EUV Pellicle Market Insights
The EU F-Gas Regulation is hardening compliance requirements for fluoropolymer films used in EUV pellicle manufacturing, pushing suppliers toward alternative chemistries. FUJIFILM Holdings Corporation leverages its deep materials science portfolio to develop next-generation pellicle membranes with reduced fluorinated content. Entegris, Inc. anchors North American supply through its contamination control specialization for semiconductor fabs. ASML Holding N.V. dominates equipment-integrated pellicle roadmaps by aligning component specifications with its EUV scanner generations.
An EUV pellicle is a thin-film membrane, typically 50 nanometers or less in thickness, suspended over a photomask to protect it from particle contamination during extreme ultraviolet lithography exposure. The membrane transmits EUV radiation at 13.5 nanometers wavelength while maintaining structural integrity under high-power source illumination, enabling continuous chip production without mask degradation. Advanced Pellicles command attention due to their compatibility with high-NA EUV systems where power densities stress conventional materials. Silicon-based pellicles sustain premium positioning because crystalline substrates offer superior thermal stability compared to polymer alternatives during extended exposure cycles.
EPA oversight in the United States and REACH in Europe constrain fluoropolymer supply chains, while Japan's METI guides domestic pellicle makers through JIS standards for semiconductor materials. These frameworks elevate qualification barriers for new entrants and reward incumbent suppliers with certified material pipelines. Stakeholders must monitor high-NA lithography deployment timelines and corresponding pellicle power-handling requirements to align R&D investments with actual fab upgrade cycles.
Market Dynamics
High-NA EUV lithography deployment is rewriting power-density requirements for pellicle membranes, forcing materials suppliers to abandon fluoropolymer chemistries before regulatory deadlines accelerate.
Growth Catalysts
- High-NA Lithography Scaling:Logic and memory fabs in Taiwan, South Korea, and the United States are qualifying next-generation pellicles for 0.55 numerical aperture systems that demand higher EUV transmission efficiency.
- EU F-Gas Regulation:The European framework is mandating phase-downs of fluorinated greenhouse gases used in pellicle films, creating urgent demand for compliant alternative chemistries among membrane suppliers.
- Contamination Control Intensification:Semiconductor manufacturers are tightening particle specifications for photomask protection as 3nm and 2nm node yields become increasingly sensitive to mask defects.
Market Restraints
- Fluoropolymer Input Volatility:Perfluorinated material supply chains face disruption from EPA oversight in the United States and REACH restrictions in Europe, compressing qualified feedstock availability.
- Single-Source Concentration Risk:Crystalline silicon substrate production for premium pellicles concentrates among Japanese specialty material suppliers, creating vulnerability to geographic supply shocks.
- Thermal Dissipation Ceiling:Polymer-based membranes hit structural degradation limits below the power thresholds required for future high-NA exposure tools, blocking their roadmap viability.
Strategic Opportunities
- Silicon-Based Membrane Expansion:Crystalline silicon pellicles offer thermal stability that polymer alternatives cannot match, positioning them for capture of high-NA tool retrofits across leading-edge fabs.
- Alternative Chemistry Development:Metal oxide and carbon nanotube film research is accelerating under Japan's METI guidance through JIS standards for next-generation semiconductor materials.
- Equipment-Integrated Roadmaps:Scanner manufacturers are embedding pellicle specifications into tool generation planning, creating captive demand channels for qualified membrane suppliers.
Industry Challenges
- Materials Science Talent Scarcity:EUV optics and thin-film physics expertise concentrates among aging specialists in Japan and the Netherlands, constraining R&D team expansion for new entrants.
- Qualification Timeline Compression:Fab customers demand 18-month certification cycles for new pellicle materials while simultaneously requiring multi-year reliability data, stretching validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EUV Pellicle Market |
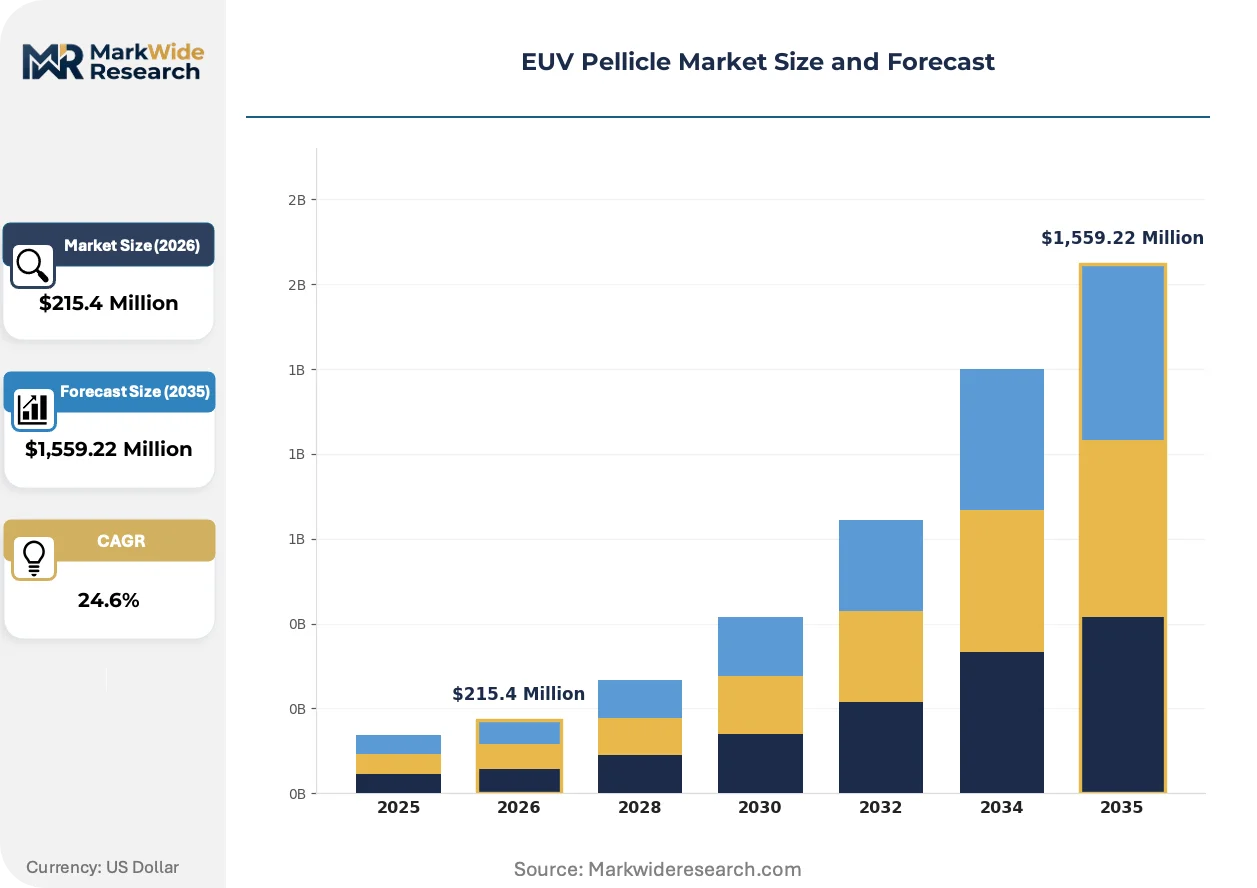
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,559.22 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pellicles, Advanced Pellicles, Composite Pellicles, Protective Pellicles Material: Quartz, Silicon, Polymer, Glass End User: Semiconductor Manufacturers, Research Institutions, Electronic Component Producers, Photomask Suppliers Application: Chip Production, Mask Quality Inspection, Lithography, Surface Protection |
| Companies Covered | FUJIFILM Holdings Corporation, SÜSS MicroTec SE, ASML Holding N.V., AGC Inc., Entegris, Inc., Mitsui Chemicals, Inc., Toppan Inc., Sumitomo Chemical Co., Ltd., Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EUV Pellicle Market Trends and Innovations
Materials innovation and regulatory chemistry restrictions are converging to accelerate pellicle architecture transitions before high-NA lithography reaches volume production.
Silicon-based pellicle membranes are rewriting thermal management expectations for EUV exposure systems. These crystalline substrates transmit 13.5nm radiation while dissipating heat loads that destroy polymer alternatives within seconds. Leading logic manufacturers in Taiwan and South Korea are prioritizing silicon pellicle qualification for their first high-NA production lines. The technology is compressing the viable supplier base to those with semiconductor-grade silicon processing capabilities.
REACH and the EU F-Gas Regulation are hardening compliance boundaries for fluoropolymer film manufacturing. The European frameworks classify perfluorinated compounds as substances of very high concern, triggering authorization requirements that add 12-24 months to material qualification timelines. Membrane suppliers serving European fabs or exporting through European distribution channels are reformulating product lines to eliminate fluorinated content entirely.
Mask protection procurement is consolidating around equipment-integrated supply agreements rather than standalone component purchasing. Semiconductor manufacturers are negotiating multi-year pellicle supply contracts bundled with scanner maintenance and upgrade services. This bundling is displacing spot-market purchasing for leading-edge fabs in the United States and Japan. The shift concentrates purchasing leverage among the three dominant scanner OEMs and their qualified membrane partners.
EUV Pellicle Market Segmentation
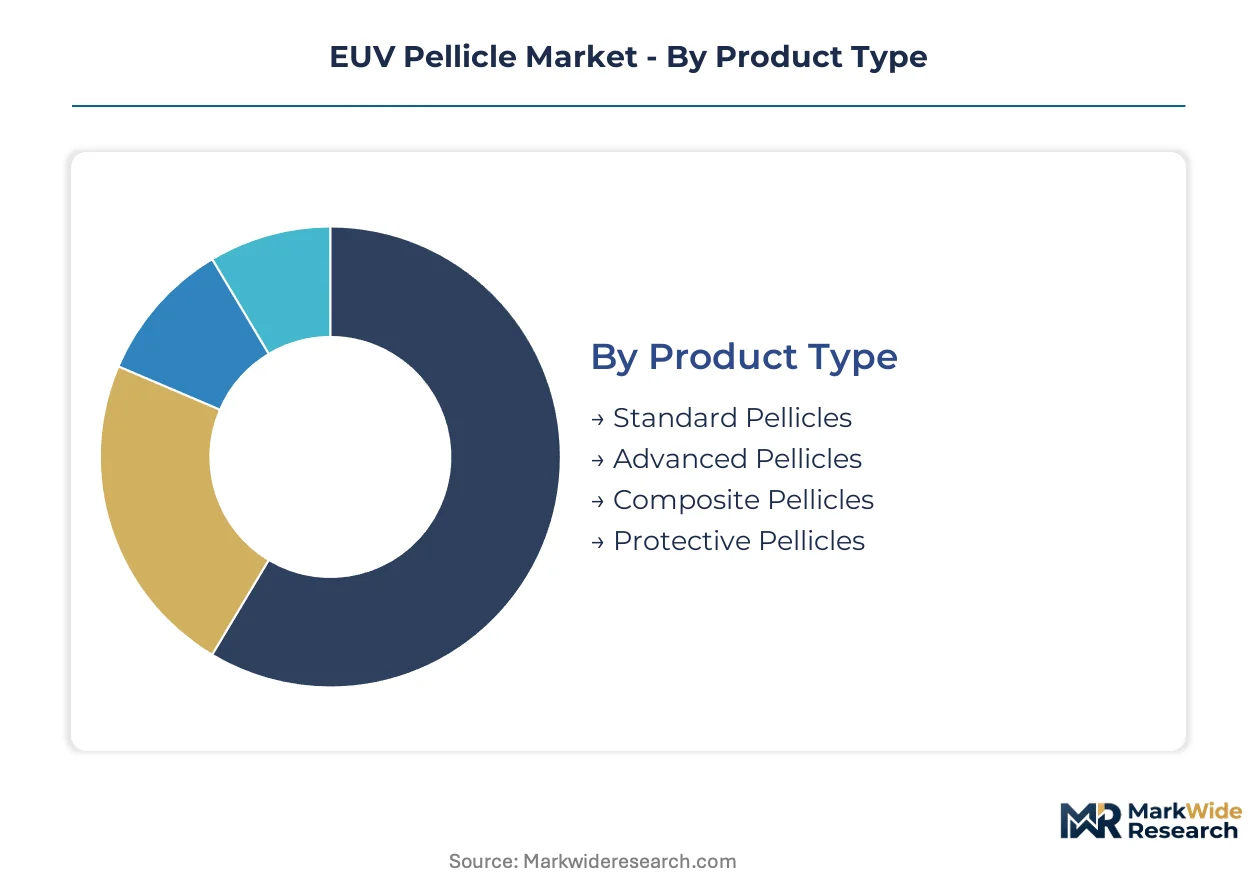
EUV pellicle segmentation reveals how membrane specifications diverge across scanner generations and fab process nodes. Material composition and thermal tolerance thresholds determine which segments capture high-NA tool placements versus legacy system retrofits.
Product Type:
Integration depth separates standalone pellicle procurement from equipment-bundled supply agreements, with premium segments increasingly embedded in scanner OEM roadmaps.
- Advanced Pellicles:Crystalline silicon membranes withstand power densities exceeding 600W that destroy polymer alternatives within seconds. Logic manufacturers in Taiwan and South Korea prioritize these for first high-NA production lines where thermal dissipation determines throughput.
- Standard Pellicles:Fluoropolymer-based films serve 0.33NA EUV systems at mature nodes. REACH and the EU F-Gas Regulation are forcing reformulation of these membranes ahead of regulatory deadlines, compressing their viable deployment window.
- Composite Pellicles:Hybrid architectures combine silicon substrates with protective surface layers for extended exposure cycles.
- Protective Pellicles:Sacrificial membranes shield master photomasks during qualification and maintenance operations.
Volume placements concentrate in Standard Pellicles; the faster expansion belongs to Advanced Pellicles.
Material:
Cost tiers align with thermal performance thresholds, separating premium crystalline substrates from commodity polymer alternatives facing regulatory phase-out.
- Silicon:Single-crystal wafers processed to sub-50nm thickness transmit 13.5nm radiation while conducting heat away from the mask plane. Japanese specialty material suppliers dominate substrate production, creating geographic concentration risk for high-NA tool deployments.
- Polymer:Perfluorinated films face structural degradation below 400W illumination thresholds. EPA oversight and REACH authorization requirements are blocking new capacity investments, turning existing inventory into stranded assets.
- Quartz:Fused silica substrates serve inspection and metrology applications outside direct EUV exposure paths.
- Glass:Borosilicate and aluminosilicate compositions protect photomasks during transport and storage operations.
Procurement volume clusters in Polymer for legacy tool maintenance; Silicon is climbing the fastest as high-NA qualifications accelerate.
End User:
Customer type determines specification stringency, with leading-edge logic and memory fabs imposing thermal and transmission requirements that research users do not replicate.
- Semiconductor Manufacturers:Logic and memory fabs in Taiwan, South Korea, and the United States specify pellicles for continuous-wave EUV sources at production duty cycles. These customers bundle multi-year supply agreements with scanner maintenance contracts, displacing spot-market purchasing.
- Photomask Suppliers:Mask shops require pellicle integration during pattern qualification and defect review. Their specifications emphasize particle protection over power handling, opening demand for lower-tier membrane categories.
- Research Institutions:Academic and national laboratory users operate EUV sources at reduced duty cycles with less stringent thermal constraints.
- Electronic Component Producers:Specialty chip manufacturers at trailing-edge nodes utilize EUV for selective layer patterning with intermittent exposure requirements.
Contract value concentrates in Semiconductor Manufacturers; Photomask Suppliers are gaining share fastest as mask complexity multiplies.
Application:
Process stage determines exposure duration and power density, separating high-throughput production applications from intermittent inspection and protection roles.
- Chip Production:Wafer exposure at 3nm and 2nm nodes requires pellicles that survive thousands of consecutive pulses at source powers exceeding 500W. Thermal cycling between exposure and idle states stresses membrane-substrate interfaces, driving qualification toward silicon architectures.
- Lithography:Pattern transfer operations encompass both logic and memory array printing with varying illumination coherence requirements. Memory manufacturers in South Korea prioritize pellicle transmission efficiency for dense array printing where dose uniformity affects bitcell yield.
- Mask Quality Inspection:Actinic review at 13.5nm wavelength verifies pattern fidelity without removing pellicle protection. These applications tolerate lower power densities but demand optical clarity that polymer films provide cost-effectively.
- Surface Protection:Transport and storage covers prevent particle adhesion during mask logistics operations.
Deployment scale favors Chip Production; Mask Quality Inspection is expanding most quickly as defect sensitivity tightens at advanced nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's most concentrated EUV pellicle demand, with Taiwan Semiconductor Manufacturing and United Microelectronics driving qualification cycles for next-generation membranes.
Taiwan
Hsinchu and Tainan Science Parks consume advanced pellicles for 3nm and 2nm node production at unmatched scale. The National Development Council coordinates semiconductor infrastructure investments under the Chip Act implementation guidelines. Kaohsiung's emerging advanced packaging cluster is extending pellicle specifications into heterogeneous integration workflows.
South Korea
Samsung Electronics and SK Hynix operate the world's densest memory-focused EUV lithography corridors around Pyeongtaek and Icheon. The Ministry of Trade, Industry and Energy administers K-Semiconductor Belt subsidies targeting materials localization. Yongin's emerging R&D complex is hosting joint qualification programs between domestic memory makers and membrane suppliers.
United States
Intel's Oregon and Arizona fabs are qualifying silicon-based pellicles for the company's first high-NA production commitments. EPA oversight under the Toxic Substances Control Act constrains fluoropolymer feedstock availability for domestic membrane manufacturing. Albany's NY CREATES complex is coordinating mask protection research between IBM Research and scanner OEM roadmaps.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor crystalline silicon substrate supply from Nagano and Niigata prefectures. METI guides pellicle material standards through JIS C 0806 semiconductor materials specifications. Tsukuba's National Institute of Advanced Industrial Science and Technology is validating alternative chemistries including metal oxide membranes under national technology programs.
Netherlands
ASML's Veldhoven headquarters determines equipment-integrated pellicle specifications across scanner generations from NXE:3600D through EXE:5000 high-NA platforms. The Dutch National Growth Fund allocates resources under the Chips Act Netherlands implementation for EUV ecosystem localization. Eindhoven's High Tech Campus is hosting collaborative thin-film research between equipment makers and membrane specialists.
EUV Pellicle Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal performance and regulatory compliance capabilities. The vendor base concentrates among Japanese specialty material houses and scanner-integrated suppliers, with limited entry paths for unqualified membrane specialists. Three archetypes dominate: crystalline silicon substrate processors, fluoropolymer reformulators navigating REACH constraints, and equipment-integrated membrane partners. Capacity expansion and alternative chemistry development represent the dominant competitive vectors as high-NA deployment accelerates.
Within the equipment-integrated tier, ASML Holding N.V. and FUJIFILM Holdings Corporation exemplify divergent positioning archetypes. Entegris, Inc. anchors North American supply chain representation among contamination control specialists. Japanese chemical conglomerates including Mitsui Chemicals, Inc., Sumitomo Chemical Co., Ltd., and Shin-Etsu Chemical Co., Ltd. occupy positions tied to domestic substrate processing and thin-film expertise clusters.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| SÜSS MicroTec SE |
| ASML Holding N.V. |
| AGC Inc. |
| Entegris, Inc. |
| Mitsui Chemicals, Inc. |
| Toppan Inc. |
| Sumitomo Chemical Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Scanner OEMs and leading-edge logic fabs concentrate procurement leverage through multi-year equipment-integrated contracts, anchoring value-based pricing that ties membrane costs to wafer throughput guarantees rather than per-unit component pricing. This buyer concentration rewards qualified suppliers with pricing power while squeezing unqualified competitors toward commodity spot-market tiers.
Pricing Analysis
Throughput-linked value pricing dominates as fabs negotiate pellicle supply bundled with scanner uptime commitments and yield protection guarantees. Price differentiation rests on thermal performance certification tier and geographic proximity to Hsinchu, Pyeongtaek, and Phoenix fab clusters. Cost compression in fluoropolymer-based standard tiers is intensifying because REACH authorization timelines strand inventory before high-NA retrofit cycles complete. Memory manufacturers in South Korea exhibit highest price sensitivity due to bitcell margin pressures, while Intel and TSMC prioritize thermal stability over unit cost.
Supply Chain Analysis
Regional distribution centers in Nagano, Hsinchu, and Eindhoven coordinate hub-and-spoke fulfillment to mask shops and fab cleanrooms with sub-24-hour replenishment windows. Crystalline silicon substrate supply concentrates in Japan, with Shin-Etsu Chemical and SUMCO drawing from domestic polysilicon feedstock. Fluoropolymer precursor supply hinges on Belgian and German chemical complexes facing ECHA authorization bottlenecks. Single-source vulnerability pervades semiconductor-grade silicon processing capabilities. Distribution runs through equipment OEM certified-partner channels rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation constructs a compliance moat that rewards incumbent pellicle suppliers with certified alternative chemistries while blocking capital deployment by fluoropolymer-dependent competitors. This regulatory barrier-to-entry compresses the viable supplier base ahead of high-NA volume ramps.
For Market Incumbents: Lock in captive supply agreements with ASML and Tokyo Electron by aligning R&D roadmaps to EXE:5000 high-NA qualification timelines. Secure backward integration into semiconductor-grade silicon substrate processing to eliminate Shin-Etsu concentration risk. Prioritize METI-JIS certification for metal oxide membrane alternatives before ECHA authorization deadlines harden.
For New Entrants and Emerging Players: Carbon nanotube thin-film architectures offer a technology-first wedge into protective pellicle segments where thermal constraints relax and qualification cycles compress. Target mask shop customers in Japan and the United States with sacrificial membrane offerings that bypass scanner OEM integration requirements. Pursue joint development agreements with Tsukuba AIST or Albany NY CREATES to access national laboratory validation infrastructure.
For Investors and Strategic Acquirers: The window for entry favors crystalline silicon substrate processors with existing semiconductor wafer thinning capabilities and JIS-certified quality systems. Acquisition targets should demonstrate qualified supply relationships with at least two of TSMC, Samsung, or Intel. Monitor ECHA SVHC candidate list additions as the inflection signal for fluoropolymer asset stranding velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Chemistry Development | Metal oxide and carbon nanotube research under METI guidance bypasses REACH authorization constraints. |
| Equipment-Integrated Partnership | ASML scanner roadmaps create captive demand channels with multi-year visibility. |
| Substrate Processing Expansion | Semiconductor-grade silicon thinning capabilities concentrate in Nagano and Niigata prefectures. |
| Regulatory Certification Investment | JIS C 0806 compliance accelerates qualification with Japanese memory and logic manufacturers. |
| Regional Distribution Localization | Kaohsiung and Yongin hubs reduce lead times to Taiwan and South Korea fab clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pellicle R&D directors, fab procurement managers at TSMC and Samsung, scanner OEM component engineers, and METI standards committee participants. SEC 10-K disclosures from Entegris and FUJIFILM, ECHA authorization dossiers, and Japanese customs export statistics provided demand-side validation. Bottom-up wafer shipment projections and top-down lithography equipment install base estimates were triangulated against membrane replacement cycle assumptions.
Data-stream reconciliation across scanner shipment schedules, fab capacity announcements, and pellicle qualification timelines generated volume and value outputs over the projection horizon. Segmentation modeling captured material type, product tier, end-user category, and regional fab cluster dimensions. CAGRs were derived from power-density requirements scaling with numerical aperture transitions and corresponding membrane architecture shifts. Forecast inputs included high-NA tool retrofit timelines and fluoropolymer regulatory phase-down schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA acceleration of SVHC listings or geopolitical disruption to Japanese silicon substrate supply. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Excimer Laser Market
Optics
Global Optical Lens Market
Optics
Laser Transmitter Market
Optics
Global Semiconductor Lasers Market
Optics
Digital Holographic Microscopy Market
Optics
Fiber Optic Development Tools Market
Optics
Global Super Hi Vision Market
Optics
Sports Optics Market
Optics
Smart Vision Systems Market
Optics
Smartphone Camera Lenses Market
Optics
Smartphone Lenses Market
Optics
Global Fiber Optic Sensors Market
Optics
Global Enhanced Vision System Market
Optics
US Photonics Market
Optics
Optical Imaging Market
Optics
Optical Wavelength Service Market