
 Global Enhanced Vision System Market | 2026-2036
Global Enhanced Vision System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enhanced Vision System Market Intelligence
A divergence in sensor fidelity and data fusion capabilities is rebalancing the market between premium, mil-spec systems and lower-cost commercial-off-the-shelf solutions. Collins Aerospace specializes in deeply integrated avionics suites for new commercial and business aircraft. In contrast, Elbit Systems Ltd. dominates the segment for sophisticated helmet-mounted displays tailored for defense forces. Thales Group competes across both domains, leveraging its extensive portfolio in sensors and display technologies.
An enhanced vision system is an electronic system that provides pilots or vehicle operators with a clear image of the external environment in low-visibility conditions. These systems typically utilize sensors like forward-looking infrared cameras that detect thermal energy signatures. Their primary purpose is to improve situational awareness, enabling safer navigation and operations. While Infrared Imaging remains a core technology, systems integrating LIDAR and advanced Image Fusion algorithms are gaining traction, particularly for military applications.
Regulatory bodies like the FAA in the United States and EASA in Europe provide critical oversight for civil aviation systems. Certifications under standards such as TSO-C162a are essential, as they grant operational credits for lower landing minima. The primary strategic decision for manufacturers is whether to focus on deep integration with specific airframes or develop platform-agnostic modular sensors.
Market Dynamics
The pursuit of operational credits from aviation authorities is the central force shaping the market. Certifications from the FAA and EASA that permit lower landing minima provide a direct financial and operational return on investment, moving EVS from a safety enhancement to a core business tool.
Growth Catalysts
- Regulatory Incentives:Certifications under standards like TSO-C162a from the Federal Aviation Administration grant operational credits, allowing aircraft to land in lower visibility conditions and increasing airport accessibility.
- Sensor Miniaturization:Advances in uncooled infrared cores and smaller sensor packages are making enhanced vision systems more accessible and affordable for the general aviation and light jet segments.
- Fleet Modernization:A consistent demand for avionics upgrades within the large installed base of private and business aircraft in the United States and Europe supports steady market expansion.
Market Restraints
- High Acquisition Cost:The significant upfront investment for EVS hardware, software, and particularly the labor-intensive installation and integration, remains a primary barrier for smaller operators and older aircraft.
- Performance Limitations:Sensor effectiveness can be compromised by certain atmospheric conditions, such as heavy rain or icing, which can obscure thermal signatures and reduce system reliability.
- Certification Timelines:The lengthy and complex process of achieving airworthiness certification for new systems or for retrofits on existing airframes can delay market entry and increase development costs.
Strategic Opportunities
- Unmanned Systems Integration:Adapting EVS technology for unmanned aerial vehicles (UAVs) and emerging urban air mobility (UAM) platforms creates a new market for enabling beyond-visual-line-of-sight operations.
- Technology Fusion:The convergence of EVS with Synthetic Vision Systems (SVS) into a single Combined Vision System (CVS) offers pilots a superior, integrated view of the operating environment.
- Geographic Expansion:Targeting nascent business aviation markets in Brazil and parts of the Middle East, where new aircraft deliveries and fleet expansion are projected, presents a key growth vector.
Industry Challenges
- Legacy System Integration:Ensuring seamless interoperability and data exchange between modern EVS sensors and the diverse, often proprietary, legacy avionics suites found in the existing aircraft fleet.
- Algorithm Certification:The validation and certification of complex image fusion and data processing algorithms to meet stringent aviation safety standards is a significant technical and regulatory hurdle.
- Technician Skill Gaps:A shortage of avionics technicians with the specialized expertise required to install, calibrate, and maintain sophisticated multi-sensor vision systems is a constraint on aftermarket growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enhanced Vision System Market |
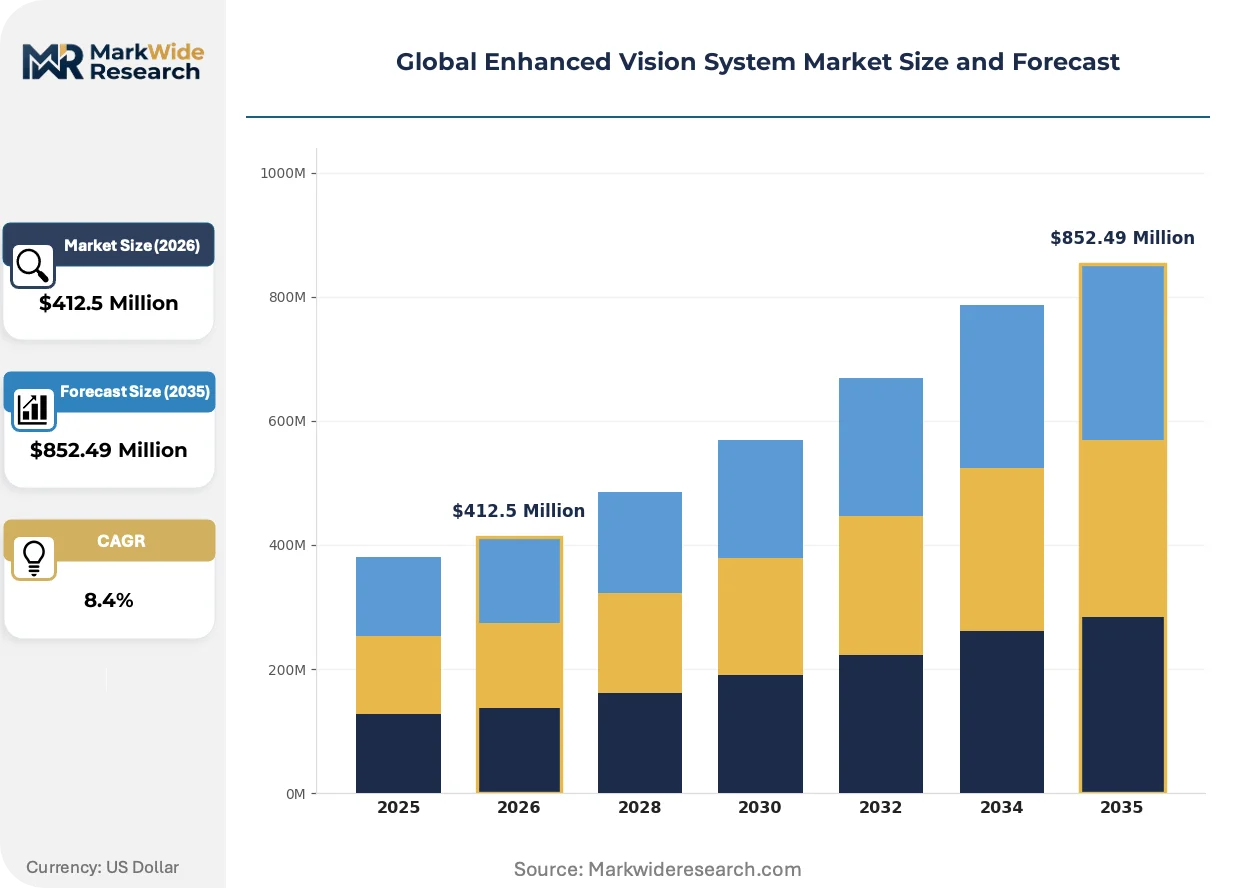
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmet Mounted Display, Head-Up Display, Night Vision Camera, Infrared Sensor, Thermal Imager Technology: Infrared Imaging, Millimeter Wave Radar, LIDAR, Electro-Optical Systems, Image Fusion Application: Military Navigation, Search and Rescue Operations, Marine Navigation, Security Surveillance, Firefighting Assistance End User: Defense Forces, Maritime Operators, Emergency Responders, Law Enforcement Agencies, Aviation Pilots |
| Companies Covered | Honeywell International Inc., Thales Group, Elbit Systems Ltd., Astronics Corporation, L3Harris Technologies, Inc., Collins Aerospace, Opgal, Esterline Technologies Corporation, MBDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enhanced Vision System Market Strategic Shifts & Innovations
A fundamental shift from single-purpose sensors to multi-modal data fusion is redefining the technology's role in the cockpit. Enhanced vision is evolving from a passive viewing aid into an active, integrated component of the aircraft's primary flight and navigation systems.
LIDAR provides precise range-finding and three-dimensional object mapping, complementing the thermal detection capabilities of infrared cameras. The defense sector is a primary adopter, using the technology for low-altitude helicopter navigation and obstacle avoidance. This active sensing capability is converging with passive thermal imaging to create a more robust environmental model for pilots and autonomous systems.
European Union Aviation Safety Agency (EASA) rulemaking continues to align with Federal Aviation Administration (FAA) standards for certifying advanced vision systems. This harmonization simplifies the development and approval process for manufacturers targeting a global customer base, reducing duplicative testing. The business jet segment, which operates extensively between the United States and Europe, is the primary beneficiary of this streamlined regulatory environment.
A clear preference is emerging among buyers of new aircraft for fully integrated vision systems offered as part of a complete avionics suite. This trend disrupts the market for standalone, aftermarket EVS units, favoring airframe manufacturers and their Tier-1 suppliers who can deliver a unified cockpit experience. This purchasing behavior is most visible in the North American market for new mid-size and large-cabin business jets.
Global Enhanced Vision System Market Segmentation
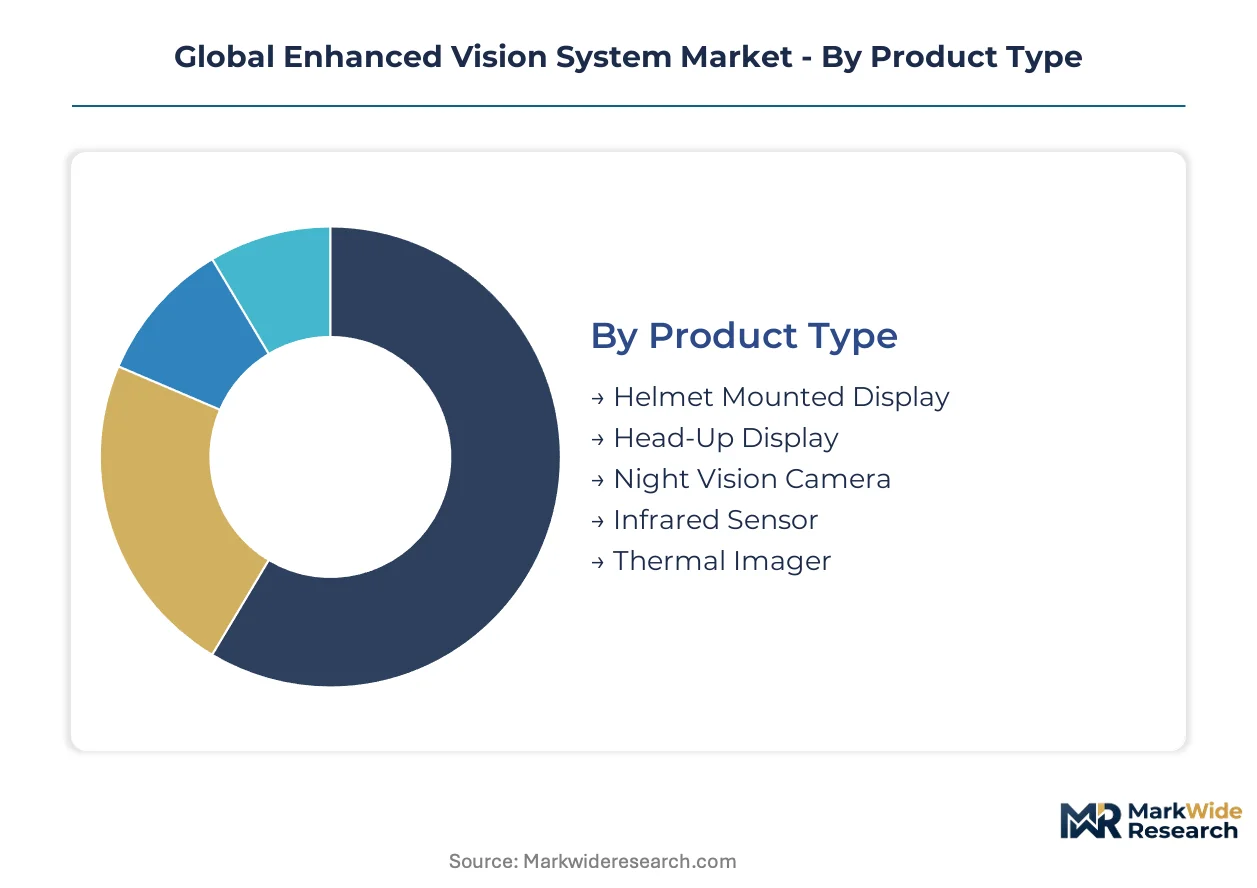
Understanding the segmentation of the Global Enhanced Vision System Market is crucial for identifying distinct customer needs and technological preferences. This detailed breakdown helps manufacturers tailor solutions, optimize product development, and strategically target specific operational environments. Analyzing these segments provides insights into where value is created and how market dynamics influence adoption rates across various applications.
Product Type:
The product type segmentation highlights the spectrum from highly integrated, specialized displays to more modular sensor components.
- Helmet Mounted Display:These systems integrate visual information directly into a pilot's or operator's line of sight, providing critical flight or tactical data and enhanced imagery. Demand is concentrating in defense forces for helicopter operations and advanced fighter aircraft, where superior situational awareness provides a tactical advantage.
- Infrared Sensor:As a core component, infrared sensors detect thermal energy signatures, forming the basis for enhanced vision systems in low-light or obscured conditions. The United States and Europe lead demand due to extensive retrofit programs for business and general aviation aircraft, driven by regulatory incentives for operational credits.
- Head-Up Display:Head-Up Displays project critical flight and sensor data onto a transparent screen in the pilot's forward field of view, minimizing head-down time.
- Night Vision Camera:These cameras amplify ambient light, enabling visibility in extremely low-light conditions, primarily used by special operations forces and law enforcement agencies.
- Thermal Imager:Thermal imagers specifically capture infrared radiation, creating images based on heat differences, essential for detecting objects in smoke, fog, or complete darkness.
Leading the category by volume: Infrared Sensor. Growing fastest: Helmet Mounted Display.
Technology:
Technological differentiation within enhanced vision systems reflects varying levels of complexity and environmental adaptability.
- Infrared Imaging:This foundational technology uses forward-looking infrared (FLIR) cameras to detect thermal radiation, allowing pilots to "see" through adverse weather conditions like fog and haze. It remains a primary technology for civil aviation EVS due to its proven reliability and certification history with the FAA and EASA.
- Image Fusion:This advanced technique combines data from multiple sensors, such as infrared, visible light, and LIDAR, to create a more comprehensive and robust image for the operator. Military applications, particularly in the United States and NATO countries, increasingly adopt image fusion for superior situational awareness in complex environments.
- Millimeter Wave Radar:Millimeter wave radar provides all-weather penetration capabilities, detecting objects and terrain features through heavy precipitation or dust.
- LIDAR:Light Detection and Ranging (LIDAR) uses pulsed laser light to measure distances, generating precise 3D maps of the environment, particularly useful for obstacle avoidance.
- Electro-Optical Systems:These systems encompass a range of technologies, including visible and near-infrared cameras, offering high-resolution imagery in daylight or well-lit conditions.
Infrared Imaging holds the largest share, while Image Fusion technology demonstrates the steepest expansion trajectory.
Application:
The diverse applications for enhanced vision systems underscore their utility across critical operational domains.
- Military Navigation:EVS provides critical situational awareness for military pilots during low-altitude flights, tactical operations, and adverse weather conditions, enhancing mission success and safety. Defense forces globally, including the US military and European NATO members, are significant users for both fixed-wing and rotary-wing aircraft.
- Search and Rescue Operations:These systems enable emergency responders to locate individuals and navigate challenging terrains in low visibility, smoke, or darkness, significantly improving response times. Emergency services in Europe and North America are increasingly investing in EVS for their aerial assets.
- Marine Navigation:EVS assists vessel operators in navigating through fog, at night, or in crowded waterways by detecting other vessels, buoys, and shorelines.
- Security Surveillance:EVS technology enhances surveillance capabilities for border patrol, critical infrastructure protection, and law enforcement by providing clear imagery in all lighting conditions.
- Firefighting Assistance:Firefighters use EVS to see through smoke and locate hot spots or trapped individuals, improving safety and effectiveness during operations.
Military Navigation generates the highest demand, with Search and Rescue Operations showing significant growth potential.
End User:
End-user segments define the specific operational contexts and regulatory environments shaping EVS requirements.
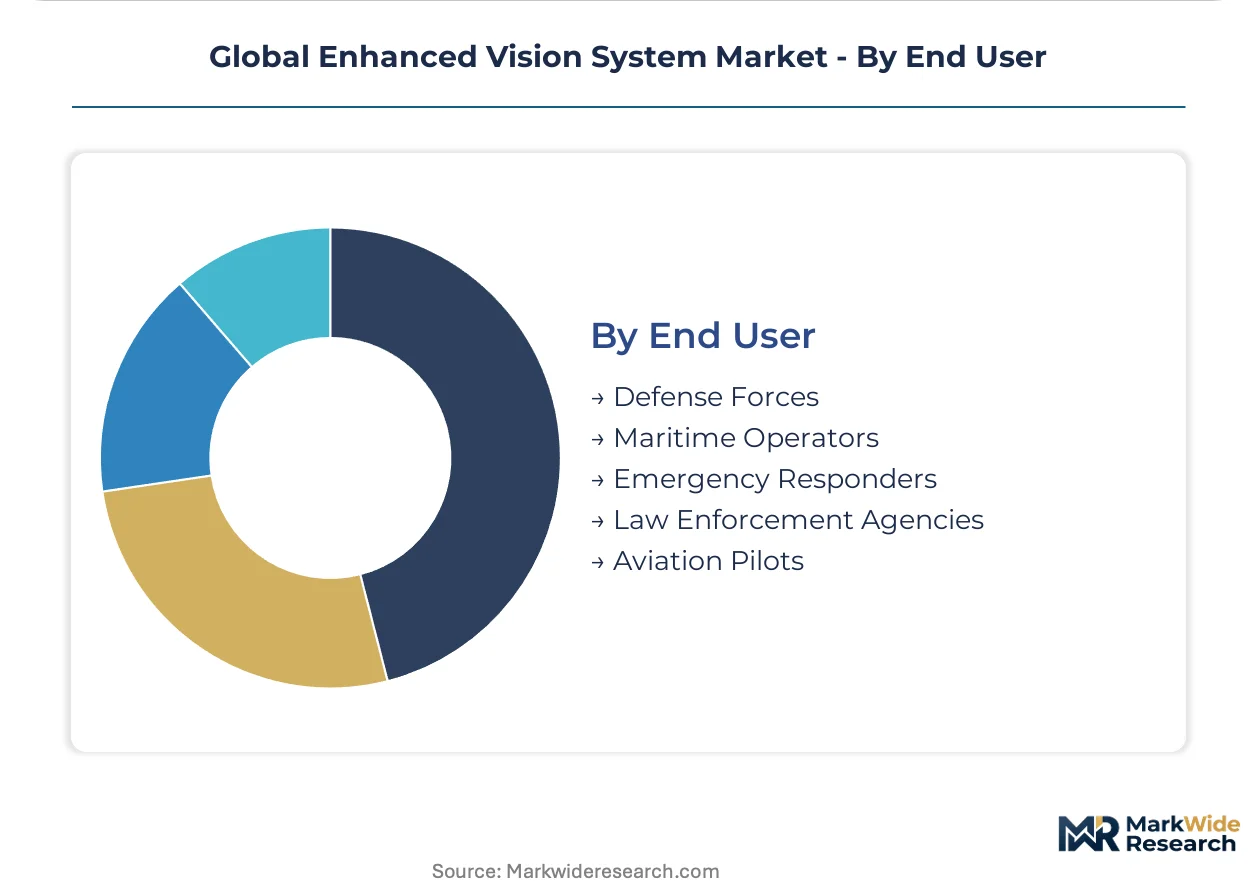
- Defense Forces:Military organizations worldwide are primary adopters of advanced EVS for tactical advantage, pilot safety, and mission effectiveness across air, land, and sea platforms. Nations with significant defense budgets, such as the United States, France, and the United Kingdom, drive demand for highly specialized and integrated systems.
- Aviation Pilots:Commercial and general aviation pilots utilize EVS to enhance situational awareness during takeoff, landing, and taxiing in low-visibility conditions, gaining operational credits from regulators like the FAA and EASA. The large installed base of private and business aircraft in North America and Europe represents a consistent market for upgrades.
- Maritime Operators:Operators of commercial vessels, ferries, and private yachts use EVS for improved navigation and collision avoidance in challenging marine environments.
- Emergency Responders:This segment includes police, fire departments, and medical transport services that deploy EVS on helicopters and other vehicles for critical response missions.
- Law Enforcement Agencies:Law enforcement utilizes EVS for surveillance, pursuit, and search operations, particularly in night-time or low-light scenarios.
Defense Forces represent the largest end-user base, while Aviation Pilots are increasingly adopting EVS for operational credits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seattle aerospace cluster, a hub for aircraft manufacturing, drives significant demand for enhanced vision systems in new commercial and business aircraft. This region benefits from a strong ecosystem of avionics suppliers and research institutions. Regulatory advancements by the Federal Aviation Administration (FAA) also encourage EVS adoption, particularly for operational credits.
United States
The United States exhibits robust demand for enhanced vision systems, driven by fleet modernization efforts within business and general aviation. FAA certifications, specifically TSO-C162a, incentivize operators to upgrade for lower landing minima. California's aerospace and defense industry, including Silicon Valley's sensor development, actively contributes to EVS innovation and integration.
France
French aerospace manufacturers and defense contractors generate substantial EVS demand, particularly for military navigation and advanced fighter aircraft. EASA regulatory frameworks support the certification of sophisticated avionics, including combined vision systems. Toulouse, a major European aerospace center, houses significant R&D and manufacturing capabilities for integrated EVS solutions.
Germany
Germany's strong general aviation and specialized military aviation sectors fuel EVS market expansion, focusing on safety enhancements and operational efficiency. European Union Aviation Safety Agency (EASA) standards for advanced vision systems provide a clear pathway for market entry. Munich's high-tech industry and aerospace component suppliers contribute to sensor development and system integration.
United Kingdom
The United Kingdom's defense forces and a growing business aviation segment contribute to the demand for advanced enhanced vision systems. UK Civil Aviation Authority (CAA) alignment with EASA regulations facilitates the adoption of certified EVS technologies. Farnborough, known for its aerospace industry, hosts companies specializing in avionics and display technologies.
Japan
Japan's aerospace sector, focusing on both defense and niche civil aviation applications, shows increasing interest in enhanced vision systems for improved situational awareness. The Japan Civil Aviation Bureau (JCAB) often aligns its certification processes with international standards for avionics. Nagoya's aerospace cluster, a key manufacturing base, supports the integration of EVS into new aircraft designs.
Global Enhanced Vision System Market Key Industry Players
Premium-margin players sit above commodity-margin players across the technological sophistication and integration depth spectrum within the enhanced vision system market. The market structure exhibits a tiered consolidation, with established aerospace and defense primes dominating the high-end segments. Strategic archetypes include integrated avionics providers, specialized sensor manufacturers, and defense-focused system integrators. Companies actively engage in strategic partnerships to broaden their product portfolios and expand geographic reach.
On the premium-tier vector, Collins Aerospace exemplifies deeply integrated avionics suites for new commercial and business aircraft, leveraging its extensive platform relationships. Elbit Systems Ltd. represents a specialized segment, focusing on sophisticated helmet-mounted displays tailored for defense forces and advanced tactical applications. Thales Group occupies a position across both civil and defense domains, anchoring its offerings on a broad portfolio of sensors and display technologies for diverse operational environments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| Astronics Corporation |
| L3Harris Technologies, Inc. |
| Collins Aerospace |
| Opgal |
| Esterline Technologies Corporation |
| MBDA |
Cost & Logistics Intelligence
Specialized avionics technician expertise in regions like Seattle and Toulouse directly influences EVS installation costs, creating distinct pricing tiers for integrated systems versus retrofit solutions. This labor-cost differential contributes to the overall market's premium positioning for highly customized solutions.
Pricing Analysis
Outcome-based operational credits from aviation authorities anchor EVS pricing, directly linking system value to lower landing minima. Pricing differentiation stems from certification level, such as TSO-C162a compliance, and the extent of after-sales support. Cost compression in the commercial-off-the-shelf segment intensifies due to increasing competition from modular sensor manufacturers. General aviation operators exhibit higher price sensitivity compared to defense forces, who prioritize advanced features and reliability.
Supply Chain Analysis
Dual-sourcing requirements for critical components like uncooled infrared cores ensure supply resilience in the EVS market. Key geographic concentrations for sensor manufacturing include the United States and Germany, while specialized display components often originate from Japan. The supply chain relies heavily on high-purity rare earth elements and advanced microelectronics, with single-source vulnerability for specialized image fusion processors representing a structural risk. Distribution runs through a direct sales model for integrated avionics suites and a network of certified aftermarket installers for standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
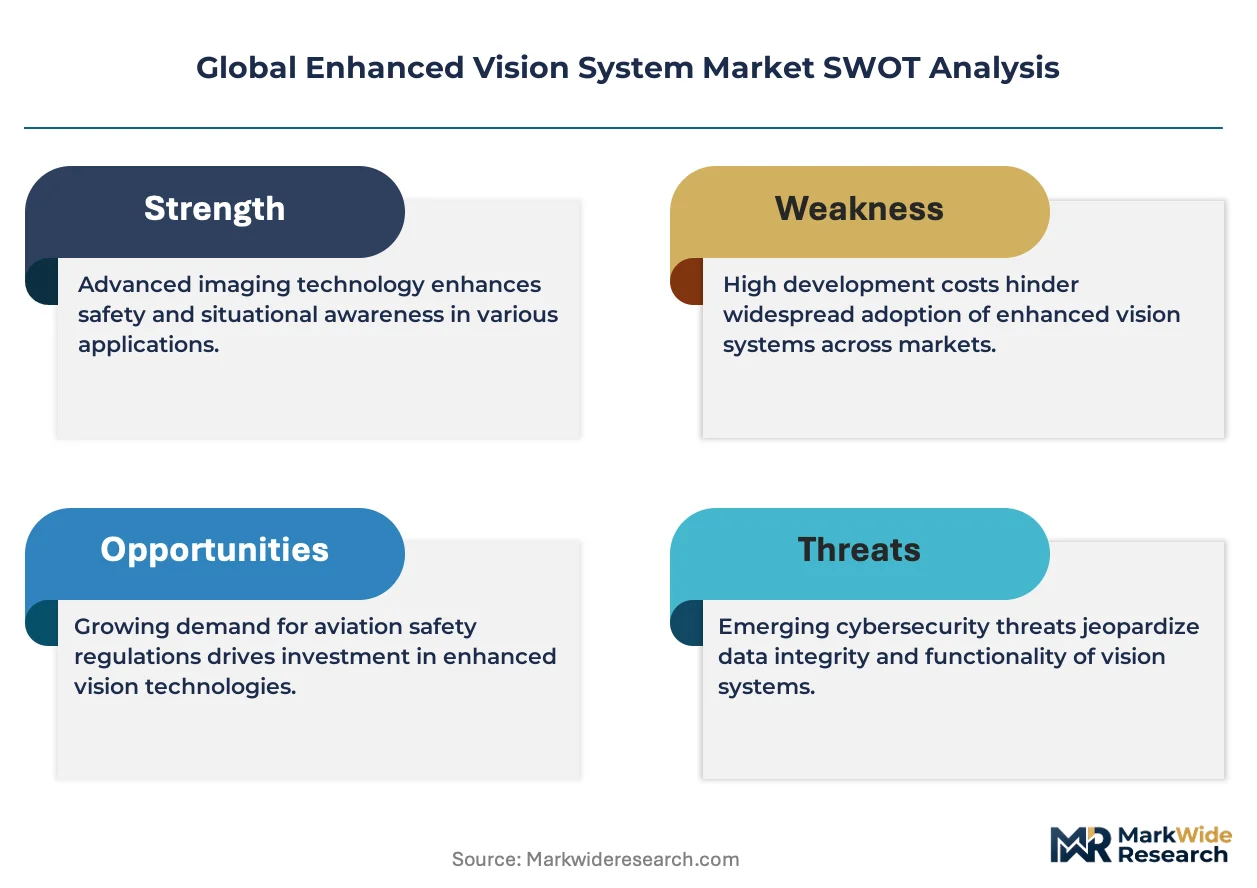
The Global Enhanced Vision System Market increasingly functions as a consolidation play, with lengthy certification timelines forcing smaller, less capitalized players out. This environment favors established avionics providers and specialized sensor manufacturers with robust R&D budgets.
For Market Incumbents: Lock in platform relationships with major airframe manufacturers through deeply integrated avionics suites, leveraging existing certification pathways. Deepen vertical integration into advanced sensor manufacturing, such as uncooled infrared cores, to mitigate supply chain risks and control costs against the threat of component commoditization. Invest heavily in algorithm certification for image fusion technologies to maintain a competitive edge. Control the aftermarket service network for proprietary systems.
For New Entrants and Emerging Players: Avionics integration specialists represent a key channel for new entrants to penetrate the retrofit market for general aviation. Target the emerging urban air mobility (UAM) and unmanned aerial vehicle (UAV) segments, where regulatory frameworks are still evolving and established players have less entrenched positions. Focus on modular, platform-agnostic sensor solutions with rapid integration capabilities. A direct-to-developer go-to-market angle can secure early design wins in nascent platforms.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized sensor manufacturers given the increasing demand for multi-modal data fusion across defense and civil applications. The long-term viability of EVS technology is assured by its role in enhancing operational safety and efficiency, particularly with autonomous systems. Target acquisition archetypes include niche providers of LIDAR or millimeter-wave radar technologies. The signal to watch is the acceleration of EASA and FAA harmonization for combined vision system certifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Sensor Manufacturing | Secures critical component supply and enhances control over product innovation for EVS providers. |
| Strategic Partnerships with Airframe OEMs | Ensures early design wins and deep integration for next-generation aircraft platforms. |
| Investment in Algorithm Certification | Accelerates market entry and broadens operational credits for advanced image fusion systems. |
| Targeted Geographic Expansion (Brazil/Middle East) | Captures growth in nascent business aviation markets with increasing fleet modernization. |
| UAV/UAM EVS Adaptation | Unlocks new market segments for beyond-visual-line-of-sight operations and autonomous flight. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and primary interviews underwrites the qualitative findings of this study. The analysis integrates insights from avionics engineers, airline procurement managers, defense contractors, and regulatory affairs specialists. Secondary validation leverages FAA certifications, EASA rulemaking documents, and company financial disclosures, ensuring a robust data foundation. Bottom-up data aggregation and top-down market sizing triangulate market estimates.
Rate-of-change decomposition across the projection horizon drives the quantitative forecast, segmenting the market by product type, technology, application, and end-user. The analytical framework also incorporates regional regulatory landscapes, such as FAA and EASA standards. Compound annual growth rates derive from historical trends and projected technological advancements. Key inputs include aircraft delivery schedules and avionics upgrade cycles.
Caveats apply where unforeseen geopolitical events or rapid technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and economic conditions. Deviation in global defense spending or civil aviation investment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber Optical Receivers Market
Optics
Laser Transmitter Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Optical Fiber Market
Optics
Optical Sensing Market
Optics
US Photonics Market
Optics
Digital Holographic Microscopy Market
Optics
Plastic Lens Market
Optics
Optical Microscope Market
Optics
Optical Lens for Mobile Phone Market
Optics
Collimating Lens Market
Optics
Optical Wavelength Service Market
Optics
Interchangeable Lens Market
Optics
Global Fiber Optic Components Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Smartphone Lenses Market