
 Optical Gratings Market | 2026-2036
Optical Gratings Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Gratings Market Insights
Capital-intensity divergence between semiconductor-grade lithography grating producers and general-purpose spectroscopy suppliers is unwinding competitive stability across the value chain. MKS Instruments leverages vertically integrated motion control and photonics capabilities to sustain premium positioning in laser tuning and semiconductor metrology. Zeiss anchors high-end reflection grating production through proprietary ion-beam etching infrastructure that competitors struggle to replicate.
Optical gratings are periodic structures that diffract incident light into multiple beams following the grating equation, with groove densities typically ranging from 30 lines per millimeter to 10,800 lines per millimeter depending on resolution requirements; manufacturers achieve these patterns through mechanical ruling, holographic interference lithography, or ion-beam etching on substrates of glass, fused silica, or metal-coated surfaces, serving primarily to disperse wavelengths for spectral analysis or precisely control laser output. Holographic gratings now dominate precision spectroscopy applications where low stray light and smooth spectral response command margin premiums, while blazed gratings retain strongholds in laser cavity tuning and telecommunications wavelength division multiplexing where efficiency at specific wavelengths determines procurement decisions. Transmission gratings compete aggressively in portable and cost-sensitive instruments, though glass substrate supply constraints periodically disrupt volume availability.
FDA analytical instrument validation guidelines and EU REACH substance restrictions on coating materials shape product development cycles and supplier qualification timelines for grating manufacturers serving regulated industries. ISO 10110 surface quality standards and IEC laser safety classifications further constrain design freedom, particularly for gratings integrated into medical diagnostic spectrometers and industrial laser systems. Stakeholders must monitor tightening photonics export controls and raw material certification burdens as these forces increasingly determine which suppliers retain access to defense, aerospace, and semiconductor end markets.
Market Dynamics
Capital-intensity divergence between semiconductor-grade lithography grating producers and general-purpose spectroscopy suppliers is unwinding competitive stability across the value chain. Ion-beam etching infrastructure concentration in Germany's precision optics cluster creates asymmetric capability access that reshapes supplier tiering.
Growth Catalysts
- Spectroscopy demand in pharmaceutical quality control:FDA analytical instrument validation guidelines mandate tighter wavelength accuracy, forcing drug manufacturers to upgrade dispersive optics in high-performance liquid chromatography and mass spectrometry systems.
- REACH compliance in Europe:ECHA substance restrictions on traditional coating materials accelerate holographic grating adoption where solvent-free manufacturing processes eliminate hazardous deposition chemistries.
- Laser cavity tuning applications:Semiconductor metrology equipment builders in Taiwan and South Korea source blazed gratings for external cavity diode lasers used in wafer inspection systems.
Market Restraints
- Fused silica substrate supply constraints:Limited high-purity synthetic quartz production capacity in Japan and the United States creates periodic volume shortages that disrupt transmission grating availability for portable instruments.
- Photonics export control tightening:Multilateral coordination on dual-use optical component restrictions complicates qualification timelines for defense and aerospace grating suppliers serving classified programs.
- Diffraction efficiency limitations in transmission designs:Physical constraints on groove aspect ratios cap performance in high-resolution applications where reflection gratings retain unavoidable advantages.
Strategic Opportunities
- Underpenetrated biomedical imaging in India:CDSCO regulatory harmonization with ISO 13485 standards opens qualification pathways for grating-integrated spectrometers in diagnostic pathology workflows.
- EU Green Deal manufacturing incentives:Horizon Europe funding for sustainable photonics production subsidizes capital equipment upgrades that reduce energy consumption in holographic exposure systems.
- Convergence of spectroscopy and machine vision:Hyperspectral imaging systems for precision agriculture combine diffraction gratings with CMOS sensor arrays, creating integrated module demand outside traditional analytical instrument channels.
Industry Challenges
- Ion-beam etching specialist scarcity:Mastery of sub-nanometer groove profile control requires decades of apprenticeship; German and Japanese training pipelines produce fewer qualified technicians than replacement demand requires.
- ISO 10110 surface quality certification timelines:Extended third-party validation cycles for scratch-dig specifications delay new product introductions in medical diagnostic spectrometer supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Gratings Market |
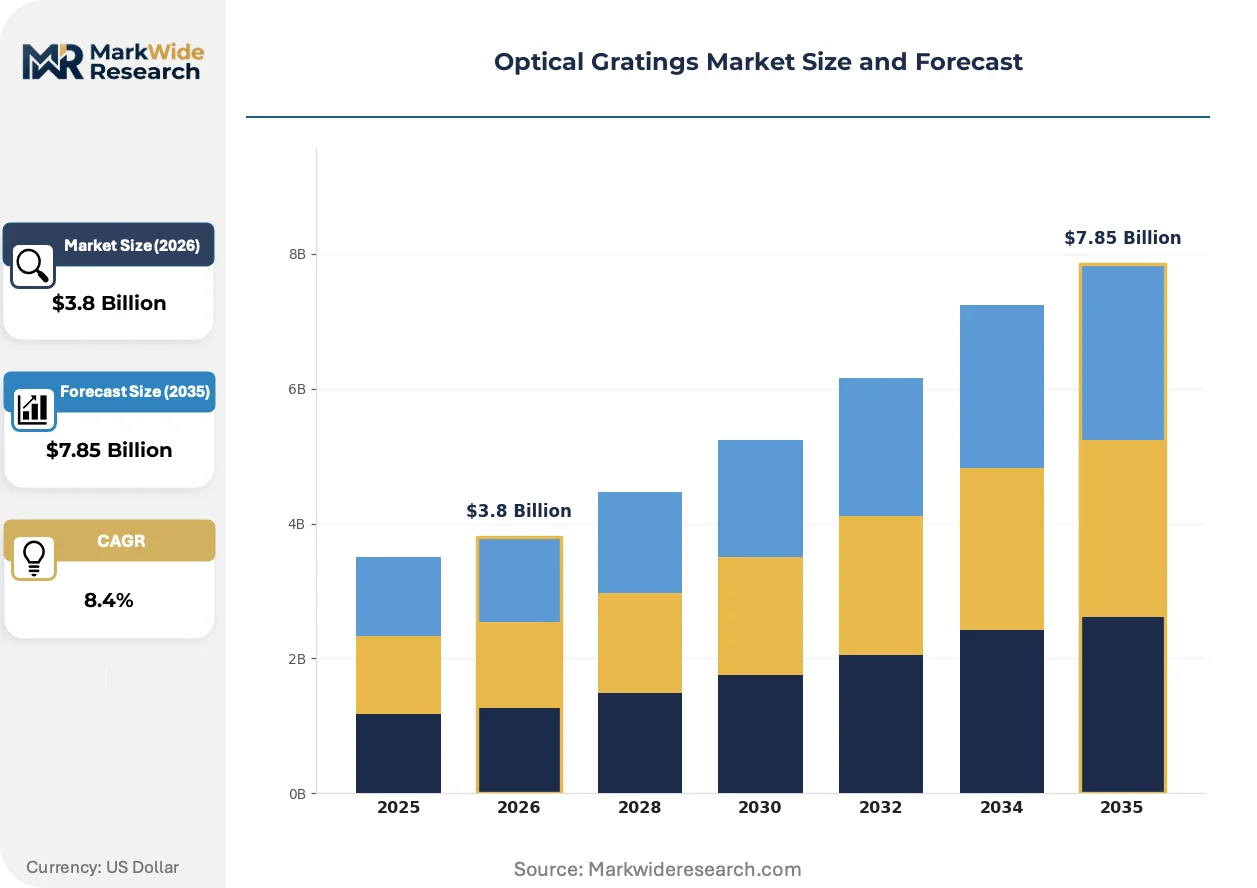
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Gratings, Reflection Gratings, Holographic Gratings, Blazed Gratings Application: Spectroscopy, Telecommunications, Laser Systems, Imaging Systems End User: Research Institutions, Industrial Laboratories, Universities, Government Facilities Material: Glass, Plastic, Metal, Coated Substrates |
| Companies Covered | MKS Instruments, Zeiss, HORIBA, Kaiser Optical Systems, Wasatch Photonics, Edmund Optics, Thorlabs, Photop Technologies, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Gratings Market Trends and Innovations
Active reshaping in optical gratings centers on manufacturing process substitution, regulatory compliance architecture, and procurement model compression that together redefine supplier-customer relationships.
Holographic interference lithography is displacing mechanical ruling for precision spectroscopy applications. Pharmaceutical quality control laboratories and environmental monitoring agencies now specify stray light performance below 0.001% at key wavelengths, a threshold only achievable through interference-pattern exposure of photoresist-coated substrates. This technology shift compresses the addressable market for traditional ruling engines while elevating capital barriers for new entrants.
EU REACH substance restrictions on hexavalent chromium and perfluorinated coating materials force reformulation of reflective layer deposition processes. Grating manufacturers serving regulated industries must requalify alternative metal-dielectric stacks under tightened ECHA authorization timelines, with medical device and food safety spectroscopy segments experiencing the most acute compliance friction.
Consolidated procurement by analytical instrument OEMs is compressing supplier margins and fragmenting aftermarket service relationships. End-users in industrial laser systems now negotiate multi-year grating supply agreements bundled with metrology calibration services, a pattern most visible in Germany's automotive manufacturing quality control departments where Zeiss and MKS Instruments compete for captive maintenance contracts.
Optical Gratings Market Segmentation
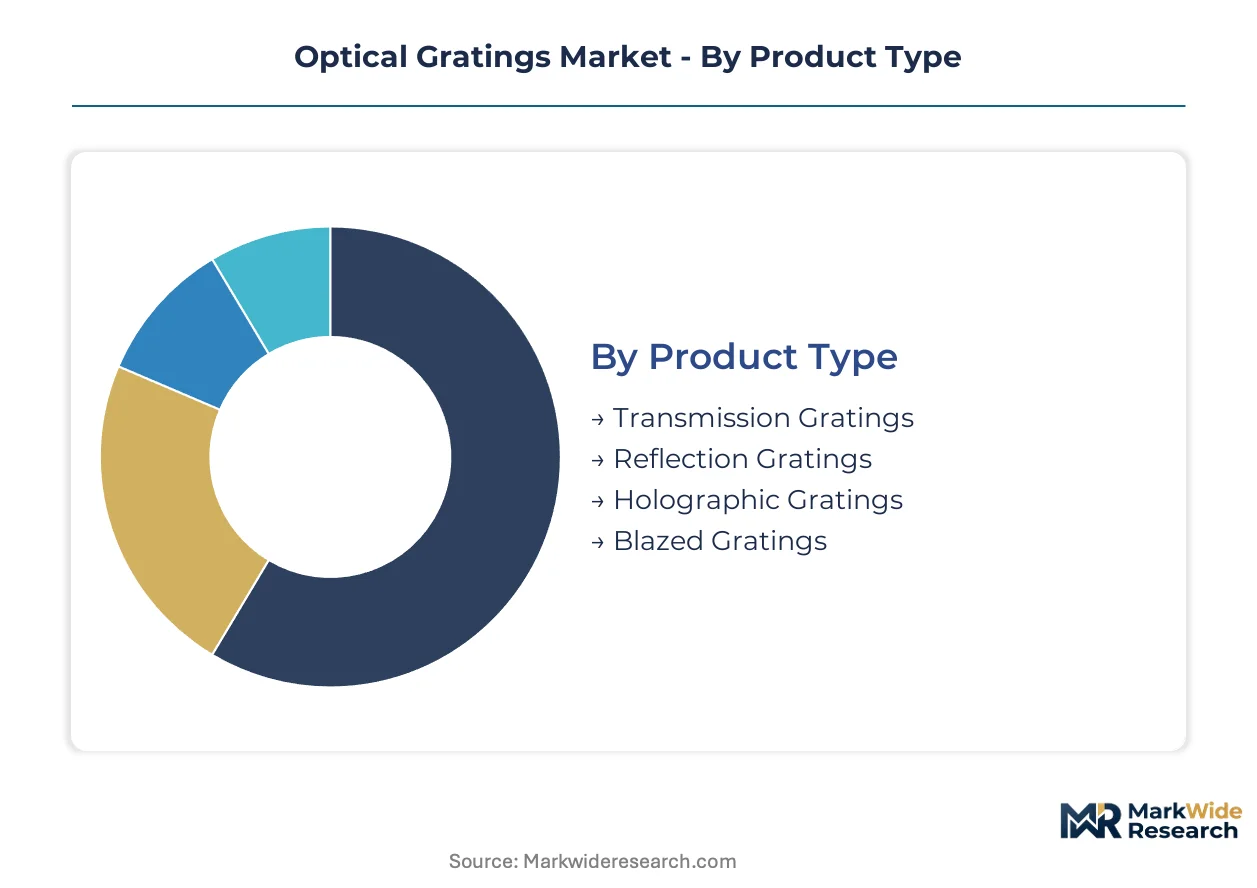
Optical grating manufacturers face divergent qualification requirements across product architectures and end-use environments. Segment-specific performance thresholds determine supplier tiering and pricing power in this capital-intensive precision optics sector.
Product Type:
German and Japanese producers dominate export volumes in high-precision categories, while domestic manufacturing concentrates in cost-optimized transmission designs for portable instrumentation.
- Reflection Gratings:Manufactured through ion-beam etching or mechanical ruling on metal-coated glass substrates, these deliver superior efficiency in ultraviolet and infrared regimes. Demand concentrates in semiconductor metrology equipment from Taiwan and South Korea, where wafer inspection systems require sub-nanometer groove profile stability.
- Holographic Gratings:Interference lithography produces sinusoidal groove patterns with stray light below 0.001%, meeting FDA analytical instrument validation guidelines for pharmaceutical quality control. EU REACH compliance favors these solvent-free manufacturing processes over traditional coating chemistries.
- Transmission Gratings:Glass substrate dispersion elements serve portable spectrometers and educational instruments where cost sensitivity outweighs absolute performance.
- Blazed Gratings:Triangular groove profiles maximize diffraction efficiency at specific wavelengths for laser cavity tuning and telecommunications wavelength division multiplexing.
Reflection gratings command the established base. The steepest expansion runs through holographic gratings.
Application:
Margin structures vary sharply by application, with regulated pharmaceutical and semiconductor segments sustaining premium pricing against commoditized educational and environmental monitoring deployments.
- Spectroscopy:UV-Vis, Raman, and mass spectrometry systems deploy gratings for wavelength dispersion with resolution requirements spanning 30 to 10,800 lines per millimeter. FDA and EMA validation protocols force instrument OEMs toward holographic designs with documented traceability.
- Laser Systems:External cavity diode lasers in semiconductor fabrication and materials processing rely on blazed gratings for precise wavelength tuning. Japanese and German suppliers anchor this segment through proprietary blaze angle control.
- Telecommunications:Dense wavelength division multiplexing equipment uses blazed and volume phase holographic gratings for channel separation in fiber optic networks.
- Imaging Systems:Hyperspectral cameras for precision agriculture and remote sensing integrate transmission gratings with CMOS sensor arrays, a convergence creating new module demand outside traditional analytical channels.
Spectroscopy retains the revenue anchor. Imaging systems are climbing the fastest as machine vision applications proliferate.
End User:
Procurement authority and technical specification control diverge dramatically between centralized government laboratories and fragmented university research groups.
- Industrial Laboratories:Pharmaceutical quality control departments and automotive manufacturing metrology labs negotiate multi-year supply agreements bundled with calibration services. REACH and FDA compliance documentation drives vendor consolidation.
- Research Institutions:National laboratories and applied research centers specify custom groove densities and substrate materials for specialized spectroscopy configurations.
- Government Facilities:Defense and aerospace programs face tightening photonics export controls that complicate qualification timelines and restrict supplier pools to domestic or allied-nation sources.
- Universities:Teaching laboratories and basic research groups prioritize cost-optimized transmission gratings with standard catalog specifications.
Industrial laboratories dominate procurement volume. Government facilities show the steepest compliance-driven supplier consolidation.
Material:
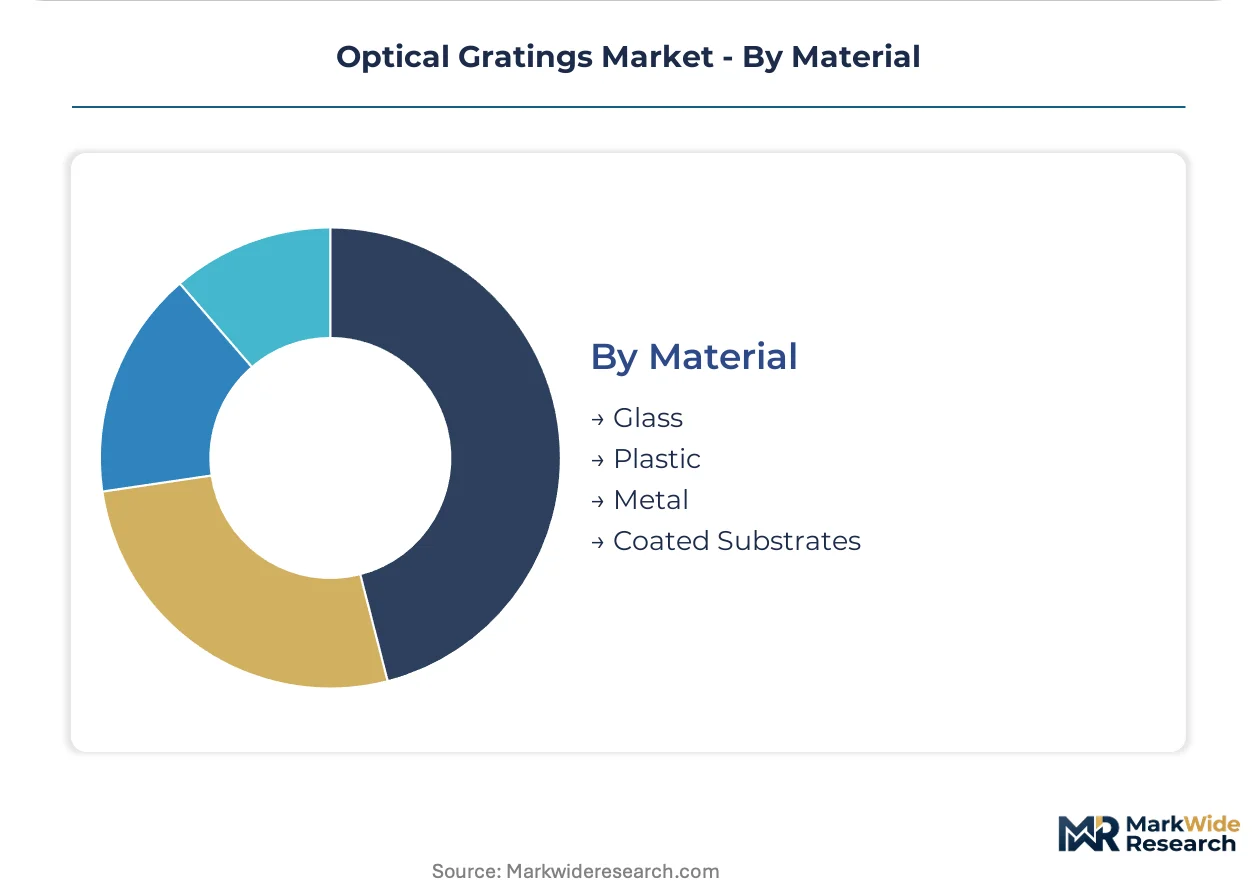
Substrate selection determines thermal stability, transmission bandwidth, and manufacturing process compatibility across grating architectures.
- Glass:Borosilicate and fused silica substrates provide thermal stability and UV transparency for high-resolution spectroscopy. Japan and United States synthetic quartz supply constraints periodically disrupt volume availability.
- Coated Substrates:Aluminum, gold, or dielectric reflective layers on glass or metal bases enable efficient reflection grating operation across specific wavelength bands. EU REACH substance restrictions on hexavalent chromium force metal-dielectric stack reformulation.
- Metal:Copper and nickel substrates serve specialized applications requiring thermal conductivity or mechanical durability in harsh environments.
- Plastic:Replicated polymer gratings from master holographic templates enable mass production for disposable and consumer-grade optical sensors.
Glass substrates anchor established demand. Coated substrates are gaining share fastest as reflection grating applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes optical gratings for semiconductor metrology and pharmaceutical spectroscopy at specification levels exceeding those in cost-sensitive Asian markets, where volume production of portable instruments dominates procurement patterns.
Germany
Wafer inspection equipment builders in Dresden and Munich source ion-beam etched reflection gratings for EUV lithography systems. ECHA REACH substance restrictions on coating materials force requalification of alternative metal-dielectric stacks. The precision optics cluster around Jena and Oberkochen anchors high-end grating production through captive etching infrastructure.
United States
Pharmaceutical quality control laboratories in New Jersey and Massachusetts upgrade dispersive optics to meet FDA analytical instrument validation guidelines. EPA environmental monitoring contracts specify stray light performance below 0.001% for water quality spectroscopy. Fused silica substrate supply constraints from domestic synthetic quartz producers periodically disrupt transmission grating availability.
Japan
Semiconductor fabrication equipment manufacturers in Tokyo and Osaka procure blazed gratings for external cavity diode lasers used in wafer inspection. METI industrial technology subsidies support holographic exposure system upgrades that reduce energy consumption. High-purity synthetic quartz production in the Chubu region supplies critical substrate material for precision gratings.
South Korea
Memory chip manufacturers in Gyeonggi Province deploy laser tuning gratings for photolithography process control. The national industrial regulator enforces ISO 10110 surface quality standards for optical components in defense-related programs. Busan-area photonics suppliers expand holographic grating capacity to serve domestic metrology equipment builders.
China
Environmental monitoring agencies in Beijing and Shanghai specify transmission gratings for portable air quality spectrometers. MIIT domestic substitution policies accelerate local production of ruled gratings for educational instruments. The Yangtze River Delta concentration of analytical instrument OEMs drives volume demand for cost-optimized designs.
Optical Gratings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in optical gratings, with capital intensity and regulatory qualification capabilities determining tier membership. German and Japanese producers dominate high-precision reflection and holographic categories through proprietary ion-beam etching infrastructure, while North American suppliers anchor spectroscopy applications through vertically integrated motion control and photonics portfolios. Three archetypes define competitive positioning: capital-intensive etching specialists, vertically integrated analytical instrument OEMs, and cost-focused transmission grating fabricators. Capacity expansion in holographic exposure systems and strategic partnerships for substrate supply security represent the dominant competitive moves.
Within the integrated leader tier, MKS Instruments and Zeiss exemplify divergent paths to premium positioning. MKS Instruments leverages backward integration into motion control and photonics capabilities to serve laser tuning and semiconductor metrology applications. Zeiss anchors high-end reflection grating production through proprietary ion-beam etching infrastructure concentrated in German precision optics clusters. Among specialist suppliers, HORIBA occupies a position bridging analytical instrument integration and component supply.
| Leading Market Players |
|---|
| MKS Instruments |
| Zeiss |
| HORIBA |
| Kaiser Optical Systems |
| Wasatch Photonics |
| Edmund Optics |
| Thorlabs |
| Photop Technologies |
| Shimadzu Corporation |
| Others |
Pricing and Supply Chain Analysis
High fixed costs in ion-beam etching infrastructure create steep scale economies that concentrate production in Germany's Jena-Oberkochen precision optics cluster, elevating price floors for semiconductor-grade reflection gratings while compressing margins for transmission grating fabricators lacking captive substrate supply.
Pricing Analysis
Multi-year calibration and maintenance contracts generate the dominant share of lifetime value in analytical instrument supply relationships. Three-tier pricing structure across premium, standard, and economy levels separates ion-beam etched reflection gratings from holographic interference products and cost-optimized transmission designs. Cost compression in standard-tier holographic gratings is intensifying because consolidated procurement by pharmaceutical OEMs bundles hardware with service obligations. University teaching laboratories exhibit the highest price sensitivity, while semiconductor metrology equipment builders absorb premium pricing for sub-nanometer groove stability.
Supply Chain Analysis
Synthetic quartz production capacity in Japan's Chubu region and the United States constitutes a chokepoint that periodically disrupts transmission grating availability for portable instrument manufacturers. High-purity fused silica, aluminum and gold reflective coatings, and photoresist materials feed from concentrated geographic sources. Single-source vulnerability in Japanese substrate supply creates exposure to export licensing delays. Distribution runs through analytical instrument OEMs and specialized photonics distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mastering sub-nanometer groove profile control requires decades of apprenticeship; the thinning pipeline of qualified ion-beam etching technicians in Germany and Japan now constrains expansion capacity more than capital availability.
For Market Incumbents: Secure captive supply of high-purity synthetic quartz through long-term offtake agreements with Japanese producers, insulating against substrate shortages that disrupt transmission grating delivery schedules. Deepen backward integration into holographic exposure system manufacturing to capture margin from solvent-free process adoption driven by ECHA REACH substance restrictions. For New Entrants and Emerging Players: Differentiate on regulatory qualification speed for CDSCO-harmonized diagnostic spectrometers in India's underpenetrated biomedical imaging segment. Target hyperspectral imaging module supply for precision agriculture outside traditional analytical instrument channels, where machine vision integrators lack established grating procurement relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among holographic grating suppliers serving pharmaceutical quality control laboratories with multi-year validation protocols. Long-term viability hinges on regulatory qualification moats rather than manufacturing scale alone. Monitor ECHA authorization timelines for alternative metal-dielectric coating stacks as an inflection indicator for compliance-driven supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Holographic Exposure Systems | Reduces energy consumption per grating while meeting EU Green Deal manufacturing incentives. |
| Backward Integration into Synthetic Quartz Supply | Secures substrate availability against Japanese production constraints and export licensing delays. |
| Regulatory Qualification Acceleration | Compresses ISO 10110 surface quality certification timelines for medical diagnostic spectrometer supply chains. |
| Hyperspectral Module Partnership | Opens distribution outside traditional analytical instrument channels through precision agriculture integrators. |
| Alternative Coating Stack Development | Eliminates hexavalent chromium dependencies ahead of tightened ECHA REACH authorization requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and patent disclosures. Interviews with precision optics manufacturing directors, analytical instrument OEM procurement leads, semiconductor metrology equipment engineers, and photonics distribution specialists informed supply chain and pricing dynamics. Secondary validation drew from ECHA substance restriction databases, FDA analytical instrument guidance documents, ISO standards publications, and METI industrial technology subsidy records. Bottom-up grating production estimates triangulated against top-down analytical instrument market sizing.
Segmentation dimensions modeled include product architecture, application environment, end-user procurement authority, and substrate material composition across the analysis window. CAGRs derived from installed base replacement cycles, regulatory upgrade mandates, and emerging application penetration curves. Forecast inputs incorporated EUV lithography equipment deployment schedules and pharmaceutical quality control laboratory capital expenditure patterns.
Decision-makers should treat outputs as directional under assumptions of stable photonics export control regimes and sustained REACH compliance timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA authorization decisions and synthetic quartz supply allocation policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Telescope Market
Optics
Global Fiber Optic Components Market
Optics
Acrylic Lenses Market
Optics
Europe Laser Interferometer Market
Optics
Optical Profilometer Market
Optics
Photostimulation Lasers Market
Optics
Picosecond Lasers Market
Optics
Fiber Optics Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Beam Expanders Market
Optics
Optical Liquid Level Sensor Market
Optics
Optical Fiber Raw Material Market
Optics
Global Nanophotonics Market
Optics
Optical Imaging Market
Optics
Laser Transmitter Market
Optics
US Photonics Market