
 3D Holographic Display Market | 2026-2036
3D Holographic Display Market Size, Share, and Industry Trends Forecast 2026-2036
3D Holographic Display Market Analytics
Light-field modulation is reconfiguring how spatial imagery gets rendered without wearable optics, collapsing the barrier between volumetric data and naked-eye viewing. Samsung Electronics leverages its semiconductor foundry scale to control core micro-display component supply. VividQ Ltd. anchors its position through proprietary software algorithms for real-time holographic computation. Looking Glass Factory Inc. specializes in desktop-format autostereoscopic panels for design and engineering workflows.
A 3D holographic display reconstructs light waves through interference patterns to produce volumetric images viewable without head-mounted apparatus, typically employing spatial light modulators with pixel pitches below ten micrometers for adequate angular resolution. The primary commercial purpose spans medical imaging, where surgeons manipulate floating organ reconstructions during preoperative planning, through retail advertising deploying holographic kiosks for product interaction. Laser-based technology currently leads hardware shipments due to mature coherent light sources, while electro-holographic approaches represent the fastest-expanding segment as computational holography chips shrink latency thresholds. Medical imaging applications command premium margin pools because regulatory validation creates defensible pricing tiers against consumer entertainment use cases.
FCC emissions compliance and CE marking requirements under EU machinery directives shape hardware design cycles and market access timelines for display manufacturers. FDA scrutiny of holographic outputs for diagnostic use imposes additional validation burdens on medical-grade product lines. ISO 13485 quality management standards increasingly factor into procurement decisions by hospital systems evaluating holographic visualization investments. Stakeholders must weigh the capital intensity of custom silicon development against the risk of modular component commoditization as foundry capacity broadens.
Market Dynamics
Spatial light modulator pixel pitch compression below ten micrometers is collapsing the barrier between laboratory holography and commercial deployment, forcing foundry capacity allocation decisions across semiconductor supply chains.
Growth Catalysts
- FCC Part 15 emissions frameworks:Tighter electromagnetic standards under US regulations are accelerating certification investments by hardware manufacturers, filtering out undercapitalized entrants and consolidating procurement toward validated suppliers.
- Surgical planning workflows:Hospital systems in California and Texas technology corridors are expanding capital budgets for holographic visualization suites, treating volumetric organ reconstructions as standard preoperative infrastructure.
- Electro-holographic computation:Dedicated holography processing chips are shrinking latency thresholds for real-time light-field rendering, enabling interactive frame rates previously restricted to offline batch processing.
Market Restraints
- Custom silicon foundry concentration:Advanced spatial light modulator production concentrates among three East Asian contract manufacturers, exposing lead time vulnerability to geopolitical friction or capacity reallocation toward consumer electronics.
- Laser source input volatility:Coherent light module costs fluctuate with rare-earth element pricing and precision optics polishing capacity, compressing margin predictability for system integrators.
- CE marking machinery directive friction:EU conformity assessment timelines for holographic display hardware extend eighteen to twenty-four months, delaying revenue recognition for European market entry strategies.
Strategic Opportunities
- Retail advertising kiosks:Product interaction holography remains underdeployed in US shopping malls and airport terminals, offering first-mover positioning before format standardization commoditizes hardware.
- ISO 13485 certification pathways:Medical-grade quality management validation creates defensible pricing tiers against consumer entertainment use cases, rewarding early investment in hospital system procurement frameworks.
- Computational holography plus edge AI:Convergence of real-time rendering algorithms with localized neural processing enables gesture-controlled volumetric interfaces without cloud latency dependencies.
Industry Challenges
- Multiphysics simulation talent scarcity:Design of interference-pattern optics requires expertise spanning Fourier optics, semiconductor physics, and thermal management, with fewer than two hundred qualified engineers available globally.
- FDA diagnostic output validation:Holographic displays intended for radiological interpretation face twelve-to-eighteen-month premarket notification timelines, compressing product development runway against competitive pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Holographic Display Market |
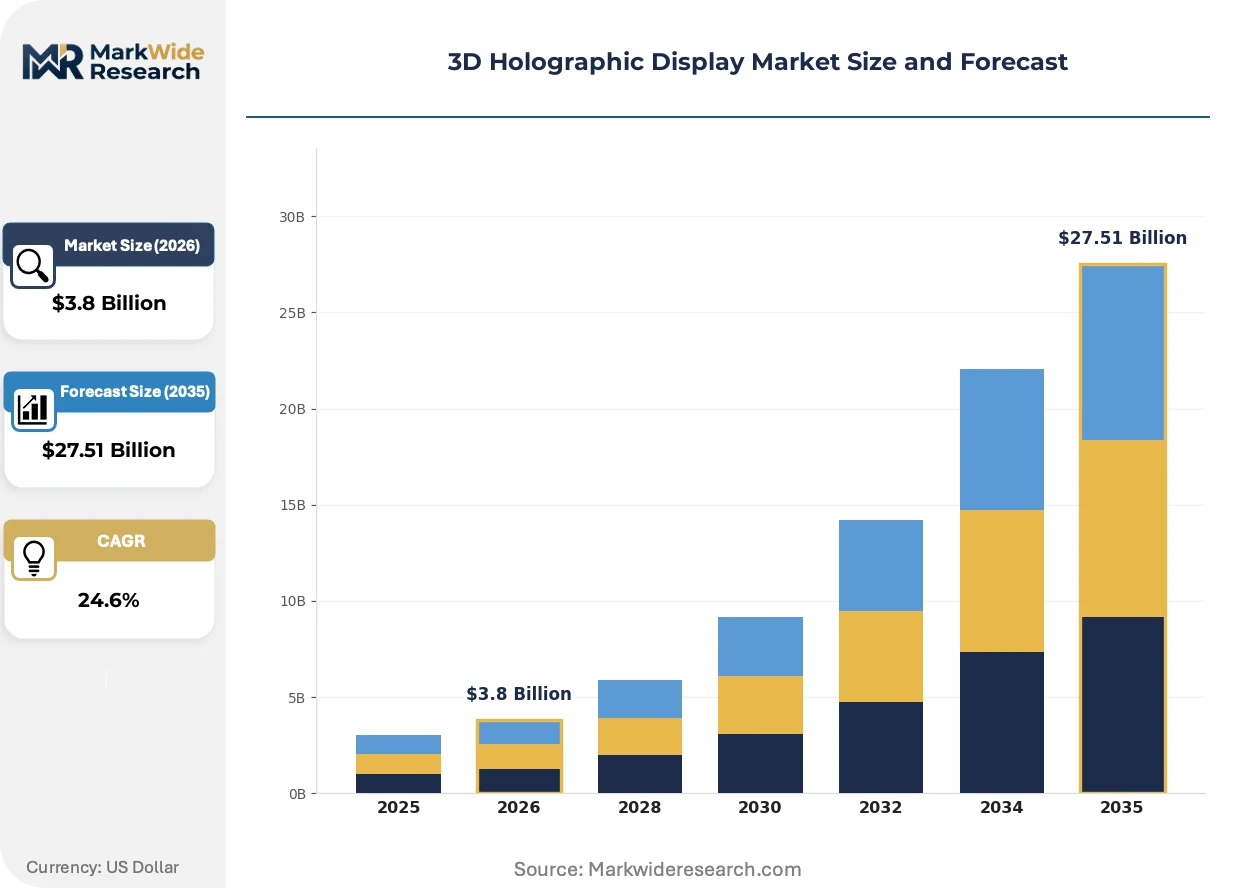
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Laser-based, Electro-holographic, Digital Light Processing, Autostereoscopic End User: Entertainment, Retail, Healthcare, Education Application: Advertising, Training Simulations, Medical Imaging, Product Visualization Product Type: Holographic Screens, Holographic Projectors, Holographic Kiosks, Holographic Displays |
| Companies Covered | Samsung Electronics Co., Ltd., VividQ Ltd., Looking Glass Factory Inc., Leia Inc., MDH Hologram Ltd., RealView Imaging Ltd., EON Reality, Voxon Photonics, RealFiction Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Holographic Display Market Evolving Landscape
Light-field modulation architectures are reconfiguring competitive positioning by eliminating wearable optics requirements, collapsing the distinction between volumetric data sources and naked-eye consumption interfaces across medical and commercial segments.
Electro-holographic display technology reconstructs light waves through computer-generated interference patterns rather than physical optical elements. Medical imaging departments in US hospital systems are adopting these systems for surgical preplanning at twelve-to-eighteen-month replacement cycles. The technology is migrating from laboratory prototyping environments into standardized product configurations with defined service level agreements and field support infrastructure.
EU machinery directives under CE marking frameworks now explicitly classify holographic display hardware as covered equipment, requiring electromagnetic compatibility testing and technical file documentation previously exempt for prototype deployments. Industrial consequences include mandatory notified body involvement for all volume shipments into European markets. Medical-grade product lines face the most severe timeline compression, as manufacturers must sequence CE conformity ahead of FDA diagnostic use submissions to maintain parallel market access.
Hospital procurement committees are consolidating vendor selection authority into centralized biomedical engineering departments, displacing decentralized department-level purchasing for holographic visualization investments. Group purchasing organizations are capturing thirty to forty percent of US hospital system orders, replacing direct manufacturer relationships. This concentration is most visible in Texas and California technology corridors, where integrated delivery networks command sufficient volume to negotiate enterprise-wide installation and maintenance contracts.
3D Holographic Display Market Segmentation
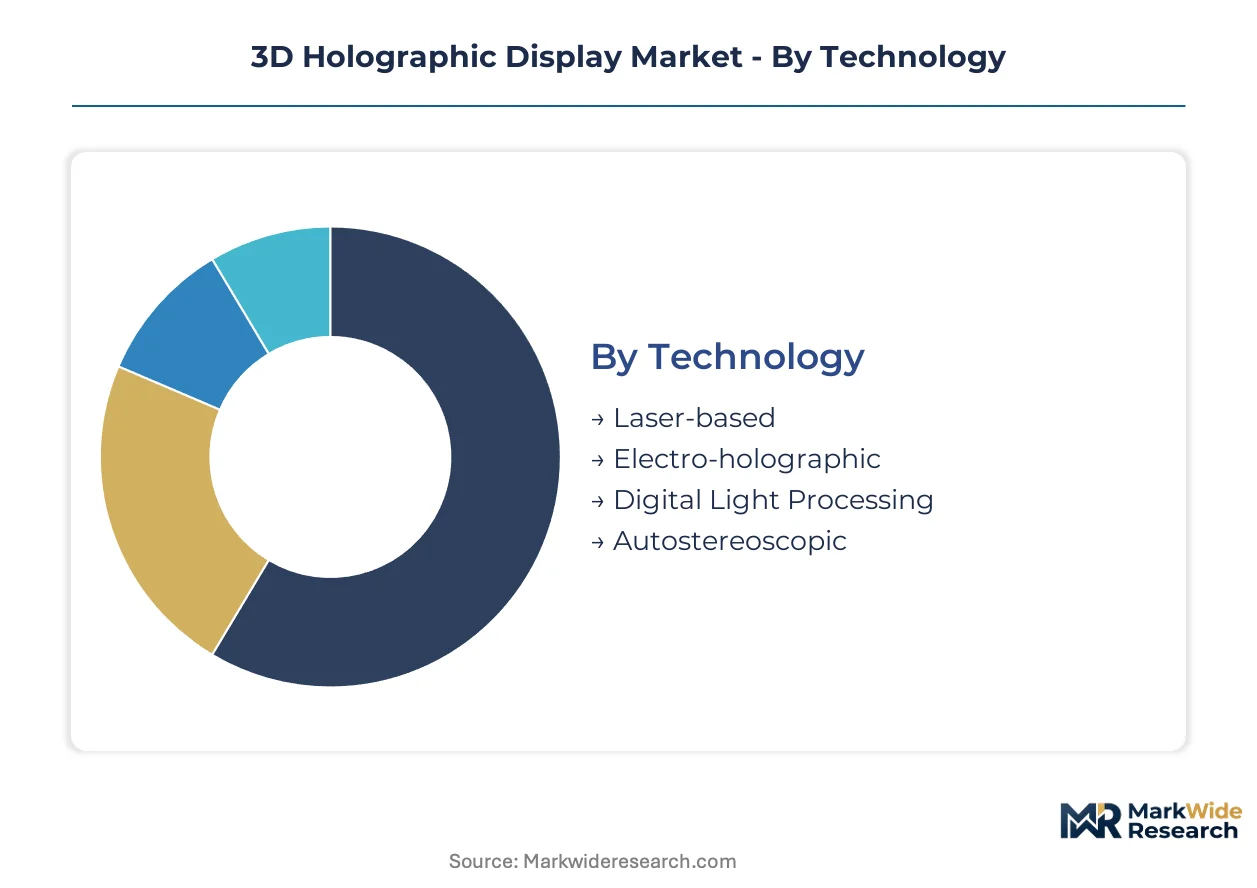
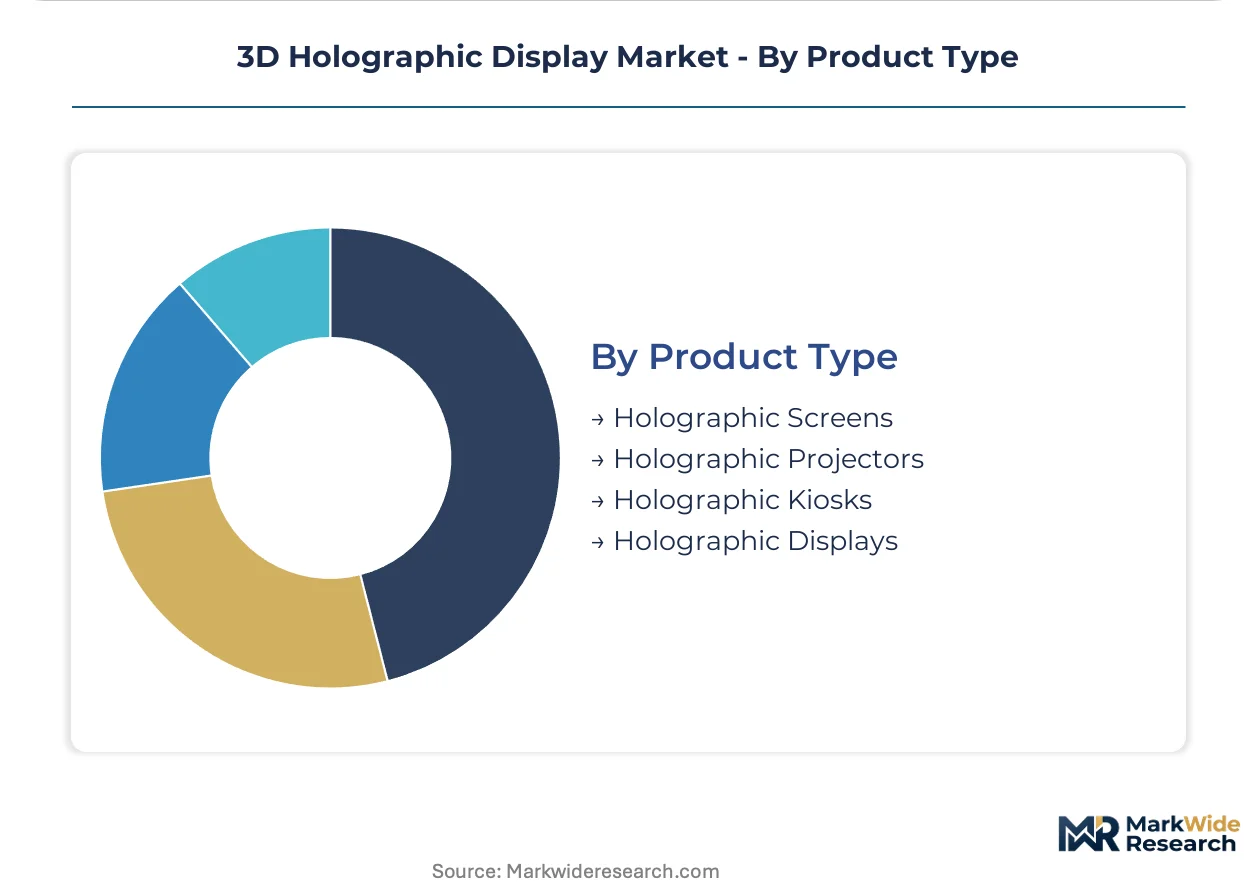
Service intensity varies sharply across 3D holographic display configurations, with medical-grade installations demanding continuous calibration support while retail kiosks operate on break-fix models. Procurement committees weigh total cost of ownership differently depending on which segment dominates their use case.
Technology:
After-sales service intensity escalates with computational complexity, as electro-holographic systems require firmware updates and optical alignment that laser-based hardware rarely needs.
- Laser-based:Coherent light sources generate interference patterns through physical optics with minimal post-installation tuning. Hospital systems in California and Texas technology corridors favor these systems for surgical planning suites where stability outweighs upgrade flexibility.
- Electro-holographic:Real-time computation of light fields demands dedicated holography processing chips and recurring software maintenance. FCC Part 15 emissions compliance adds validation overhead that filters out undercapitalized vendors.
- Digital Light Processing:Mature micromirror arrays reduce field service dependency through standardized DLP chipsets.
- Autostereoscopic:Lenticular or parallax barrier approaches eliminate eyewear but require precise viewer positioning calibration.
By volume, laser-based leads. By expansion trajectory, electro-holographic is climbing the fastest.
End User:
Customer procurement sophistication determines margin capture, with healthcare buyers demanding ISO 13485 certification that entertainment clients rarely require.
- Healthcare:FDA scrutiny of diagnostic outputs imposes twelve-to-eighteen-month premarket notification timelines. Biomedical engineering departments in US hospital systems now centralize vendor selection authority, displacing decentralized department-level purchasing.
- Retail:Shopping mall and airport terminal deployments remain underpenetrated, offering first-mover positioning before format standardization commoditizes hardware. Group purchasing organizations capture limited share here compared to hospital networks.
- Entertainment:Consumer venues prioritize visual impact over regulatory validation, compressing sales cycles but squeezing pricing power.
- Education:Institutional procurement moves through extended budget approval processes with heavy reliance on grant funding cycles.
Healthcare commands premium tiers. Retail is gaining share fastest.
Application:
Application-specific performance requirements drive component selection, with medical imaging demanding sub-ten-micrometer pixel pitches that advertising content rarely needs.
- Medical Imaging:Volumetric organ reconstructions for preoperative planning require spatial light modulators with adequate angular resolution. Replacement cycles run twelve-to-eighteen months as hospital systems treat holographic visualization as standard infrastructure.
- Advertising:Product interaction holography in US retail environments benefits from lower regulatory barriers but faces shorter technology obsolescence horizons. CE marking machinery directive friction extends EU market entry timelines eighteen to twenty-four months.
- Training Simulations:Gesture-controlled volumetric interfaces converge computational holography with edge AI to eliminate cloud latency dependencies.
- Product Visualization:Engineering workflows demand desktop-format panels with defined service level agreements and field support infrastructure.
Medical imaging dominates value capture. Advertising shows the steepest expansion trajectory.
Product Type:
Physical form factor determines installation complexity and recurring revenue potential, with integrated kiosk systems offering bundled maintenance contracts that standalone projectors cannot match.
- Holographic Kiosks:Self-contained units combine display, computation, and enclosure for retail and airport deployments. EU machinery directives now explicitly classify these as covered equipment, mandating notified body involvement for volume shipments.
- Holographic Displays:Desktop-format autostereoscopic panels serve design and engineering workflows with standardized product configurations. Samsung Electronics leverages semiconductor foundry scale to control core micro-display component supply for this category.
- Holographic Screens:Large-format installations for entertainment venues require custom mounting and environmental hardening.
- Holographic Projectors:Modular systems allow component upgrades but expose integrators to laser source input volatility from rare-earth element pricing swings.
Displays lead by shipment volume. Kiosks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in California and Texas technology corridors are expanding capital budgets for holographic visualization suites, while European manufacturers navigate eighteen-to-twenty-four-month CE marking timelines under machinery directives.
United States
FDA scrutiny of diagnostic holographic outputs imposes twelve-to-eighteen-month premarket notification burdens on medical-grade product lines. FCC Part 15 emissions frameworks accelerate certification investments by hardware manufacturers, filtering undercapitalized entrants. California and Texas technology corridors concentrate hospital system procurement authority into centralized biomedical engineering departments.
Germany
Industrial engineering workflows in Baden-Württemberg drive demand for desktop-format autostereoscopic panels with defined service level agreements. CE marking requirements under EU machinery directives explicitly classify holographic display hardware as covered equipment, mandating notified body involvement. Munich and Stuttgart clusters anchor precision optics polishing capacity for coherent light modules.
China
MIIT standards for electromagnetic compatibility shape hardware design cycles for domestic display manufacturers. Spatial light modulator foundry capacity concentrates among East Asian contract manufacturers, exposing lead time vulnerability to capacity reallocation. Shenzhen and Shanghai technology corridors integrate holographic kiosks into retail advertising infrastructure.
Japan
METI industrial policy supports computational holography chip development to shrink latency thresholds for real-time light-field rendering. PMDA regulatory pathways for medical device approval create parallel validation requirements for diagnostic-grade displays. Tokyo and Osaka metropolitan areas host surgical planning workflow adoption in university hospital systems.
South Korea
MFDS quality management standards factor into procurement decisions by hospital systems evaluating holographic visualization investments. Samsung Electronics leverages semiconductor foundry scale to control core micro-display component supply. Seoul Capital Area technology clusters drive electro-holographic computation hardware development.
3D Holographic Display Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating toward validated suppliers capable of navigating multi-jurisdictional certification timelines. The vendor base separates into three strategic archetypes: semiconductor foundry-scale integrators controlling upstream component supply, software-algorithm specialists anchoring real-time holographic computation, and desktop-format panel manufacturers serving design and engineering workflows. Dominant competitive moves include strategic partnerships for foundry capacity allocation and technology licensing for FCC and CE marking compliance acceleration.
Within the semiconductor-scale tier, Samsung Electronics Co., Ltd. exemplifies upstream control over micro-display component supply chains. VividQ Ltd. and Looking Glass Factory Inc. represent contrasting archetypes—proprietary software algorithm development versus specialized desktop-format autostereoscopic panel manufacturing. These three companies occupy positions spanning foundry integration, computational holography, and workflow-specific hardware deployment.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| VividQ Ltd. |
| Looking Glass Factory Inc. |
| Leia Inc. |
| MDH Hologram Ltd. |
| RealView Imaging Ltd. |
| EON Reality |
| Voxon Photonics |
| RealFiction Holding AB |
| Others |
Value Network & Pricing Analysis
East Asian foundry clusters in Taiwan and South Korea concentrate spatial light modulator fabrication, translating tight pixel-pitch capacity into pricing leverage for downstream display integrators serving California hospital procurement committees.
Pricing Analysis
Cost-plus contracts with rare-earth element indexation dominate coherent light module procurement, exposing system integrators to neodymium and yttrium price swings. Three-tier pricing structure across medical-grade, commercial-grade, and consumer-grade certification levels separates FDA-validated installations from retail kiosk deployments. Cost compression in commercial-grade tiers intensifies as Shenzhen-based competitors expand electro-holographic chipset supply. Hospital systems demonstrate lowest price sensitivity due to ISO 13485 quality requirements, while retail advertising buyers prioritize capital expenditure minimization over service bundling.
Supply Chain Analysis
Supplier-financing facilities with ninety-day extended payment terms have become standard for spatial light modulator procurement from Taiwanese and South Korean foundries. The supply chain draws from precision optics polishing capacity in Germany and Japan alongside semiconductor fabrication in East Asia. Single-source vulnerability concentrates in sub-ten-micrometer pixel-pitch production nodes. Distribution runs through biomedical engineering departments in integrated delivery networks for medical-grade systems, while retail kiosks deploy through systems integrators with field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fewer than two hundred qualified multiphysics simulation engineers globally constrain design throughput, creating scarcity premiums for teams capable of Fourier optics and thermal management integration.
For Market Incumbents: Insulate core margin pools by securing captive foundry allocation for sub-ten-micrometer spatial light modulator production against emerging Chinese electro-holographic chipset vendors. Accelerate FDA premarket notification submissions ahead of CE marking sequences to compress parallel market access timelines. Prioritize ISO 13485 certification maintenance as hospital procurement centralization raises compliance barriers. For New Entrants and Emerging Players: US shopping mall and airport terminal holographic advertising remains structurally underpenetrated relative to installed base potential in Texas and California corridors. Target retail kiosk deployments with break-fix service models that bypass medical-grade validation overhead. Pursue partnerships with group purchasing organizations for hospital system access rather than direct biomedical engineering department sales cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant holographic display divisions lacking regulatory compliance infrastructure. Frame long-term viability around convergence of computational holography with edge AI processing architectures. Monitor FDA diagnostic output validation queue lengths as inflection signal for medical-grade product line timing.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Part 15 Certification Acceleration | Preemptive electromagnetic compliance investments filter undercapitalized competitors from US hospital procurement pools. |
| Spatial Light Modulator Foundry Partnership | Secured allocation at Taiwanese contract manufacturers insulates against consumer electronics capacity reallocation. |
| ISO 13485 Quality Management Investment | Medical-grade validation creates defensible pricing tiers against consumer entertainment use cases. |
| Retail Kiosk Format Standardization | Self-contained enclosure design reduces field service dependency for shopping mall and airport deployments. |
| Computational Holography Chip Development | Real-time light-field rendering silicon shrinks latency thresholds for interactive surgical planning workflows. |
Research Methodology
A standing panel of biomedical engineering directors, surgical planning workflow leads, FCC certification consultants, spatial light modulator foundry managers, and retail systems integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, CE marking technical file registries, hospital procurement committee minutes, and semiconductor foundry capacity disclosure filings. Bottom-up shipment estimates triangulated against top-down addressable market sizing by technology tier and end-use application.
Scenario-bracketing framed volume and value outputs across the projection horizon, with electro-holographic versus laser-based technology splits, medical imaging versus advertising application mixes, and geographic regulatory cluster differentiation as core segmentation dimensions. CAGRs derived from fitted growth curves applied to technology-specific adoption S-cycles, incorporating spatial light modulator pixel-pitch compression trajectories and hospital capital budget cycle patterns as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or rare-earth element pricing volatility would shift the trajectory. Forecasts reflect assumptions around regulatory timeline stability and foundry capacity allocation continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
OLED Display Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Industrial Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Low Power Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
OLED Panel Market
Display Technologies
Microdisplay Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Screenless Display Market
Display Technologies
Head Up Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Global UHD Display Market
Display Technologies
Global Next Generation Display Market