
 North America Micro-LED Display Market | 2026-2036
North America Micro-LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micro-LED Display Market Insights
Sub-10-micron pixel pitch specification is redrawing competitive boundaries across premium display tiers. Apple Inc. leverages captive semiconductor design teams to control chiplet architecture roadmaps. Samsung Electronics anchors volume manufacturing through its vertical display foundry network. LG Display specializes in large-format substrate bonding techniques for television panels.
North America Micro-LED Display denotes a self-emissive display technology utilizing indium gallium nitride (InGaN) micro-diodes measuring under 50 micrometers, assembled via mass transfer onto backplane substrates to deliver luminance exceeding 5,000 nits with sub-millisecond response times for daylight-visible and high-dynamic-range applications. RGB technology leads current shipments due to its color fidelity demands in consumer electronics, while transparent configurations represent the fastest-expanding margin pool as retailers integrate see-through storefront displays. Flexible technology occupies a nascent but strategically defended position among wearable device contracts.
The FCC governs electromagnetic interference thresholds for display modules deployed in connected vehicle dashboards, while the EPA's ENERGY STAR specifications constrain standby power draw for commercial digital signage installations. OSHA workplace safety standards influence luminance exposure limits for industrial display deployments in manufacturing floors. Stakeholders must weigh California's Title 24 building efficiency codes against Texas and Arizona manufacturing incentives when siting micro-LED fabrication facilities.
Market Dynamics
Sub-10-micron pixel pitch specifications are compressing manufacturing yields and redrawing competitive boundaries across premium display tiers. The EPA's tightening ENERGY STAR standby power limits and the FCC's electromagnetic interference thresholds for connected vehicle dashboards are forcing simultaneous compliance investments.
Growth Catalysts
- Automotive cockpit digitization:Detroit and Silicon Valley OEMs are expanding procurement of high-brightness displays for daylight-visible instrument clusters. Michigan's manufacturing belt concentrates contract awards.
- EPA commercial display efficiency mandates:The agency's standby power draw specifications for digital signage are accelerating replacement cycles in retail and corporate deployments.
- InGaN micro-diode luminance performance:Self-emissive architectures exceeding 5,000 nits are displacing incumbent LCD backlighting in outdoor and high-ambient applications.
Market Restraints
- Mass transfer yield volatility:Sub-50-micrometer die placement precision requirements create input cost instability for bonding equipment and inspection systems.
- Substrate supply concentration:Advanced glass and silicon backplane sourcing clusters in East Asian foundry networks, exposing North American module assemblers to logistics friction.
- Thermal management complexity:High-density micro-diode arrays generate localized heat loads that exceed passive dissipation limits in compact form factors.
Strategic Opportunities
- Transparent display retail integration:See-through storefront configurations in California's technology corridor represent an underpenetrated margin pool for architectural and luxury goods advertising.
- Flexible substrate wearables:Nascent contracts for curved and bendable micro-LED panels target health monitoring and augmented reality headset form factors.
- Texas and Arizona manufacturing incentives:State-level tax abatements and infrastructure grants are attracting backplane fabrication and mass transfer equipment investments.
Industry Challenges
- Chiplet architecture talent scarcity:Captive semiconductor design capabilities for heterogeneous integration remain concentrated among a handful of vertically integrated technology groups.
- FCC electromagnetic compliance timelines:Connected vehicle dashboard modules face extended certification cycles for electromagnetic interference validation.
- RGB pixel repair infrastructure:Sub-10-micron defect detection and localized replacement require capital-intensive inspection and rework cell deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micro-LED Display Market |
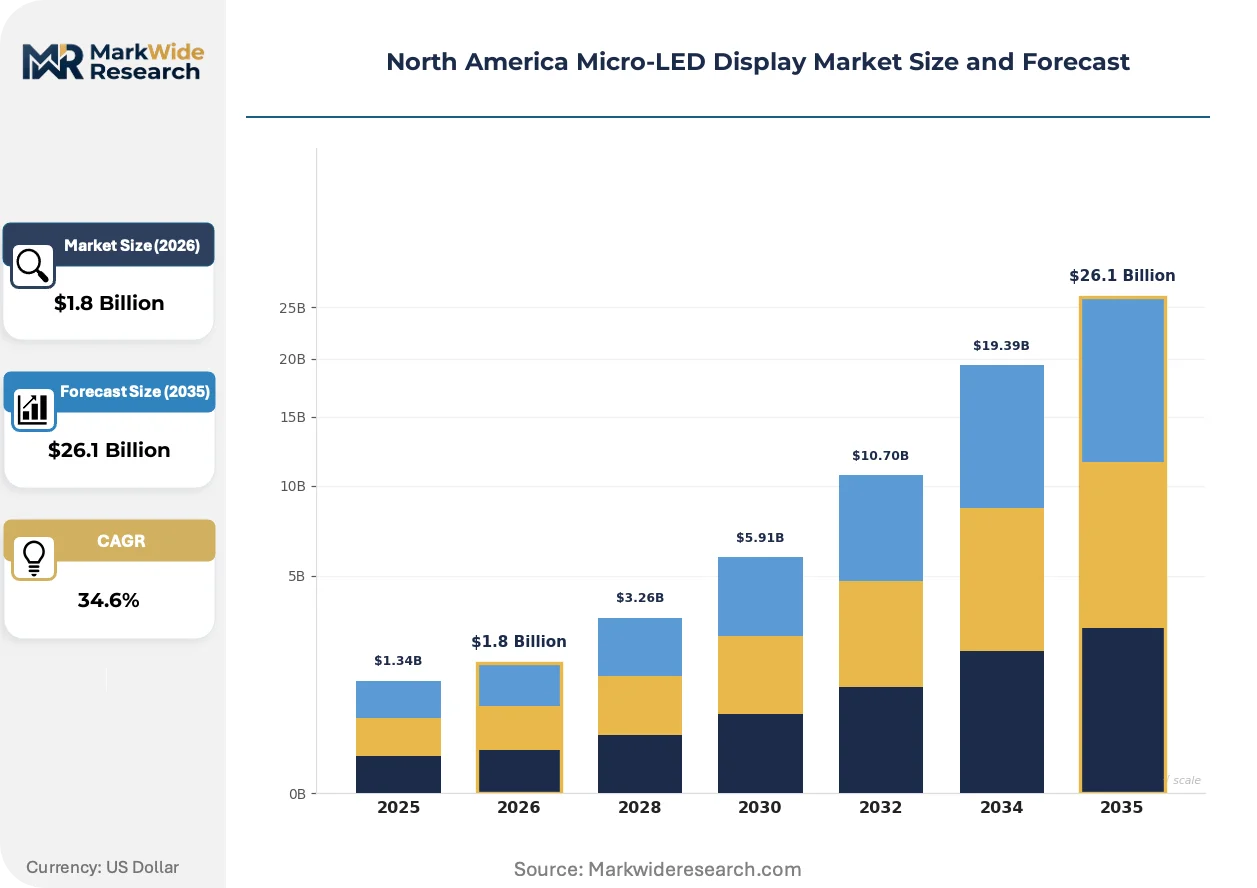
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.1 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TV, Smartphone, Wearable, Digital Signage End User: Consumer Electronics, Automotive, Retail, Advertising Technology: RGB, Monochrome, Transparent, Flexible Application: Home Entertainment, Industrial Displays, Outdoor Advertising, Automotive Displays |
| Companies Covered | Apple Inc., Samsung Electronics, LG Display, Sony Corporation, Epistar Corporation, Lumiode Inc., Aledia SA, PlayNitride, Ostendo Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micro-LED Display Market Trends and Innovations
Mass transfer bonding architectures are fragmenting along equipment vendor lines as display assemblers pursue divergent throughput-yield tradeoffs. The convergence of automotive safety requirements and retail energy efficiency mandates is compressing product development cycles.
Laser-assisted die placement is fragmenting conventional pick-and-place dominance in micro-LED assembly workflows. Tier-one display foundries in Taiwan and South Korea are adopting ultraviolet laser lift-off systems for 10,000+ dies-per-second throughput. This equipment shift is compressing capital recovery timelines for North American module houses that lack comparable bonding scale.
The FCC's electromagnetic interference thresholds for connected vehicle dashboards are tightening test protocol stringency for cockpit display modules. Automotive OEMs in Detroit now require pre-certified sub-assemblies that meet FCC Part 15 Class B limits before system integration. This regulatory compression is favoring suppliers with captive electromagnetic compatibility laboratories over smaller module integrators.
Buyer concentration among Detroit automotive OEMs and Silicon Valley technology platforms is shortening contract renewal cycles from multi-year frameworks to annual performance reviews. Procurement teams now unbundle display hardware from software integration services, forcing specialized bonding houses to compete directly with vertically integrated foundries. This disintermediation is most visible in Michigan's automotive supply base and California's consumer electronics procurement corridors.
North America Micro-LED Display Market Segmentation
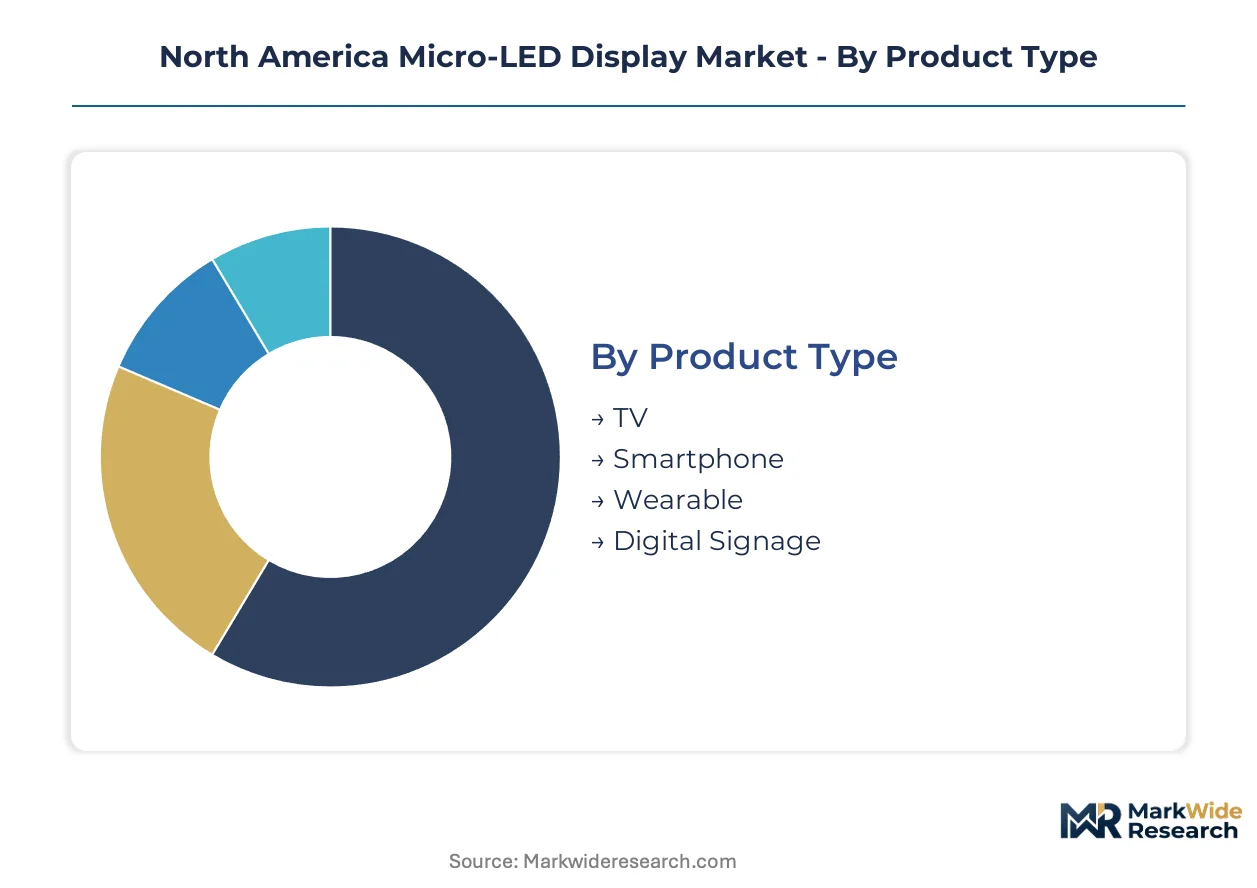
Micro-LED display procurement channels diverge sharply by technical specification and end-use certification requirements. Each segment category channels through distinct buyer concentrations and regulatory compliance pathways across the North American supply base.
Product Type:
TV panels flow through retail electronics distributors, while automotive and wearable modules route through tier-one system integrators with captive bonding capabilities.
- TV:Large-format substrate bonding demands specialized equipment for backplane assembly. Procurement concentrates among California-based technology platforms seeking high-dynamic-range home entertainment panels, though thermal management complexity constrains compact form factor deployment.
- Smartphone:Sub-10-micron pixel pitch specifications dominate technical requirements. Michigan's automotive belt and Silicon Valley OEMs are expanding procurement of daylight-visible configurations, displacing incumbent OLED in premium tier devices.
- Wearable:Compact form factors prioritize power efficiency and luminance performance in health monitoring applications.
- Digital Signage:Commercial deployments face EPA ENERGY STAR standby power mandates that accelerate replacement cycles.
By volume, TV leads procurement. By expansion trajectory, smartphone is climbing the fastest.
End User:
Cost tier differentiation separates consumer electronics volume from automotive and retail margin premiums.
- Consumer Electronics:RGB color fidelity requirements dominate specification sheets for premium device tiers. California's technology corridor concentrates demand for sub-millisecond response time panels in gaming and mobile applications.
- Automotive:FCC Part 15 Class B electromagnetic compliance is mandatory before Detroit OEMs integrate cockpit modules. Daylight-visible instrument clusters exceeding 5,000 nits are displacing LCD backlighting across Michigan's manufacturing belt.
- Retail:Transparent configurations enable see-through storefront advertising in luxury goods corridors.
- Advertising:Outdoor deployments require high-brightness performance against ambient light interference.
Consumer electronics commands the largest volume share. Automotive is gaining share fastest on safety digitization mandates.
Technology:
Manufacturing yield curves separate mature RGB production from emerging transparent and flexible architectures.
- RGB:Full-color indium gallium nitride micro-diode arrays deliver color fidelity for consumer and automotive applications. Current shipments concentrate in premium television and smartphone tiers where color gamut specifications exceed incumbent display technologies.
- Monochrome:Single-color configurations serve industrial indicator and heads-up display applications with simplified bonding requirements.
- Transparent:See-through pixel architectures integrate architectural glass and retail storefront systems. California retailers are piloting installations that overlay digital content on physical merchandise visibility.
- Flexible:Curved substrate bonding targets nascent wearable and augmented reality headset form factors with bendable mechanical properties.
RGB dominates current output. Transparent is expanding most quickly on retail architectural integration.
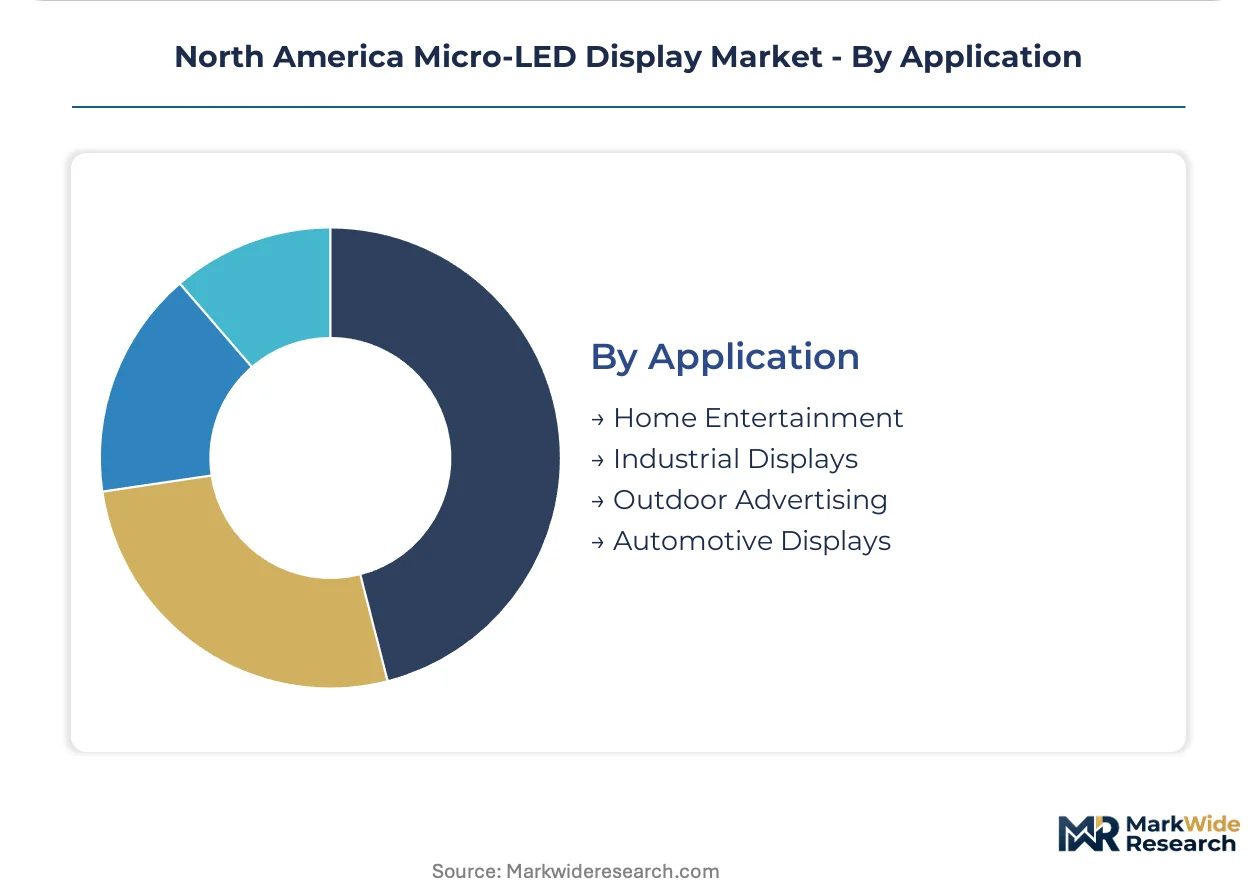
Application:
Geography clusters separate home entertainment demand from industrial and outdoor commercial deployments.
- Home Entertainment:Large-format television panels prioritize luminance uniformity and HDR performance. Texas and Arizona manufacturing incentives are attracting backplane fabrication investments to serve residential demand concentration.
- Industrial Displays:OSHA workplace safety standards constrain luminance exposure limits for manufacturing floor deployments. Ruggedized form factors face thermal management challenges in high-ambient industrial environments.
- Outdoor Advertising:High-brightness specifications exceeding 5,000 nits enable daylight visibility against direct solar loading. EPA efficiency mandates constrain standby power draw for permanent installations.
- Automotive Displays:Connected vehicle dashboard modules require pre-certified electromagnetic compliance before Detroit OEM system integration. Sub-50-micrometer die placement precision creates input cost instability for bonding equipment procurement.
Home entertainment leads by installed base. Automotive displays show the steepest expansion trajectory on cockpit digitization investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in micro-LED display components tilt toward import dependence for backplane substrates and mass transfer equipment, while module assembly and system integration concentrate regionally. The United States dominates North American demand, with Canada and Mexico playing specialized roles in supply chain positioning.
United States
California's technology corridor drives consumer electronics procurement, while Michigan's automotive belt concentrates cockpit display contracts. The FCC's electromagnetic interference thresholds for connected vehicle dashboards mandate pre-certification before Detroit OEM integration. Texas and Arizona manufacturing incentives are attracting backplane fabrication investments to serve residential and commercial demand clusters.
Canada
Ontario's advanced manufacturing base supports precision equipment supply for mass transfer bonding workflows. Health Canada's electromagnetic compatibility standards align with FCC thresholds, facilitating cross-border component certification. Quebec's photonics research clusters contribute to micro-diode characterization and inspection system development.
Mexico
Baja California's electronics assembly corridor handles module integration for re-export to United States retail channels. The country's national standards body coordinates with EPA efficiency benchmarks for digital signage deployments. Nuevo León's industrial parks are positioning for tier-two supplier contracts in automotive display sub-assembly.
North America Micro-LED Display Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and captive semiconductor design capabilities. The vendor base stratifies between vertically integrated technology platforms with in-house chiplet architecture teams and specialized bonding houses dependent on external equipment vendors. Three archetypes dominate: captive semiconductor designers controlling heterogeneous integration roadmaps, volume display foundries with vertical manufacturing networks, and substrate bonding specialists focused on large-format television panels. Competitive moves center on electromagnetic compliance laboratory investments and state-level manufacturing incentive capture.
Among technology-platform incumbents, Apple Inc. and Samsung Electronics occupy positions at the premium-tier vector, while LG Display exemplifies the substrate bonding specialist archetype. These three entities anchor distinct competitive vectors through their respective strengths in semiconductor design, vertical manufacturing scale, and large-format panel assembly techniques.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| LG Display |
| Sony Corporation |
| Epistar Corporation |
| Lumiode Inc. |
| Aledia SA |
| PlayNitride |
| Ostendo Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
InGaN micro-diode substitution for conventional LCD backlighting is redrawing procurement geography across North American module houses while compressing margin structures for bonding equipment dependent on East Asian foundry networks. This input transition simultaneously elevates pricing power for captive semiconductor designers and erodes assembler margins exposed to mass transfer yield volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for automotive cockpit modules, with pricing stratifying across FCC pre-certification tier, volume scale, and thermal management complexity. Price differentiation runs through electromagnetic compliance grade and die placement precision specifications. Cost compression in standard-tier smartphone panels is intensifying because substrate supply concentration exposes assemblers to logistics friction. Tier-one system integrators exhibit lowest price sensitivity due to captive bonding capabilities, while specialized module houses face acute margin pressure.
Supply Chain Analysis
Inventory cycles for mass transfer bonding equipment stretch 18-24 months, constraining North American capacity expansion timelines. Backplane substrate sourcing draws from Taiwan, South Korea, and Japan, while InGaN epitaxy wafers feed from specialized foundry networks in the same corridor. Single-source vulnerability in ultraviolet laser lift-off systems creates procurement risk for module assemblers lacking equipment vendor diversification. Distribution runs through tier-one system integrators for automotive and wearable contracts, with retail electronics distributors handling television panel flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
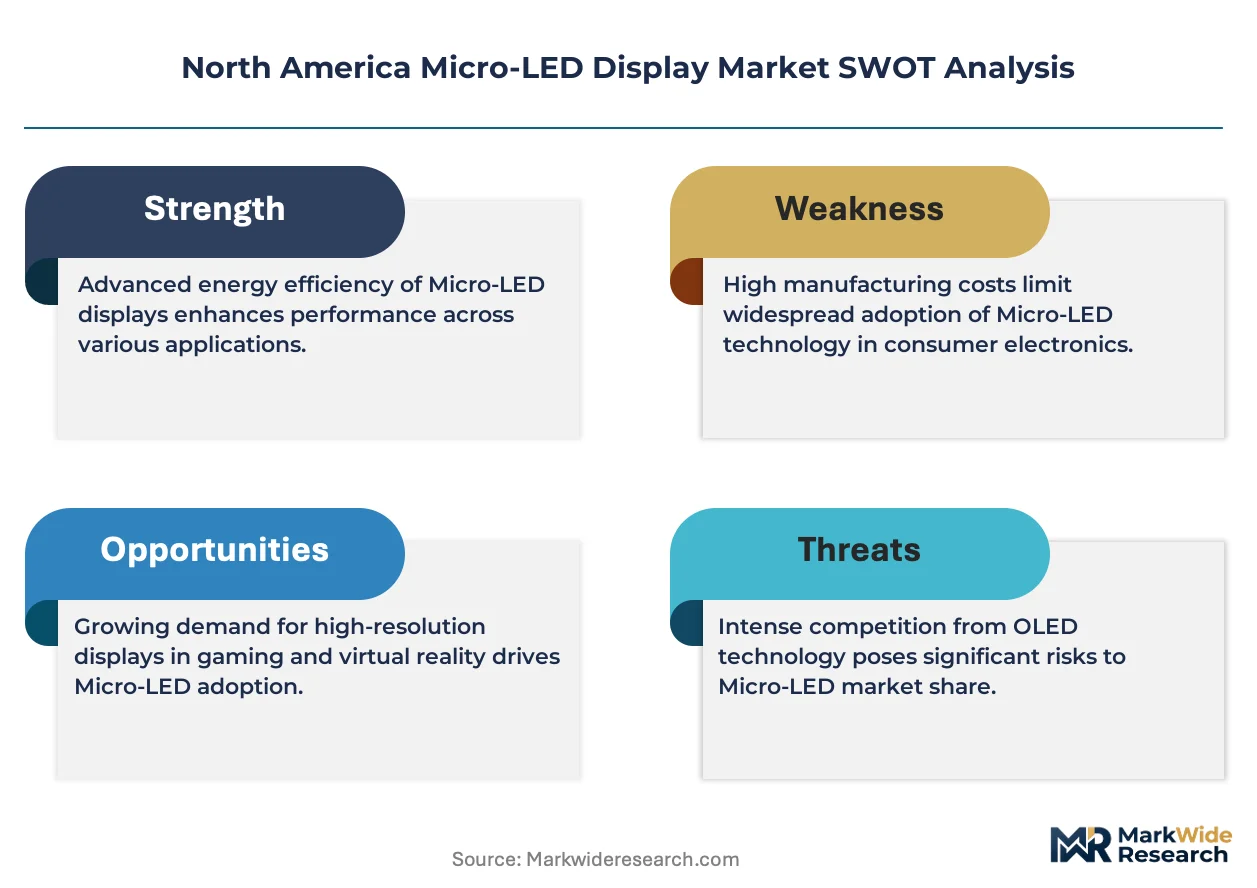
This market functions as a defensive-moat story anchored in regulatory entrenchment. FCC electromagnetic compliance pre-certification requirements and EPA efficiency mandates create switching costs that favor incumbents with captive laboratory infrastructure.
For Market Incumbents: Compound electromagnetic compliance capabilities through captive laboratory investments that accelerate Detroit OEM pre-certification cycles. Deepen upstream control over chiplet architecture roadmaps to defend against heterogeneous integration specialists. Capacity addition in Texas and Arizona manufacturing corridors captures state-level tax abatements while shortening logistics lead times for residential demand clusters. For New Entrants and Emerging Players: Lead with transparent display retail integration in California's technology corridor, where see-through storefront configurations remain underpenetrated against architectural advertising demand. Target flexible substrate wearables for health monitoring form factors, exploiting nascent contract availability before vertical foundries consolidate bendable panel supply. Position as FCC pre-certification service providers to tier-two automotive suppliers lacking in-house electromagnetic compatibility infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward substrate bonding specialists with large-format television panel capabilities and established relationships with California technology platforms. Long-term viability over the projection horizon hinges on mass transfer equipment scale and state-level incentive capture. Watch for inflection signals in laser-assisted die placement adoption rates among Taiwan and South Korean tier-one foundries, as throughput advantages compress capital recovery timelines for North American module houses.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Compliance Laboratory Investment | FCC Part 15 Class B pre-certification accelerates Detroit OEM integration timelines. |
| Mass Transfer Equipment Scale-Up | Laser-assisted die placement throughput of 10,000+ dies-per-second compresses capital recovery. |
| Backplane Fabrication Geographic Expansion | Texas and Arizona manufacturing incentives attract substrate production for residential demand clusters. |
| Chiplet Architecture R&D Partnership | Heterogeneous integration roadmaps defend against OLED substitution in premium smartphone tiers. |
| Transparent Display Retail Pilot Programs | California storefront installations establish architectural advertising channel control before consolidation. |
Research Methodology
Cross-validation between primary interviews with display module procurement directors and secondary analysis of FCC equipment authorization databases anchors the qualitative findings. Stakeholder engagement spanned tier-one automotive OEM platform engineers, tier-two supplier bonding house operations leads, retail electronics distributor category managers, and EPA ENERGY STAR program administrators. Secondary sources included SEC 10-K filings from vertically integrated technology platforms, customs records for backplane substrate import flows, and equipment vendor technical specifications. Bottom-up assembly cost modeling triangulates against top-down demand segmentation across consumer electronics, automotive, and retail end-use categories.
Sensitivity analysis across mass transfer yield assumptions and substrate pricing scenarios shapes the analytical framework over the projection horizon. Segmentation dimensions span product type, end user, technology architecture, and application, with additional modeling of pixel pitch specification tiers and thermal management complexity grades. CAGRs derive from installed base replacement cycles, regulatory mandate compliance deadlines, and OEM procurement framework transitions. Industry-specific forecast inputs incorporate EPA standby power specification tightening trajectories and FCC electromagnetic interference threshold evolution for connected vehicle deployments.
The analysis sits within stated boundaries; outcomes outside sustained InGaN micro-diode luminance performance improvements or relaxation of FCC pre-certification timelines would require recalibration. Forecasts reflect documented assumptions regarding substrate supply concentration and equipment vendor fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Control Unit Market
LED
Philippines LED Market
LED
US LED Downlight Market
LED
Europe Indoor LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Germany Outdoor LED Lighting Market
LED
India Indoor LED Lighting Market
LED
Outdoor LED Display Market
LED
United States Micro LED Market
LED
France LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
Single-Digit 7 Segment LED Displays Market
LED
LED Flip Chip Market
LED
UK Indoor LED Lighting Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
LED Modular Display Market