
 Asia Pacific Safety Switches Market | 2026-2036
Asia Pacific Safety Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Safety Switches Market Outlook
Market Context with Strategic Players
ISO 13849-1 certification for safety-related control systems is collapsing the field of qualified suppliers across the Asia Pacific basin. Schneider Electric leverages its captive distribution network to dominate specification-grade projects in Southeast Asian petrochemical complexes. Siemens AG anchors high-volume supply relationships with Japanese automotive OEMs through localized electromechanical production. Rockwell Automation Inc competes on integrated safety-PLC architectures that bundle safety switches with Allen-Bradley control platforms.
Technical Definition and Structural Segments
Asia Pacific safety switches are electromechanical or electronic control devices engineered to IEC 60947-5-1 specifications, designed to interrupt power or signal hazardous conditions when guards open, emergency stops activate, or personnel enter restricted zones. Non-contact switches utilizing inductive or magnetic sensing principles are displacing mechanical interlocks in food and beverage washdown environments where IP69K sealing eliminates contamination risks. Emergency stop switches retain the largest installed base across machine tools and material handling systems, though RFID-enabled technology represents the fastest-expanding margin pool as pharmaceutical manufacturers track operator authentication and guard-state compliance in real time.
Regulatory Framework and Outlook
Australia's WHS regulators, China's SAMR under GB standards, and India's BIS certification regime collectively mandate functional safety compliance for industrial machinery, forcing importers to maintain local testing partnerships or forfeit project specifications. Japan's METI circulars on collaborative robot safety are accelerating demand for smart technology switches with dual-channel redundancy and diagnostic feedback loops. Stakeholders must monitor divergence between harmonized IEC frameworks and country-specific implementation timelines when allocating certification budgets across multi-country manufacturing footprints.
Market Dynamics
ISO 13849-1 functional safety certification is collapsing the supplier base across Asia Pacific, forcing distributors to consolidate specification-grade relationships while Japanese automotive OEMs demand localized electromechanical production with dual-channel redundancy.
Growth Catalysts
- GB standards enforcement:China's SAMR mandates functional safety compliance for industrial machinery, compelling domestic manufacturers to upgrade guard-interlock systems or forfeit state procurement contracts.
- Pharmaceutical cleanroom automation:RFID-enabled safety switches with real-time operator authentication are penetrating sterile manufacturing environments in Singapore and South Korea under GMP-aligned facility upgrades.
- Pune-Chennai automotive belt:India's concentrated OEM assembly operations are driving bulk procurement of emergency-stop switches with IP69K sealing for paint-shop and weld-cell installations.
Market Restraints
- Neodymium magnet supply volatility:Non-contact magnetic switches depend on rare-earth inputs concentrated in Chinese processing facilities, exposing cost structures to export quota fluctuations.
- IEC-GB divergence friction:China's implementation timeline for harmonized safety standards lags IEC 60947-5-1 revisions by 18-24 months, forcing dual-certification expenditure for pan-Asian suppliers.
- Mechanical interlock substitution ceiling:Legacy electromechanical switches retain installed-base dominance in cost-sensitive Indian metalworking shops resistant to capacitive-sensing upgrades.
Strategic Opportunities
- Vietnam electronics manufacturing:Underpenetrated safety-switch specification in Ho Chi Minh City industrial zones offers first-mover positioning as Korean and Japanese contract manufacturers expand capacity.
- METI collaborative robot circulars:Japan's safety mandates for cobot workcells create demand for smart switches with force-limited feedback loops and SIL3-rated diagnostic outputs.
- Direct-to-OEM digital channels:Configurator platforms bypassing traditional electrical distributors are capturing specification authority in Australian mining-equipment procurement.
Industry Challenges
- Functional safety engineering scarcity:Qualified TÜV-certified designers capable of ISO 13849-1 validation are concentrated in Tokyo and Shanghai, creating recruitment bottlenecks for Southeast Asian system integrators.
- Legacy Allen-Bradley integration complexity:Brownfield automotive plants in Thailand face protocol-mismatch costs when retrofitting safety switches into DeviceNet-architected control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Safety Switches Market |
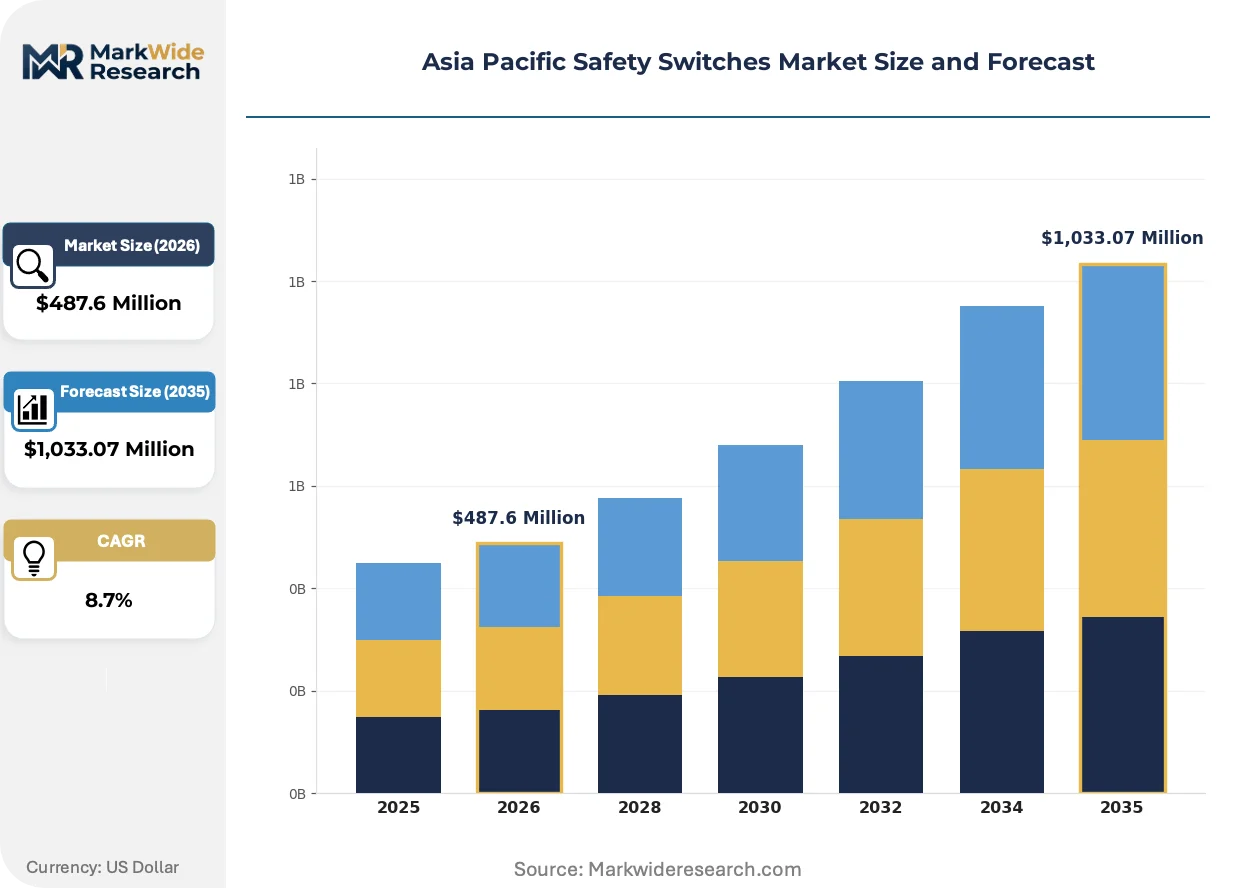
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Contact Switches, Emergency Stop Switches, Key Operated Switches, Safety Interlock Switches Application: Industrial Automation, Packaging, Machine Tools, Material Handling End User: Manufacturing, Oil & Gas, Food & Beverage, Pharmaceuticals Technology: Electromechanical, Electronic, Smart Technology, RFID-enabled |
| Companies Covered | Schneider Electric, Rockwell Automation Inc, Banner Engineering Corp, Eaton Corporation, SICK AG, Euchner GmbH, Siemens AG, Omron Electronics LLC, Honeywell International Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Safety Switches Market Strategic Shifts
Capacitive and magnetic sensing architectures are decomposing mechanical interlock dominance across washdown-intensive industries, while regulatory divergence between harmonized IEC frameworks and country-specific implementation timelines is reshaping certification investment patterns.
RFID-enabled guard interlocks are decomposing the traditional binary open/closed safety circuit. Pharmaceutical manufacturers in Singapore and South Korea are adopting these systems at accelerated pace to satisfy GMP documentation requirements for operator traceability. The technology is decomposing aftermarket service revenue models by shifting value capture toward subscription-based compliance-monitoring platforms.
Australia's WHS regulators are tightening enforceable undertakings for machinery guarding failures, compelling mining and materials-handling operators to replace legacy pull-cord switches with SIL-rated emergency-stop devices. The industrial consequence is accelerated replacement cycles in Western Australian iron-ore processing facilities. Underground coal operations in Queensland are responding by specifying dual-channel redundant architectures with forced-guidance relay monitoring.
Specification authority is migrating from maintenance departments to centralized EHS functions with standardized vendor-approval lists. Australian and Japanese electrical distributors are losing influence to direct OEM engagement as procurement teams consolidate safety-component spend under framework agreements. This concentration is most visible in Japanese automotive tier-one supply chains, where Toyoda Gosei and Denso affiliates enforce approved-component databases across Southeast Asian subsidiaries.
Asia Pacific Safety Switches Market Segmentation
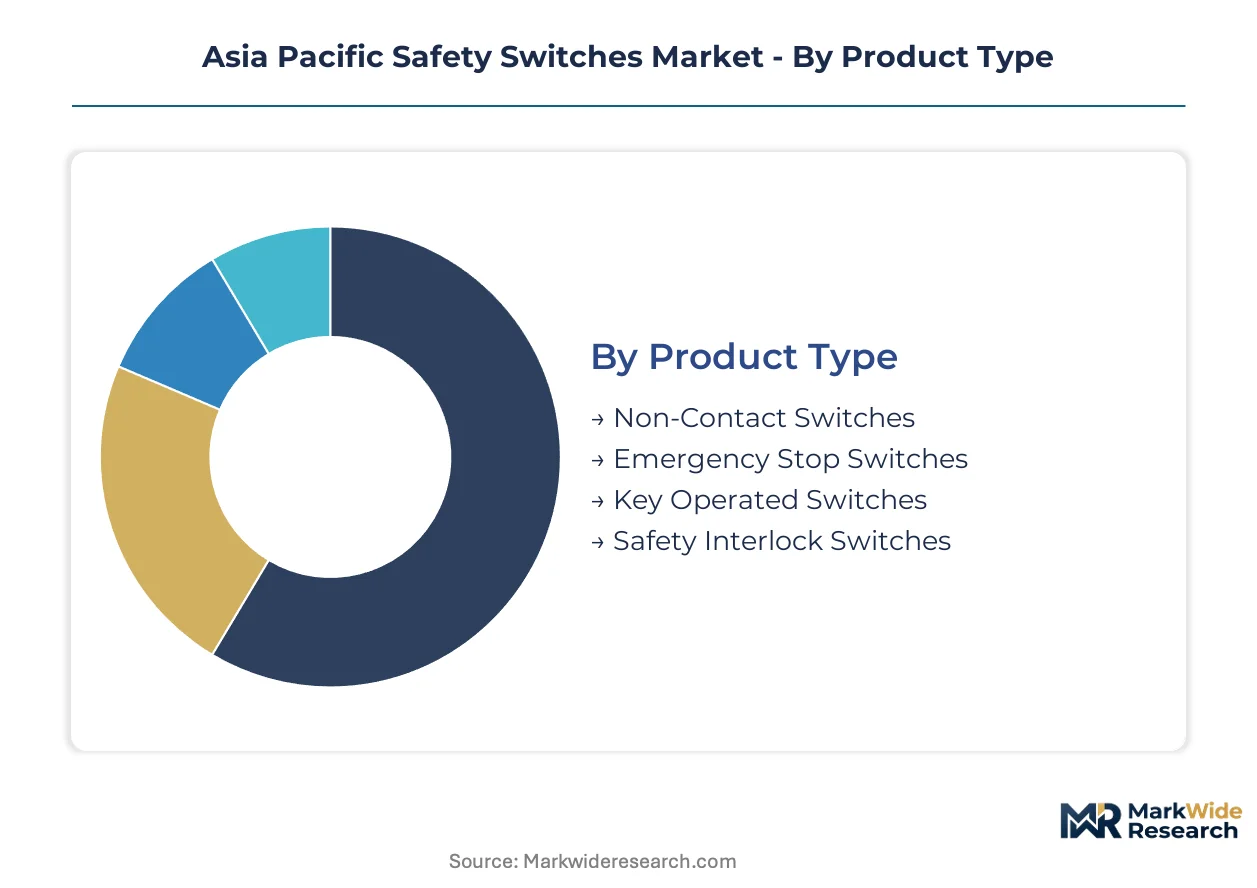
Safety switch procurement patterns across Asia Pacific diverge sharply between export-oriented manufacturing hubs and domestic industrial zones. Understanding these segment boundaries clarifies where specification authority concentrates and which certification regimes govern purchasing decisions.
Product Type:
Domestic Chinese and Indian metalworking shops favor mechanical interlocks for cost containment, while export-facing facilities in Vietnam and Thailand specify non-contact architectures to satisfy OEM customer mandates.
- Non-Contact Switches:Inductive and magnetic sensing architectures eliminate mechanical wear in washdown environments. Demand concentrates in South Korean food processing plants and Australian mining operations where IP69K sealing withstands high-pressure cleaning protocols.
- Emergency Stop Switches:Mushroom-head and pull-cord variants constitute the largest installed base across Asia Pacific machine tools. Pune and Chennai automotive assembly lines specify these devices in bulk for weld-cell and paint-shop installations under BIS certification requirements.
- Key Operated Switches:Personnel authentication applications in Japanese collaborative robot workcells.
- Safety Interlock Switches:Guard-door applications in Chinese semiconductor fabrication facilities.
Emergency stop switches command the established base. The steepest expansion runs through non-contact switches.
Application:
Cost tiers separate specification-grade projects from maintenance-driven replacements, with new-build automation commanding premium electromechanical architectures.
- Industrial Automation:PLC-integrated safety circuits dominate greenfield automotive and electronics manufacturing. Japanese automotive OEMs in Thailand and Indonesia require dual-channel redundancy with forced-guidance relay monitoring for their tier-one supplier networks.
- Machine Tools:Lathe and milling center retrofits in India's Ludhiana and Rajkot clusters sustain mechanical interlock demand despite capacitive-sensing availability. Metalworking shops prioritize upfront cost over diagnostic feedback capabilities.
- Packaging:High-speed carton and bottling lines in Vietnam's emerging manufacturing zones.
- Material Handling:Conveyor and crane applications in Australian iron-ore processing facilities.
Industrial automation absorbs the premium tier. Machine tools anchor the replacement cycle volume.
End User:
Customer type determines whether procurement flows through centralized EHS functions or decentralized maintenance budgets, reshaping distributor influence.
- Manufacturing:Discrete production facilities across the region's automotive and electronics belts specify safety switches through approved-vendor databases. Toyoda Gosei and Denso affiliates enforce component standardization across Southeast Asian subsidiaries, consolidating spend under framework agreements.
- Pharmaceuticals:Sterile manufacturing in Singapore and South Korea drives RFID-enabled guard interlocks with operator traceability. GMP documentation requirements mandate real-time authentication systems that decompose traditional binary safety circuits.
- Oil & Gas:Petrochemical complexes in Malaysia and Indonesia specifying IEC 61508-compliant architectures.
- Food & Beverage:Australian dairy and meat processing plants upgrading to IP69K-sealed devices.
Manufacturing captures the broadest specification base. Pharmaceuticals generate the fastest technology migration.
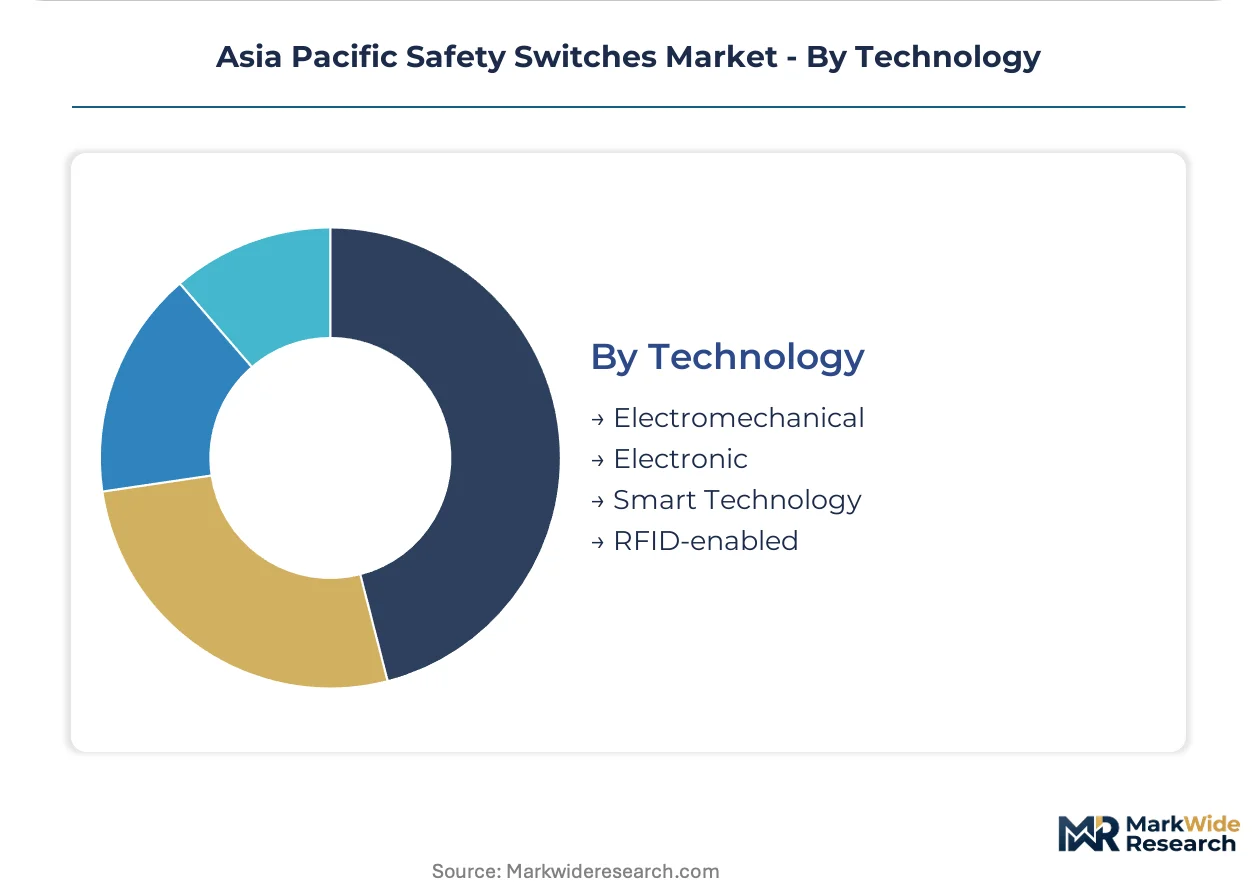
Technology:
Supply concentration for rare-earth magnet inputs shapes cost structures across non-contact architectures, with Chinese processing quotas transmitting volatility downstream.
- Smart Technology:SIL3-rated diagnostic outputs with force-limited feedback loops address Japan's METI collaborative robot circulars. These devices integrate with safety PLCs to enable cobot workcell deployments in Osaka and Nagoya manufacturing zones.
- RFID-enabled:Guard-state compliance tracking and operator authentication penetrate pharmaceutical cleanrooms. Real-time data capture shifts value toward subscription-based compliance-monitoring platforms, decomposing aftermarket service revenue models.
- Electromechanical:Legacy mechanical interlocks retaining dominance in cost-sensitive Indian metalworking.
- Electronic:Solid-state architectures displacing mechanical contacts in high-cycle applications.
Electromechanical technology holds the installed base. Smart technology climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's WHS regulators, China's SAMR, and India's BIS certification regime are tightening functional safety mandates across industrial machinery, forcing importers to maintain local testing partnerships or forfeit project specifications.
China
Domestic manufacturers face SAMR enforcement of GB standards that lag IEC 60947-5-1 revisions by 18-24 months, compelling dual-certification expenditure. Semiconductor fabrication facilities in Shanghai and Beijing specify safety interlock switches for cleanroom guard-door applications. Yangtze River Delta electronics exporters upgrade to non-contact architectures to satisfy OEM customer mandates.
Japan
METI circulars on collaborative robot safety accelerate demand for smart technology switches with dual-channel redundancy and SIL3-rated diagnostic outputs. Osaka and Nagoya manufacturing zones deploy force-limited feedback loops for cobot workcell integrations. Automotive tier-one supply chains enforce approved-component databases across Southeast Asian subsidiaries.
India
BIS certification requirements govern bulk procurement of emergency-stop switches for Pune and Chennai automotive assembly lines. Paint-shop and weld-cell installations specify IP69K sealing for harsh environments. Ludhiana and Rajkot metalworking clusters sustain mechanical interlock demand despite capacitive-sensing availability.
Australia
WHS regulators impose enforceable undertakings for machinery guarding failures, compelling Western Australian iron-ore processing facilities to replace legacy pull-cord switches. Queensland underground coal operations specify dual-channel redundant architectures with forced-guidance relay monitoring. Mining-equipment procurement shifts toward direct OEM engagement via configurator platforms.
South Korea
MFDS-aligned GMP documentation requirements drive RFID-enabled guard interlocks with real-time operator authentication in pharmaceutical cleanrooms. Food processing plants specify inductive sensing architectures with IP69K sealing for high-pressure cleaning protocols. Seoul Capital Area electronics manufacturers adopt non-contact switches for washdown-intensive environments.
Asia Pacific Safety Switches Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with captive distribution networks and specialized safety-component houses with ISO 13849-1 certification depth. Electromechanical specialists and integrated safety-PLC architects represent the dominant strategic archetypes. Competitive moves concentrate on specification-grade relationship consolidation and localized production partnerships with Japanese automotive OEMs.
Among diversified industrial conglomerates, Schneider Electric, Siemens AG, and Rockwell Automation Inc occupy positions anchored by distribution network scale and platform integration capabilities. Schneider Electric exemplifies the specification-grade project archetype through petrochemical complex dominance. Siemens AG represents localized electromechanical production relationships with automotive OEMs. Rockwell Automation Inc sits within the integrated safety-PLC tier, bundling safety switches with control platform architectures.
| Leading Market Players |
|---|
| Schneider Electric |
| Rockwell Automation Inc |
| Banner Engineering Corp |
| Eaton Corporation |
| SICK AG |
| Euchner GmbH |
| Siemens AG |
| Omron Electronics LLC |
| Honeywell International Inc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates at ISO 13849-1 certified production facilities in Japan and Germany set price floors across Asia Pacific, concentrating supply among electromechanical specialists who capture specification-grade premiums while Chinese non-certified producers compete on unit economics for maintenance-driven replacements.
Pricing Analysis
Certification level creates the primary spread between specification-grade and commodity tiers. Three-tier pricing structure across SIL3-rated diagnostic, dual-channel redundant, and basic electromechanical levels separates Japanese automotive OEM contracts from Indian metalworking shop procurement. Cost compression in standard-grade mechanical interlocks is intensifying because Vietnamese electronics manufacturers are consolidating volume under framework agreements. Price sensitivity peaks among Ludhiana and Rajkot metalworking clusters prioritizing upfront capital expenditure over lifecycle diagnostics.
Supply Chain Analysis
Rare-earth processing concentration in Chinese Jiangxi and Inner Mongolia facilities underwrites cost volatility for magnetic sensing architectures. Neodymium magnet feedstock and forced-guidance relay components draw from domestic Chinese and Japanese electromechanical production bases. Single-source vulnerability concentrates in GB standards certification testing partnerships required for SAMR compliance. Distribution runs through captive networks at Schneider Electric and Siemens AG, supplemented by independent electrical distributors losing specification authority to direct OEM engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive and RFID-enabled architectures are accelerating substitution pressure against legacy mechanical interlocks, forcing incumbents to defend specification relationships through certification depth and integrated safety-PLC bundling.
For Market Incumbents: Compound ISO 13849-1 certification depth with localized electromechanical production partnerships in Thailand and Indonesia to defend against capacitive-sensing entrants targeting Japanese automotive tier-one networks. Backward integration into rare-earth magnet sourcing mitigates neodymium cost volatility threatening non-contact switch margins. For New Entrants and Emerging Players: Lead with Vietnam electronics manufacturing zones in Ho Chi Minh City where safety-switch specification remains underpenetrated as Korean contract manufacturers expand capacity. Configurator platforms bypassing traditional electrical distributors capture specification authority in Australian mining-equipment procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical specialists with TÜV-certified engineering talent concentrated in Tokyo and Shanghai. Acquisition targets should demonstrate captive relationships with pharmaceutical cleanroom automation projects in Singapore and South Korea. The signal to watch is divergence between IEC harmonization timelines and country-specific GB standards implementation creating dual-certification expenditure burdens.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13849-1 Certification Investment | Collapses qualified supplier field and secures specification-grade project access in petrochemical complexes. |
| Localized Electromechanical Production | Satisfies Japanese automotive OEM mandates for dual-channel redundancy with regional manufacturing footprints. |
| RFID-Enabled Guard Interlock Development | Captures pharmaceutical cleanroom demand under GMP-aligned operator traceability requirements. |
| Direct-to-OEM Digital Channel Buildout | Bypasses distributor margin capture in Australian mining-equipment procurement consolidation. |
| Rare-Earth Magnet Supply Partnership | Stabilizes non-contact switch cost structures against Chinese export quota volatility. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across plant engineers at Pune and Chennai automotive facilities, EHS directors at Australian iron-ore processing operations, procurement leads at Japanese tier-one suppliers, and aftermarket service heads at Southeast Asian distributors. Secondary validation drew from IEC 60947-5-1 specification documents, SAMR GB standards filings, BIS certification registries, and customs trade data for electromechanical component flows. Bottom-up procurement volume estimates triangulated against top-down industrial automation capex disclosures.
Across the analysis window, forecasts segmented by product type, application intensity, end-user procurement centralization, and technology architecture maturity. CAGRs derived from installed-base replacement cycles, greenfield automation project pipelines, and regulatory compliance deadline clustering. Industry-specific inputs included METI collaborative robot circular implementation timelines and MFDS GMP documentation requirement phase-ins.
Underlying assumptions cover stable rare-earth magnet supply quotas and IEC-GB standards convergence trajectories, with deviation risk concentrated in neodymium export restrictions and country-specific certification timeline delays. Practitioners should keep alternative scenarios live as China's SAMR enforcement intensity and Japan's cobot safety mandate expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Brazil Switchgear Market
Switches
Disconnect Switch Market
Switches
Reed Switches Sensors Market
Switches
Temperature and Pressure Switches Market
Switches
India Switchgear Market
Switches
5G Electromechanical RF Switch Market
Switches
Tactile Switch Keyboard Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
Global Float Level Switches Market
Switches
Fusible Switches Market
Switches
Global Light Control Switches Market
Switches
Electric Switch Market
Switches
Rotary Limit Switches Market
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
North America Switchgear Market