
 Semiconductor Rectifier Market | 2026-2036
Semiconductor Rectifier Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Rectifier Market Intelligence
Silicon carbide is realigning cost-performance tradeoffs in high-voltage rectification. Infineon Technologies AG anchors European automotive qualification pipelines through in-house SiC crystal growth. Mitsubishi Electric Corporation dominates traction-grade rectifier modules for rail and EV inverter platforms. Vishay Intertechnology specializes in discrete rectifier packaging for industrial power supply density requirements.
A semiconductor rectifier is a two-terminal electronic device that permits unidirectional current flow through a p-n junction, with forward voltage drops ranging from 0.3V in Schottky configurations to 1.1V in ultrafast silicon recovery types, serving to convert alternating current into direct current for downstream electronic systems. GaN Technology segments command premium positioning in 650V-class server power supplies where switching losses determine thermal budgets. Schottky Rectifiers sustain mature volume economics in consumer adapter applications despite silicon carbide encroachment at higher voltages. Fast Recovery Rectifiers retain structural importance in industrial motor drive commutation circuits where reverse recovery time parameters dictate electromagnetic compatibility compliance.
The US EPA and FCC constrain rectifier electromagnetic interference signatures in grid-tied power electronics, while the EU RoHS and REACH frameworks restrict hexavalent chromium plating in leadframe finishes. China's GB standards and MIIT efficiency mandates accelerate adoption of wide-bandgap rectifier topologies in domestic data center builds. Stakeholders must calibrate material roadmaps against divergent regional efficiency certification timelines.
Market Dynamics
Silicon carbide substrate economics are compressing legacy silicon diode margins while concentrating high-voltage rectifier procurement in East Asian foundry corridors with captive SiC crystal growth capabilities.
Growth Catalysts
- MIIT efficiency mandates:China's Ministry of Industry and Information Technology minimum efficiency standards for data center power supplies accelerate wide-bandgap rectifier adoption in domestic server farms.
- EV powertrain electrification:Automotive OEM supply chains demand high-efficiency rectification for onboard chargers and DC-DC converters across 800V architectures.
- Silicon carbide substrate migration:Foundries in Japan and South Korea scale 6-inch SiC wafer production, lowering unit costs for 1200V-class Schottky rectifiers.
Market Restraints
- Silicon carbide wafer supply concentration:Over 70% of substrate production concentrates in two Japanese suppliers, creating input bottlenecks for European and North American module makers.
- REACH substance restrictions:ECHA authorization requirements for leadframe plating chemistries extend qualification timelines for new rectifier packages entering EU markets.
- Technical performance gaps below 100V:Silicon retains cost advantages in low-voltage consumer adapters where GaN HEMTs and SiC diodes cannot justify premium positioning.
Strategic Opportunities
- India's PLI scheme for power electronics:Production-linked incentives for semiconductor manufacturing attract rectifier packaging investments to Gujarat and Karnataka industrial corridors.
- Grid-scale energy storage integration:Battery inverter manufacturers require high-current rectification modules for bidirectional power conversion in utility-scale installations.
- GaN-on-silicon convergence with SiC:Hybrid module designs combining 650V GaN switches with SiC Schottky freewheeling diodes optimize switching loss tradeoffs in server power supplies.
Industry Challenges
- AEC-Q101 automotive qualification timelines:18-24 month validation cycles for traction-grade rectifiers delay revenue recognition from EV platform wins.
- Packaging thermal management expertise:Copper clip and ribbon bonding techniques for high-current density modules require specialized equipment and process engineering talent concentrated in Southeast Asian OSATs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Rectifier Market |
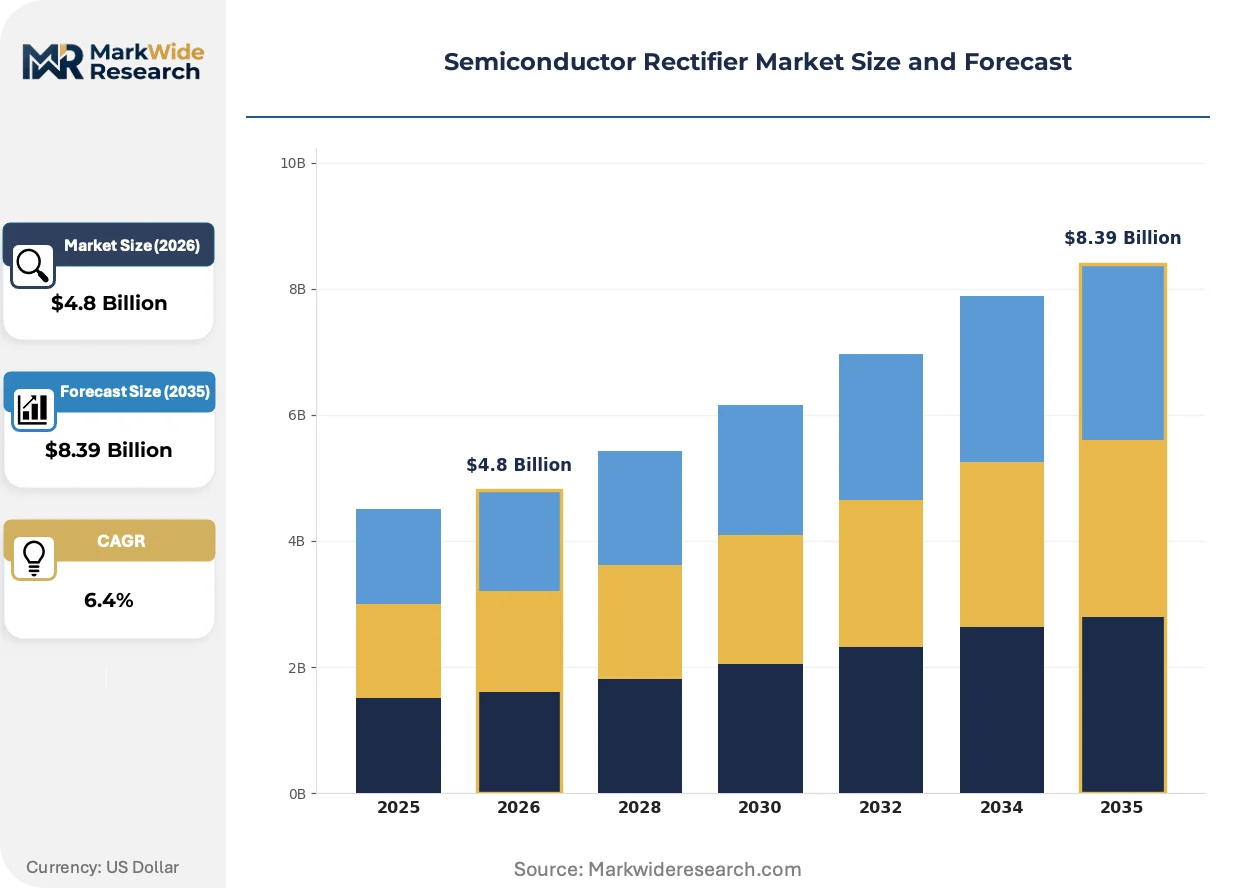
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Rectifiers, Schottky Rectifiers, Zener Diodes, Fast Recovery Rectifiers Technology: Diode Technology, Transistor Technology, MOSFET Technology, GaN Technology End User: Consumer Electronics, Automotive, Industrial Automation, Power Supply Systems Application: Power Conversion, Voltage Regulation, Signal Processing, Renewable Energy Solutions |
| Companies Covered | onsemi, Mitsubishi Electric Corporation, Infineon Technologies AG, ROHM Semiconductor, Renesas Electronics Corporation, STMicroelectronics N.V., Vishay Intertechnology, Microchip Technology, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Rectifier Market Strategic Shifts & Innovations
Rectifier technology trajectories center on wide-bandgap material substitution, regulatory efficiency floor elevation, and procurement consolidation around vertically integrated suppliers with captive substrate capabilities.
Silicon carbide Schottky barrier diodes now dominate 650V to 1700V applications where switching losses determine thermal budgets. Data center power supply manufacturers in Taiwan and South Korea specify SiC rectifiers for 80 Plus Titanium efficiency targets. This technology is unifying previously separate silicon ultrafast and Schottky product lines into single wide-bandgap platforms.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases indirectly pressure power electronics efficiency standards. Industrial motor drive OEMs must demonstrate reduced switching losses to avoid oversized thermal management systems. German and Italian manufacturers accelerate SiC module qualification to maintain CE marking compliance without design compromises.
Consolidated procurement through tier-one automotive suppliers now dictates rectifier specification roadmaps. Direct contracting with foundries possessing in-house SiC crystal growth replaces traditional distributor relationships. Japanese and Korean EV battery manufacturers drive this pattern most visibly, locking multi-year supply agreements with substrate-integrated module houses.
Semiconductor Rectifier Market Segmentation
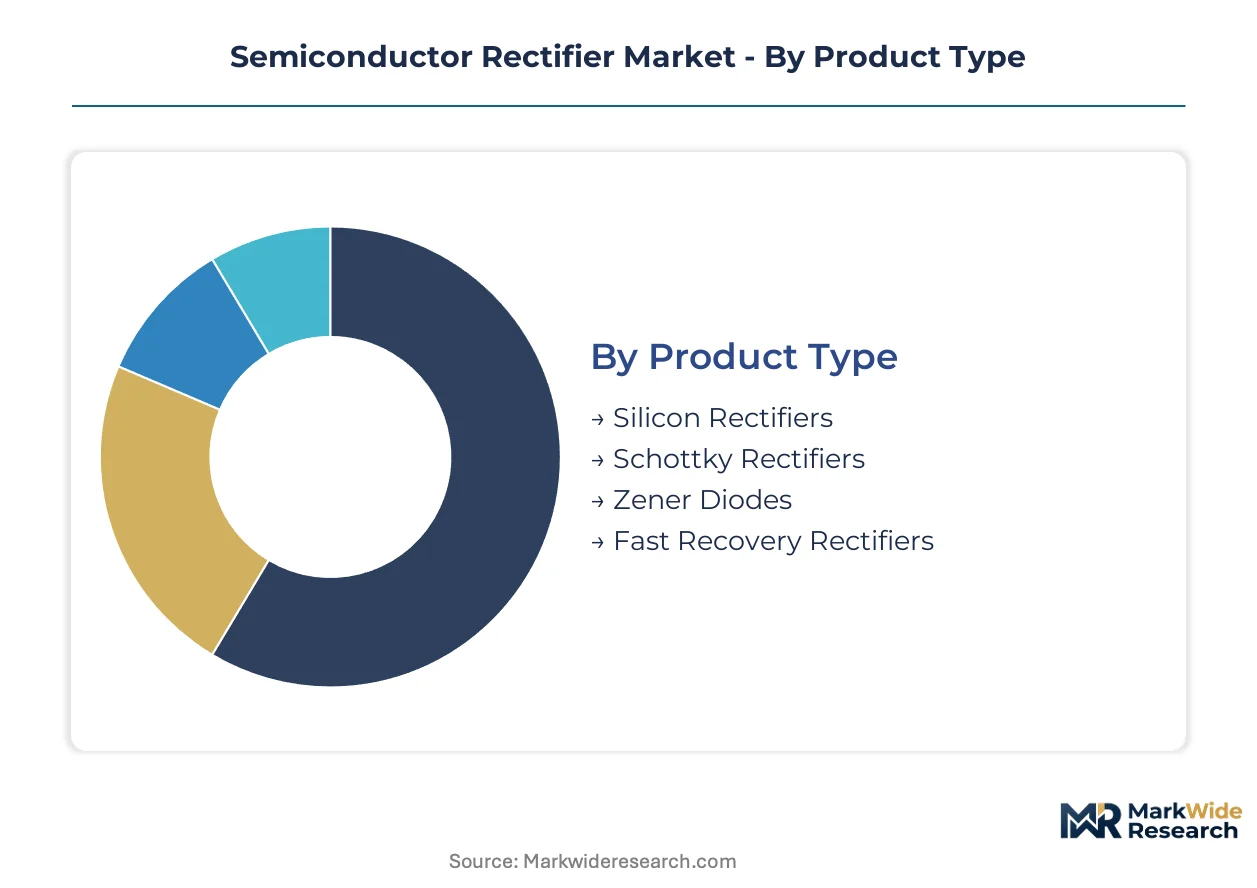
Rectifier segmentation reveals divergent margin structures across voltage classes and switching frequencies. Material choices between silicon, SiC, and GaN create distinct procurement channels that resist standardization even as automotive and data center customers consolidate supplier bases.
Product Type:
Customization intensity varies sharply across voltage ratings and recovery speed requirements, with standard silicon diodes commoditized below 100V while SiC Schottky variants command engineering engagement at 1200V+.
- Schottky Rectifiers:Metal-semiconductor junctions deliver forward voltage drops of 0.3V to 0.5V, eliminating reverse recovery losses. Data center power supply manufacturers in Taiwan specify these for 80 Plus Titanium efficiency targets where thermal budgets constrain switching losses.
- Fast Recovery Rectifiers:Engineered p-n junctions with controlled minority carrier lifetime reduce reverse recovery time to under 50 nanoseconds. Industrial motor drive OEMs in Germany rely on these for electromagnetic compatibility compliance in variable frequency inverter commutation circuits.
- Silicon Rectifiers:Standard diffused junction devices dominate consumer adapter economics where cost-per-ampere trumps efficiency metrics.
- Zener Diodes:Avalanche breakdown characteristics enable precise voltage clamping and reference applications across automotive body electronics modules.
Leading the category by volume: Silicon Rectifiers. Growing fastest: Schottky Rectifiers.
Technology:
Cost tier separation runs from mature silicon diffusion processes to capital-intensive wide-bandgap epitaxy requiring captive substrate supply.
- GaN Technology:Heterostructure devices on silicon substrates enable 650V-class operation with switching speeds exceeding silicon limits by an order of magnitude. Server power supply designers combine GaN switches with SiC freewheeling diodes to optimize loss tradeoffs.
- MOSFET Technology:Vertical trench structures with integrated body diodes serve synchronous rectification in high-current DC-DC converters where conduction losses dominate.
- Diode Technology:Discrete rectifier p-n junctions persist in cost-sensitive applications where unipolar conduction suffices.
- Transistor Technology:Bipolar junction configurations retain niche relevance in ultrahigh-current welding equipment and plating rectifiers.
Highest margin capture: GaN Technology. Steepest volume expansion: MOSFET Technology.
End User:
Application maturity separates established industrial automation procurement from emerging EV powertrain qualification cycles with extended validation timelines.
- Automotive:800V traction architectures demand AEC-Q101 qualified rectifiers for onboard chargers and DC-DC stages. Japanese and Korean battery manufacturers lock multi-year supply agreements with substrate-integrated module houses.
- Power Supply Systems:Server farm efficiency mandates from China's MIIT accelerate wide-bandgap rectifier specification in domestic hyperscaler builds.
- Consumer Electronics:Smartphone and laptop adapter manufacturers prioritize silicon Schottky economics at sub-100V operating points.
- Industrial Automation:Motor drive and welding equipment OEMs specify fast recovery types for electromagnetic compatibility in harsh electrical environments.
Fastest qualification velocity: Power Supply Systems. Longest validation cycles: Automotive.
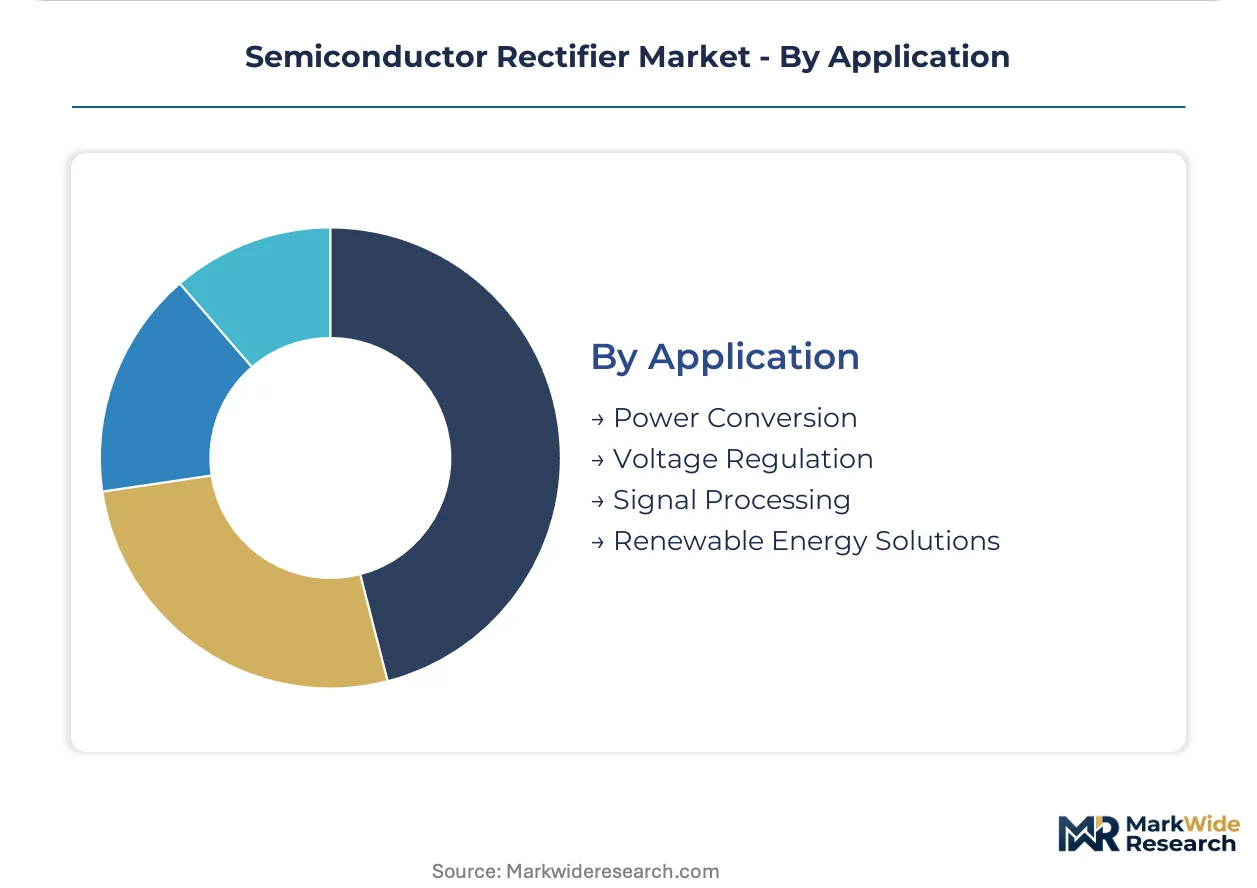
Application:
Customer type fragmentation spans OEM direct procurement for renewable energy inverters versus distributor-mediated fulfillment for maintenance-driven replacement demand.
- Power Conversion:AC-DC and DC-DC stage rectification spans adapter, server, and EV charger topologies with divergent efficiency floor requirements across regulatory jurisdictions.
- Renewable Energy Solutions:Utility-scale solar inverters and battery energy storage systems require high-current modules for bidirectional power flow in grid-tied installations.
- Voltage Regulation:Zener and shunt regulator applications serve precision reference and protection functions in automotive and industrial control systems.
- Signal Processing:Small-signal rectification in RF and detection circuits demands low capacitance Schottky variants for frequency response integrity.
Revenue concentration: Power Conversion. Fastest policy tailwind: Renewable Energy Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian special economic zones concentrating SiC substrate fabrication anchor global rectifier procurement. China's MIIT efficiency mandates, Japan's METI semiconductor subsidies, and South Korea's K-Semicon Belt incentives collectively reshape manufacturing geography. Industrial corridors in Taiwan, Japan, and South Korea now capture high-voltage module assembly.
China
MIIT data center efficiency mandates and dual carbon goals accelerate wide-bandgap rectifier adoption in domestic server farms. GB standards for power supply efficiency create regulatory floors that silicon devices cannot satisfy. Yangtze River Delta clusters around Shanghai and Suzhou concentrate foundry capacity for 1200V-class SiC Schottky production.
Japan
Automotive OEM supply chains for 800V EV architectures source traction-grade rectifiers through vertically integrated module houses. METI's semiconductor reinforcement subsidies underwrite SiC crystal growth capacity expansion in Kyushu. Kumamoto and Kagoshima prefectures host concentrated substrate production that feeds regional packaging facilities.
South Korea
Battery manufacturers lock multi-year supply agreements for onboard charger rectifiers across Hyundai-Kia and Samsung SDI platforms. K-Semicon Belt tax incentives attract power module packaging investments to Gyeonggi Province. Pangyo and Hwaseong industrial complexes anchor domestic SiC wafer processing and module qualification pipelines.
Germany
Industrial motor drive OEMs accelerate SiC module qualification to maintain CE marking compliance under EU F-Gas Regulation phase-down schedules. ECHA REACH authorization requirements for leadframe plating chemistries extend qualification timelines for EU market entry. Bavaria and Baden-Württemberg host concentrated automotive power electronics R&D corridors.
United States
EPA and FCC electromagnetic interference constraints shape rectifier specification for grid-tied solar inverters and energy storage systems. IRA production tax credits incentivize domestic module assembly investments. Arizona and Texas industrial corridors attract packaging facilities serving North American renewable energy OEMs.
Semiconductor Rectifier Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around substrate-integrated module houses with captive SiC crystal growth capabilities. Three archetypes dominate: European automotive qualification specialists, East Asian vertically integrated foundries, and North American discrete packaging houses. Competitive moves center on multi-year supply agreement lock-ins with tier-one automotive suppliers and foundry capacity expansion for 6-inch SiC wafer processing.
Among Japanese substrate-integrated suppliers, Mitsubishi Electric Corporation and ROHM Semiconductor exemplify the vertically integrated archetype with in-house SiC crystal growth. Infineon Technologies AG anchors European automotive qualification pipelines. These three occupy positions where substrate control and module packaging capabilities converge.
| Leading Market Players |
|---|
| onsemi |
| Mitsubishi Electric Corporation |
| Infineon Technologies AG |
| ROHM Semiconductor |
| Renesas Electronics Corporation |
| STMicroelectronics N.V. |
| Vishay Intertechnology |
| Microchip Technology |
| Texas Instruments |
| Others |
Cost & Logistics Intelligence
AEC-Q101 certification tiers bifurcate pricing power between automotive-qualified SiC modules and unqualified silicon discretes, with the former commanding engineering premiums through captive substrate supply while the latter faces commoditization through distributor-mediated spot purchasing. This tier divergence concentrates margin capture in Japanese and Korean foundries with in-house crystal growth, while European and North American packagers absorb cost pressure from substrate bottlenecks.
Pricing Analysis
Volume concentration in sub-100V silicon Schottky adapters sustains razor-thin margins, while 1200V-class SiC Schottky modules for 800V EV architectures capture value through multi-year offtake contracts. Price differentiation hinges on AEC-Q101 qualification status and wafer diameter scale, with 6-inch substrate access determining cost competitiveness. Cost compression in standard silicon diodes intensifies as Chinese foundries expand 200mm production, while automotive buyers show lowest price sensitivity due to platform-lock-in effects.
Supply Chain Analysis
End-of-life module refurbishment flows remain underdeveloped, with most traction-grade rectifiers scrapped rather than remanufactured due to thermal cycling degradation. Raw material supply concentrates in Japan and South Korea for SiC substrates, with China and Taiwan handling backend packaging and testing. The chain draws from high-purity silicon carbide powder, copper leadframes, and epoxy mold compounds, with single-source vulnerability concentrated in two Japanese substrate suppliers. Distribution runs through tier-one automotive module houses and industrial distributor networks serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substrate fabrication capacity constraints prop pricing premiums for qualified SiC rectifiers, with 6-inch wafer supply bottlenecks extending through the analysis window as automotive qualification pipelines absorb available output.
For Market Incumbents: Deploy captive SiC crystal growth capacity as the primary defensive lever against margin erosion from Chinese silicon foundry expansion. Lock multi-year supply agreements with Hyundai-Kia and Samsung SDI battery platforms before substrate-integrated competitors consolidate share. Accelerate AEC-Q101 qualification pipelines for 1700V modules to preempt emerging GaN-on-silicon substitutes in server power supplies. For New Entrants and Emerging Players: India's PLI scheme for power electronics opens a window for packaging investments in Gujarat and Karnataka corridors, bypassing East Asian substrate concentration through modular assembly specialization. Target industrial motor drive retrofit markets in Germany where REACH compliance timelines delay incumbent product refreshes. Pursue qualification-light consumer adapter segments below 100V where silicon Schottky economics resist wide-bandgap displacement. For Investors and Strategic Acquirers: Re-rating potential sits with substrate-integrated module houses given MIIT efficiency mandates accelerating Chinese data center procurement. Long-term viability centers on backward integration into SiC crystal growth or forward integration into automotive module assembly. Monitor Japanese substrate supplier capacity expansion announcements as the inflection signal for pricing pressure direction.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | 6-inch SiC wafer foundry investments in Kyushu and Gyeonggi Province anchor automotive supply security. |
| Backward Integration | In-house SiC crystal growth eliminates substrate margin capture by Japanese duopoly suppliers. |
| Long-term Supply Agreement | Multi-year offtake contracts with Korean battery manufacturers lock revenue visibility through EV platform cycles. |
| Joint Venture | Taiwanese packaging specialists partnering with Chinese substrate foundries bypass tariff exposure in module assembly. |
| Green Manufacturing Transition | REACH-compliant leadframe plating chemistries enable CE marking without ECHA authorization delays. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with SiC substrate procurement managers, automotive power electronics platform engineers, and industrial motor drive OEM technical directors. SEC 10-K disclosures, METI semiconductor subsidy reports, and MIIT efficiency standard documents provided supply-side validation. Bottom-up unit shipment estimates triangulated against top-down value projections across voltage class and end-use segments.
Shipment and revenue streams reconciled through segmented modeling across product type, technology node, end-user vertical, and application topology, with voltage rating and switching frequency serving as cross-cutting dimensions. CAGRs derived from regression against EV powertrain penetration curves, data center build-out rates, and renewable energy installation forecasts. Substrate wafer supply forecasts and automotive qualification pipeline durations informed capacity-constrained scenario analysis.
Caveats apply where Japanese substrate supplier expansion delays or Chinese foundry overcapacity could materially shift the outlook. Practitioners should monitor AEC-Q101 qualification completion rates and 6-inch wafer pricing indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Charge Controller System Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Solid State Power Controller Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Digital Inverter Market
Power Systems
Voltage Regulators Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
DC-DC Converter Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Global Flexible Batteries Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market