
 Fixed Focal Length Lenses Market | 2026-2036
Fixed Focal Length Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Focal Length Lenses Market Insights
ISO 9001 quality certification is bifurcating supplier tiers in factory automation procurement. Edmund Optics leverages vertically integrated glass grinding to sustain cost advantages in North American machine vision channels. Schneider Kreuznach anchors European cinematography demand through heritage coating expertise. ZEISS dominates semiconductor lithography subsystems with sub-nanometer surface figure control.
A fixed focal length lens contains a single, non-zooming optical group with constant angular field of view and fixed back focal distance, typically manufactured through precision aspheric grinding and multi-layer anti-reflective deposition to achieve modulation transfer function targets above 0.3 at Nyquist frequency for sensor-limited imaging. Its primary purpose spans dimensional metrology, defect detection, and spectral analysis where positional stability outweighs framing flexibility. Macro lenses command premium positioning in medical imaging due to working distance constraints and flat-field correction requirements. Infrared technology segments attract defense and thermal inspection budgets as uncooled sensor costs decline. Hybrid optical-digital architectures reshape broadcasting workflows by embedding real-time distortion correction.
FDA 21 CFR Part 820 quality system regulation shapes medical imaging lens specifications for surgical camera integrators. REACH substance restrictions in Europe constrain exotic glass dopants and coating chemistries, pushing suppliers toward fluorite alternatives. China's GB/T national standards and MIIT imaging equipment certifications gate domestic procurement for smart manufacturing infrastructure. Stakeholders must weigh certification portfolio breadth against vertical specialization depth as end-user qualification cycles lengthen.
Market Dynamics
Machine vision deployment in semiconductor fabs is concentrating demand for sub-micron distortion control, forcing lens suppliers to prioritize surface figure precision over volume scale.
Growth Catalysts
- MIIT Imaging Equipment Certification:China's mandatory factory automation supplier qualification gates domestic procurement, channeling volumes toward certified precision optics manufacturers serving smart manufacturing infrastructure.
- Uncooled Infrared Sensor Cost Decline:Defense thermal inspection and industrial predictive maintenance budgets are expanding as vanadium oxide microbolometer prices fall, opening fixed-IR lens segments previously constrained by detector economics.
- Semiconductor Lithography Subsystems:EUV and DUV scanner OEMs require fixed focal length projection lenses with sub-nanometer surface figure stability, creating captive demand pools resistant to commoditization pressures.
Market Restraints
- Exotic Glass Dopant Supply Concentration:Lanthanum and tantalum oxide feedstocks concentrate in Chinese rare earth processing, exposing non-integrated suppliers to input cost volatility and export control friction.
- REACH Substance Restrictions:ECHA constraints on lead arsenate and cadmium-containing optical glasses force European suppliers toward fluorite and calcium fluoride alternatives with inferior dispersion characteristics.
- Plastic Aspheric Mold Precision Limits:Injection-molded polymer optics cannot achieve the wavefront error tolerances required for semiconductor metrology, capping addressable market expansion in high-performance segments.
Strategic Opportunities
- Hybrid Optical-Digital Architectures:Real-time distortion correction embedded in broadcast camera systems allows simplified lens designs, creating service revenue streams through firmware-enabled performance upgrades.
- Medical Imaging Flat-Field Correction:Surgical camera integrators under FDA 21 CFR Part 820 quality system regulation seek macro lenses with extended working distances, commanding premium positioning in minimally invasive procedure equipment.
- Spectral Analysis Instrumentation:Raman and LIBS spectrometer OEMs require achromatic fixed focal length designs across UV-NIR bands, an application segment with lower competitive density than machine vision.
Industry Challenges
- Aspheric Grinding Master Craftsman Scarcity:Precision glass molding and deterministic polishing require tacit knowledge accumulated over decade-long apprenticeships, constraining capacity expansion at specialized mid-tier suppliers.
- Multi-Jurisdictional Certification Overlap:Simultaneous pursuit of ISO 9001, FDA 820, and China GB/T compliance extends qualification cycles to 18-24 months, freezing working capital in pre-revenue product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Focal Length Lenses Market |
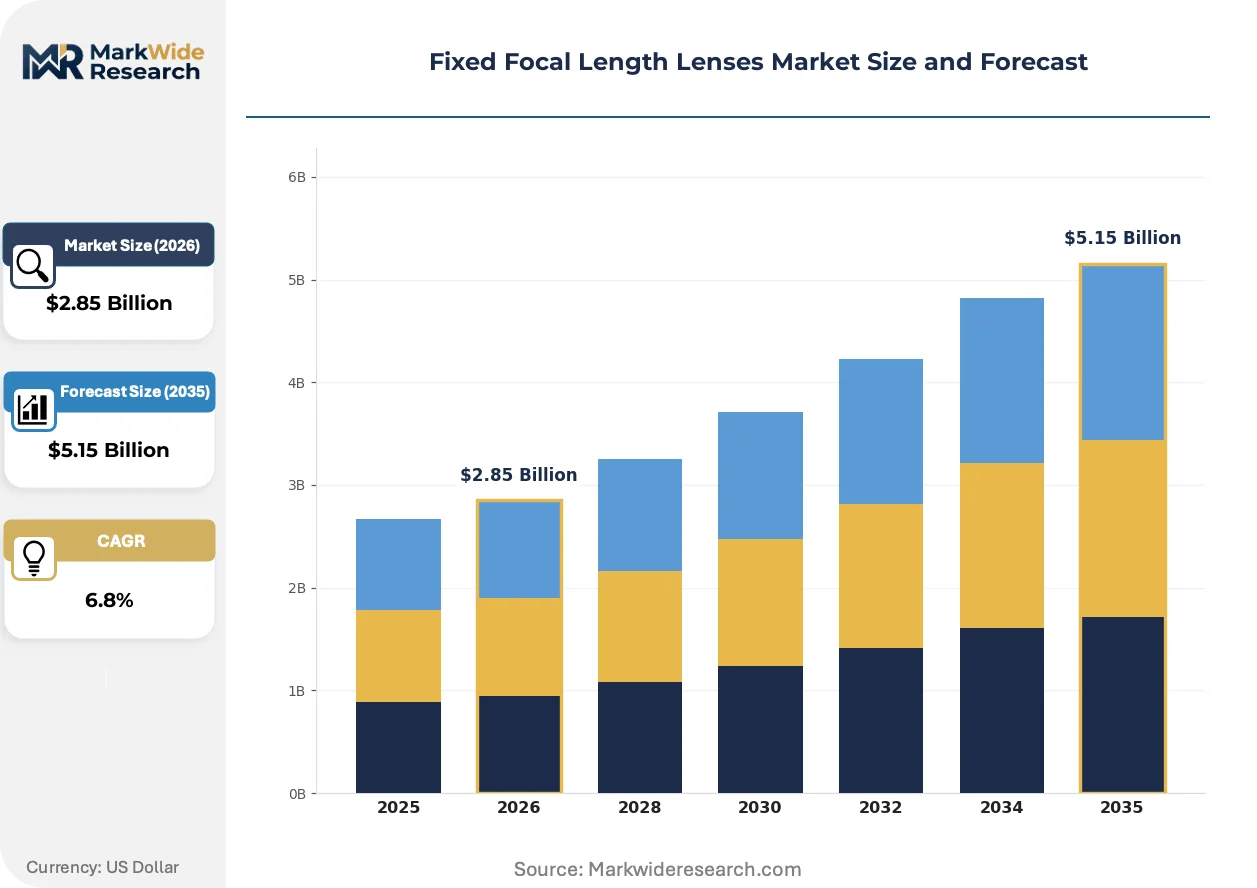
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telephoto, Wide-Angle, Standard, Macro End User: Photography, Videography, Surveillance, Industrial Application: Broadcasting, Medical Imaging, Security, Cinematography Technology: Optical, Digital, Hybrid, Infrared |
| Companies Covered | Kowa, Edmund Optics, Opto Engineering, Wenglor, KEYENCE, VS Technology, Computar, Schneider Kreuznach, ZEISS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Focal Length Lenses Market Trends and Innovations
Computational imaging and embedded correction algorithms are decoupling optical performance from mechanical complexity, enabling simplified lens architectures that trade pure optical precision for software-augmented output quality.
Freeform surface manufacturing is displacing traditional spherical and axisymmetric aspheric grinding in head-up display and AR waveguide projector applications. Automotive Tier-1 suppliers are adopting diamond-turned aluminum freeform mirrors at 18-month design cycles. This technology is displacing multi-element relay lens assemblies previously required for pupil expansion, compressing bill-of-material counts by 40-60% in near-eye optical engines.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon solvent elimination from anti-reflective coating deposition processes. European lens fabricators are transitioning to plasma-enhanced chemical vapor deposition and atomic layer deposition chemistries. Medical imaging and semiconductor lithography subsystems face the steepest compliance timelines, with German and French suppliers reporting 12-16 month process revalidation periods.
Buyer consolidation among machine vision integrators is compressing supplier negotiation cycles and unbundling after-sales service from hardware procurement. Large automotive inspection line operators in Germany and Japan now demand lifetime MTF degradation guarantees rather than discrete acceptance testing. This contractual shift concentrates procurement authority with vertically integrated optics houses capable of absorbing long-term performance liability.
Fixed Focal Length Lenses Market Segmentation
Fixed focal length lens procurement channels diverge sharply by performance tier and certification burden. Machine vision integrators, cinematography rental houses, and defense contractors operate through disconnected qualification systems that reshape supplier access.
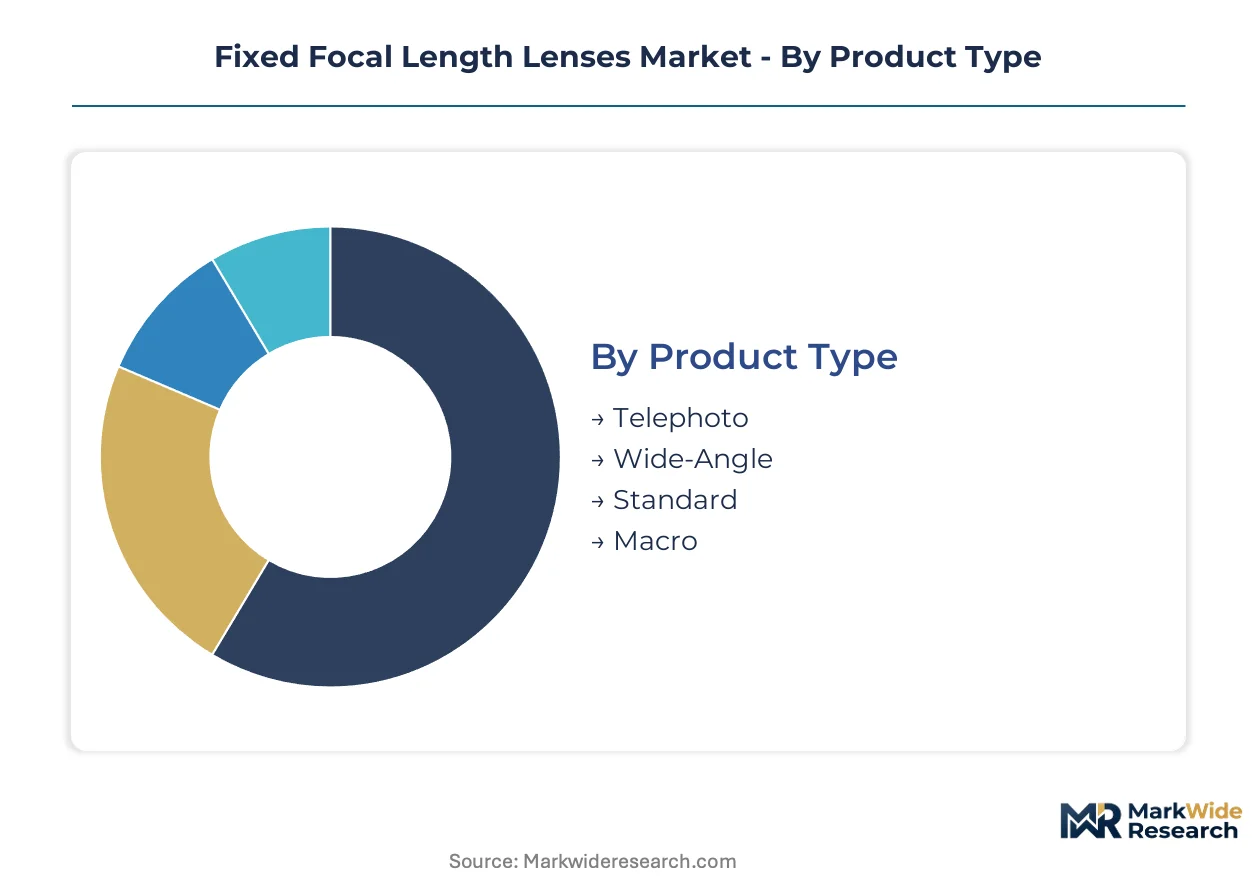
Product Type:
Distribution runs through three distinct channels: cinematography rental houses for premium telephoto and wide-angle glass, factory automation distributors for macro and standard lenses, and defense integrators for specialized infrared-corrected variants.
- Telephoto:Long focal length designs with tight angular field of view and minimal distortion prioritize large-format sensor coverage. Demand concentrates in sports broadcasting and wildlife cinematography where working distance flexibility outweighs aperture speed. REACH-compliant lead-free glass formulations constrain European supplier margins.
- Macro:Flat-field correction and extended working distances define medical imaging and semiconductor metrology specifications. Procurement from German and Japanese machine vision integrators requires ISO 9001 and FDA 21 CFR Part 820 dual certification. China's MIIT imaging equipment certification gates domestic factory automation channels.
- Wide-Angle:Short focal lengths with barrel distortion control for immersive cinematography and architectural documentation.
- Standard:Moderate focal lengths serving general-purpose photography and entry-level machine vision where cost tolerance limits precision specifications.
Macro dominates installed base in semiconductor fabs and surgical suites. Wide-Angle is where expansion concentrates in streaming content production.
End User:
Margin structures vary dramatically across customer types, with industrial procurement absorbing 40-60% longer qualification cycles than consumer-facing segments.
- Industrial:Machine vision deployment in semiconductor inspection lines and automotive quality gates demands sub-micron distortion stability. Japanese and German automotive Tier-1s now require lifetime MTF degradation guarantees rather than discrete acceptance testing. This contractual shift concentrates procurement with vertically integrated optics houses.
- Photography:Professional and enthusiast segments prioritize maximum aperture speed and bokeh rendering characteristics. Leica, Zeiss, and Sigma service this channel through heritage brand positioning and limited-edition optical formulas.
- Videography:Independent content creators and commercial production houses driving demand for cine-modified stills lenses with unified gear pitch and T-stop calibration.
- Surveillance:Municipal and enterprise security budgets favor cost-optimized designs with weather sealing and vandal resistance over optical performance.
Industrial commands premium pricing through certification barriers. Videography represents the steepest expansion trajectory as streaming platform content budgets multiply.
Application:
Regulatory jurisdiction determines specification rigidity, with medical and semiconductor applications facing the most constrained design windows.
- Medical Imaging:Surgical camera and endoscopy integrators operate under FDA 21 CFR Part 820 quality system regulation in the US and MDR compliance in Europe. Macro lenses with extended working distances and sterilization-compatible housings command 3-5x pricing multiples over industrial equivalents.
- Cinematography:Feature film and high-end commercial production demand T-stop consistency, unified focus gear pitch, and minimal breathing. Cooke and Arri service this segment through multi-decade rental house relationships and standardized mount ecosystems.
- Broadcasting:Hybrid optical-digital architectures with embedded real-time distortion correction are displacing pure optical precision requirements. Firmware-enabled performance upgrades create recurring service revenue streams.
- Security:Mass-market surveillance favors molded plastic aspherics and simplified coatings where wavefront error tolerance permits cost minimization.
Cinematography anchors revenue per unit. Medical Imaging is where margin expansion concentrates through regulatory moats.
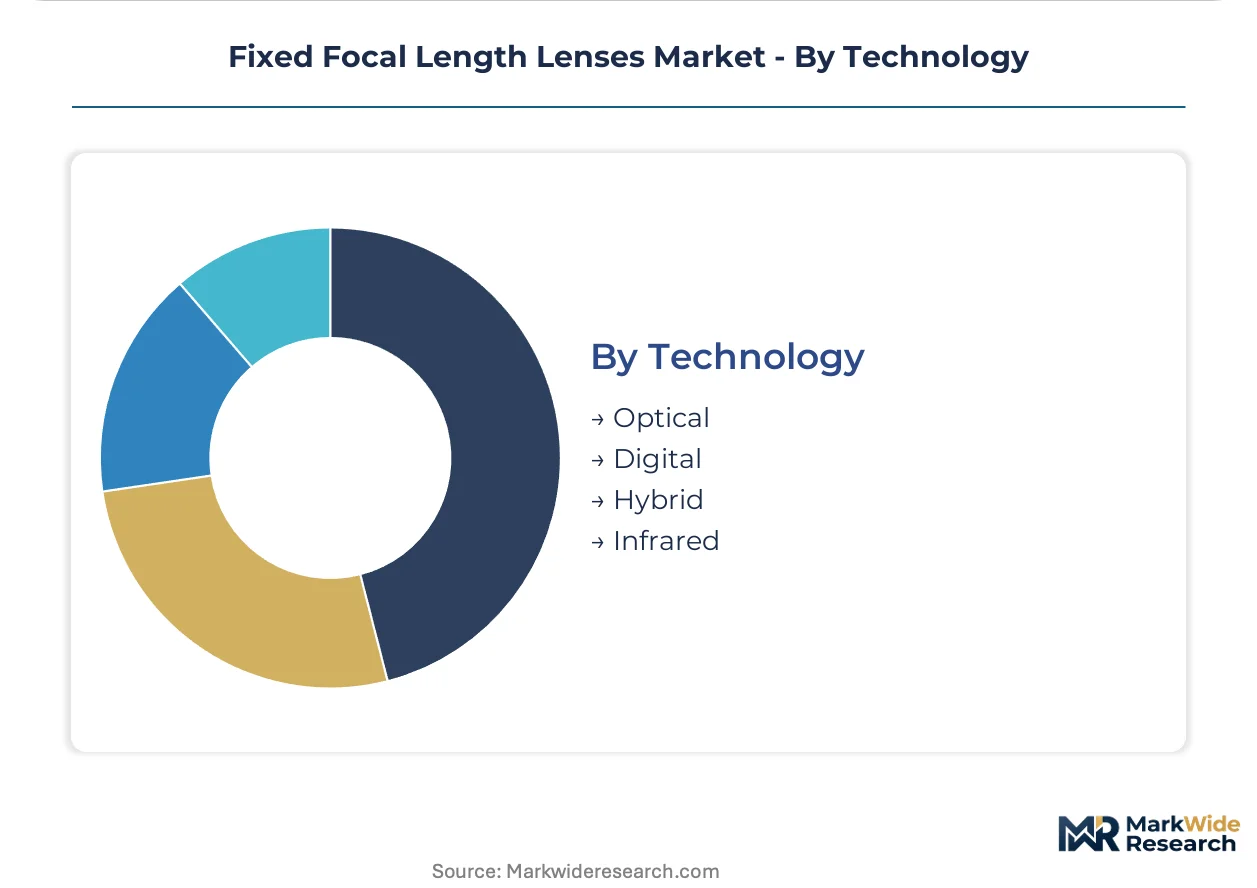
Technology:
Supply concentration in exotic glass dopants and coating deposition equipment creates asymmetric access for integrated versus merchant suppliers.
- Optical:Pure refractive designs with precision-ground spherical and aspheric elements remain dominant in semiconductor lithography and medical imaging where software correction is prohibited by validation protocols. Lanthanum and tantalum oxide feedstock concentration in Chinese rare earth processing exposes non-integrated suppliers to input volatility.
- Infrared:Fixed-IR lenses for thermal imaging and defense applications are expanding as vanadium oxide microbolometer costs decline. Uncooled sensor economics now permit industrial predictive maintenance deployment previously constrained by detector pricing.
- Hybrid:Optical-digital architectures embedding real-time distortion correction simplify mechanical complexity and enable firmware-based performance upgrades.
- Digital:Computational imaging pipelines with minimal optical front-ends are penetrating consumer and prosumer segments where output quality tolerates software augmentation.
Optical dominates validated applications where regulatory preclusion of software correction is mandatory. Hybrid is where capability expansion concentrates through algorithmic performance scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine vision integrators and semiconductor equipment OEMs cluster in East Asian precision manufacturing corridors and German automotive belts. Procurement authority concentrates with buyers demanding MIIT, ISO 9001, and FDA dual certifications.
China
Domestic factory automation channels gate through MIIT imaging equipment certification requirements. Smart manufacturing infrastructure investments in Suzhou and Shenzhen industrial parks drive fixed focal length lens volumes for semiconductor inspection lines. Yangtze River Delta precision optics clusters supply certified vendors to domestic lithography subsystem integrators.
Germany
Automotive Tier-1 inspection line operators in Stuttgart and Munich now mandate lifetime MTF degradation guarantees. ECHA REACH substance restrictions on lead arsenate optical glasses force suppliers toward fluorite alternatives. Bavarian machine vision integrators anchor European demand for macro lenses with sub-micron distortion stability.
Japan
Metropolitan Tokyo and Osaka house concentrated semiconductor fab equipment OEM procurement. METI industrial standards shape specification windows for fixed-IR lenses in thermal inspection applications. Chubu region precision grinding workshops supply deterministic polishing expertise for EUV projection subsystems.
United States
Surgical camera integrators under FDA 21 CFR Part 820 quality system regulation command premium macro lens positioning. Greater Boston and Silicon Valley machine vision startups absorb fixed focal length designs for defect detection pipelines. Defense thermal imaging budgets in Southern California expand fixed-IR segments as uncooled sensor economics improve.
South Korea
Seoul Capital Area display panel manufacturers deploy machine vision for OLED defect inspection at sub-pixel resolution. MFDS medical device regulations parallel FDA pathways for endoscopy lens qualification. Busan-Ulsan shipbuilding automation lines import German and Japanese macro lenses for dimensional metrology.
Fixed Focal Length Lenses Market Competitive Landscape
Player mix skews toward vertically integrated precision optics houses and specialized machine vision component suppliers. The vendor base separates into heritage cinematography brands, semiconductor lithography subsystem specialists, and factory automation distributors. Three archetypes dominate: coating-heritage European houses, glass-grinding integrated Asian suppliers, and software-augmented hybrid architecture vendors. Competitive moves concentrate on captive rare earth feedstock security and firmware-enabled performance upgrade service models.
Among heritage European coating specialists, Schneider Kreuznach and ZEISS occupy positions exemplifying premium-tier archetypes through decades of lithography and cinematography channel anchoring. Edmund Optics represents the North American integrated fabricator model with in-house glass grinding capabilities. Japanese specialists including Kowa and Computar sit within the factory automation distributor channel, serving machine vision integrators with certified macro and telephoto designs.
| Leading Market Players |
|---|
| Kowa |
| Edmund Optics |
| Opto Engineering |
| Wenglor |
| KEYENCE |
| VS Technology |
| Computar |
| Schneider Kreuznach |
| ZEISS |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month qualification cycles for dual ISO 9001 and FDA 21 CFR Part 820 certification freeze working capital at mid-tier suppliers, compressing pricing power among non-integrated fabricators while amplifying margin capture for vertically integrated houses with captive glass grinding. This lead-time concentration reshapes procurement negotiations as German automotive Tier-1s and Chinese MIIT-certified factory automation channels demand lifetime MTF degradation guarantees rather than discrete acceptance testing.
Pricing Analysis
Cost-plus contracts with lanthanum oxide feedstock indexation dominate procurement agreements for semiconductor lithography subsystems. Pricing stratifies across premium, standard, and economy tiers based on surface figure precision grades and certification portfolio breadth. Cost compression in standard-grade machine vision lenses is intensifying as Chinese rare earth processing concentration exposes non-integrated suppliers to input volatility. Industrial integrators exhibit lowest price sensitivity due to qualification lock-in, while surveillance and entry-level photography segments absorb maximum downward pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German and French coating deposition equipment imports. Precision glass feedstock draws from Chinese rare earth processing, Japanese optical glass melting, and German fluorite crystal growth. Single-source vulnerability concentrates in lanthanum and tantalum oxide supply. Distribution runs through factory automation distributors, cinematography rental houses, and defense integrators with disconnected qualification systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among machine vision integrators and automotive Tier-1 inspection line operators has shifted negotiation leverage toward procurement departments demanding extended performance guarantees, fragmenting supplier pricing power across certification tiers.
For Market Incumbents: Secure captive rare earth feedstock through backward integration into Chinese or Australian oxide processing to mitigate lanthanum cost volatility threatening margin stability. Deepen certification moats by accelerating FDA 21 CFR Part 820 and China MIIT dual qualification pipelines before qualification cycle lengthening freezes out mid-tier competitors. For New Entrants and Emerging Players: Differentiate on hybrid optical-digital architectures with firmware-enabled distortion correction to bypass the decade-long craftsman apprenticeship barriers constraining pure optical competitors. Target spectral analysis instrumentation for Raman and LIBS spectrometer OEMs, a segment with lower competitive density than machine vision and reduced certification burden. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory moats in medical imaging and semiconductor lithography subsystems widen as qualification cycles extend. Acquisition focus should center on mid-tier precision grinding houses with tacit knowledge assets but underinvested certification portfolios. The signal to watch is MIIT imaging equipment certification expansion beyond current factory automation channels into medical device infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxide Processing | Mitigates lanthanum feedstock concentration risk from Chinese export controls. |
| Dual Certification Pipeline Expansion | Accelerates ISO 9001 and FDA 21 CFR Part 820 qualification before cycle lengthening. |
| Hybrid Optical-Digital Architecture Development | Enables firmware-based performance upgrades bypassing craftsman scarcity constraints. |
| Freeform Surface Manufacturing Investment | Displaces multi-element relay assemblies in AR waveguide and HUD applications. |
| Lifetime MTF Degradation Guarantee Programs | Matches German automotive Tier-1 contractual demands concentrating procurement authority. |
Research Methodology
Initial hypotheses were tested against primary input from machine vision integrators, semiconductor equipment OEM procurement leads, precision optics plant managers, and coating deposition process engineers and refined through secondary validation against SEC 10-K filings, ECHA REACH substance restriction updates, MIIT certification registries, and customs trade data. Bottom-up volume builds from certified supplier production capacity triangulated against top-down end-use demand segmentation across lithography, medical imaging, and factory automation channels.
Variance decomposition across product type, end user, application, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro drivers including uncooled infrared sensor cost decline and EU F-Gas Regulation compliance timelines. Industry-specific forecast inputs incorporated vanadium oxide microbolometer pricing trajectories and deterministic polishing capacity expansion constraints.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, ECHA REACH, and China MIIT certification regimes; material policy shifts would require re-modeling. Specific risks include exotic glass dopant export control expansion, EU F-Gas Regulation acceleration, and plastic aspheric mold precision breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Global Super Hi Vision Market
Optics
Glass Scintillator Market
Optics
Germanium Lens Market
Optics
Optical Measuring Systems Market
Optics
Smartphone Camera Lenses Market
Optics
AR and VR Lens Market
Optics
Fiber-Optic Filters Market
Optics
Optical Receivers Market
Optics
Digital Holographic Microscopy Market
Optics
North America Optical Imaging Market
Optics
Optical Fiber Market
Optics
Fiber Optic Preform Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Asia-Pacific Optical Imaging Market
Optics
India Laser Market
Optics
Plastic Lens Market