
 Silicon Wafer Market | 2026-2036
Silicon Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Wafer Market Intelligence
Japanese polysilicon-to-wafer supply chains is hardening against raw material volatility. Shin-Etsu Chemical leverages captive polysilicon refining to insulate margins from feedstock swings. SUMCO anchors 300mm logic-wafer output through long-term supply agreements with foundry customers. SK Siltron competes in SiC-adjacent silicon substrates as automotive electrification broadens the addressable wafer base.
A silicon wafer is a thin, circular slice of single-crystal or polycrystalline silicon with diameters ranging from 150mm to 300mm for commercial production, polished to atomic-scale flatness for subsequent photolithographic patterning. It serves as the fundamental substrate for integrated circuit fabrication, where transistor layers deposit epitaxially across its crystalline lattice. Monocrystalline wafers dominate leading-edge logic and memory applications due to defect-free lattice structures that maximize chip yield. SOI substrates command premium positioning in RF and power-efficient designs where buried oxide layers reduce parasitic capacitance. Photovoltaic-grade multicrystalline wafers occupy a mature cost-optimized tier as solar module manufacturers prioritize cell efficiency gains over substrate refinement.
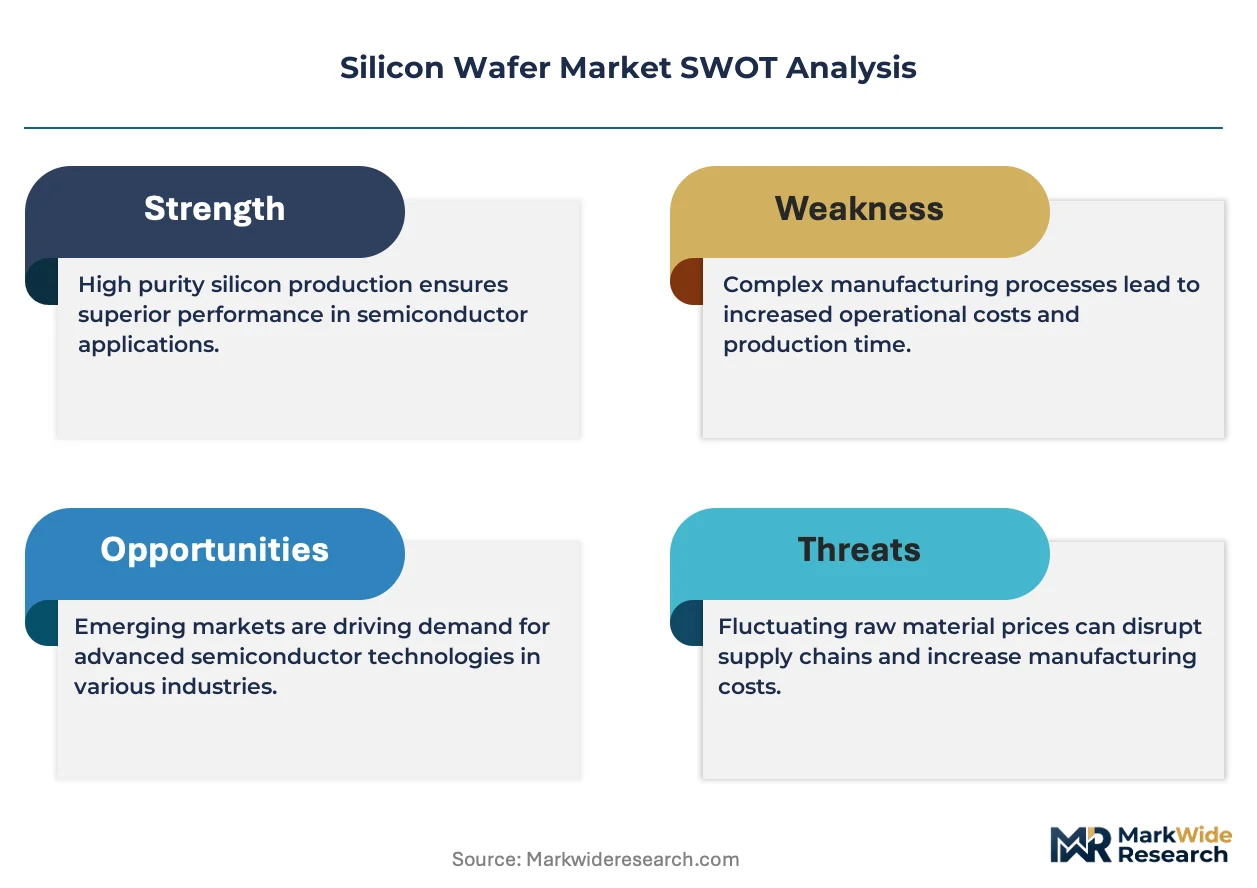
Japan's METI enforces domestic semiconductor material security guidelines that prioritize local wafer inventory buffers for strategic fabs. The EU Chips Act and REACH chemical compliance collectively shape where new European silicon purification and crystal-pulling capacity can locate. China's GB standards and MIIT semiconductor self-sufficiency targets redirect domestic wafer procurement toward certified local suppliers. Stakeholders must monitor how export control alignment between the US, Japan, and the Netherlands reshapes equipment access and thus wafer geometry roadmaps.
Market Dynamics
Leading-edge logic and memory fabs are compressing node transitions while expanding 300mm wafer consumption, tightening supply-demand balances across polysilicon-to-polished-wafer chains. This structural pressure is redrawing procurement timelines and inventory strategies for substrate buyers.
Growth Catalysts
- Advanced logic node ramps:3nm and 2nm process introductions at Taiwan and South Korea foundries are expanding 300mm epitaxial wafer volumes. These fabs now specify ultra-flat substrates with sub-nanometer topology tolerances.
- EU Chips Act capital deployment:Subsidized fab construction in Germany, France, and Italy is generating localized demand for 300mm silicon. The regulation mandates supply chain resilience criteria that favor European-qualified wafer vendors.
- Automotive SiC transition:Power module manufacturers are specifying silicon-on-insulator and thick epitaxial wafers for traction inverters. This application diversifies demand beyond traditional logic and memory segments.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon feedstock costs swing with Chinese solar panel production cycles. Wafer manufacturers without captive polysilicon refining face margin compression during upstream spikes.
- Equipment access restrictions:Export control alignment between the US, Japan, and the Netherlands limits crystal puller and epitaxy tool availability in China. This constrains domestic 300mm capacity expansion despite MIIT self-sufficiency targets.
- SOI substrate cost premiums:Bonded and smart-cut silicon-on-insulator wafers command 3-5x pricing over bulk silicon. This restricts adoption to RF and low-power designs where parasitic reduction justifies expenditure.
Strategic Opportunities
- India semiconductor ecosystem buildout:PLI scheme incentives for display and fab projects in Gujarat and Karnataka are creating first-mover advantages for wafer suppliers establishing local technical service presence.
- GaN-on-silicon power integration:Gallium nitride epitaxy on 200mm silicon substrates is penetrating consumer fast-charger and data center power supply markets. This merges compound semiconductor performance with silicon cost structures.
- Japan METI material security stockpiling:Domestic inventory buffer mandates for strategic fabs create contracted offtake opportunities. Suppliers with JIS-certified 300mm capacity can secure multi-year purchase commitments.
Industry Challenges
- Crystal growth technician scarcity:Czochralski puller operation and defect engineering require 10-15 year experience curves. Foundry expansion timelines outpace skilled labor formation in Taiwan and South Korea.
- Epitaxial reactor certification delays:Automotive-grade wafer qualification under AEC-Q100 and customer-specific PPAP protocols extends 18-24 months. This mismatches with power semiconductor demand acceleration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Wafer Market |
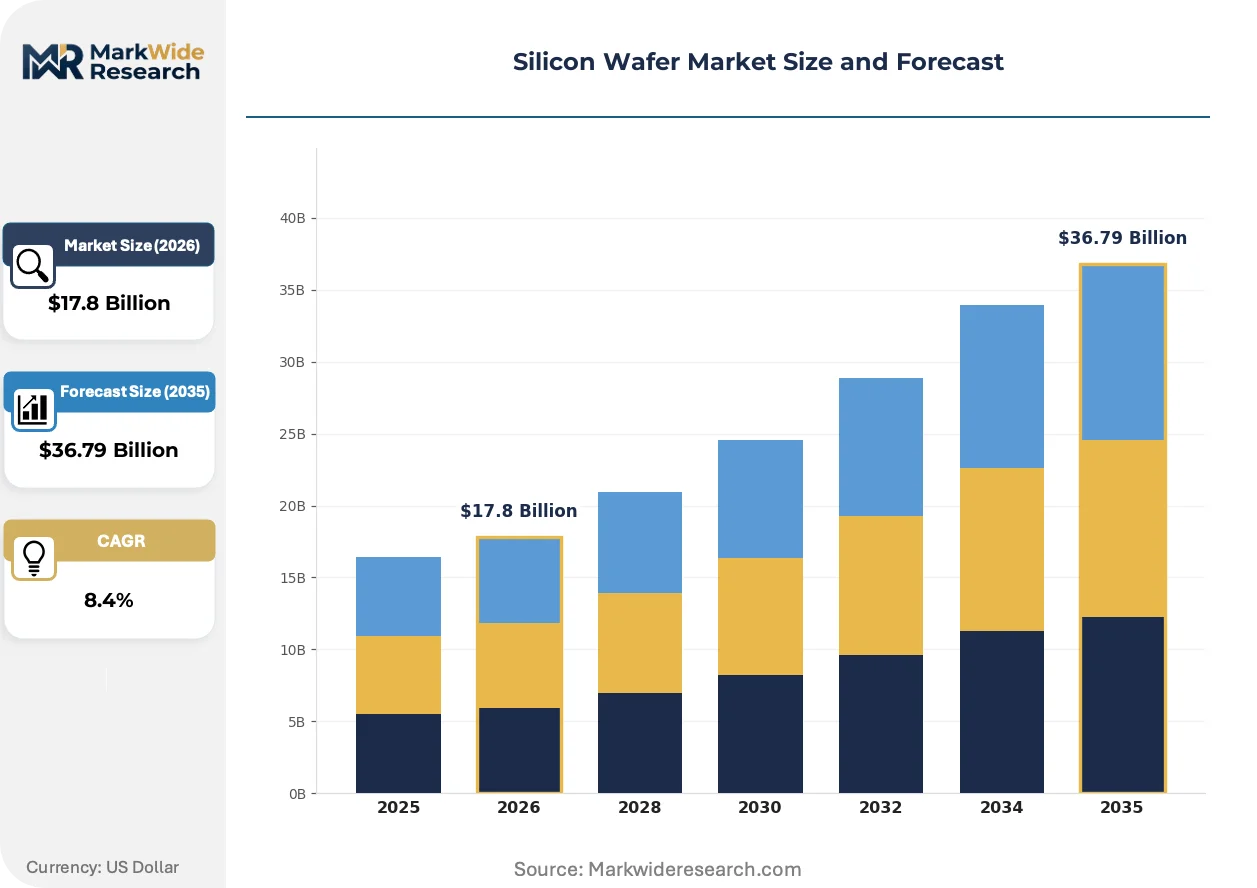
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $36.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Multicrystalline, Polycrystalline, SOI Diameter: 150mm, 200mm, 300mm, 450mm Application: Semiconductors, Photovoltaic Cells, MEMS, Sensors End Use Industry: Electronics, Renewable Energy, Automotive, Telecommunications |
| Companies Covered | Shin-Etsu Chemical Co. Ltd., SUMCO Corporation, GlobalWafers Co. Ltd., Siltronic AG, SK Siltron Co. Ltd., Soitec SA, Okmetic Oy, Wafer Works Corporation, WaferPro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Wafer Market Strategic Shifts & Innovations
Wafer geometry roadmaps are diverging as logic, memory, and power applications impose incompatible substrate specifications. This specialization is fragmenting equipment utilization and reshaping vendor R&D allocation.
Silicon carbide-ready 200mm substrates are electrifying automotive power module supply chains. Tier-1 inverter manufacturers in Germany and Japan are qualifying these wafers for 800V traction systems. The technology is compressing timelines for silicon carbide cost parity by enabling larger die yields per wafer.
REACH chemical compliance and the EU Green Deal are restricting fluorinated gas usage in silicon etch and cleaning processes. Wafer manufacturers are retrofitting abatement systems and qualifying fluorine-free chemistries at European crystal growth facilities. This affects primarily 300mm logic-wafer polishing operations where surface preparation chemistry is most intensive.
Long-term supply agreements are displacing spot market purchasing for leading-edge 300mm wafers. Taiwan and South Korea foundries are contracting 3-5 year volume commitments directly with Shin-Etsu and SUMCO. This concentration is visible most acutely in 5nm and 3nm node ramps where substrate defect specifications are tightest.
Silicon Wafer Market Segmentation
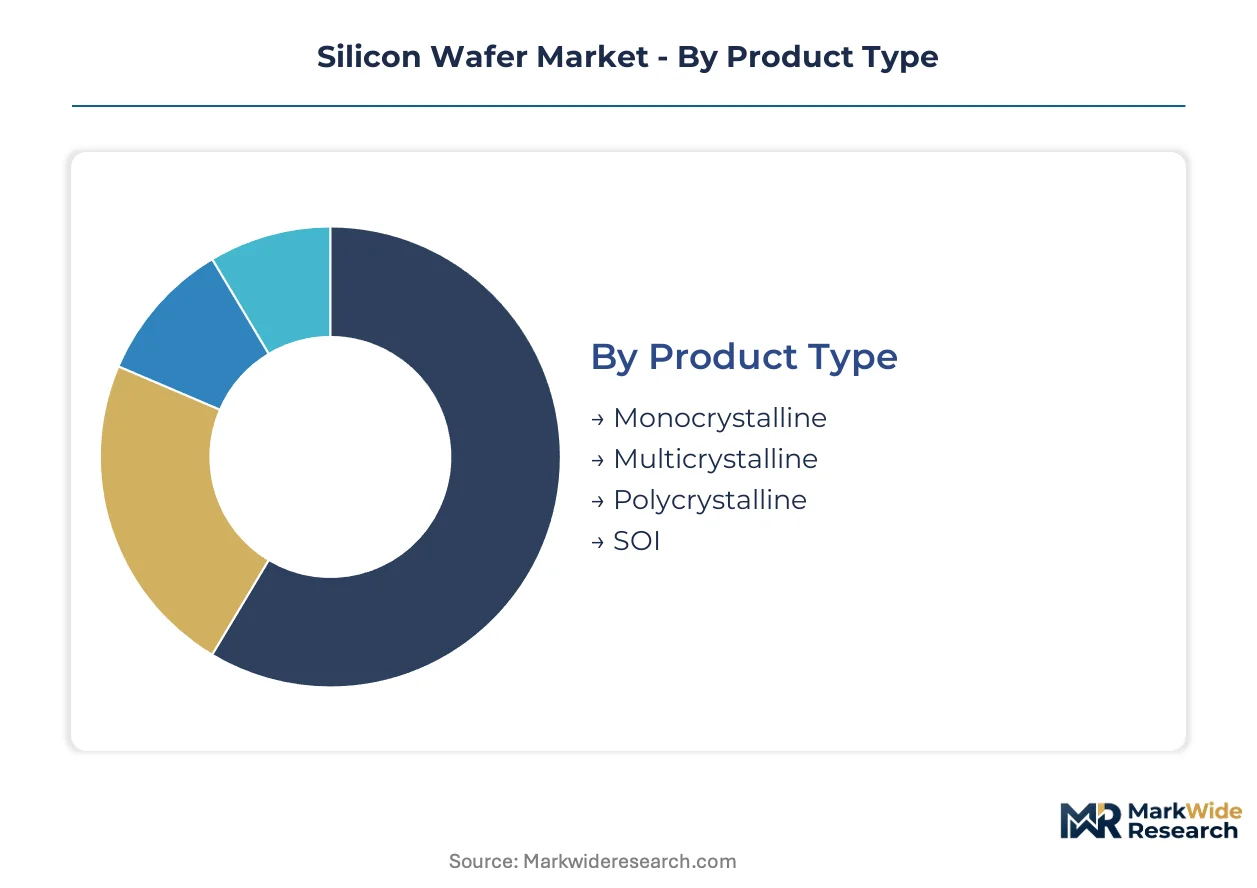
Silicon wafer segmentation tracks how substrate specifications diverge across logic, memory, power, and solar applications. Each dimension—crystal structure, diameter, application, and end-use—carries distinct margin profiles and supply chain requirements that reshape vendor prioritization.
Product Type:
Volume concentrates in monocrystalline substrates while premium pricing accrues to specialized architectures.
- Monocrystalline:Single-crystal ingots grown via Czochralski pulling deliver defect-free lattices essential for leading-edge logic and DRAM fabrication. Taiwan and South Korea foundries now specify sub-nanometer flatness tolerances for 3nm node ramps, tightening qualification windows for suppliers.
- SOI:Silicon-on-insulator substrates incorporate buried oxide layers that cut parasitic capacitance in RF transceivers and low-power designs. Automotive radar module manufacturers in Germany and Japan are expanding bonded-wafer procurement despite 3-5x cost premiums over bulk silicon.
- Multicrystalline:Directional solidification produces cost-optimized substrates for legacy power semiconductors and industrial sensors where crystal perfection matters less than unit economics.
- Polycrystalline:Cast silicon blocks sliced into wafers serve photovoltaic cell manufacturing, with Chinese solar module producers driving procurement scale.
Today's leader: Monocrystalline. Tomorrow's challenger: SOI.
Diameter:
Customer type splits the market—foundries and memory houses at 300mm, power and analog specialists at 200mm, legacy fabs and researchers below.
- 300mm:Twelve-inch wafers maximize die-per-wafer economics for advanced logic and NAND flash production. Shin-Etsu and SUMCO have locked in multi-year supply agreements with Taiwan Semiconductor Manufacturing and Samsung Foundry, cementing procurement concentration.
- 200mm:Eight-inch substrates dominate automotive power discretes, analog ICs, and MEMS sensors where process maturity outweighs scaling economics. Infineon and STMicroelectronics in Europe are expanding 200mm silicon carbide-ready wafer qualification for 800V traction inverters.
- 150mm:Six-inch wafers persist in specialty foundries, university research consortia, and gallium nitride-on-silicon pilot lines for fast-charger applications.
- 450mm:Eighteen-inch prototypes remain stalled after Intel and TSMC shelved migration roadmaps; equipment non-availability and retrofit costs have frozen development.
300mm captures the revenue concentration. 200mm is climbing the fastest as automotive electrification broadens the addressable base.
Application:
Application segmentation reveals how substrate purity, crystallography, and surface preparation requirements diverge across device categories.
- Semiconductors:Integrated circuit fabrication demands the tightest defect specifications and epitaxial layer control, with Taiwan and South Korea fabs consuming the majority of 300mm prime-grade output.
- Photovoltaic Cells:Solar wafer procurement prioritizes cost-per-watt over lattice perfection, with Chinese panel manufacturers specifying multicrystalline and cast-mono architectures.
- MEMS:Microelectromechanical systems require thick silicon layers for mechanical structures, with Bosch and STMicroelectronics driving 200mm demand for automotive pressure and inertial sensors.
- Sensors:Image sensors and environmental detectors use tailored resistivity grades, with Sony and OmniVision specifying customized epitaxial thickness for CMOS imagers.
Semiconductors anchor current procurement. Photovoltaic cells are gaining share fastest as renewable energy targets accelerate module deployment.
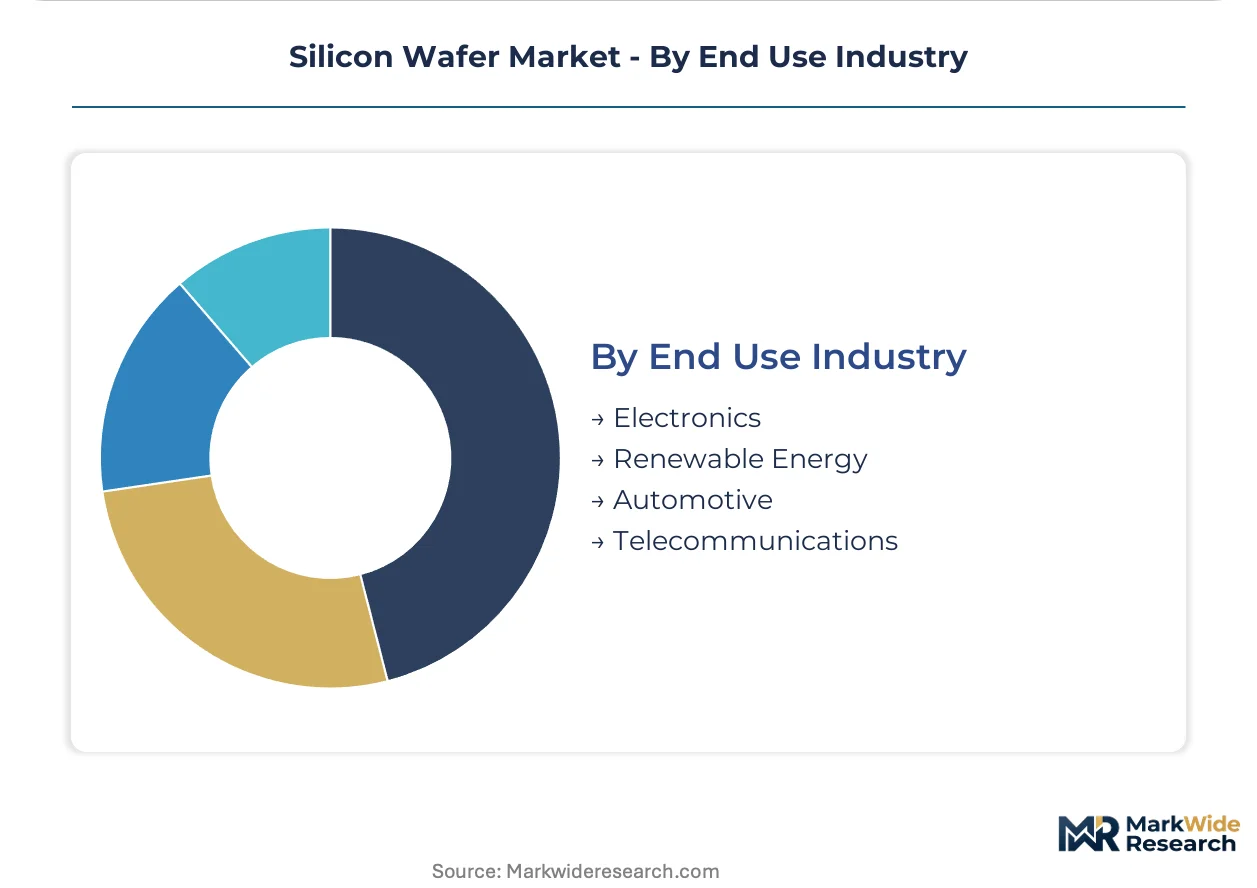
End Use Industry:
Maturity stratification separates established electronics demand from emerging automotive and renewable energy growth vectors.
- Electronics:Smartphones, PCs, and data center infrastructure consume the majority of leading-edge logic and memory wafers, with Taiwan and South Korea foundries translating consumer device cycles into substrate pull.
- Automotive:Electrification and advanced driver-assistance systems are expanding silicon carbide and SOI wafer demand for traction inverters and radar modules, with German and Japanese tier-1 suppliers qualifying new substrate specifications.
- Renewable Energy:Solar farm deployments and distributed generation are driving polysilicon and multicrystalline wafer consumption, with Chinese installation targets shaping upstream procurement.
- Telecommunications:5G base station and satellite communication builds are lifting RF SOI substrate demand for switch and low-noise amplifier integration.
Electronics maintains the revenue base. Automotive is expanding most quickly as power semiconductor content per vehicle multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting silicon wafer capacity toward jurisdictions with lower compliance costs and stronger subsidy regimes. Japan's METI material security mandates and the EU Chips Act's local content requirements are pulling investment in opposite directions, while equipment access restrictions fragment China's expansion trajectory.
Japan
Domestic foundry demand from Tokyo Electron's ecosystem and automotive radar module manufacturers anchors 300mm wafer consumption. METI enforces semiconductor material security guidelines requiring local inventory buffers for strategic fabs. The Kanto region around Tokyo hosts Shin-Etsu Chemical's captive polysilicon refining and SUMCO's logic-wafer polishing operations.
Taiwan
TSMC and United Microelectronics drive the densest concentration of leading-edge 300mm epitaxial wafer procurement globally. The island's National Development Council coordinates supply chain resilience programs with Japanese material suppliers. Hsinchu Science Park clusters foundry demand with immediate proximity to wafer vendor technical service teams.
Germany
Infineon and Bosch are expanding 200mm silicon carbide-ready wafer qualification for 800V automotive traction inverters. The EU Chips Act mandates supply chain resilience criteria favoring European-qualified vendors. Saxony's Silicon Saxony cluster in Dresden concentrates memory and logic fab construction subsidized under national IPCEI frameworks.
South Korea
Samsung Foundry and SK Hynix compress node transitions while expanding 300mm consumption for 3nm logic and DRAM stacks. The Ministry of Trade, Industry and Energy operates K-Semiconductor Belt initiatives linking Seoul to Pyeongtaek. Yongin and Icheon host the densest wafer consumption corridors outside Taiwan.
China
MIIT semiconductor self-sufficiency targets redirect domestic procurement toward certified local suppliers despite equipment access constraints. Dual carbon goals and GB standards shape where new purification capacity locates. The Yangtze River Delta around Shanghai and the Pearl River Delta host competing clusters of 300mm pilot lines and legacy 200mm expansion.
Silicon Wafer Market Key Industry Players
Japanese producers anchor the premium-tier supply base; Taiwanese and Korean specialists hold volume-contract positions with foundry customers. The market structure concentrates around five integrated manufacturers controlling polysilicon-to-polished-wafer chains, with mid-scale European and Korean players occupying specialized niches in SOI and SiC-adjacent substrates. Two archetypes dominate: vertically integrated chemical conglomerates with captive feedstock refining, and pure-play wafer specialists relying on long-term supply agreements for margin stability. Competitive moves center on multi-year offtake contracting with leading-edge foundries and geographic expansion into India and Southeast Asia.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co. Ltd. and SUMCO Corporation exemplify the integrated archetype through upstream control over polysilicon supply. Siltronic AG represents European positioning within REACH-compliant manufacturing environments. SK Siltron Co. Ltd. occupies a specialized tier serving power semiconductor transitions.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co. Ltd. |
| SUMCO Corporation |
| GlobalWafers Co. Ltd. |
| Siltronic AG |
| SK Siltron Co. Ltd. |
| Soitec SA |
| Okmetic Oy |
| Wafer Works Corporation |
| WaferPro |
| Others |
Cost & Logistics Intelligence
Polysilicon feedstock costs cascade through metallurgical-grade silicon purification to crystal pulling and epitaxial polishing, with Shin-Etsu Chemical's captive refining insulating margins from Chinese solar panel production swings that otherwise compress spot-market wafer pricing. Long-term offtake agreements between Japanese suppliers and Taiwan foundries now lock in volume commitments that shield premium 300mm logic-wafer tiers from commodity volatility while exposing multicrystalline solar-grade producers to upstream price cycles.
Pricing Analysis
Distributor margins compress where wafer vendors sell direct to foundry procurement teams, with Shin-Etsu and SUMCO commanding premium positioning through multi-year supply agreements that bypass intermediary layers. Three-tier pricing structure across prime-grade epitaxial, test-grade, and reclaim wafers separates Taiwan Semiconductor Manufacturing's sub-nanometer flatness specifications from automotive MEMS producers tolerating higher defect densities. Cost compression in solar-grade multicrystalline tiers intensifies because Chinese panel manufacturers prioritize cost-per-watt over lattice perfection. Memory fabs exhibit lowest price sensitivity due to die-yield economics, while distributed solar installers negotiate aggressively on volume procurement.
Supply Chain Analysis
Regional distribution centers in Yokkaichi, Hsinchu, and Dresden cluster polished wafer inventory adjacent to foundry consumption corridors, compressing logistics lead times for just-in-time epitaxial reactor feeds. Supply concentrates in Japan, Taiwan, and South Korea for 300mm prime-grade output, with China building domestic 200mm capacity despite equipment access constraints. Raw material flows draw from metallurgical-grade silicon smelters in China, high-purity polysilicon refineries in Japan, and specialized quartz crucible manufacturers in Germany. Single-source vulnerability runs through ASML-aligned crystal puller equipment access. Distribution runs through direct vendor-OEM contracting for leading-edge tiers, with spot-market intermediaries handling solar-grade surplus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where captive polysilicon refining meets automotive power semiconductor qualification, with SOI substrate premiums and SiC-ready 200mm specifications opening pricing power disconnected from commodity silicon cycles.
For Market Incumbents: Anticipate equipment access restrictions fragmenting competitor expansion in China, reinforcing Shin-Etsu and SUMCO's locked-in positions with Taiwan and South Korea foundries. Defend margin stability by deepening backward integration into polysilicon refining and securing JIS-certified capacity for Japan METI stockpile mandates. Crystal growth technician scarcity threatens foundry expansion timelines; anchor competitive position through apprenticeship pipelines and automated puller operation investments. For New Entrants and Emerging Players: Capture India PLI scheme incentives for Gujarat and Karnataka fab projects where first-mover technical service presence secures qualification windows before Shin-Etsu and SUMCO establish local subsidiaries. GaN-on-silicon fast-charger applications and automotive SiC power modules represent penetrable white-space segments outside leading-edge logic concentration. Pursue joint qualification partnerships with European tier-1 inverter manufacturers seeking second-source 200mm silicon carbide-ready substrates. For Investors and Strategic Acquirers: Consolidation pressure builds where equipment access restrictions strand mid-scale Chinese capacity and European REACH compliance costs elevate. Long-term viability favors vertically integrated chemical conglomerates with captive feedstock and multi-year foundry offtake contracts over pure-play wafer specialists exposed to spot-market solar-grade volatility. Acquisition targets include SOI substrate specialists and SiC-adjacent 200mm qualification leaders. Watch export control alignment between the US, Japan, and Netherlands as the signal for capacity relocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Shin-Etsu's captive supply insulates margins from Chinese solar production cycle swings. |
| Long-term Supply Agreement with Foundry | Taiwan Semiconductor Manufacturing's multi-year commitments lock out spot-market competitors. |
| Automotive SiC-Ready Wafer Qualification | Infineon and Bosch 800V traction inverter specifications open premium pricing tiers. |
| JIS-Certified Capacity for METI Stockpiling | Japan's material security mandates create contracted offtake opportunities for domestic suppliers. |
| India Technical Service Presence Establishment | PLI scheme incentives in Gujarat and Karnataka reward first-mover localization for fab projects. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wafer manufacturing executives, foundry procurement directors, epitaxial reactor operators, and automotive tier-1 supplier quality engineers with secondary validation against SEMI shipment statistics, Japan METI industrial production indices, EU Chips Act implementation filings, and customs trade data for polysilicon and wafer movements. Bottom-up fabrication capacity builds and top-down semiconductor equipment spending patterns were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across monocrystalline, SOI, and multicrystalline product tiers; 300mm, 200mm, and 150mm diameter categories; and semiconductor, photovoltaic, MEMS, and sensor applications. CAGRs were derived from supply-demand balance modeling across the projection horizon, incorporating crystal puller equipment delivery schedules, foundry node ramp timelines, and automotive power semiconductor content-per-vehicle trajectories as core inputs.
Export control alignment shifts, polysilicon price volatility spikes, and foundry node transition delays are the dominant revision risks that could reshape capacity expansion timelines and pricing trajectories. Forecasts reflect documented assumptions about equipment access, subsidy disbursement schedules, and qualification protocol durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market