
 Lipids Market | 2026-2036
Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Lipids Market Intelligence
Revenue from commodity-grade triglycerides is narrowing as profit pools migrate toward high-purity phospholipids and synthetic lipids for pharmaceutical applications. Croda International Plc specializes in manufacturing excipients that meet stringent regulatory standards for drug formulations. BASF SE leverages its extensive chemical synthesis capabilities to produce custom lipids for industrial and medical clients. Meanwhile, Aker BioMarine sustains its market position through a captive supply of krill-derived omega-3 phospholipids, ensuring traceability and quality control.
Lipids are a class of organic molecules, including fats and waxes, characterized by their insolubility in water. They consist of hydrocarbon chains and serve critical biological functions such as energy storage and forming cellular membranes. The market's product landscape shows that phospholipids and specific fatty acids command premium pricing due to their essential role in drug delivery systems. The triglycerides segment, primarily serving food and animal nutrition applications, represents a mature, high-volume category with lower margins.
Market access and product specifications for pharmaceutical-grade lipids are heavily influenced by regulatory bodies. The United States Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce strict Good Manufacturing Practice (GMP) standards for excipients. These rules mandate rigorous quality control and supply chain transparency. Navigating the differing requirements of regulators like Japan's PMDA is critical for suppliers aiming to serve biopharmaceutical manufacturers on a global scale.
Market Dynamics
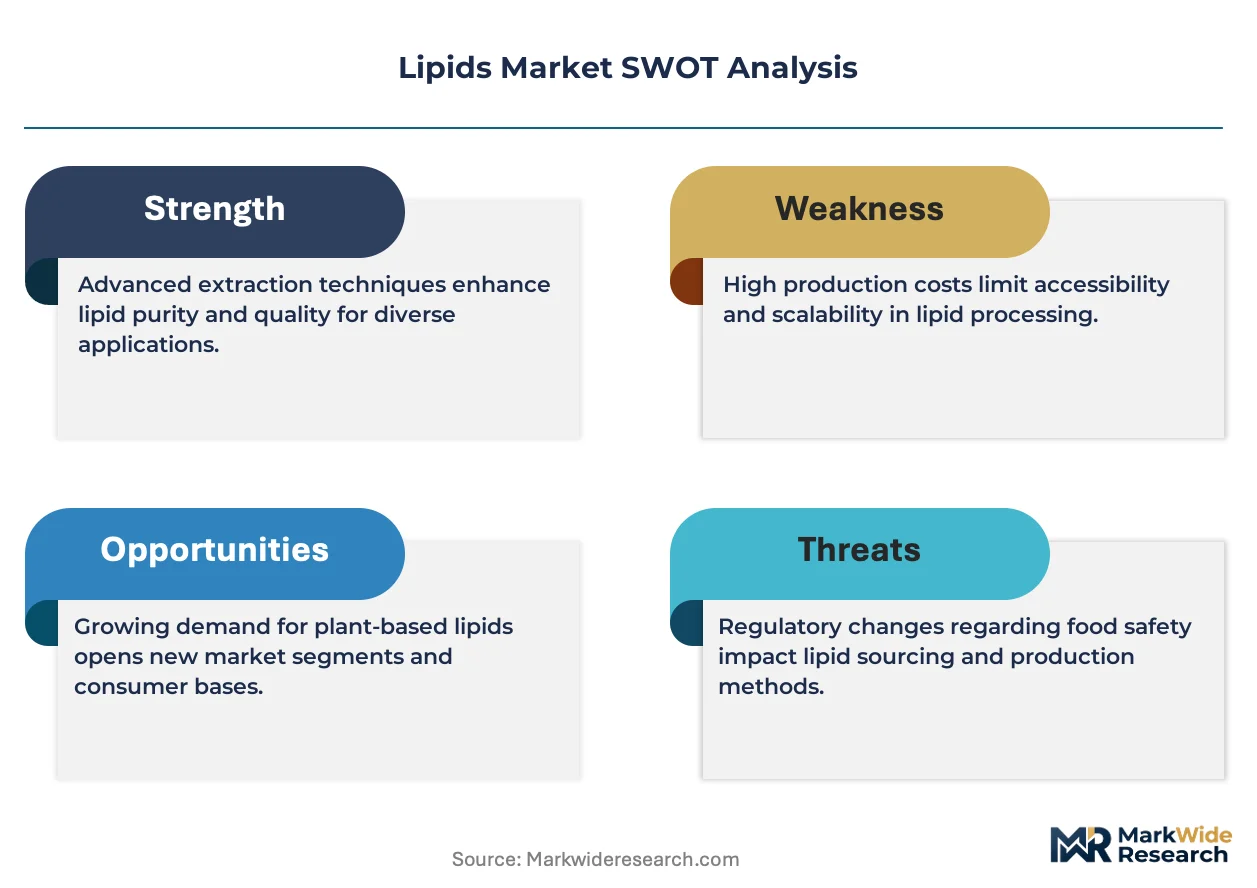
The market's central dynamic is the value shift from high-volume, commodity triglycerides to high-purity synthetic lipids. This migration is driven by the technical requirements of advanced drug delivery platforms, particularly for mRNA vaccines and cell therapies.
Growth Catalysts
- Biopharmaceutical Expansion:Demand for GMP-grade phospholipids and cholesterol is escalating with the growth of mRNA therapeutics and cell therapies, which depend on lipid nanoparticles for active ingredient delivery and stability.
- Nutraceutical Innovation:The integration of omega-3 phospholipids into functional foods and dietary supplements, supported by health-conscious consumer trends and favorable regulatory claims in Europe and North America, stimulates growth.
- Regulatory Harmonization:Initiatives by the International Council for Harmonisation (ICH) streamline the technical and regulatory requirements for pharmaceutical excipients, simplifying market access for suppliers across the United States, the EU, and Japan.
Market Restraints
- Raw Material Volatility:Production costs for natural phospholipids are subject to price fluctuations of agricultural inputs like soybeans and marine sources such as krill, impacting margin stability for manufacturers.
- Stringent GMP Manufacturing:The substantial capital investment and operational complexity required to comply with FDA and EMA good manufacturing practices for sterile excipients create high barriers to entry.
- Complex Purification Chemistry:Achieving the high purity levels demanded for synthetic lipids in parenteral drugs involves multi-step synthesis and chromatography, which are inherently costly and result in lower process yields.
Strategic Opportunities
- Novel Lipid Development:There is a significant opportunity in designing and commercializing proprietary ionizable and cationic lipids that offer improved transfection efficiency and better safety profiles for gene therapy applications.
- Biosynthesis Platforms:Engineering microorganisms like algae and yeast to produce specific high-value lipids, such as EPA and DHA, offers a sustainable and scalable alternative to traditional extraction methods.
- Indian Biopharma Market:Supplying GMP-compliant lipids to India's expanding vaccine and biologics manufacturing sector presents a key geographic growth vector as local producers upgrade their formulation capabilities.
Industry Challenges
- Analytical Standardization Gaps:A lack of universally adopted analytical methods for characterizing complex lipid excipients leads to inconsistencies in quality assessment and complicates regulatory filings with agencies like the PMDA.
- Scale-Up Engineering Hurdles:Transferring novel lipid synthesis processes from the laboratory bench to large-scale, GMP-compliant commercial manufacturing requires specialized chemical engineering expertise and significant capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipids Market |
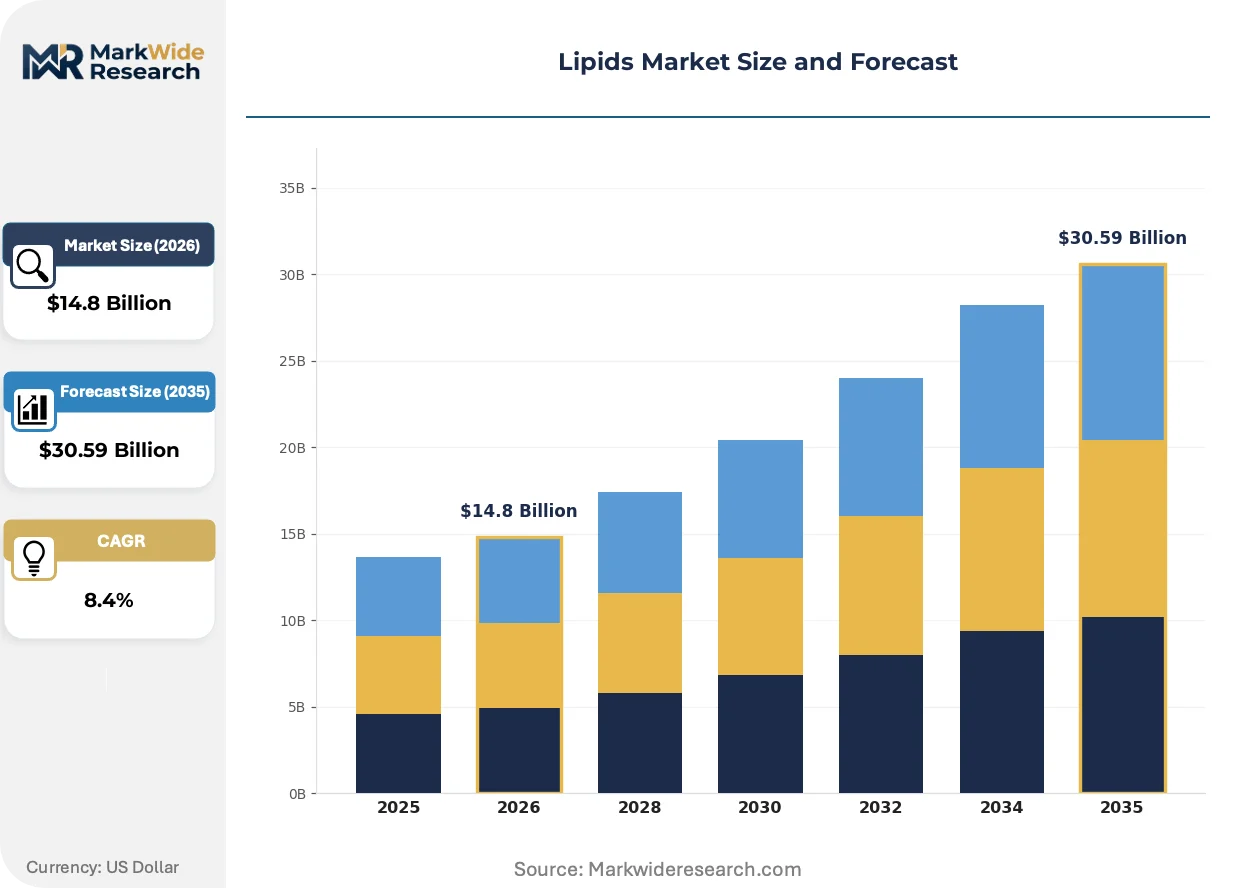
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phospholipids, Sterols, Fatty Acids, Triglycerides, Glycolipids Application: Food & Beverage, Cosmetics, Pharmaceuticals, Animal Nutrition, Industrial Lubricants End User: Food Manufacturers, Personal Care Producers, Drug Makers, Feed Formulators, Chemical Companies Form: Liquid, Powder, Granules, Emulsion, Gel |
| Companies Covered | DSM, Croda International Plc, Cargill, Incorporated, Aker BioMarine, Omega Protein Corporation, Archer Daniels Midland Company, Stepan Company, Evonik Industries AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipids Market Strategic Shifts & Innovations
Precision engineering is displacing empirical formulation in the lipids space. The development of advanced therapeutics demands lipids with specific, predictable functionalities, pushing manufacturers toward rational design and synthesis over reliance on natural, variable sources.
Computational chemistry provides tools for designing novel lipids with targeted properties. Pharmaceutical research teams are increasingly adopting molecular dynamics simulations to predict how a lipid will interact within a lipid nanoparticle (LNP) delivery system. This in-silico approach is virtualizing the initial stages of formulation, enabling rapid screening of candidates and reducing reliance on expensive, time-consuming lab work.
Stricter regulatory expectations for excipient quality and supply chain integrity are enforced by the FDA and EMA. These agencies demand comprehensive data on raw material provenance, synthesis pathways, and impurity profiles for lipids in parenteral drugs. This requirement elevates compliance costs for suppliers of synthetic lipids, forcing investment in enhanced quality management systems.
Co-development partnerships are becoming the preferred engagement model between biopharmaceutical firms and lipid suppliers. This collaborative approach involves custom synthesis of proprietary lipids for specific drug delivery systems, replacing transactional procurement of off-the-shelf products. The trend is most visible within cell and gene therapy sectors concentrated in the United States and Germany.
Lipids Market Segmentation
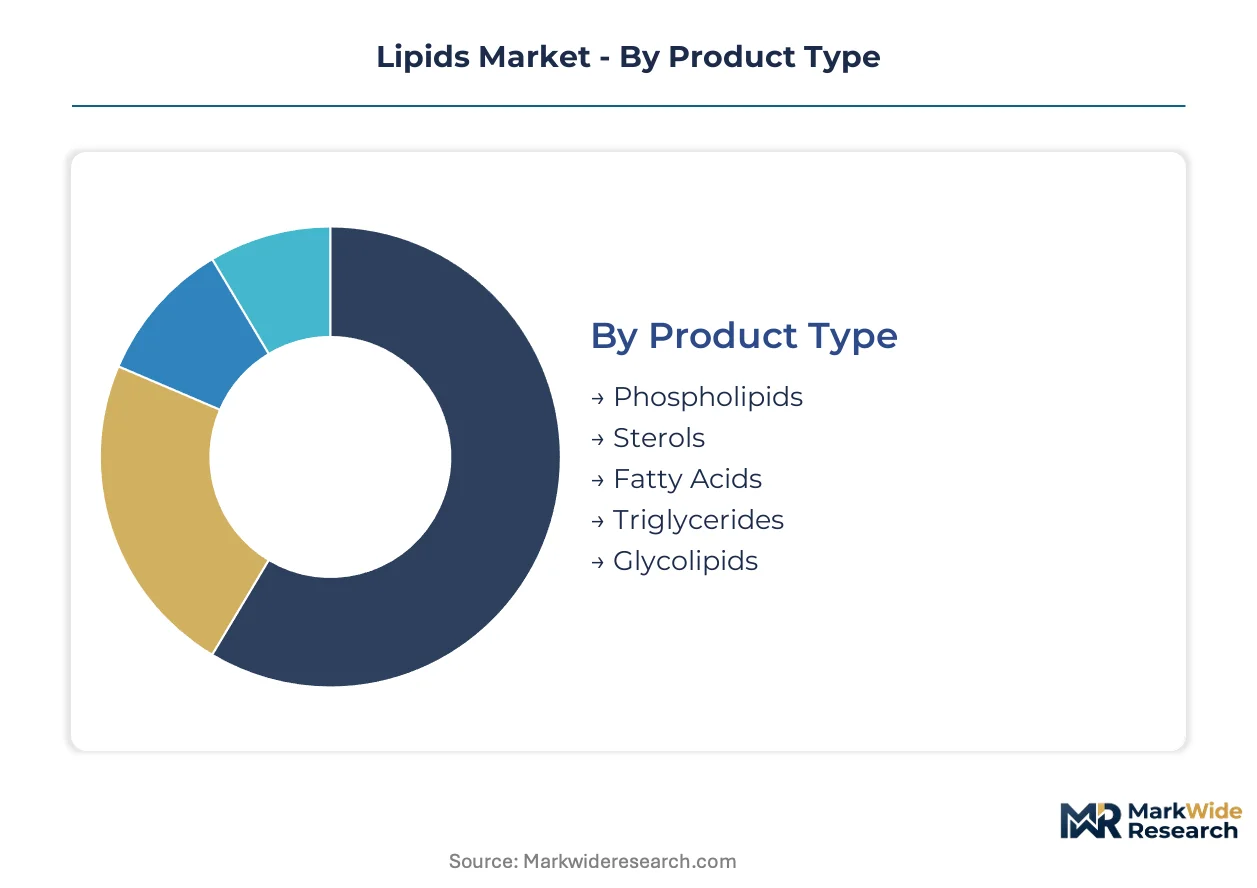
The lipids market segmentation provides a granular view of its diverse product landscape and application areas. Understanding these distinct segments is crucial for identifying where value creation is concentrating and where specialized requirements drive innovation. This detailed breakdown highlights the varying technical demands and regulatory compliance needs across the industry.
Product Type:
The after-sales-service intensity for different lipid product types varies significantly, reflecting their complexity and application demands.
- Phospholipids:These complex lipids are critical for advanced drug delivery systems, particularly in lipid nanoparticle formulations for mRNA vaccines and cell therapies. Demand concentrates in biopharmaceutical manufacturing hubs within the United States and Germany due to stringent purity requirements.
- Triglycerides:Comprising three fatty acids linked to a glycerol backbone, this high-volume segment primarily serves the food and animal nutrition industries. These lipids represent a mature category globally, characterized by lower profit margins compared to specialized pharmaceutical ingredients.
- Sterols:Essential structural components in cell membranes, sterols function as precursors for hormones and vitamins. They are utilized in nutraceutical formulations and some specialized pharmaceutical applications.
- Fatty Acids:Straight-chain hydrocarbons with a carboxyl group, fatty acids are fundamental building blocks in various industrial processes. They find application in personal care products and as dietary supplements.
- Glycolipids:Lipids with attached carbohydrate groups, glycolipids play important roles in cell recognition and signaling pathways. They are investigated for niche applications in cosmetics and targeted drug delivery systems.
By volume, the triglycerides segment leads the market. By growth pace, phospholipids are expanding most quickly.
Application:
The cost tier for lipid applications varies widely, influenced by purity requirements and regulatory compliance.
- Pharmaceuticals:This application demands high-purity, GMP-compliant lipids for advanced drug delivery systems and excipient functions. Demand is rising from mRNA vaccine production and cell therapies in the United States and European Union.
- Food & Beverage:This segment utilizes commodity-grade triglycerides and other lipids for energy, texture, and nutritional enhancement in a wide array of products. It represents a high-volume, lower-margin category globally.
- Cosmetics:Lipids are integrated into cosmetic formulations for their emollient properties, skin barrier repair, and active ingredient delivery. They are found in various personal care products.
- Animal Nutrition:This application incorporates lipids as crucial energy sources and for essential fatty acid supplementation in animal feeds. It supports livestock and aquaculture health and productivity.
- Industrial Lubricants:Specific lipid derivatives serve as biodegradable alternatives to petroleum-based compounds in industrial lubricant formulations. This reduces environmental impact in machinery operations.
The pharmaceuticals application segment commands higher margins due to stringent specifications. Conversely, food and beverage applications operate on tighter profit margins.
End User:
Supply concentration patterns for lipid end users reflect specialized procurement needs and regulatory landscapes.
- Drug Makers:These manufacturers require highly specialized, GMP-certified lipids for parenteral drug formulations and advanced therapeutics. Their procurement is shifting towards co-development partnerships with lipid suppliers, particularly in the United States and Germany.
- Food Manufacturers:These companies source large volumes of commodity lipids for various product lines, ranging from cooking oils to baked goods. Their procurement emphasizes cost-effectiveness and consistent supply for global production.
- Personal Care Producers:These firms integrate lipids for emollients, emulsifiers, and active ingredient delivery in their cosmetic and personal care products. They focus on cosmetic-grade purity and stability.
- Feed Formulators:These specialists utilize lipids as crucial energy and nutrient sources in animal feeds for livestock and aquaculture. They prioritize bulk availability and nutritional value from suppliers.
- Chemical Companies:These industrial users employ lipids as raw materials for various chemical syntheses and derivative production. They seek cost-efficient and scalable sources for their manufacturing processes.
Market access barriers are highest for drug makers due to strict regulatory requirements. Feed formulators face fewer hurdles regarding product specifications.
Form:
Application versatility for lipids in different forms dictates their utility across diverse industrial and medical sectors.
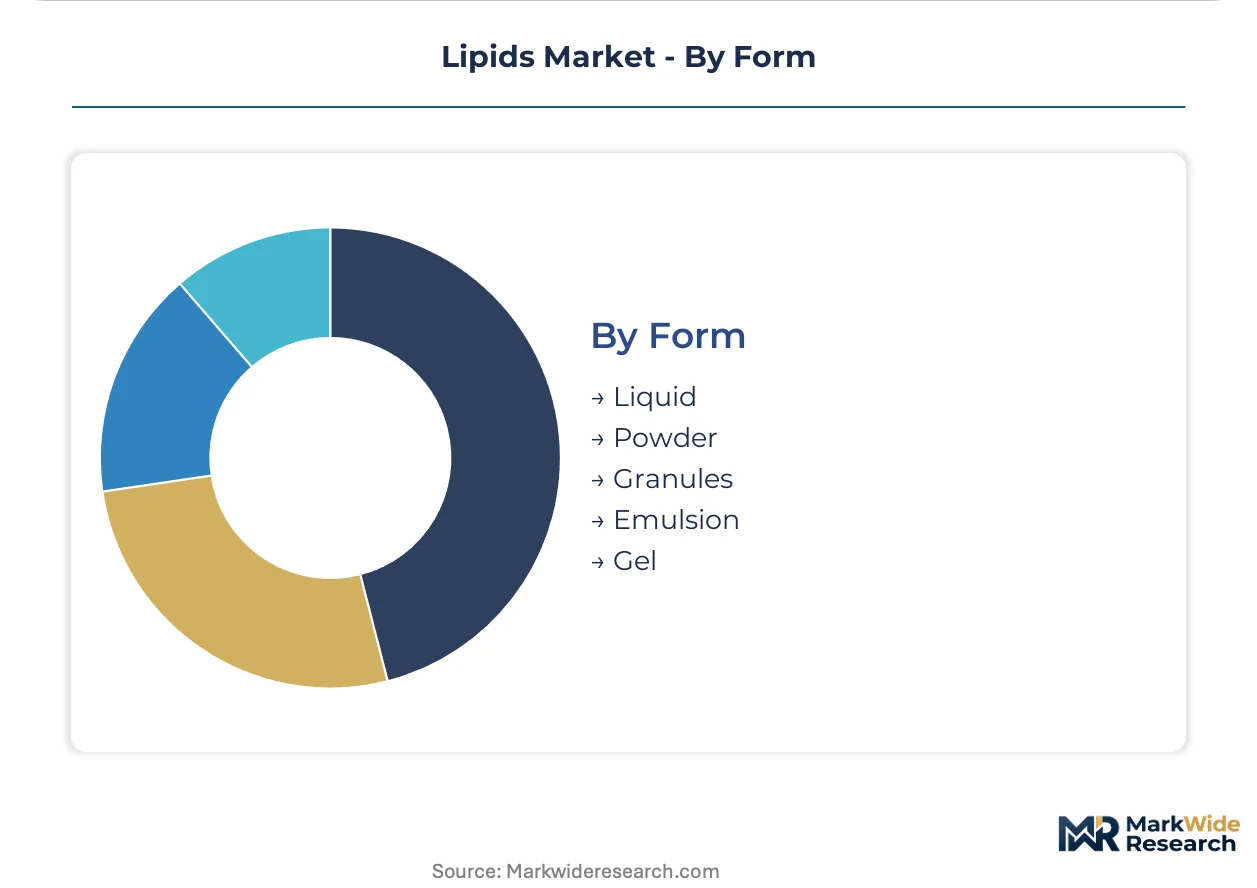
- Liquid:This form offers ease of handling, precise dosing, and excellent miscibility in many formulations. It is common for oils, fatty acids, and some phospholipids across various industries.
- Powder:Providing enhanced stability and simplified storage and transportation, the powder form is highly versatile. It is often preferred for solid dosage forms in pharmaceuticals and dry mix applications in food manufacturing.
- Granules:This form facilitates controlled release mechanisms and improves flowability in solid preparations. It is utilized in dietary supplements and certain pharmaceutical excipients.
- Emulsion:An emulsion enables the uniform dispersion of immiscible liquids, forming stable mixtures. It is critical for parenteral nutrition and topical drug delivery systems.
- Gel:The gel form offers sustained release properties and localized action for active ingredients. It is frequently employed in dermatological and ophthalmic preparations.
The processing complexity is generally lower for liquid and powder forms. Emulsion and gel forms require more specialized formulation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global lipids market exhibits distinct consumption patterns across geographies. While some regions prioritize high-purity lipids for advanced pharmaceutical applications, others maintain a strong demand for commodity-grade triglycerides in food and animal nutrition. This differential in application focus shapes regional investment and regulatory priorities.
United States
Demand for GMP-grade phospholipids and cholesterol escalates with mRNA therapeutics and cell therapies. The US FDA enforces stringent Good Manufacturing Practice (GMP) standards for excipients used in parenteral drugs. Biopharmaceutical manufacturing hubs in Boston and San Francisco drive innovation in novel lipid delivery systems.
Germany
Manufacturing of high-purity synthetic lipids benefits from a robust biopharmaceutical sector and advanced chemical synthesis capabilities. The European Medicines Agency (EMA) requires strict quality control and supply chain transparency for pharmaceutical excipients. Concentrated in regions like Bavaria, specialized lipid suppliers co-develop proprietary formulations with drug makers.
Japan
The market for specialized lipids is propelled by the country's advanced pharmaceutical industry and stringent quality requirements. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) sets rigorous standards for excipient characterization and regulatory filings. Pharmaceutical research clusters in Tokyo and Osaka focus on lipid-based drug delivery for new therapies.
India
Expanding vaccine and biologics manufacturing sectors are driving the need for GMP-compliant lipids. The Central Drugs Standard Control Organization (CDSCO) is strengthening regulatory oversight for pharmaceutical excipients. Production facilities in Hyderabad and Pune are upgrading capabilities to meet global formulation standards.
China
Significant investment in biopharmaceutical production and nutraceutical innovation boosts demand for both high-purity and commodity lipids. The National Medical Products Administration (NMPA) is tightening regulations on pharmaceutical raw materials and excipients. Major chemical manufacturing zones, including those in the Yangtze River Delta, are expanding lipid synthesis capacities.
Lipids Market Key Industry Players
Capability concentration sits with specialized manufacturers focusing on high-purity pharmaceutical lipids; scale advantage sits with large agricultural and chemical conglomerates producing commodity-grade lipids. The market structure is tiered, featuring highly specialized excipient providers, diversified chemical giants, and integrated commodity suppliers. Strategic archetypes include innovation-driven biopharma partners, high-volume industrial suppliers, and niche players with captive raw material sources. Competitive moves involve co-development partnerships to meet stringent regulatory standards and strategic acquisitions to expand lipid portfolios.
Specialization in high-purity lipids is exemplified by Croda International Plc, a company known for manufacturing excipients meeting stringent regulatory standards for drug formulations. BASF SE, a diversified chemical company, occupies a position leveraging extensive chemical synthesis capabilities to produce custom lipids for both industrial and medical clients. Aker BioMarine, a Norwegian company, represents an integrated model, sustaining its market position through a captive supply of krill-derived omega-3 phospholipids, ensuring traceability and quality control.
| Leading Market Players |
|---|
| DSM |
| Croda International Plc |
| Cargill, Incorporated |
| Aker BioMarine |
| Omega Protein Corporation |
| Archer Daniels Midland Company |
| Stepan Company |
| Evonik Industries AG |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Manufacturing high-purity lipids in specialized facilities within the United States and Germany dictates where premium profit pools accumulate across the biopharmaceutical sector. This concentration influences pricing power for advanced drug delivery excipients.
Pricing Analysis
Long-term, contract-based agreements dominate pharmaceutical-grade lipid pricing, reflecting co-development partnerships and stringent regulatory compliance. Price differentiation stems from GMP certification levels and the degree of custom synthesis for proprietary drug delivery systems. Pricing softness runs through commodity triglycerides, driven by high-volume competition in food and animal nutrition applications. Drug makers exhibit lower price sensitivity for high-purity excipients, unlike food manufacturers who prioritize cost-effectiveness.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often support the capital-intensive production of high-purity lipids. Geographic supply concentrates in biopharmaceutical hubs like the United States and Germany, alongside chemical synthesis capabilities in China. The market draws from agricultural inputs such as soybeans and marine sources like krill. Raw material volatility presents a structural supply chain risk. Distribution runs through direct sales channels for specialized pharmaceutical lipids and broader networks for commodity products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lipids market faces a capability scarcity, particularly in specialized chemical engineering required for scaling novel lipid synthesis from lab to GMP-compliant commercial production. This necessitates targeted strategic interventions across the value chain.
For Market Incumbents:
Entrench market position by investing significantly in advanced purification technologies and expanding GMP-compliant manufacturing capacity, especially in the United States and Germany. Secure long-term raw material contracts to mitigate volatility from agricultural and marine sources, defending against margin pressure. Forge deeper co-development partnerships with biopharmaceutical firms, leveraging intellectual property around novel lipid structures. This defends against threats from emerging biosynthesis platforms.
For New Entrants and Emerging Players:
Establish a beachhead in novel lipid development by focusing on proprietary ionizable and cationic lipids for gene therapy applications. Target the Indian biopharma market, which is upgrading its formulation capabilities and requires GMP-compliant lipids. Pursue biosynthesis platforms for sustainable EPA and DHA production, offering a scalable alternative to traditional extraction. Go-to-market via technology licensing agreements with larger pharmaceutical excipient manufacturers.
For Investors and Strategic Acquirers:
Capital is best deployed toward vertically integrated mid-cap specialists possessing proprietary synthesis technologies and robust regulatory compliance for pharmaceutical excipients. The long-term viability favors firms positioned for the sustained shift to high-purity, specialized lipids in advanced drug delivery. Target acquisition profiles should emphasize companies with established co-development partnerships and strong intellectual property. The signal to watch is a consistent increase in FDA and EMA approvals for lipid nanoparticle-based therapeutics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for GMP Lipids | Addresses the escalating demand from mRNA vaccine production and cell therapies in the United States. |
| Co-development Partnerships with Biopharma | Secures long-term contracts and integrates lipid suppliers into novel drug delivery system development. |
| Investment in Biosynthesis R&D | Offers a sustainable and scalable alternative for high-value lipid production, reducing raw material volatility. |
| Acquisition of Purification Technology | Enhances the purity levels required for parenteral drugs, meeting stringent FDA and EMA standards. |
| Strengthening Supply Chain Traceability | Ensures compliance with regulatory mandates for excipient provenance, particularly for global biopharmaceutical manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, and R&D directors at lipid manufacturers, then refined. This involved extensive interviews and validation against secondary sources like FDA filings, EMA submissions, and industry association reports. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Demand-supply balance was meticulously assessed across the analysis window, integrating historical trends and anticipated market shifts. Segmentation dimensions modeled included product type, application, end user, form, and regional regulatory clusters. Compound annual growth rates were derived from a synthesis of historical data and projected shifts in technology adoption. Key forecast inputs included mRNA vaccine pipeline developments and cell therapy growth rates.
Sensitivities concentrate around evolving regulatory frameworks from agencies like the FDA and EMA, alongside raw material price fluctuations. Forecasts reflect assumptions regarding biopharmaceutical R&D success rates and market adoption of advanced therapies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Starch Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
United States Corn Glucose Market
Ingredients
Campesterol Market
Ingredients
Hydrogenated Starch Market
Ingredients
Carotenes Market
Ingredients
Self-Rising Flour Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Beverage Ingredients Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Fig Ingredient Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Animal and Marine Fats and Oils Market