
 Animal and Marine Fats and Oils Market | 2026-2036
Animal and Marine Fats and Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Animal and Marine Fats and Oils Market Outlook
Skilled rendering technicians and marine lipid chemists is reorganizing output capacity across the value chain, particularly in wet rendering and supercritical fluid extraction lines. Cargill, Incorporated leverages its integrated oilseed and animal fat infrastructure to secure feedstock flows across North American protein processing clusters. JBS S.A. anchors South American tallow supply through its beef slaughterhouse network, converting fresh offal into industrial-grade inputs within hours. Darling Ingredients Inc. competes on collection density, operating rendering facilities proximate to poultry and pork processors to minimize raw material spoilage.
Animal and marine fats and oils encompass triglyceride-rich lipid matrices derived from terrestrial livestock adipose tissue and aquatic species, typically containing fatty acid profiles ranging from saturated C16:0 palmitic acid in tallow to long-chain omega-3 EPA and DHA concentrates in cold-water fish oil; these materials serve as foundational inputs for food formulation, oleochemical synthesis, and nutritional supplementation. Tallow and lard occupy mature, price-sensitive positions in soap and biodiesel applications where margin compression is routine, while fish oil concentrates command premium positioning in pharmaceutical-grade omega-3 distillates. Supercritical fluid extraction is gaining structural traction among personal care brands seeking solvent-free marine lipid fractions, though conventional rendering still dominates total volume throughput.
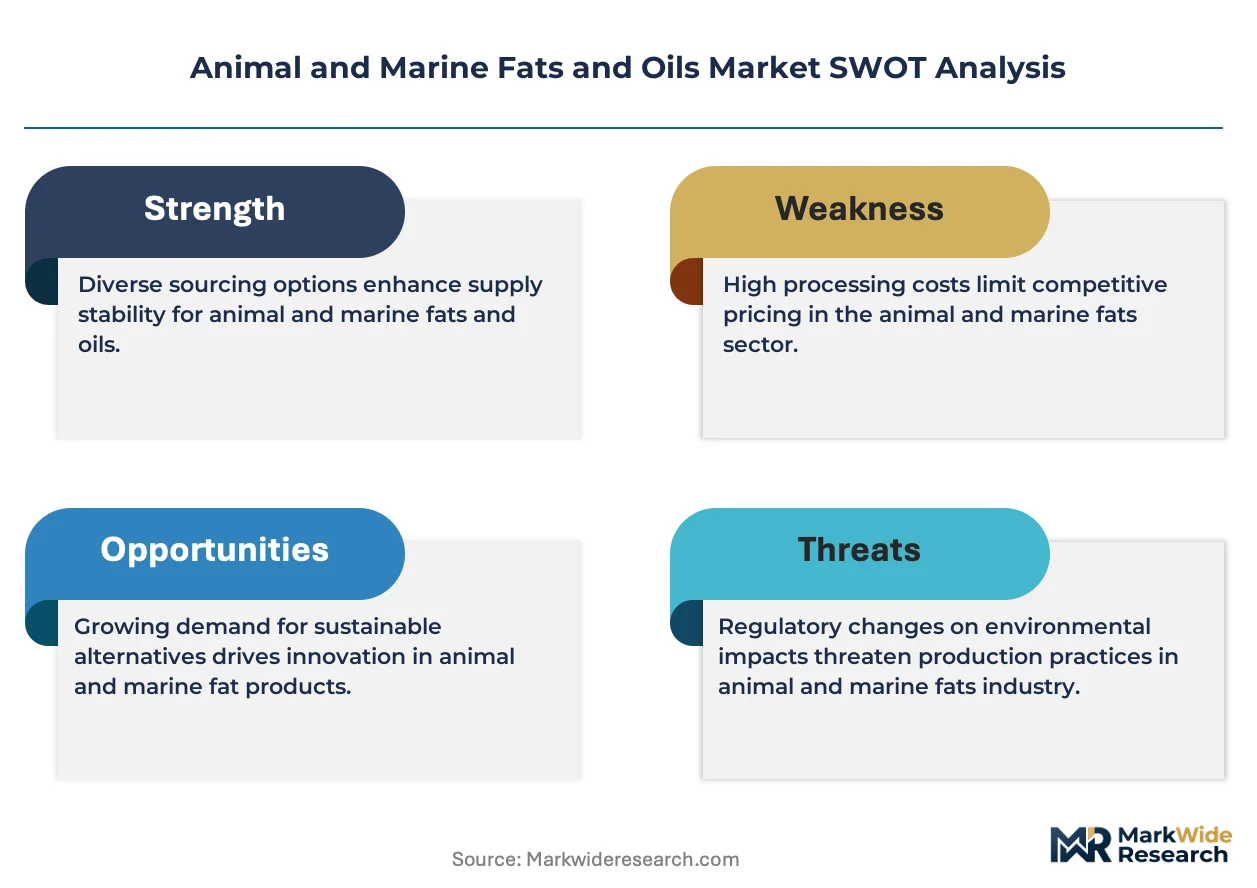
The FDA maintains Current Good Manufacturing Practice oversight for dietary supplement fish oil products under 21 CFR Part 111, while the EPA regulates discharges from rendering facilities under Clean Water Act permits. EFSA sets maximum contaminant thresholds for dioxins and PCBs in marine oils sold within the European Union, directly conditioning import eligibility for non-EU processors. Stakeholders must monitor tightening maximum residue limits for persistent organic pollutants, as these thresholds will determine which extraction and refining investments preserve market access.
Market Dynamics
Supercritical fluid extraction is compressing margins for conventional rendering operations while concentrating premium marine lipid supply among solvent-free processors. Wet rendering capacity expansion in Indonesia and Brazil is tightening feedstock competition for tallow and poultry fat collectors.
Growth Catalysts
- Aquaculture feed omega-3 enrichment mandates:Norwegian and Chilean salmon farming regulations now require minimum EPA/DHA inclusion in grower diets. Fish oil inclusion rates in compound feeds are rising accordingly.
- EU F-Gas Regulation phase-down:Refrigerant restrictions on hydrofluorocarbons are accelerating investment in heat-pump rendering systems across Dutch and Danish processing clusters.
- REACH compliance-driven purification upgrades:European oleochemical buyers are demanding certified low-PCB marine oil fractions. Supercritical CO2 extraction lines are capturing this specification premium.
Market Restraints
- Crude fish oil price volatility:Peruvian anchovy quota fluctuations transmit directly to omega-3 concentrate input costs. Margins on 18/12 standard-grade products compress during El Niño events.
- Indonesian downstream concentration:Wilmar International controls a dominant share of Asian refining capacity. Smaller collectors face captive pricing for CPO-admixed tallow streams.
- Plant-based lipid substitution in soaps:Palm kernel olein and coconut oil fractions are capturing mid-tier personal care formulations previously served by beef tallow.
Strategic Opportunities
- Pharmaceutical-grade EPA/DHA concentrates:Prescription omega-3 therapies are expanding indication scope. Lipid chemists with GMP-certified molecular distillation capacity can access this reimbursement-backed channel.
- Indian aquaculture feed expansion:Andhra Pradesh and Gujarat shrimp farming clusters lack local fish oil refining. Import substitution through coastal supercritical extraction investments addresses this supply gap.
- EU Green Deal biorefinery incentives:Horizon Europe funding streams support integrated animal fat-to-biodiesel and oleochemical complexes. Combined heat and power integration improves project IRRs.
Industry Challenges
- Marine lipid chemist scarcity:Supercritical extraction and molecular distillation operations require specialized process engineering talent. Training pipelines lag capacity expansion timelines in Vietnam and Ecuador.
- Multi-jurisdictional contaminant testing:EFSA dioxin limits, FDA heavy metal action levels, and CFDA new dietary ingredient notifications create overlapping compliance burdens for omega-3 concentrate exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal and Marine Fats and Oils Market |
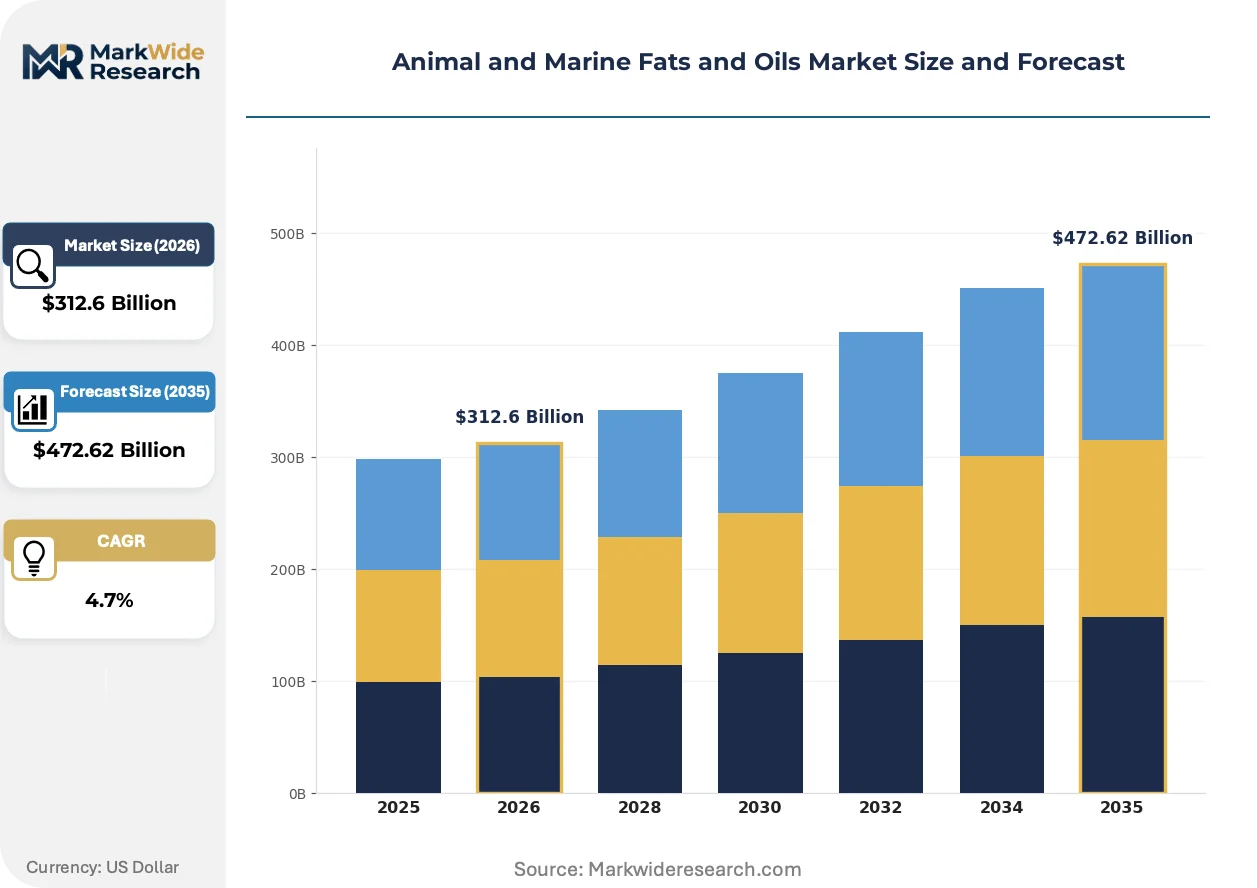
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Lard, Tallow, Seal Oil Application: Animal Feed, Cosmetics, Food & Beverage, Industrial Lubricants End User: Pet Food Manufacturers, Pharmaceutical Companies, Personal Care Brands, Food Processors Processing Method: Rendering, Cold Pressing, Supercritical Fluid Extraction, Refining |
| Companies Covered | Wilmar International Limited, Tyson Foods, Inc., Cargill, Incorporated, Ten Kate Vetten BV, JBS S.A., Bunge Limited, Darling Ingredients Inc., Baker Commodities Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal and Marine Fats and Oils Market Strategic Shifts
Processing technology differentiation is fragmenting the competitive landscape between solvent-free premium processors and cost-optimized conventional renderers. Regulatory contaminant thresholds are accelerating capital deployment toward purification-intensive extraction architectures.
Supercritical CO2 extraction systems are displacing hexane-based marine oil fractionation in pharmaceutical-grade omega-3 production. Nordic nutraceutical contract manufacturers are retrofitting molecular distillation lines with integrated supercritical finishing stages. This displacement is compressing commodity-grade fish oil margins while expanding certified solvent-free product premiums.
EFSA's tightening maximum residue limits for dioxins and PCBs in marine oils are forcing import qualification restructuring. Non-EU processors must demonstrate laboratory-certified contaminant profiles below 2.0 pg TEQ/g for market access. Peruvian and Moroccan concentrate exporters are investing in activated carbon and short-path distillation to preserve European eligibility.
Salmon farming operators are consolidating procurement around long-term offtake agreements with specified omega-3 content guarantees. Spot market fish oil purchasing is retreating in favor of 12-24 month contracts with certified sustainability credentials. This preference shift is most visible in Norwegian and Scottish aquaculture clusters, where Marine Stewardship Council chain-of-custody documentation now gates supplier qualification.
Animal and Marine Fats and Oils Market Segmentation
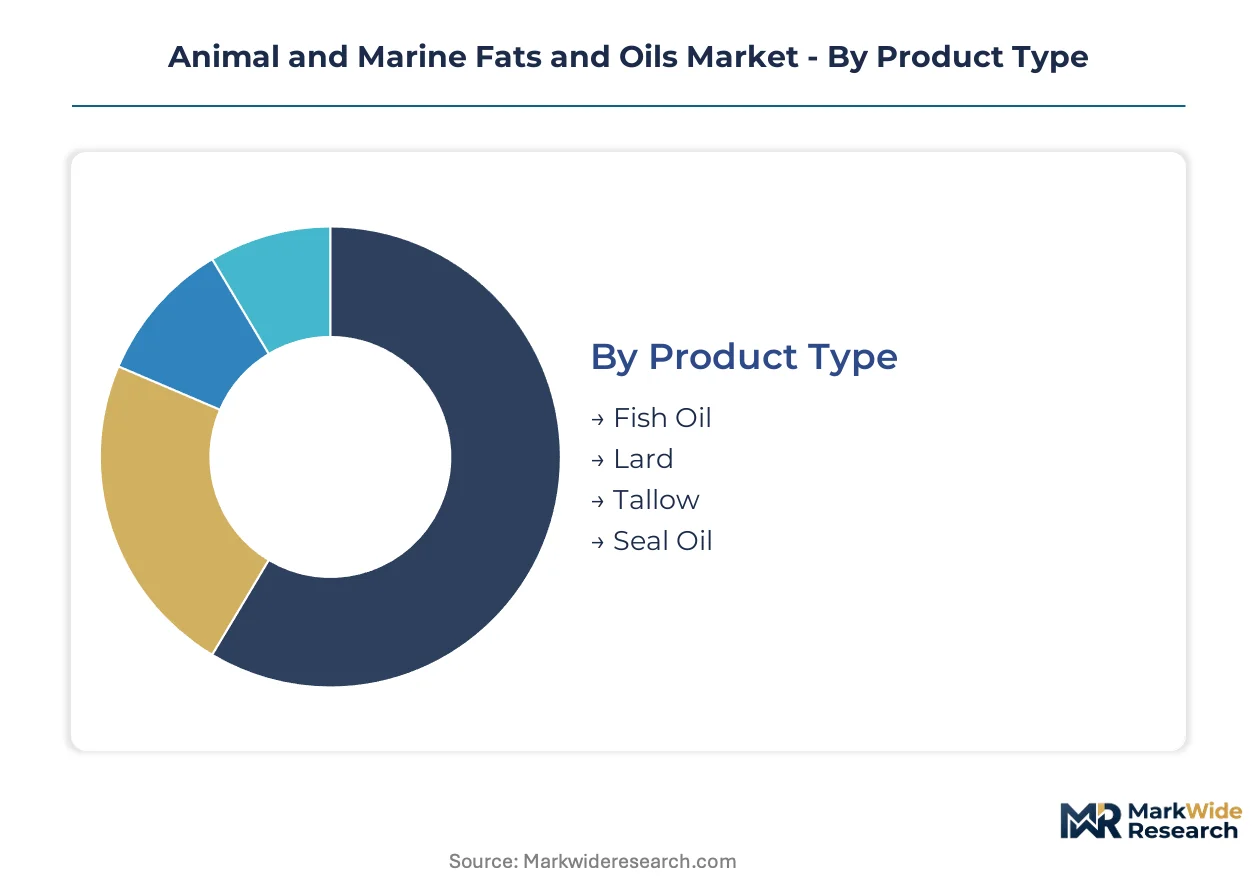
Segmentation in animal and marine fats and oils reveals divergent margin structures and regulatory exposure across lipid categories. Product type determines feedstock sourcing economics while processing method governs contaminant compliance costs and end-market access.
Product Type:
Substitution pressure from plant-based lipids concentrates most intensely on tallow and lard, while marine oils defend positioning through irreplaceable omega-3 functionality.
- Fish Oil:Triglyceride matrix containing 18-33% EPA and 10-25% DHA by weight, with fatty acid profiles varying by species origin. Norwegian salmon feed compounders are locking in 24-month offtake agreements with Marine Stewardship Council chain-of-custody requirements. EFSA dioxin thresholds below 2.0 pg TEQ/g are disqualifying non-certified Peruvian processors from EU pharmaceutical channels.
- Lard:Rendered swine adipose tissue with 40% saturated fatty acids dominated by C16:0 palmitic and C18:0 stearic fractions. Mexican and Polish food processors use lard in traditional bakery applications where crystallization behavior governs product texture. REACH compliance costs are accelerating consolidation among European renderers serving personal care oleochemical buyers.
- Tallow:Bovine-derived lipid with higher melting point than lard due to elevated stearic acid content; standard grades feed soap and biodiesel applications where palm kernel olein substitution is eroding volume.
- Seal Oil:Marine mammal lipid with distinctive omega-3 positional distribution on sn-1/sn-3 glycerol carbons; Canadian and Norwegian harvest quotas restrict commercial scale.
Tallow anchors the volume base in commodity oleochemical applications while fish oil gains share at the steepest rate through aquaculture feed mandates and pharmaceutical-grade concentrate demand.
Application:
Application segmentation traces cost tier stratification, with food and beverage commanding specification premiums and industrial lubricants competing on price against synthetic alternatives.
- Animal Feed:Compound feed inclusion rates for aquaculture species now carry regulatory minimums for long-chain omega-3 content. Chilean salmon farming regulations mandate EPA/DHA thresholds that pull fish oil volumes upward regardless of crude price spikes.
- Cosmetics:Formulators specify supercritical CO2-extracted fractions for solvent-free positioning in premium skincare. ECHA REACH registration requirements for residual hexane traces are accelerating displacement of conventional extraction.
- Food & Beverage:Bakery and confectionery applications in Mexico, Poland, and Vietnam specify lard for shortening functionality where crystallization kinetics determine finished product mouthfeel.
- Industrial Lubricants:Tallow-derived base stocks compete with Group II mineral oils and polyalphaolefins; biodegradability specifications in EU machinery directives provide residual demand support.
Industrial lubricants anchor the volume base through tallow fatty acid displacement of petroleum derivatives while cosmetics gains share fastest on supercritical extraction premiums.
End User:
End user segmentation maps customer type to procurement sophistication, with pharmaceutical companies imposing the most stringent contaminant documentation requirements.
- Pet Food Manufacturers:Palatability enhancement drives poultry fat and tallow inclusion in dry kibble formulations; FDA feed safety regulations govern rendering facility qualification.
- Pharmaceutical Companies:Prescription omega-3 therapies require GMP-certified molecular distillation with FDA 21 CFR Part 111 compliance; dioxin and PCB certificates must accompany every batch.
- Personal Care Brands:Clean-label positioning favors certified solvent-free marine lipid fractions; EU cosmetic regulation (EC) No 1223/2009 governs impurity disclosure.
- Food Processors:Traditional applications in Mexican and Polish baking specify lard for texture control; Indonesian and Malaysian processors blend tallow with palm stearin for cost optimization.
Food processors anchor the volume base through mature bakery and frying applications while pharmaceutical companies expand fastest on prescription EPA/DHA therapy approvals.
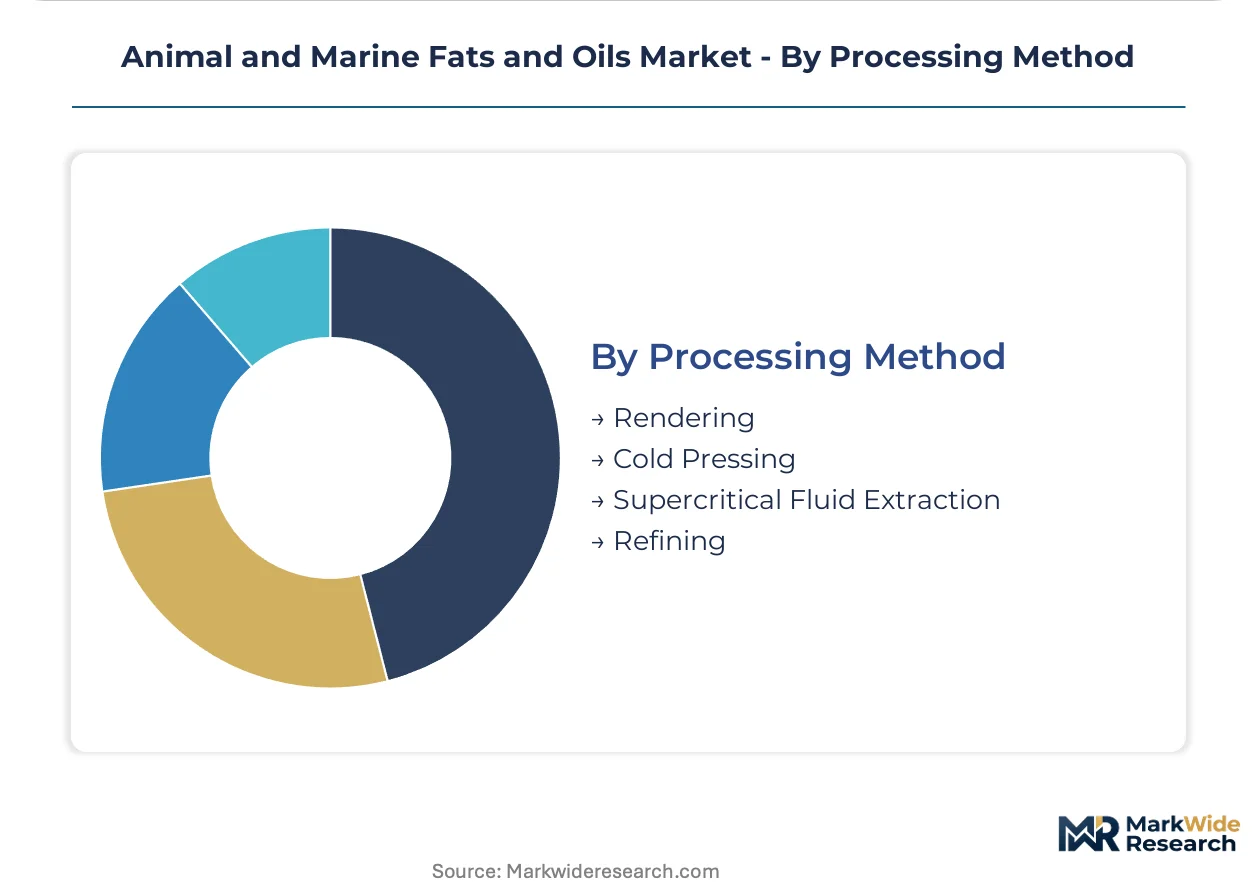
Processing Method:
Processing method segmentation tracks supply concentration, with supercritical fluid extraction consolidating among specialized equipment operators and conventional rendering fragmenting across collector networks.
- Rendering:Wet rendering dominates tallow and poultry fat production in Brazil and Indonesia; heat integration with biodiesel plants improves project economics under EU Green Deal biorefinery incentives.
- Cold Pressing:Mechanical extraction preserves heat-sensitive fatty acid profiles in specialty marine oils; Moroccan and Peruvian artisanal operations serve niche nutraceutical buyers.
- Supercritical Fluid Extraction:CO2-based fractionation eliminates hexane residues for EU REACH compliance and pharmaceutical-grade certification. Nordic contract manufacturers are retrofitting molecular distillation lines with integrated supercritical finishing stages.
- Refining:Bleaching, degumming, and deodorization steps upgrade crude fish oil to food-grade specifications; activated carbon treatment removes dioxins for EFSA threshold compliance.
Rendering anchors the volume base through established wet processing infrastructure while supercritical fluid extraction climbs fastest on solvent-free specification premiums and REACH-driven purification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's tightening contaminant thresholds for dioxins and PCBs are reshaping import qualification across European ports, while Indonesian downstream concentration and Brazilian wet rendering expansion are redrawing feedstock competition maps.
Indonesia
Aquaculture feed compounders in Surabaya and Medan are absorbing rising fish oil volumes for shrimp and tilapia diets. The national downstream regulator enforces halal certification and food safety standards for marine oil refining. Wilmar International anchors refining capacity in Jakarta-Bogor-Depok, converting crude tallow and palm oil admixtures into export-ready oleochemical streams.
Norway
Salmon farming operators in Bergen and Trondheim are locking in 24-month offtake agreements with specified EPA/DHA content guarantees. The Norwegian Food Safety Authority implements EU-aligned maximum residue limits for persistent organic pollutants in feed-grade marine oils. Supercritical CO2 extraction facilities in Stavanger are capturing solvent-free specification premiums from pharmaceutical-grade omega-3 buyers.
United States
Pet food manufacturers in Kansas and Iowa are expanding poultry fat inclusion in dry kibble formulations for palatability enhancement. The FDA maintains Current Good Manufacturing Practice oversight for dietary supplement fish oil products under 21 CFR Part 111. Darling Ingredients operates rendering facilities proximate to Midwestern pork and poultry processors to minimize raw material spoilage.
Brazil
Beef slaughterhouses in São Paulo and Mato Grosso are converting fresh offal into industrial-grade tallow within hours of harvest. ANVISA governs contaminant thresholds for imported marine oils used in pharmaceutical and nutraceutical applications. JBS S.A. anchors South American tallow supply through its integrated protein processing network.
India
Shrimp farming clusters in Andhra Pradesh and Gujarat lack local fish oil refining capacity for omega-3 enriched grower diets. The FSSAI sets maximum limits for heavy metals and pesticide residues in edible oils and fats. Coastal supercritical extraction investments in Visakhapatnam are targeting import substitution for aquaculture feed formulations.
Animal and Marine Fats and Oils Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with solvent-free supercritical processors commanding premium positioning while conventional wet renderers compete on feedstock collection density and scale. The market structure fragments across three tiers: integrated agribusiness conglomerates with captive protein processing networks, specialized rendering and oleochemical operators focused on collection logistics, and pharmaceutical-grade nutraceutical contract manufacturers with GMP-certified purification capacity. Dominant competitive moves include backward integration into slaughterhouse and fishing fleet operations to secure raw material flows, and geographic expansion toward aquaculture clusters in Southeast Asia and Latin America.
Among Asia-Pacific-based downstream refiners, Wilmar International Limited exemplifies the integrated conglomerate archetype with dominant positioning in regional oleochemical flows. Cargill, Incorporated and JBS S.A. represent the protein-processing-anchored tier, leveraging slaughterhouse network density to secure tallow and poultry fat feedstocks. Darling Ingredients Inc. occupies a position within the specialized rendering tier, with facility placement strategies focused on minimizing raw material spoilage through proximity to protein processors.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Tyson Foods, Inc. |
| Cargill, Incorporated |
| Ten Kate Vetten BV |
| JBS S.A. |
| Bunge Limited |
| Darling Ingredients Inc. |
| Baker Commodities Inc. |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
EFSA's tightening dioxin thresholds gate both European market access and price stratification across marine oil grades simultaneously. Non-certified Peruvian processors face exclusion from pharmaceutical channels while Nordic supercritical operators capture solvent-free premiums. Buyers segment procurement between long-term offtake contracts with chain-of-custody documentation and spot-market commodity purchases.
Pricing Analysis
Peruvian crude fish oil trades at spreads to Norwegian refined concentrates reflecting contaminant certification tiers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications tracks EFSA compliance investment and molecular distillation capacity. Pricing pressure stems from El Niño-driven anchovy quota volatility compressing margins on 18/12 standard products. Feed compounders exhibit highest price sensitivity, while pharmaceutical buyers prioritize batch-certified purity over cost.
Supply Chain Analysis
Indonesia and Brazil anchor wet rendering capacity for tallow and poultry fat, while Peru and Morocco concentrate marine oil extraction. Raw material flows draw from JBS slaughterhouse networks, Darling Ingredients collection density, and Peruvian anchovy fishing fleets. Single-source vulnerability runs through Wilmar International's dominance of Asian downstream refining. Distribution runs through oleochemical traders in Rotterdam and Singapore before reaching aquaculture feed mills and pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal and marine fats and oils incumbents face substitution defense against palm kernel olein and coconut oil fractions capturing personal care formulations. Incumbents must navigate plant-based lipid displacement while securing omega-3 functionality premiums in aquaculture and pharmaceutical channels.
For Market Incumbents: Secure backward integration into slaughterhouse operations to lock tallow feedstock flows against Brazilian and Indonesian wet rendering expansion. Invest in GMP-certified molecular distillation capacity to access prescription EPA/DHA therapy reimbursement channels. Defend against palm oil substitution by emphasizing halal certification and crystallization performance in traditional bakery applications. For New Entrants and Emerging Players: Anchor in Indian coastal supercritical extraction to serve Andhra Pradesh and Gujarat shrimp farming clusters lacking local fish oil refining. Target pharmaceutical-grade omega-3 concentrates where EFSA compliance barriers limit incumbent field. Pursue solvent-free positioning through CO2 extraction to capture REACH-driven specification premiums from European personal care brands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rendering networks lacking supercritical upgrade capital. Long-term viability hinges on aquaculture feed mandate durability and prescription omega-3 therapy expansion. Watch for El Niño frequency intensification as inflection indicator for crude fish oil input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughterhouse Operations | JBS and Cargill leverage protein processing networks to secure fresh offal-to-tallow conversion within hours. |
| Supercritical CO2 Extraction Capacity Addition | Nordic contract manufacturers retrofit molecular distillation lines to capture REACH-compliant solvent-free premiums. |
| Long-term Offtake Agreements with Aquaculture Operators | Norwegian salmon farmers lock 24-month contracts with Marine Stewardship Council chain-of-custody requirements. |
| GMP-Certified Molecular Distillation Investment | Pharmaceutical-grade EPA/DHA concentrate producers meet FDA 21 CFR Part 111 and EFSA dioxin thresholds. |
| Geographic Expansion to Coastal India | Supercritical extraction investments in Visakhapatnam address Andhra Pradesh shrimp feed import substitution gaps. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across rendering facility managers, marine lipid chemists, aquaculture feed compounders, and pharmaceutical procurement officers. Secondary validation drew from FDA 21 CFR filings, EFSA contaminant threshold updates, ANVISA pharmaceutical import regulations, and customs trade data on crude fish oil flows. Bottom-up capacity assessments triangulated against top-down consumption estimates across the analysis window.
Across the modeling period, volume and value outputs segmented by product type, processing method, application, and end-user archetype. CAGRs derived from trend extrapolation of aquaculture feed inclusion rates, REACH compliance investment cycles, and supercritical extraction adoption curves. Forecast inputs incorporated El Niño frequency patterns and EU Green Deal biorefinery incentive allocation.
Material uncertainties — anchovy quota volatility, F-Gas Regulation refrigerant phase-down timelines, and plant-based lipid substitution velocity — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory threshold stability and salmon farming EPA/DHA mandate durability. Recalibration cycles align with material shifts in Peruvian fishing season outcomes and EFSA maximum residue limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Natural Gum Market
Ingredients
North America Soy Protein Market
Ingredients
Baobab Powder Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
South America Lipid Market
Ingredients
Vegetable Glycerin Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Glucuronolactone Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Bean Pasta Market
Ingredients
Fermented Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
Brewer's Yeast Market
Ingredients
US Ingredients Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Animal-Derived Ingredients Market