
 Self-Rising Flour Market | 2026-2036
Self-Rising Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Rising Flour Market Analytics
Private-label co-manufacturing revenue is fragmenting as branded millers reclaim production capacity for captive use. Ardent Mills leverages its vertically integrated grain elevator network to secure cost-advantaged wheat supply. King Arthur Baking Company differentiates through premium positioning and direct-to-consumer channel control.
Self-rising flour combines refined wheat flour with leavening agents—typically baking powder and salt—at precise ratios, eliminating separate ingredient measurement for commercial and home baking applications. White self-rising flour occupies the dominant volume position due to its neutral flavor profile and broad recipe compatibility, while gluten-free self-rising flour captures accelerated growth as celiac-sensitive consumers and clean-label formulations expand addressable demand. Organic self-rising flour commands premium shelf placement and margin pools, though certification requirements constrain supply elasticity.
The FDA governs enriched flour standards under 21 CFR 137, while the USDA Organic seal governs certified organic product claims; in Europe, EFSA evaluates novel food ingredients and health claim substantiation for fortified formulations. These frameworks elevate compliance costs for new entrants but protect incumbent quality reputations. Stakeholders must monitor evolving fortification thresholds and emerging state-level labeling requirements that could reshape formulation economics and regional competitive balance.
Market Dynamics
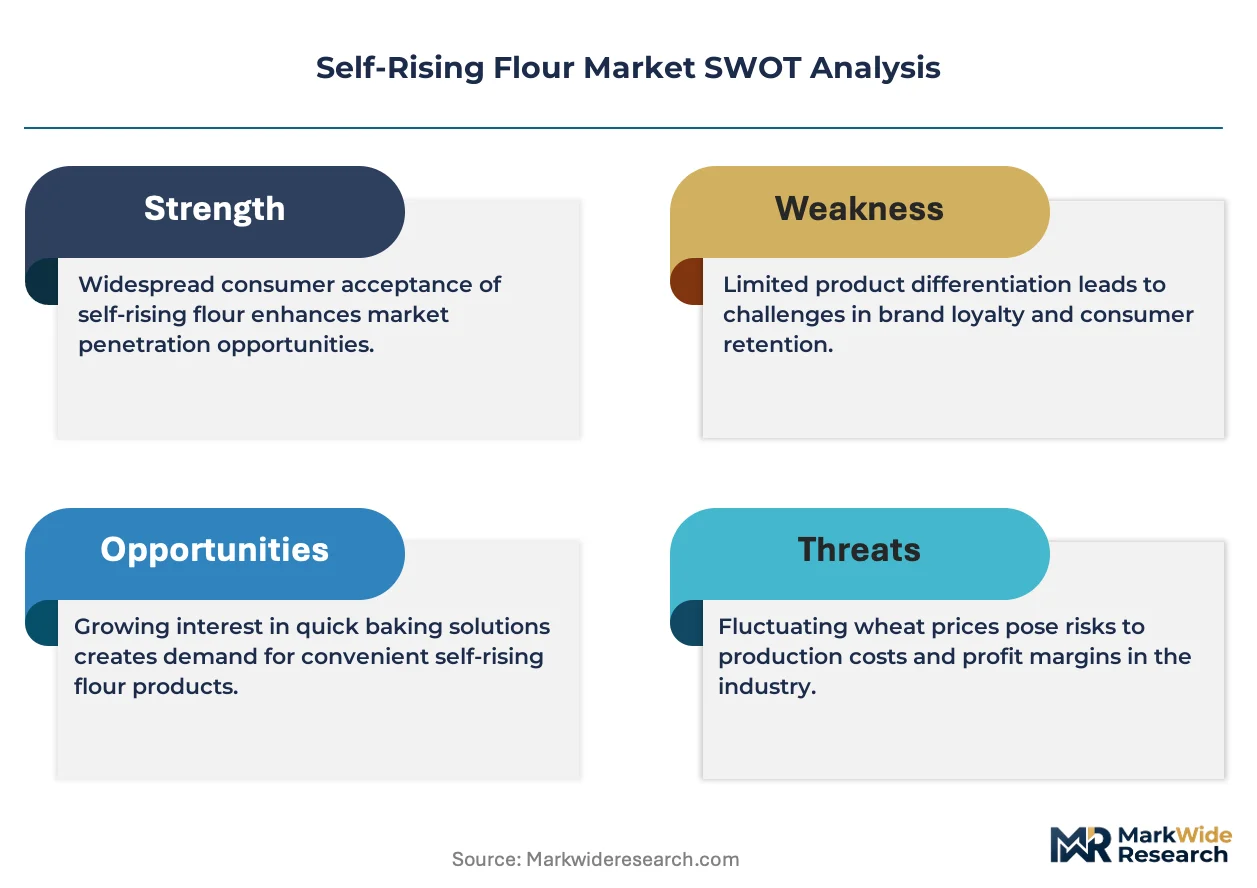
Fortification mandates from the FDA and EFSA are compressing formulation flexibility while fragmenting competitive advantage across North American and European milling operations. This regulatory pressure is forcing capital reallocation toward compliance infrastructure and certified organic supply chains.
Growth Catalysts
- Convenience-Driven Home Baking:Post-pandemic kitchen habits have institutionalized scratch-cooking behaviors, with prepared flour formulations capturing permanent shelf space in US and UK retail channels.
- 21 CFR 137 Enrichment Standards:FDA-mandated nutrient fortification creates barrier-protected demand for compliant domestic millers against lower-standard imports.
- Gluten-Free Formulation Advances:Rice, almond, and tapioca-based self-rising blends are displacing wheat-only portfolios as celiac-sensitive consumers expand addressable demand pools.
Market Restraints
- Wheat Price Volatility:Input cost swings tied to Black Sea supply disruptions and drought cycles in the US Great Plains compress margin predictability for non-integrated millers.
- Supply Concentration Risk:North American grain elevator networks and milling infrastructure cluster in the US Midwest, creating geographic vulnerability to localized weather or logistics shocks.
- Clean-Label Substitution Pressure:Consumer preference for unprocessed ingredients threatens prepared flour categories as home bakers return to separate leavening measurement.
Strategic Opportunities
- Underpenetrated European Organic Channels:German and French retail chains show shelf-space expansion for USDA Organic and EU Organic dual-certified self-rising SKUs with 40-60% price premiums.
- Direct-to-Consumer Subscription Models:Specialty millers bypass traditional grocery slotting fees through recipe-curated flour deliveries targeting committed home bakers.
- EFSA Novel Food Pathway:Probiotic-fortified and protein-enriched self-rising formulations can access differentiated health claim positioning pending substantiation approval.
Industry Challenges
- Certification Timeline Compression:USDA Organic and Non-GMO Project verification cycles extend 12-18 months, delaying product launches against faster conventional competitors.
- Legacy Equipment Retrofit Costs:Segregated production lines for gluten-free SKUs require dedicated milling and packaging infrastructure that strains mid-capitalization millers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Rising Flour Market |
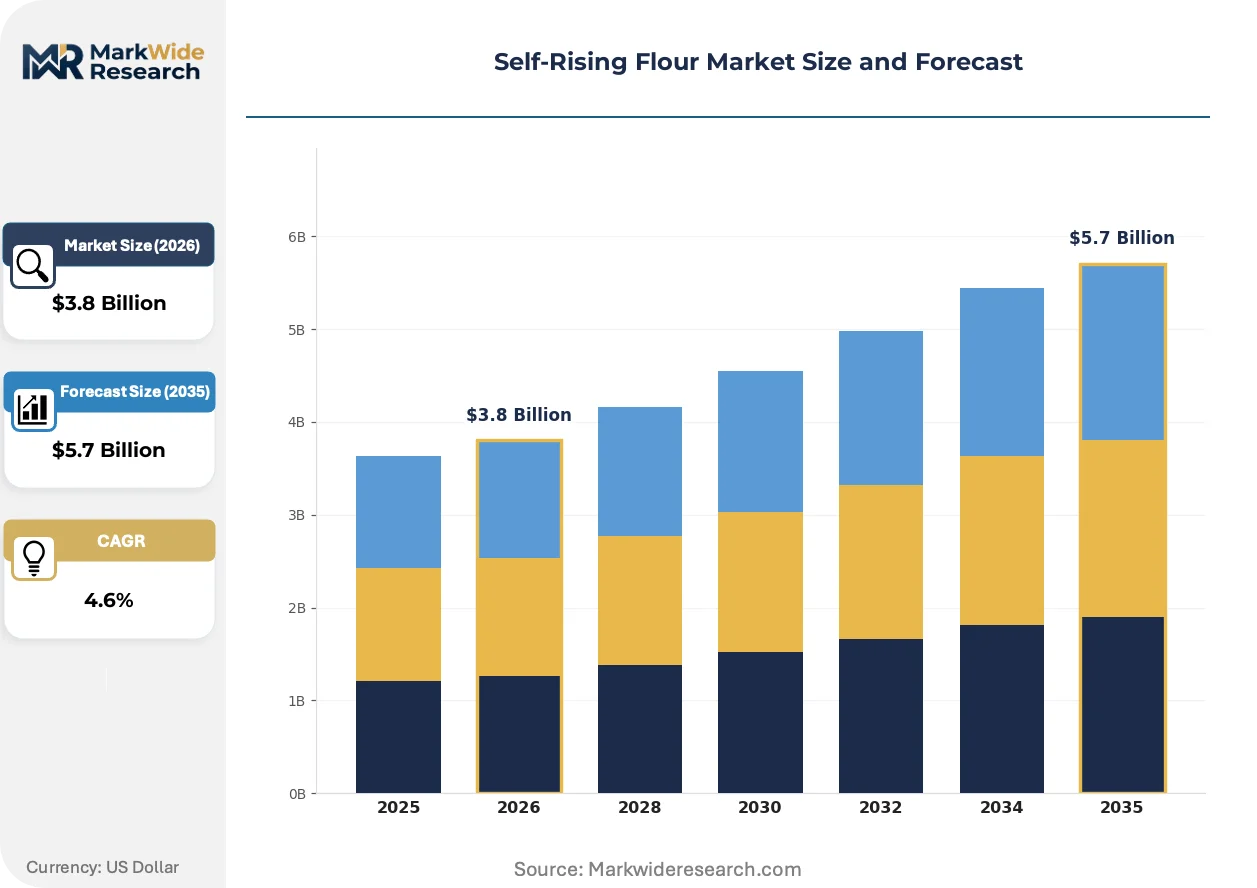
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Self-Rising Flour, Whole Wheat Self-Rising Flour, Gluten-Free Self-Rising Flour, Organic Self-Rising Flour End Use: Bakeries, Home Baking, Food Manufacturing, Restaurants Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores Packaging Type: Bags, Boxes, Bulk Packaging, Individually Wrapped |
| Companies Covered | Ardent Mills, The J.M. Smucker Company, General Mills Inc., Bob's Red Mill Natural Foods Inc., Conagra Brands Inc., Archer Daniels Midland Company, King Arthur Baking Company, Associated British Foods plc, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Rising Flour Market Evolving Landscape
Formulation science and distribution architecture are converging to redefine competitive moats in prepared flour categories. Three active developments are compressing traditional advantage structures.
Precision blending technology is hybridizing conventional wheat-based self-rising flour with ancient grain and pulse protein inclusions. Premium-positioned millers in the Pacific Northwest and Northeast US are deploying these formulations to capture clean-label baking enthusiasts. The technology is hybridizing commodity flour economics with functional food positioning, forcing legacy millers to choose between equipment reinvestment or margin erosion.
EFSA's evolving stance on health claim substantiation is tightening evidentiary requirements for protein and fiber fortification claims. European millers now face 18-24 month validation cycles that advantage established players with dedicated regulatory affairs functions. Organic self-rising flour segments absorb disproportionate compliance burden as dual USDA-EU certification requirements multiply documentation overhead.
Home baker purchasing patterns are fragmenting across channel types as specialty retailers and direct platforms capture share from conventional grocery. King Arthur Baking Company's owned-channel strategy exemplifies this displacement, using recipe content to drive subscription flour purchases. This channel rotation is most pronounced in coastal US metropolitan markets where premium positioning commands sustained price elasticity.
Self-Rising Flour Market Segmentation
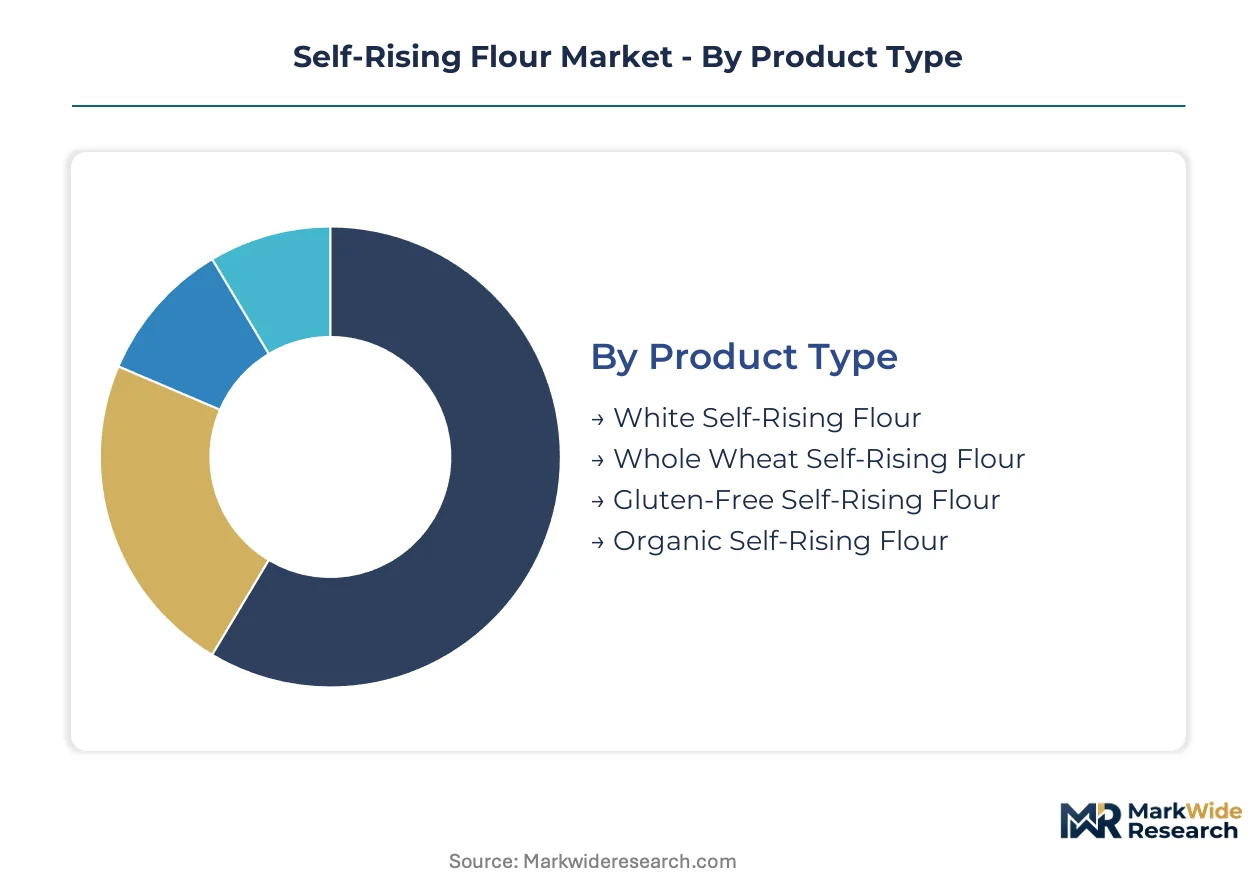
Self-rising flour segmentation reveals how formulation specificity, channel control, and packaging economics create distinct profit pools. Understanding these divisions exposes where capital efficiency concentrates and where new entrants face structural barriers.
Product Type:
Inventory velocity varies sharply across formulations, with commodity white flour turning weekly while certified organic SKUs sit 3-4x longer due to supply chain verification requirements.
- White Self-Rising Flour:Refined wheat base with standardized baking powder and salt ratios delivers neutral flavor for broad recipe compatibility. Demand concentrates in US Midwest and Southeast home baking channels where price sensitivity dominates purchase decisions and private-label penetration is deepest.
- Gluten-Free Self-Rising Flour:Rice, almond, or tapioca-based blends with modified leavening chemistry for celiac-sensitive applications. Growth concentrates in coastal US metropolitan markets and UK retail where health-conscious consumers absorb 40-60% price premiums and specialty grocers command shelf space.
- Whole Wheat Self-Rising Flour:Bran-inclusive milled wheat with adjusted leavening for denser crumb structure, targeting fiber-seeking home bakers in health-focused demographics.
- Organic Self-Rising Flour:USDA or EU Organic certified wheat with traceable supply chains; certification documentation extends procurement cycles and limits supplier flexibility.
White Self-Rising Flour anchors the volume base while Gluten-Free Self-Rising Flour gains share at the steepest rate.
End Use:
Application economics separate high-volume contract manufacturing from fragmented foodservice spot purchasing, with home baking occupying the middle ground on margin stability.
- Home Baking:Retail-packaged SKUs for consumer kitchens where convenience drives repurchase loyalty and brand recognition commands price elasticity. US and UK supermarkets dominate volume, with direct-to-consumer subscription models capturing premium tiers in coastal metros.
- Food Manufacturing:Industrial-scale procurement of bulk formulations for ready-to-eat baked goods and frozen dough operations. Demand concentrates in Midwest US production corridors where Ardent Mills and regional co-ops maintain elevator-to-plant logistics integration.
- Bakeries:Artisan and commercial operations requiring consistent leavening performance across batch sizes; procurement shifts toward specialty millers with technical service support.
- Restaurants:Spot purchasing with high SKU fragmentation and limited forward contracting; operators prioritize cost control over brand specification in casual dining segments.
Food Manufacturing delivers the most stable contract volumes while Home Baking shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines working capital intensity, with wholesale distributors demanding extended payment terms and online retail compressing gross margins through fulfillment cost absorption.
- Supermarkets:Dominant US and UK volume channel where slotting fees and promotional allowances consume 15-25% of manufacturer revenue; consolidation into Walmart, Kroger, and Tesco concentrates buyer power.
- Online Retail:Amazon and specialty platforms enable subscription models and recipe-content bundling; King Arthur Baking Company leverages owned-channel control to bypass traditional grocery economics.
- Wholesale Distributors:Industrial and foodservice intermediaries with regional warehousing networks; mid-capitalization millers depend on these relationships for geographic expansion without direct sales force investment.
- Specialty Stores:Premium and organic-focused retailers with educated consumer bases and higher tolerance for price premiums; shelf space allocation favors dual-certified USDA-EU Organic SKUs.
Supermarkets retain the dominant volume position while Online Retail climbs the fastest.
Packaging Type:
Packaging format selection reflects the tension between shelf differentiation and logistics efficiency, with sustainability mandates from California and EU regulations reshaping material specifications.
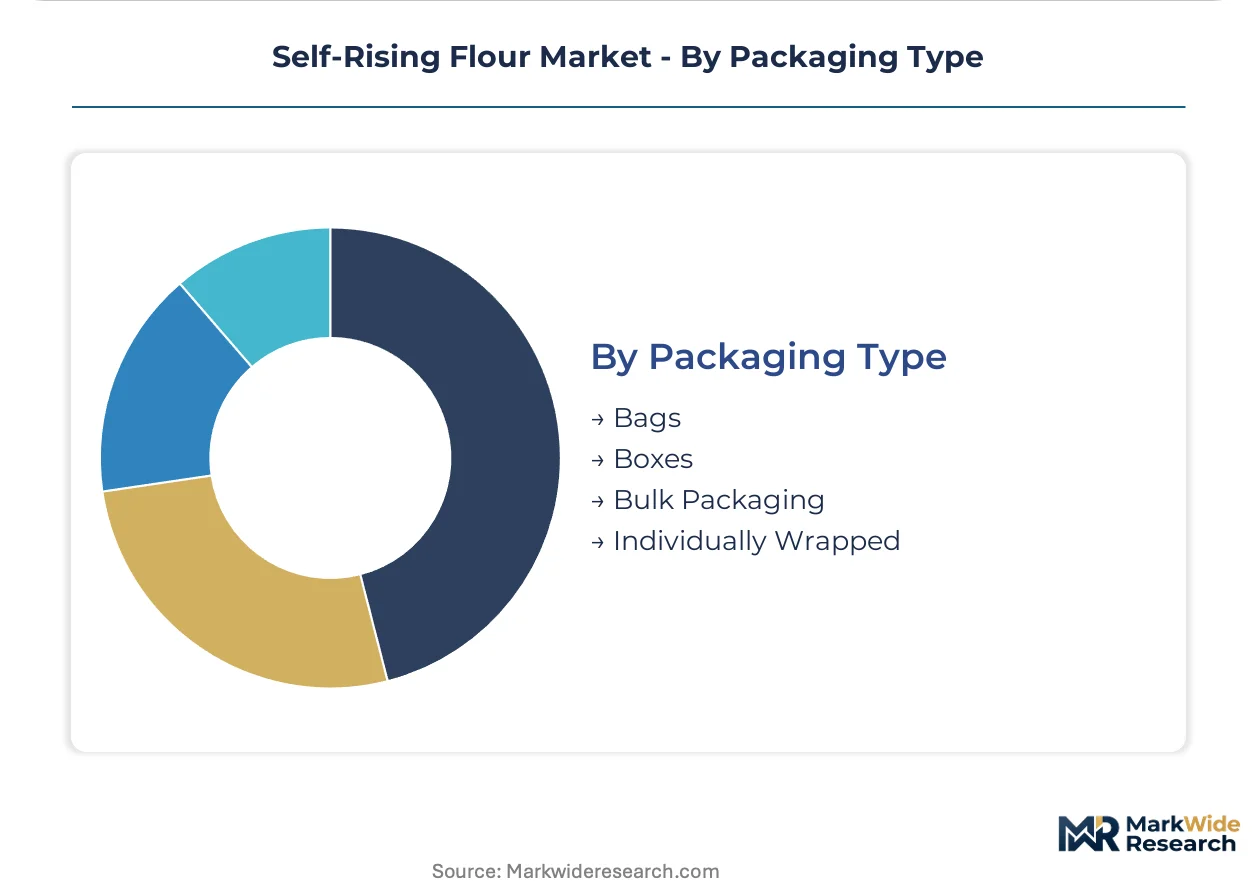
- Bags:Multi-wall paper or plastic laminate structures for 2-5 pound consumer units; dominates US retail where recycling infrastructure varies by municipality and EPR regulations in Europe drive compostable material trials.
- Bulk Packaging:25-50 pound sacks for industrial and foodservice procurement; Midwest US milling corridors optimize rail and truckload economics around these specifications.
- Boxes:Rigid packaging for premium positioning and gift-oriented SKUs; limited volume but high margin concentration in specialty retail channels.
- Individually Wrapped:Single-serve portions for foodservice and travel retail; highest packaging cost per unit with limited adoption outside institutional catering.
Bags carry the volume base while Bulk Packaging expands most quickly in industrial channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for self-rising flour varies sharply by market maturity. Established baking cultures in Western Europe absorb organic premiums with limited volume erosion, while emerging markets in Asia-Pacific prioritize cost-efficient formulations. Regulatory fortification mandates in North America and Europe compress margin flexibility for non-compliant imports.
United States
Home baking convenience drives sustained retail demand across Midwest and Southeast supermarkets. FDA enrichment standards under 21 CFR 137 protect domestic millers from lower-standard imports. Minneapolis-St. Paul anchors North American milling infrastructure with elevator-to-plant logistics integration.
Germany
Dual-certified USDA-EU Organic SKUs command 40-60% shelf price premiums in Berlin and Munich specialty retail. EFSA fortification evaluations extend validation cycles for novel protein-enriched formulations. The North Rhine-Westphalia corridor concentrates industrial baking procurement with rail-linked bulk distribution.
United Kingdom
Post-pandemic scratch-cooking behaviors institutionalized prepared flour adoption in Tesco and Sainsbury's channels. EFSA-aligned enrichment requirements reshape product composition for cross-border EU trade. Greater London and Manchester metropolitan markets show steepest gluten-free formulation growth.
France
Premium organic positioning captures health-conscious consumers in Paris and Lyon retail networks. EU Organic certification documentation extends procurement cycles for traceable wheat supply. The Grand Est region maintains heritage milling infrastructure with limited gluten-free capacity expansion.
Canada
Cross-border retail integration with US channels concentrates demand in Ontario and British Columbia supermarkets. Health Canada fortification guidelines align with FDA standards for enriched flour imports. Prairie Province grain elevators supply cost-advantaged wheat to integrated milling operations.
Self-Rising Flour Market Competitive Landscape
Vertically integrated millers and specialty baking brands split the market between scale efficiency and premium positioning. The vendor base concentrates around three strategic archetypes: grain-elevator-integrated conglomerates, direct-to-consumer specialty millers, and private-label co-manufacturers. Dominant competitive moves include backward integration into grain supply and owned-channel distribution bypassing traditional grocery slotting fees.
Among North American milling conglomerates, Ardent Mills and General Mills occupy positions defined by elevator network control and retail channel density. King Arthur Baking Company exemplifies the specialty-tier archetype through recipe-content-driven subscription models. Associated British Foods plc anchors European market representation with multi-brand portfolio breadth.
| Leading Market Players |
|---|
| Ardent Mills |
| The J.M. Smucker Company |
| General Mills Inc. |
| Bob's Red Mill Natural Foods Inc. |
| Conagra Brands Inc. |
| Archer Daniels Midland Company |
| King Arthur Baking Company |
| Associated British Foods plc |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Elevator network undercapacity in the US Great Plains compresses wheat procurement flexibility for non-integrated millers while simultaneously amplifying pricing power for Ardent Mills and Cargill. This utilization asymmetry forces mid-capitalization competitors into premium positioning or private-label dependence.
Pricing Analysis
Recipe-content subscriptions and extended brand loyalty programs drive lifetime value for King Arthur Baking Company and specialty millers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel control, with USDA Organic dual-certified SKUs commanding the widest spreads. Cost compression in commodity white flour is intensifying because private-label co-manufacturers reclaim branded capacity. Food manufacturing buyers exhibit the highest price sensitivity due to contract volume concentration, while direct-to-consumer home bakers absorb premium tiers with limited elasticity.
Supply Chain Analysis
Ardent Mills, General Mills, and Cargill Incorporated hold dominant North American milling capacity through vertically integrated elevator networks. Wheat supply concentrates in the United States, Canada, and Australia, with milled flour production anchored in Midwest US rail corridors. The supply chain draws from hard red winter wheat, soft red winter wheat, and certified organic grain pools. Single-source vulnerability to Black Sea supply disruptions elevates procurement risk. Distribution runs through supermarket retail consolidation, wholesale distributor networks, and owned-channel direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic supply chain documentation expertise represents a binding constraint that fragments competitive advantage toward established millers with dedicated regulatory affairs functions.
For Market Incumbents: Harden elevator network utilization through captive organic grain procurement and segregated gluten-free production line investment. Defensive consolidation should prioritize backward integration into Prairie Province grain supply to offset Black Sea volatility. Channel control through recipe-content platforms protects margin position against private-label encroachment. For New Entrants and Emerging Players: German and French specialty retail chains present underpenetrated shelf space for dual-certified USDA-EU Organic SKUs with technical service support. White-space targets include probiotic-fortified formulations pending EFSA novel food approval and coastal US metropolitan direct-to-consumer subscription models. A go-to-market angle anchored in precision blending technology for ancient grain inclusions bypasses commodity price wars. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gluten-free SKU segregation and certified organic supply chain verification. Long-term viability favors millers with elevator-to-plant logistics integration and owned-channel distribution architecture. Acquisition target archetypes include mid-capitalization specialty millers with USDA Organic certification and technical service capabilities. The signal to watch is EFSA health claim substantiation timeline compression for protein-enriched formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Supply | Captive wheat procurement from Prairie Province elevators insulates margin from Black Sea price volatility. |
| Segregated Gluten-Free Production Line Investment | Dedicated milling infrastructure captures celiac-sensitive demand pools in coastal US metropolitan markets. |
| Direct-to-Consumer Subscription Launch | Recipe-content bundling bypasses supermarket slotting fees and builds brand loyalty among committed home bakers. |
| Dual USDA-EU Organic Certification | Dual certification unlocks 40-60% price premiums in German and French specialty retail channels. |
| Precision Blending Technology Deployment | Ancient grain and pulse protein inclusions hybridize commodity economics with functional food positioning. |
Research Methodology
Cross-validation between primary interviews with milling operations executives, organic certification specialists, and supermarket category buyers anchors the qualitative findings. Secondary validation draws from FDA 21 CFR 137 enrichment standards documentation, USDA Organic certification databases, EFSA novel food submission records, and North American grain elevator capacity reports. Bottom-up SKU-level demand modeling triangulates with top-down regional consumption estimates.
Calibration against historical volume trajectories and elasticity assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions include product formulation type, end-use application, distribution channel architecture, and packaging format specification. CAGRs derive from fitted growth curves adjusted for regulatory fortification mandate impacts and channel shift velocities. Wheat futures price volatility and organic certification timeline compression serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated conglomerates into direct-to-consumer channels would shift outcomes. Model assumptions reflect current FDA and EFSA enrichment thresholds, with deviation risk from state-level labeling requirements or EU Green Deal packaging mandates. Quarterly review of organic grain elevator utilization rates and EFSA novel food approval cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Yeast Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Pea Hull Fiber Market
Ingredients
Non Meat Ingredients Market
Ingredients
Roll-Dried Starch Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Terminalia Extract Market
Ingredients
Textural Food Ingredients Market
Ingredients
France Protein Market
Ingredients
Specialty Yeast Market
Ingredients
Honey Powder Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
North America Agar Market
Ingredients
Global Infant Nutrition Ingredients Market