
 Hydrogenated Starch Market | 2026-2036
Hydrogenated Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenated Starch Market Outlook
Direct-to-bulk-ingredient procurement is fragmenting as food manufacturers bypass traditional distributors to secure hydrogenated starch volumes. Cargill, Incorporated leverages its North American grain origination infrastructure to anchor supply contracts with major processed-food producers. Ingredion Incorporated competes through specialty modified starch R&D pipelines that sustain premium positioning in pharmaceutical excipient grades.
Hydrogenated starch denotes starch derivatives whose reducing terminal glucose units have been chemically converted to sorbitol or maltitol moieties through catalytic hydrogenation, yielding polyols with controlled hygroscopicity and reduced caloric density for use as bulk sweeteners, humectants, and tablet binders. The hydrogenated starch segment itself occupies mature volume pools in confectionery and oral care, while modified starch variants capture faster growth in pharmaceutical controlled-release matrices where excipient functionality commands higher margin structures. Natural starch channels face compression from clean-label substitution trends, though instant starch formats gain traction in convenience-food manufacturing for reduced hydration times.
FDA food additive regulations and EPA wastewater discharge standards for corn wet-milling operations constrain production economics and site licensing in the United States, while REACH registration requirements and EFSA novel food assessments govern market access across European Union member states. China's NMPA and GB standards for food-grade polyols impose additional testing protocols on imports. Stakeholders must monitor evolving pharmaceutical excipient monographs and regional biofuel policy shifts that redirect corn feedstock availability.
Market Dynamics
Clean-label ingredient mandates are forcing hydrogenated starch producers to requalify supply chains, as FDA modified starch guidance and REACH purity benchmarks simultaneously tighten specification windows across North American and European food manufacturing channels.
Growth Catalysts
- Pharmaceutical excipient grade demand:Controlled-release tablet formulations require hydrogenated starch hydrolysates with precise sorbitol equivalence ratios, pulling volume into higher-margin pharmaceutical channels.
- REACH registration completion:European polyol manufacturers achieving full substance registration under ECHA protocols now access unified EU market access without member-state fragmentation barriers.
- China domestic sweetener consumption:NMPA food-grade polyol approvals for hydrogenated starch syrup variants accelerate substitution of sucrose in processed food manufacturing across coastal provinces.
Market Restraints
- Corn feedstock price volatility:Wet-milling operations face margin compression when drought conditions in US Midwest grain belts spike origination costs for starch base material.
- Hydrogenation catalyst supply concentration:Ruthenium and nickel catalyst manufacturing concentrates in Chinese and Russian suppliers, creating input vulnerability for European and North American hydrogenation facilities.
- Allulose and rare sugar substitution:Enzymatically produced low-calorie sweeteners achieve similar bulking functionality with superior consumer perception in clean-label positioning.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO excipient monograph harmonization with USP standards positions Mumbai and Hyderabad tablet producers as import substitution targets for hydrogenated starch binders.
- Biopolymer packaging convergence:Hydrogenated starch polyols serve as feedstock for biodegradable film applications where PLA brittleness limitations create formulation gaps.
- EU Green Deal bio-based content mandates:Renewable carbon certification schemes reward hydrogenated starch incorporation in personal care and household products seeking ISO 16620 biobased content verification.
Industry Challenges
- Pharmaceutical excipient qualification timelines:USP-NF monograph compliance and ICH Q3D elemental impurity testing extend new grade introduction cycles to 18-24 months.
- Legacy equipment hydrogenation retrofit costs:Batch reactor facilities require pressure vessel recertification and automated process control upgrades to meet current Good Manufacturing Practice standards for pharmaceutical supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenated Starch Market |
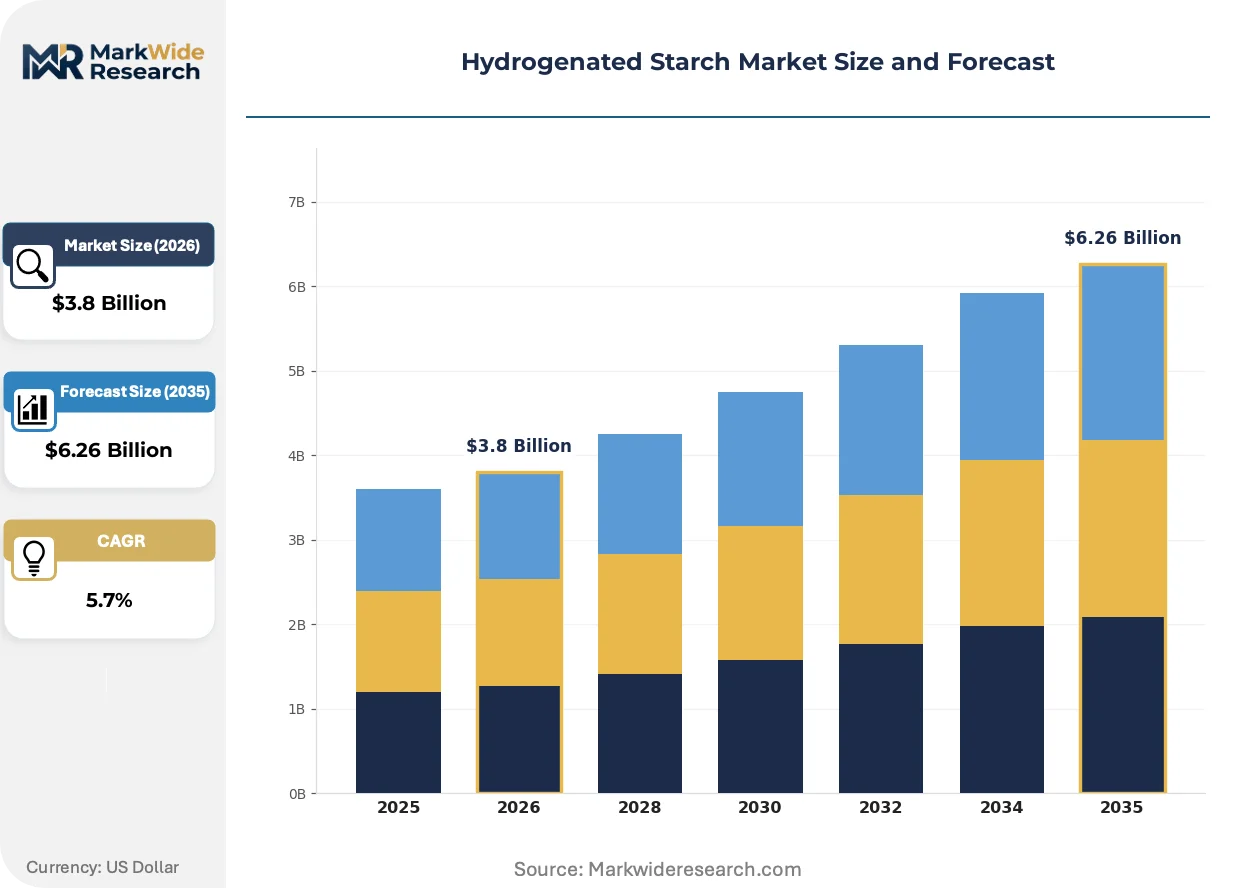
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogenated Starch, Modified Starch, Natural Starch, Instant Starch Application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial End Use Industry: Food Manufacturing, Paper Coating, Textile, Adhesives Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Matsutani Chemical Industry Co., Ltd., Südzucker AG, Grain Processing Corporation, Shandong Bailong Chuangyuan Bio-Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenated Starch Market Strategic Shifts
Enzymatic modification techniques are displacing purely chemical hydrogenation routes, while regulatory convergence on excipient standards accelerates qualification efficiency across pharmaceutical supply chains.
Continuous-flow hydrogenation reactor technology is migrating from petrochemical polyol production into starch-derived sweetener manufacturing. European ingredient suppliers adopt these systems to reduce catalyst consumption and improve heat transfer efficiency. The shift compresses batch cycle times from hours to minutes, enabling just-in-time production models that reduce working capital requirements for contract manufacturers.
EFSA novel food assessments now require comprehensive toxicological dossiers for hydrogenated starch hydrolysates entering European markets, including 90-day rodent feeding studies and human glycemic response data. This regulatory burden favors established suppliers with existing safety portfolios while raising capital barriers for new market entrants. Pharmaceutical-grade applications face parallel scrutiny under revised EU GMP Annex 1 contamination control guidelines.
Food manufacturers now specify excipient-grade hydrogenated starch for functional benefits previously satisfied by lower-purity industrial grades. Procurement teams at major confectionery and oral care producers demand certificates of analysis with expanded microbial and heavy metal testing panels. This certification-driven preference shift concentrates volume with suppliers maintaining dual food-pharma quality systems, most visible in German and Swiss contract manufacturing relationships.
Hydrogenated Starch Market Segmentation
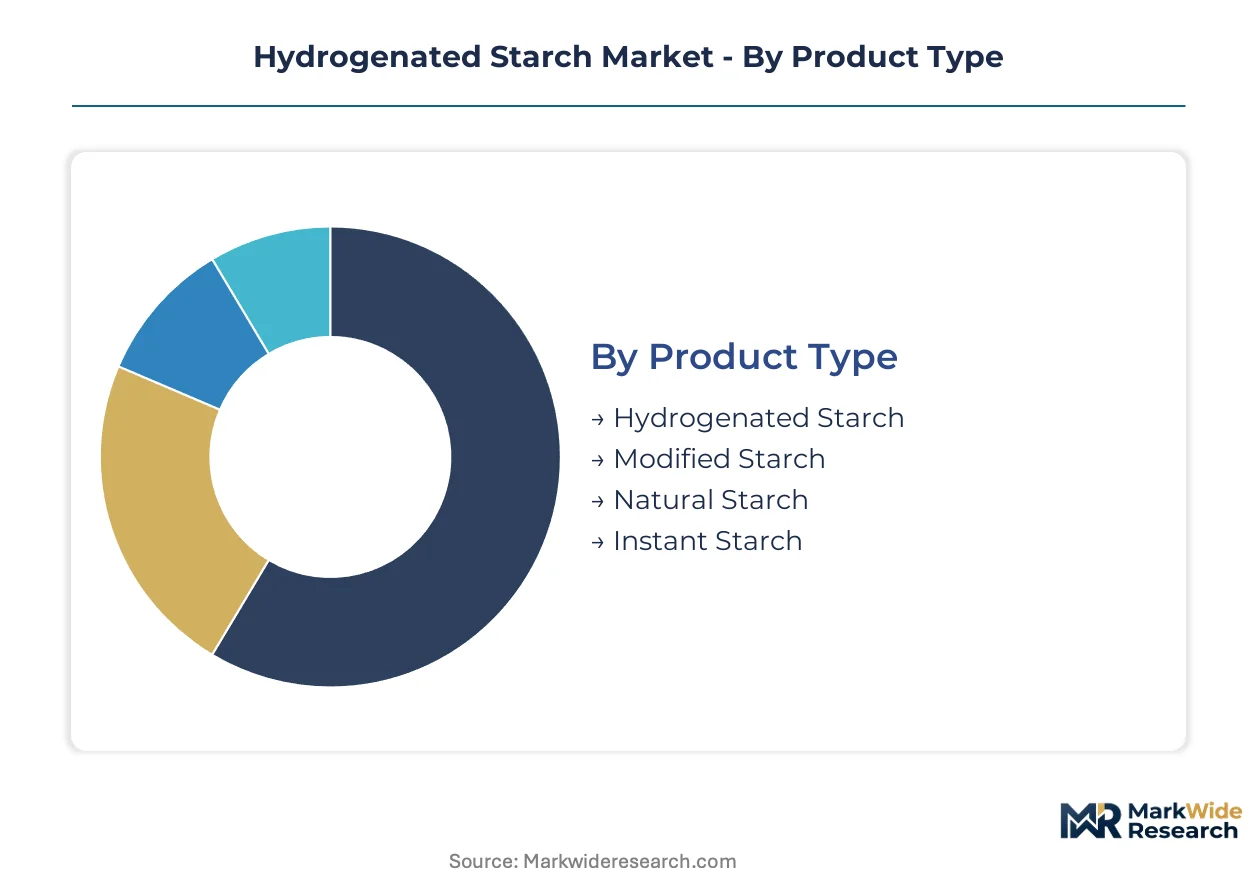
Segmentation reveals how hydrogenated starch producers allocate technical service resources across divergent customer requirements. Pharmaceutical and food-grade buyers demand markedly different qualification support, certification documentation, and supply security guarantees than industrial purchasers.
Product Type:
After-sales intensity varies sharply across product categories, with pharmaceutical-grade hydrogenated starch requiring 18-24 month qualification cycles and ongoing regulatory file maintenance compared to commodity starch variants.
- Hydrogenated Starch:Catalytic hydrogenation converts reducing terminal glucose units to sorbitol or maltitol moieties, yielding polyols with controlled hygroscopicity. Pharmaceutical excipient demand in controlled-release tablet formulations pulls volume into higher-margin channels where USP-NF monograph compliance commands premium positioning.
- Modified Starch:Chemical or enzymatic alteration introduces functional properties including cross-linked stability and oxidation resistance. Food manufacturers in coastal China specify modified variants for clean-label substitution of synthetic thickeners, accelerating NMPA approval-driven volume expansion.
- Natural Starch:Unmodified extraction from corn, potato, or tapioca sources serves cost-sensitive industrial applications.
- Instant Starch:Pre-gelatinized formats eliminate hydration time requirements for convenience-food manufacturing.
Hydrogenated starch holds the largest share; momentum sits with modified starch.
Application:
Application-driven cost tiers separate premium pharmaceutical specifications from commodity industrial grades, with certification burden and testing protocol intensity determining pricing stratification.
- Food & Beverage:Bulk sweetener and humectant functionality in confectionery, bakery, and beverage applications. Clean-label mandates in Germany and Switzerland drive specification upgrades toward excipient-grade purity even for food uses.
- Pharmaceuticals:Tablet binders and controlled-release matrices require precise sorbitol equivalence ratios. CDSCO harmonization with USP standards in India positions Mumbai and Hyderabad producers for import substitution of hydrogenated starch hydrolysates.
- Personal Care:Humectant and film-forming properties in oral care and cosmetic formulations.
- Industrial:Adhesive, paper coating, and textile sizing applications prioritize cost efficiency over certification burden.
Food and beverage commands current volume; pharmaceuticals represent the steepest expansion trajectory.
End Use Industry:
Customer-type concentration shapes service models, with multinational food manufacturers demanding dedicated technical account management versus spot-market industrial procurement.
- Food Manufacturing:Processed food and beverage production consumes hydrogenated starch polyols as sucrose substitutes. REACH-registered European suppliers capture unified EU market access, consolidating procurement relationships with pan-national manufacturers.
- Paper Coating:Surface sizing and coating binders leverage starch film-forming properties.
- Textile:Warp sizing applications require specific viscosity and adhesion characteristics.
- Adhesives:Corrugated board and packaging glue formulations represent volume-driven, price-sensitive demand.
Food manufacturing dominates current offtake; biopolymer packaging convergence creates emerging pull from paper coating.
Distribution Channel:
Supply concentration in wet-milling hubs dictates channel configuration, with direct sales anchoring high-volume pharmaceutical contracts while distributors serve fragmented industrial accounts.
- Direct Sales:Long-term supply contracts with major processed-food and pharmaceutical manufacturers. Cargill leverages North American grain origination infrastructure to anchor direct relationships, bypassing traditional distributor margins.
- Distributors:Regional inventory positioning and technical service for mid-tier food and personal care manufacturers.
- Wholesalers:Commodity starch aggregation for small-scale industrial purchasers.
- Online Retail:Emerging channel for specialty and sample-grade quantities in research and pilot-scale applications.
Direct sales holds the largest share; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network anchors North American corn wet-milling logistics, enabling bulk starch origination from Midwest grain belts to coastal processing hubs. This infrastructure underwrites hydrogenated starch supply security for pharmaceutical and food manufacturers across multiple continents.
United States
Pharmaceutical excipient demand from New Jersey and North Carolina tablet manufacturers pulls hydrogenated starch hydrolysates into controlled-release formulations. FDA modified starch guidance and USP-NF monograph compliance tighten purity benchmarks for domestic suppliers. Iowa and Illinois wet-milling clusters concentrate hydrogenation capacity near corn origination points.
Germany
REACH registration completion under ECHA protocols grants unified EU market access for Mannheim and Frankfurt-area polyol producers. EFSA novel food assessments require toxicological dossiers including glycemic response data. Bavarian chemical parks integrate continuous-flow hydrogenation reactors from petrochemical polyol production.
China
NMPA food-grade polyol approvals accelerate sucrose substitution in Shandong and Jiangsu processed food manufacturing. GB standards impose testing protocols on hydrogenated starch syrup imports. Shanghai and Tianjin pharmaceutical clusters drive excipient-grade consumption for tablet binder applications.
India
CDSCO excipient monograph harmonization with USP standards positions Mumbai and Hyderabad tablet producers for import substitution. FSSAI clean-label mandates push food manufacturers toward modified starch variants. Gujarat chemical zones attract hydrogenation capacity investments serving domestic sweetener demand.
Switzerland
Swissmedic pharmaceutical regulations and ISO 16620 biobased certification requirements shape premium excipient procurement from Basel-area manufacturers. EU Green Deal renewable carbon mandates reward hydrogenated starch incorporation in personal care formulations. Swiss contract manufacturing relationships concentrate dual food-pharma quality system suppliers.
Hydrogenated Starch Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The hydrogenated starch market structures around grain-origination conglomerates, specialty ingredient R&D houses, and regional chemical processors. Three archetypes dominate: wet-milling giants with captive corn supply, pharmaceutical excipient specialists with monograph expertise, and Asian polyol manufacturers with cost-optimized hydrogenation scale. Competitive moves concentrate on backward integration into grain origination and forward integration into pharmaceutical qualification services.
Among North American grain-origination conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify platform-scale supply security. Ingredion Incorporated occupies a position within the specialty modified starch tier, anchoring premium pharmaceutical excipient positioning through R&D-intensive product pipelines. These three entities represent divergent strategic postures: captive agricultural supply, diversified processing scale, and targeted high-margin specialization.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Matsutani Chemical Industry Co., Ltd. |
| Südzucker AG |
| Grain Processing Corporation |
| Shandong Bailong Chuangyuan Bio-Tech Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity signals in European hydrogenation facilities are compressing batch-reactor utilization rates below threshold economics, forcing suppliers to absorb catalyst cost spikes rather than pass through pricing, while simultaneously accelerating migration toward continuous-flow systems that reset competitive cost structures.
Pricing Analysis
Volume-discount tiering structures stratify across pharmaceutical excipient, food-grade, and industrial purity bands, with USP-NF monograph compliance commanding substantial premia over standard food-grade specifications. Price differentiation hinges on certification burden intensity and after-sales technical support depth, with pharmaceutical buyers exhibiting minimal price sensitivity compared to adhesive and textile manufacturers facing commodity substitution pressures. Pricing pressure stems from allulose and rare sugar enzymatic substitutes achieving functional parity in clean-label confectionery applications. Food manufacturers in coastal China demonstrate highest price elasticity, while Swiss and German pharmaceutical contract manufacturers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Corn feedstock origination anchors upstream supply concentration across the United States, China, and Brazil, with Midwest grain belts feeding Iowa and Illinois wet-milling clusters. Hydrogenation catalyst sourcing draws from concentrated Chinese and Russian ruthenium and nickel suppliers, creating single-source vulnerability for European and North American processing facilities. Tariff exposure on catalyst imports compounds margin compression risks. Distribution runs through direct sales contracts with multinational food and pharmaceutical manufacturers, supplemented by regional distributors serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow hydrogenation reactor technology is disrupting batch-process economics, compressing cycle times from hours to minutes and resetting capital-efficiency benchmarks for producers seeking pharmaceutical qualification.
For Market Incumbents: Insulate pharmaceutical excipient positioning through preemptive USP-NF monograph file maintenance and ICH Q3D elemental impurity testing infrastructure investments. Accelerate backward integration into Midwest grain origination to neutralize corn price volatility exposure. Prioritize captive catalyst recycling capabilities to offset ruthenium supply concentration risks from Chinese suppliers.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical excipient supply through CDSCO monograph harmonization with USP standards, targeting Mumbai and Hyderabad tablet manufacturing clusters. Penetrate biopolymer packaging feedstock applications where PLA brittleness limitations create formulation gaps for hydrogenated starch polyols. Pursue toll-manufacturing partnerships with existing wet-milling operators to bypass capital-intensive reactor investments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous-flow hydrogenation sub-segments as reactor technology migrates from petrochemical polyol production. Long-term viability favors platform-scale grain-origination conglomerates with integrated pharmaceutical qualification capabilities over standalone chemical processors. Monitor EFSA novel food assessment completion rates as inflection indicators for European market access timelines and competitive consolidation triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Adoption | Compresses batch cycle times from hours to minutes, enabling just-in-time pharmaceutical production models. |
| Backward Integration into Grain Origination | Cargill leverages Midwest corn supply infrastructure to anchor direct sales contracts with processed-food manufacturers. |
| Pharmaceutical Excipient Monograph Investment | USP-NF compliance extends qualification cycles to 18-24 months, concentrating volume with established suppliers. |
| Biopolymer Packaging Feedstock Pivot | EU Green Deal ISO 16620 certification rewards renewable carbon content in personal care and household applications. |
| India Market Entry via CDSCO Harmonization | Excipient monograph alignment with USP standards positions Mumbai producers for import substitution opportunities. |
Study Parameters
A spread of perspectives from wet-milling plant managers, pharmaceutical procurement directors at New Jersey tablet manufacturers, ECHA regulatory affairs specialists, and Chinese food-grade polyol distributors converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA modified starch guidance documents, REACH registration databases, NMPA approval filings, and customs trade flow records. Bottom-up volume modeling triangulated against top-down industry association estimates from ACC and Cefic.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across product type, application, end-use industry, and distribution channel dimensions. Pharmaceutical excipient grade demand, corn feedstock origination economics, and hydrogenation catalyst availability served as industry-specific forecast inputs. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves.
Sensitivities concentrate around corn price volatility from drought conditions in US Midwest grain belts, REACH registration timeline extensions, and allulose enzymatic production scale-up rates. Forecasts reflect documented assumptions regarding continuous-flow reactor adoption curves and pharmaceutical qualification cycle durations. Cross-checking against ECHA substance registration completion databases and CDSCO excipient monograph update schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sunflower Oil Market
Ingredients
Desiccated Coconut Market
Ingredients
Fruit Pectin Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Carotenes Market
Ingredients
Maracuja Oil Market
Ingredients
Caramel Malt Market
Ingredients
Dill Seed Oil Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
Pomace Olive Oil Market
Ingredients
Broccoli Powder Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
India Bakery Ingredients Market