
 Asia-Pacific Potato Protein Market | 2026-2036
Asia-Pacific Potato Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Potato Protein Market Outlook
Sports nutrition is restructuring end-use demand across the Asia-Pacific potato protein landscape. Roquette Frères leverages its European extraction expertise to supply premium isolate grades to Japanese supplement manufacturers. AVEBE anchors supply through its potato starch co-product streams, sustaining cost advantages in concentrate production. KMC Ingredients competes on clean-label positioning, differentiating its offerings for health supplement brands seeking allergen-free alternatives.
Potato protein refers to the globulin and albumin fractions extracted from potato tuber juice, typically containing 70-90% protein content depending on processing grade, with functional properties including emulsification, gelation, and foaming capacity that serve food formulation and nutritional fortification. Isolate grades command margin pools in sports nutrition applications where protein purity thresholds exceed 85%, while concentrate segments dominate volume in animal feed and processed food manufacturing due to lower unit economics. Hydrolysate variants are gaining traction in nutraceutical applications where pre-digested protein fractions accelerate absorption kinetics for aging populations across Japan and South Korea.
Japan's PMDA and Food for Specified Health Uses (FOSHU) framework shape ingredient approval timelines, while China's NMPA and GB standards govern protein content claims and novel food registrations. South Korea's MFDS enforces functional food labeling requirements that directly influence product positioning for health supplement brands. Stakeholders must monitor regulatory divergence across these three approval regimes when scaling formulations for cross-border distribution.
Market Dynamics
Sports nutrition brands in Japan and South Korea are restructuring formulation strategies around potato protein isolates, while China's NMPA reforms compress novel ingredient approval timelines from 24 months to under 12 months for qualified applicants.
Growth Catalysts
- FOSHU Framework Expansion:Japan's Food for Specified Health Uses category now accommodates protein fortification claims for aging consumers, creating a regulatory pathway for functional food positioning.
- Starch Co-Product Economics:Potato processing clusters in Shandong and Heilongjiang provinces generate concentrated feedstock streams that lower isolate production costs by 15-20% versus dedicated protein crops.
- Clean-Label Substitution:Formulators are displacing soy and dairy proteins in allergen-sensitive applications across Australian nutraceutical manufacturing, driven by pediatric and geriatric nutrition demand.
Market Restraints
- Input Cost Volatility:Fresh potato prices fluctuate with seasonal harvest cycles in China's northern growing regions, compressing margin stability for concentrate producers.
- Supply Concentration Risk:Over 70% of commercial isolate capacity sits with European-owned extraction facilities, creating import dependency for premium-grade material.
- Technical Limitation:Potato protein's lower lysine content versus whey and casein restricts complete amino acid profile marketing in competitive sports nutrition positioning.
Strategic Opportunities
- Vietnam and Indonesia Penetration:Emerging middle-class protein consumption in Ho Chi Minh City and Jakarta metro corridors remains underdeveloped for plant-based isolates.
- Cell Culture Media Applications:Biopharma-grade hydrolysate variants are entering fermentation feedstock supply chains for cultivated meat startups in Singapore.
- Dual Carbon Policy Alignment:China's national carbon neutrality mandates favor low-water-intensity protein extraction versus soybean cultivation, accelerating state-backed facility approvals.
Industry Challenges
- Protein Purity Certification Timelines:Third-party validation for 85%+ isolate grades requires 8-14 months through ISO-accredited laboratories, delaying product launches.
- Specialized Extraction Engineering Talent:Membrane filtration and chromatography expertise for food-grade protein recovery remains concentrated in European technical institutes.
- Legacy Equipment Retrofit Costs:Starch processors face $2-4 million capital requirements per line to add protein recovery circuits to existing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Potato Protein Market |
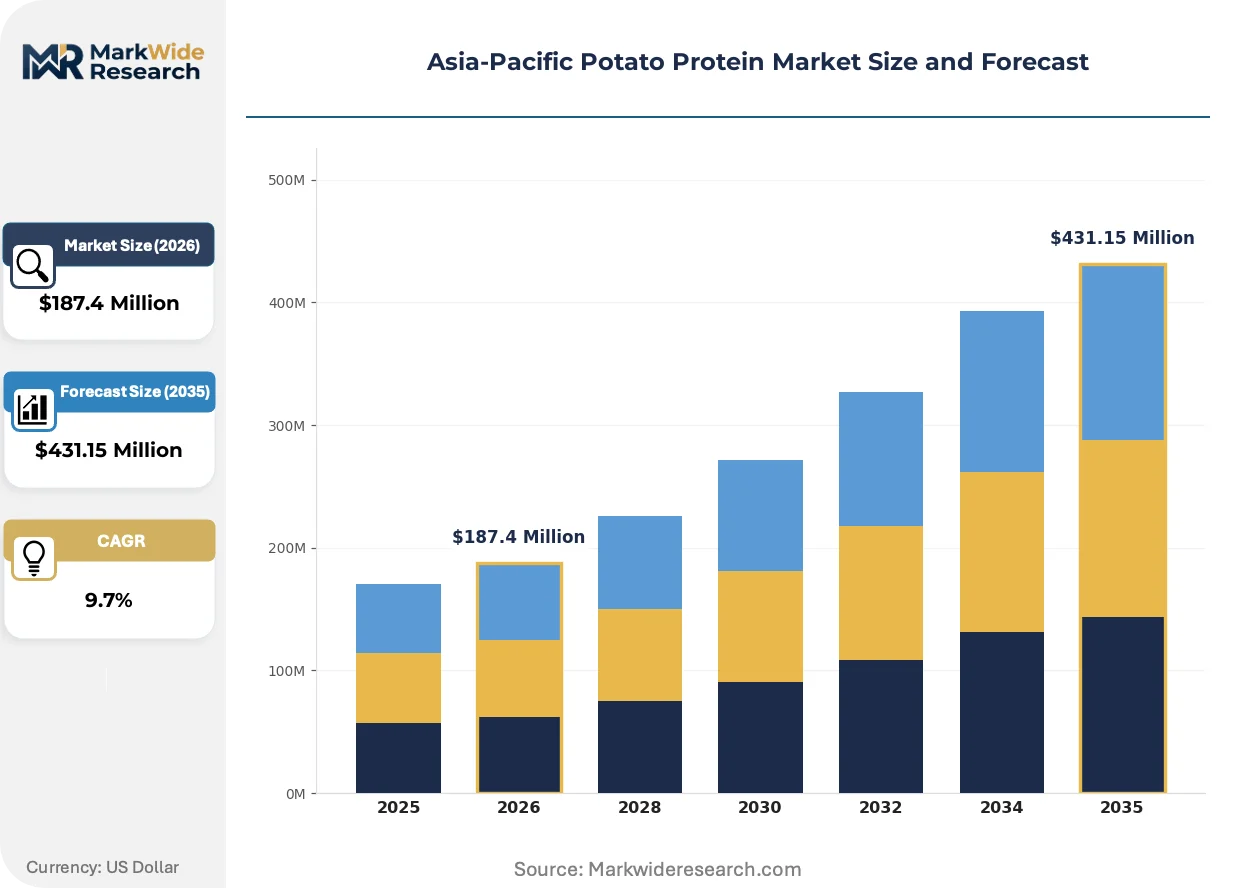
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Flour Application: Food & Beverages, Animal Feed, Nutraceuticals, Sports Nutrition Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales End User: Food Manufacturers, Beverage Producers, Feed Manufacturers, Health Supplement Brands |
| Companies Covered | Coöperatie AVEBE U.A., AGRANA Beteiligungs-AG, Roquette Frères, Kemin Industries, Inc., Bioriginal Food & Science Corp., KMC Ingredients, Emsland Group, Meelunie B.V., Tereos Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Potato Protein Market Strategic Shifts
Enzymatic hydrolysis and precision membrane filtration are compressing extraction energy requirements while expanding functional property customization for specific end-use categories.
Membrane filtration technology is integrating ultrafiltration and diafiltration stages into continuous processing lines. Japanese supplement contract manufacturers are adopting these systems at pilot scale for 2025 commercial deployment. This integration is enabling real-time protein fractionation that was previously batch-limited, compressing production cycles from 48 hours to 12 hours for isolate grades.
China's NMPA has published draft guidelines for novel protein ingredient safety assessment that align with Codex Alimentarius frameworks. The industrial consequence is accelerated cross-border registration for European and North American suppliers seeking direct China market access. Sports nutrition brands in Shanghai and Jiangsu are responding by reformulating existing products to meet the new purity and labeling specifications ahead of formal enforcement.
Direct procurement from extraction facilities is displacing traditional ingredient distributor intermediaries among mid-scale nutraceutical manufacturers. Australian and New Zealand brands are establishing annual volume contracts with AVEBE and Roquette Frères rather than regional chemical distributors. This pattern is most visible in Melbourne and Sydney, where clean-label positioning commands 20-30% price premiums that justify supply chain reconfiguration costs.
Asia-Pacific Potato Protein Market Segmentation
Potato protein segmentation in the Asia-Pacific region reflects divergent purity specifications, formulation requirements, and procurement economics across food manufacturing and nutritional applications. Understanding these category boundaries enables targeted positioning against Japan's FOSHU framework, China's NMPA registration pathways, and South Korea's functional food labeling mandates.
Product Type:
Processing intensity and protein recovery rates define the technical specification axis across extraction grades.
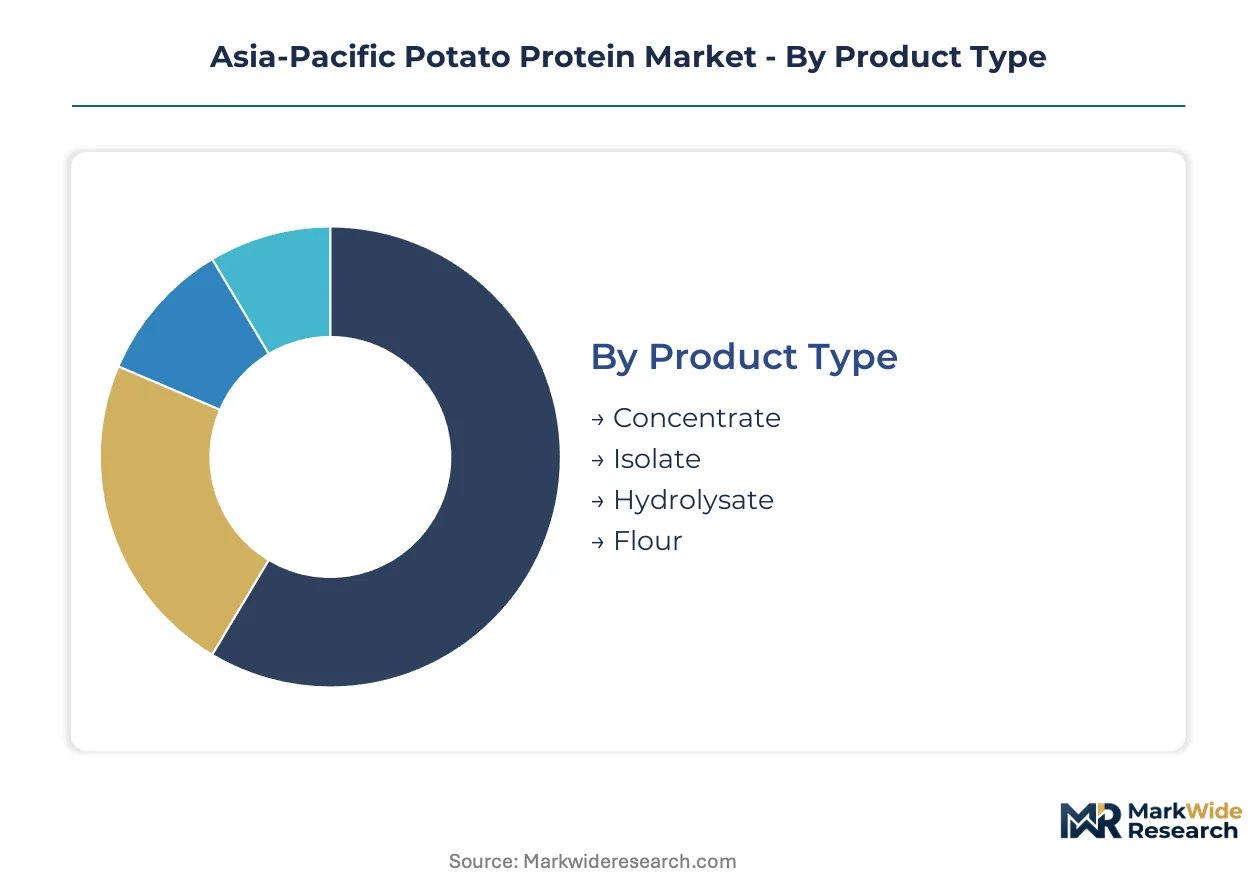
- Concentrate:Protein content ranges from 70-85% with retained starch fractions and fiber components. Chinese feed manufacturers in Shandong province absorb the majority of regional concentrate volume, driven by cost-sensitive aquaculture and livestock formulation requirements.
- Isolate:Purity exceeds 85% through advanced membrane filtration and chromatographic separation. Japanese sports nutrition brands in Tokyo and Osaka metro areas specify isolate grades for FOSHU-eligible protein fortification claims targeting aging consumers.
- Hydrolysate:Pre-digested peptide fractions manufactured through enzymatic hydrolysis. South Korean nutraceutical contract manufacturers favor hydrolysates for rapid absorption positioning in geriatric nutrition products.
- Flour:Whole potato protein with minimal processing, typically 5-15% protein content. Australian clean-label bakery applications represent the primary demand concentration for this grade.
Concentrate leads on scale; isolate leads on momentum.
Application:
End-use formulation requirements segment demand by functional property priorities and regulatory compliance burdens.
- Food & Beverages:Emulsification and gelation properties drive adoption in plant-based meat analogs and dairy alternatives. Shanghai-based food processors are reformulating existing product lines to incorporate potato protein isolates ahead of NMPA's revised novel ingredient guidelines.
- Sports Nutrition:High-purity isolate requirements for protein content claims and amino acid profile marketing. Japanese supplement brands are displacing soy and dairy proteins in allergen-sensitive positioning for endurance and strength training segments.
- Animal Feed:Concentrate grades dominate aquaculture and poultry formulations across China's northern potato processing corridor. Price elasticity in this segment compresses margins but sustains volume throughput for co-product recovery economics.
- Nutraceuticals:Hydrolysate variants targeting pre-digested absorption claims for aging populations. South Korea's MFDS functional food labeling framework shapes product positioning requirements for Seoul-based health supplement manufacturers.
Food & Beverages commands the largest revenue pool; Sports Nutrition is climbing the fastest.
Distribution Channel:
Procurement scale and relationship intensity determine channel selection across customer types.
- Direct Sales:Annual volume contracts between extraction facilities and mid-scale nutraceutical manufacturers. Australian and New Zealand brands in Melbourne and Sydney are bypassing traditional chemical distributors to secure clean-label supply chains.
- Wholesale:Aggregated procurement for smaller food manufacturers lacking dedicated ingredient sourcing teams. Indonesian and Vietnamese formulators rely on Singapore-based distributors for technical support and customs clearance.
- Online Retail:E-commerce platforms serving small-batch health supplement startups and research institutions. Alibaba's 1688 platform and specialized B2B marketplaces are gaining transaction share for sample and pilot-scale orders.
- Supermarkets:Limited penetration restricted to consumer-packaged protein powders and finished goods. Japanese retail chains stock finished sports nutrition products rather than bulk ingredients.
Direct Sales captures the highest margin transactions; Online Retail is expanding most quickly.
End User:
Technical capability and formulation sophistication create distinct customer tiers with divergent service requirements.
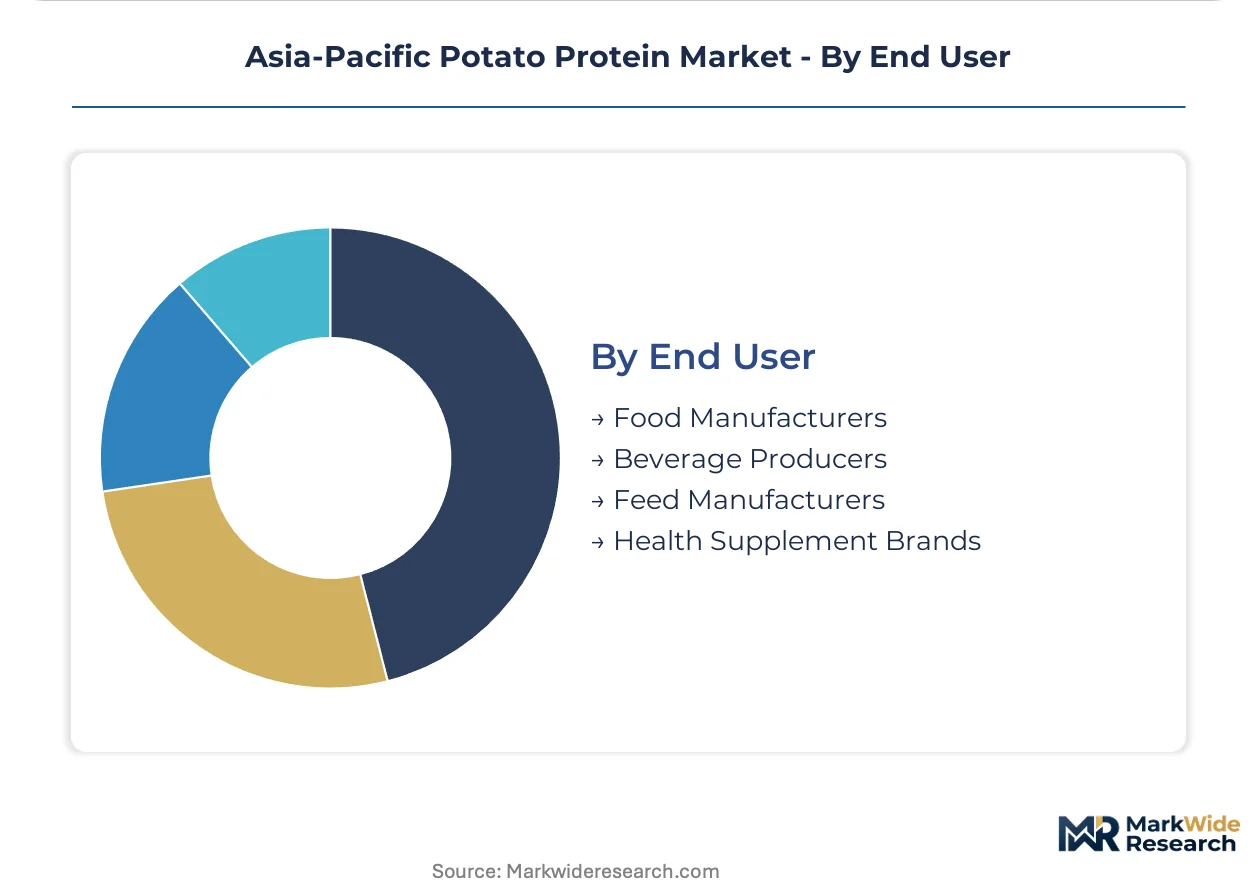
- Food Manufacturers:Large-scale processors in eastern China's food manufacturing corridor around Shanghai and Jiangsu province. These customers demand consistent functional properties for industrial-scale emulsification and texture modification applications.
- Health Supplement Brands:Japanese and South Korean companies pursuing FOSHU and functional food registrations. Regulatory compliance support and certificate of analysis documentation represent critical supplier selection criteria.
- Feed Manufacturers:Cost-optimized procurement for aquaculture and livestock operations. Northern Chinese processors prioritize protein content per unit cost over functional property consistency.
- Beverage Producers:Emerging demand for protein fortification in ready-to-drink formulations. Clarity and solubility specifications limit adoption to premium isolate grades for this application.
Food Manufacturers represent the deepest volume commitment; Health Supplement Brands are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting extraction facility investments toward jurisdictions with streamlined novel food approval pathways and co-product processing incentives. Producers are migrating capacity to exploit compliance-cost gaps between European registration regimes and Asia-Pacific fast-track frameworks.
China
Shandong and Heilongjiang provinces generate concentrated potato starch co-product streams that lower isolate production costs substantially. NMPA's compressed approval timelines for qualified applicants now run under twelve months. The eastern processing corridor around Shanghai and Jiangsu province concentrates food manufacturer demand for emulsification-grade isolates.
Japan
Tokyo and Osaka metro areas anchor sports nutrition formulation demand for FOSHU-eligible protein fortification claims. PMDA's Food for Specified Health Uses framework shapes ingredient approval timelines and marketing positioning. Aging consumer demographics in Kanto and Kansai regions drive hydrolysate adoption for rapid-absorption geriatric nutrition products.
South Korea
Seoul-based health supplement manufacturers specify hydrolysate variants for MFDS functional food labeling compliance. MFDS enforcement of functional food labeling requirements directly influences product positioning strategies. The Seoul Capital Area concentrates contract manufacturing capacity for pre-digested peptide fractions targeting absorption-kinetic claims.
Australia
Melbourne and Sydney nutraceutical brands command clean-label price premiums that justify direct procurement from European extraction facilities. TGA oversight of complementary medicine ingredients shapes supplier qualification requirements. Clean-label bakery applications in Victoria and New South Wales represent primary demand concentration for minimally processed flour grades.
Vietnam
Ho Chi Minh City metro corridors show underdeveloped penetration for plant-based isolates among emerging middle-class protein consumers. The country's national food safety authority governs novel ingredient import registrations with evolving technical specifications. Singapore-based distributors currently intermediate supply for Vietnamese formulators lacking dedicated ingredient sourcing teams.
Asia-Pacific Potato Protein Market Competitive Environment
Capacity expansion dominates the current landscape as starch processors retrofit existing facilities to capture protein recovery economics. The vendor base clusters around European extraction specialists with co-product supply advantages and regional distributors serving price-sensitive feed applications. Three archetypes define competitive positioning: co-product-integrated processors leveraging starch facility economics, premium-grade specialists targeting FOSHU and functional food registrations, and regional traders optimizing logistics for aquaculture feed manufacturers. M&A activity and technology licensing arrangements represent the dominant competitive moves as players seek membrane filtration expertise.
Among European-anchored processors, Coöperatie AVEBE U.A., Roquette Frères, and AGRANA Beteiligungs-AG exemplify the co-product-integrated archetype. AVEBE occupies a position tied to potato starch facility economics. Roquette Frères represents premium-grade specialization for Japanese and South Korean sports nutrition applications. AGRANA Beteiligungs-AG anchors diversified extraction capabilities across multiple plant protein categories. These entities sit within a competitive structure where technical expertise in chromatographic separation and membrane filtration concentrates among established European operators, while regional distributors in Singapore and Shanghai intermediate volume for cost-optimized concentrate grades.
| Leading Market Players |
|---|
| Coöperatie AVEBE U.A. |
| AGRANA Beteiligungs-AG |
| Roquette Frères |
| Kemin Industries, Inc. |
| Bioriginal Food & Science Corp. |
| KMC Ingredients |
| Emsland Group |
| Meelunie B.V. |
| Tereos Group |
| Others |
Value Chain & Pricing Dynamics
Isolate-concentrate grade divergence splits procurement economics across the Asia-Pacific potato protein landscape, with FOSHU-eligible purity thresholds commanding threefold supply chain complexity versus feed-grade concentrate streams. Japanese health supplement manufacturers absorb premium logistics costs for European-sourced isolates, while Shandong aquaculture formulators optimize for truck-freight feedstock from co-located starch facilities.
Pricing Analysis
Distributor margin layers compress 12-18 points between Rotterdam extraction facilities and Osaka formulation labs, while direct-to-OEM channels eliminate intermediary markups for Australian nutraceutical brands contracting AVEBE annual volumes. Pricing stratifies across premium isolate, standard concentrate, and economy feed-grade tiers, with NMPA certification status and ISO-accredited purity validation as primary differentiation drivers. Cost compression in concentrate segments intensifies because fresh potato harvest volatility in Heilongjiang feeds directly into spot-input pricing. Feed manufacturers in northern China exhibit highest price sensitivity; Japanese FOSHU-registered brands demonstrate lowest elasticity due to regulatory compliance switching costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Shanghai food processors and Tokyo sports nutrition brands, while Singapore-based distributors intermediate fragmented Vietnamese and Indonesian formulator demand. Geographic supply concentration rests on Netherlands and Germany for premium isolate extraction, China for concentrate co-product streams, and Australia for minimally processed flour grades. Raw material dependencies draw from Shandong and Heilongjiang potato starch harvests, European membrane filtration equipment, and Japanese enzymatic hydrolysis reagents. Single-source vulnerability concentrates in chromatographic separation technology licensed from German engineering firms. Distribution runs through annual volume contracts for premium tiers, spot procurement for feed applications, and Alibaba 1688 for pilot-scale sampling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific potato protein market functions as a geographic-arbitrage play, exploiting twelve-month NMPA approval timelines versus twenty-four-month European novel food registration cycles to capture margin from China-bound European suppliers.
For Market Incumbents: Cement co-product processing economics through membrane filtration retrofit investments in Shandong and Heilongjiang starch facilities, locking in 15-20 point cost advantages against dedicated protein crop competitors. Defend against emerging precision-fermentation protein substitutes by accelerating FOSHU registration support for Japanese health supplement partners, converting regulatory compliance burden into switching-cost moats.
For New Entrants and Emerging Players: Capture underdeveloped plant-isolate penetration in Ho Chi Minh City and Jakarta metro corridors, where emerging middle-class protein consumption lacks established supplier relationships. Target Vietnamese formulators through Singapore distributor partnerships offering technical support and customs clearance bundling, leveraging established logistics infrastructure without direct facility investment.
For Investors and Strategic Acquirers: Asymmetric upside sits with membrane filtration technology licensors holding captive relationships with Chinese starch processors seeking protein recovery circuit retrofits. Five-to-ten year viability hinges on dual carbon policy alignment accelerating state-backed facility approvals versus precision fermentation cost curves. Watch NMPA enforcement timing on revised novel protein guidelines as inflection indicator for European supplier direct-market-access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Shandong starch processors capture protein recovery economics from existing co-product streams. |
| FOSHU Registration Support | European suppliers secure Japanese health supplement brand loyalty through compliance partnership. |
| Direct Procurement Contracts | Australian nutraceutical brands bypass distributor markups to secure clean-label supply chains. |
| Enzymatic Hydrolysis Scale-Up | South Korean contract manufacturers meet MFDS functional food labeling for geriatric nutrition. |
| Singapore Distribution Partnership | Vietnamese formulators gain technical support and customs clearance for plant-isolate adoption. |
Study Parameters
Multiple input streams — extraction facility production managers, Japanese health supplement regulatory affairs leads, Chinese aquaculture feed procurement officers, and European membrane filtration equipment engineers — were reconciled against customs trade records, NMPA novel food registration databases, FOSHU approval filings, and starch industry co-product recovery reports. Bottom-up capacity assessments from Shandong and Heilongjiang processing clusters were triangulated with top-down demand modeling from Tokyo, Osaka, and Seoul formulation markets.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, modeling segmentation dimensions including purity grade tier, end-use application, distribution channel intensity, and regional regulatory cluster. CAGRs were derived from installed capacity expansion trajectories, NMPA approval velocity assumptions, and substitution elasticity estimates for soy and dairy protein displacement. Forecast inputs incorporated fresh potato harvest cycle volatility, membrane filtration energy efficiency curves, and FOSHU framework expansion scope.
Regulatory enforcement delays, precision fermentation protein cost breakthroughs, and fresh potato harvest failures are the dominant revision risks to baseline projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Dairy Protein Market
Ingredients
North America Cocoa Products Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Potato Granules Market
Ingredients
Sesame Seed Extract Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Arrowroot Starch Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Hemp Seed Peptide Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Organic Pastry Flour Market
Ingredients
Specialty Feed Additives Market
Ingredients
Rose Hips Extract Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
China Cane Sugar Market