
 Instant Tea Premix Consumption Market | 2026-2036
Instant Tea Premix Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Tea Premix Consumption Market Analysis
The capital-intensity divergence between multinational blenders and regional packagers is collapsing as automated dosing and sachet-filling technology becomes accessible at smaller scale. Nestlé S.A. leverages its freeze-drying infrastructure across multiple beverage categories to sustain cost advantages in powdered mix production. Tata Consumer Products Limited anchors its position through backward integration into Assam and Darjeeling tea estates, controlling leaf quality from garden to sachet. Wagh Bakri Tea Group competes on regional palate knowledge, dominating Gujarati and Maharashtrian distribution networks with masala-forward formulations.
Instant tea premix denotes a manufactured beverage base combining spray-dried or freeze-dried tea extract with sweeteners, dairy or non-dairy creamers, and flavoring agents, reconstituted with hot or cold water to deliver standardized taste and caffeine content. Powdered mix occupies the largest volume position due to extended shelf stability and lower logistics cost, while liquid concentrate captures premium margin pools in café and foodservice channels where speed of preparation governs labor economics. Sachets lead household penetration across South Asian markets where single-serve pricing aligns with daily wage purchasing patterns.
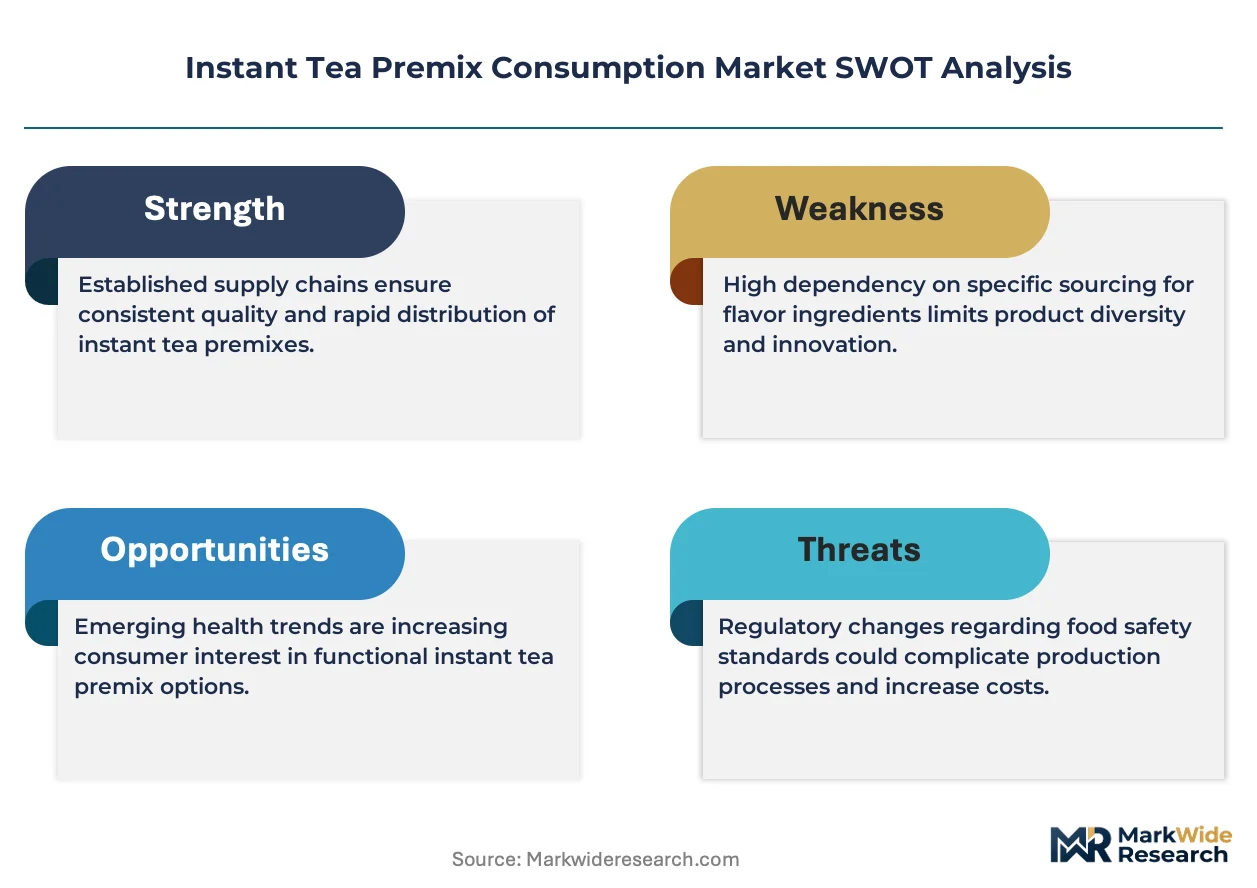
FSSAI mandates on additive disclosure and caffeine labeling in India directly constrain formulation flexibility for brands targeting mass retail. EFSA and FDA parallel frameworks on novel food ingredients and GRAS status for botanical extracts shape which flavor innovations—such as adaptogenic or probiotic-enhanced variants—can cross into European and North American shelves. Stakeholders must monitor evolving front-of-pack labeling rules across multiple jurisdictions to anticipate reformulation costs and preempt market access barriers before compliance deadlines harden.
Market Dynamics
Automated sachet-filling and dosing technology is collapsing the minimum efficient scale for instant tea premix production, eroding the capital-cost advantage that historically separated multinational blenders from regional packagers.
Growth Catalysts
- Corporate pantry modernization:Employers across India and Southeast Asia are upgrading office beverage services, expanding institutional procurement of single-serve premix solutions.
- FSSAI labeling mandates:India's tightening disclosure requirements for pre-mixed beverages are accelerating formulation transparency, pushing compliant brands toward premium positioning.
- Freeze-drying infrastructure reuse:Multi-category beverage manufacturers are redeploying existing spray-drying and freeze-drying assets into tea premix lines, compressing unit economics.
Market Restraints
- Tea leaf price volatility:Input cost swings for Assam and Kenyan auction-grade leaves squeeze margin predictability for non-integrated packagers.
- Supply concentration in South Asia:Garden-level sourcing dependence on Indian and Sri Lankan estates creates climate and geopolitical exposure.
- Technical shelf-life ceilings:Dairy-creamer oxidation limits in hot-fill sachets constrain distribution reach into humid tropical corridors.
Strategic Opportunities
- Adaptogenic and probiotic variants:EFSA novel food pathways and FDA GRAS determinations for botanical extracts open premium positioning in European and North American retail.
- Cold-brew liquid concentrates:Café and foodservice channels are adopting speed-of-preparation formats that command labor-cost arbitrage.
- Direct-to-pantry corporate subscriptions:Technology-enabled replenishment models bypass traditional distributor markups in Indian metropolitan corridors.
Industry Challenges
- Reformulation timeline compression:Front-of-pack labeling rule changes across multiple jurisdictions force simultaneous compliance sprints.
- Flavor chemist scarcity:Formulation expertise for masala-forward and region-specific palates concentrates in Gujarat and Maharashtra.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Tea Premix Consumption Market |
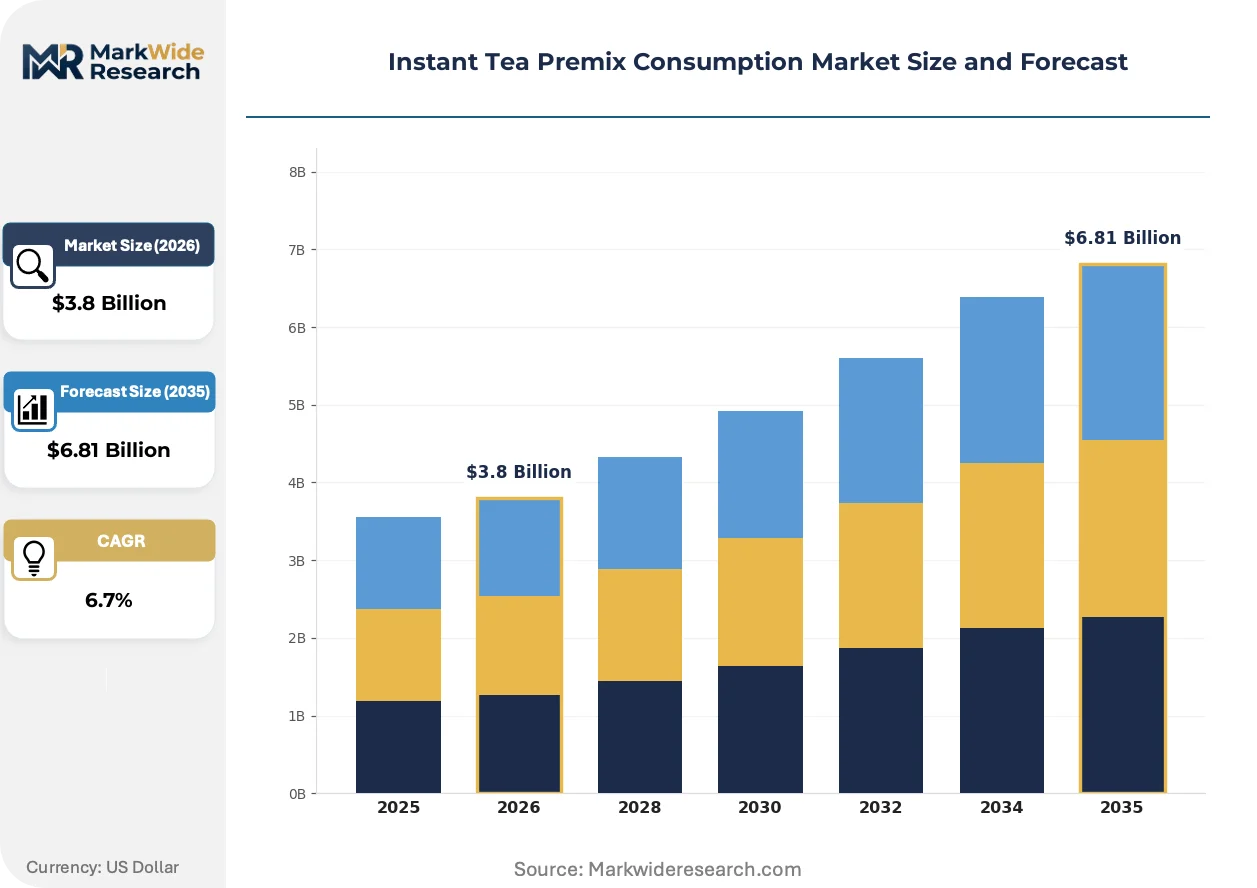
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Mix, Liquid Concentrate, Sachets, Ready-to-Drink Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops End User: Households, Cafés, Restaurants, Offices Flavor Profile: Masala, Lemon, Green Tea, Chai |
| Companies Covered | Bigelow Tea, Whittard of Chelsea, Nestlé S.A., Wagh Bakri Tea Group, Typhoo Tea Ltd., Tata Consumer Products Limited, Dilmah Ceylon Tea Company PLC, Ito En Ltd., Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Tea Premix Consumption Market Emerging Trajectories
Formulation science and packaging automation are converging to compress production scale thresholds while regulatory disclosure mandates reshape competitive positioning.
Micro-encapsulation of volatile flavor compounds is decomposing the traditional trade-off between shelf stability and taste fidelity. Regional packagers in South India are adopting this technology to match multinational sensory profiles. The approach is decomposing the premium tier's historical insulation from mid-market competition.
EFSA's evolving stance on novel food ingredients and caffeine disclosure thresholds is tightening formulation flexibility for brands targeting European retail. Manufacturers must now pre-validate adaptogenic claims through centralized scientific assessment. Premium functional variants face the steepest compliance cost escalation.
Single-serve pricing alignment with daily wage purchasing patterns is concentrating household penetration in urban Indian and Southeast Asian metropolitan corridors. Traditional multi-serve tins are losing shelf space to sachet formats in modern trade. This rotation is most visible in Bangalore, Jakarta, and Ho Chi Minh City convenience networks.
Instant Tea Premix Consumption Market Segmentation
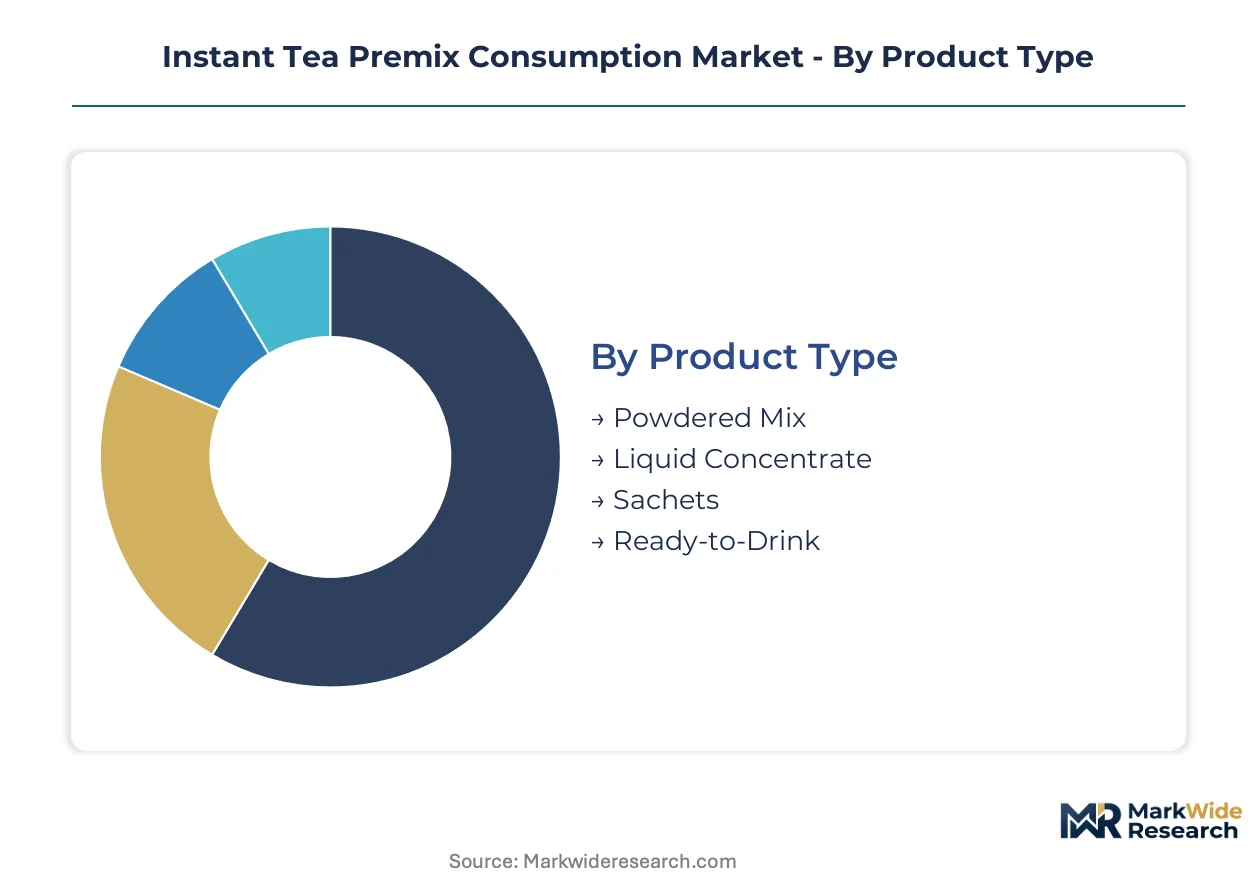
Segmentation in instant tea premix reveals divergent margin structures across formats and channels. Powdered mixes compete on logistics efficiency while liquid concentrates extract premium value from foodservice labor economics. Understanding these divides guides capital allocation between mass-market penetration and margin-rich positioning.
Product Type:
Powdered mixes dominate domestic consumption across South Asian households, while liquid concentrates serve export-oriented café chains in Europe and North America. Sachets bridge both markets with single-serve portability.
- Powdered Mix:Spray-dried or freeze-dried tea extract combined with sweeteners and creamers delivers extended shelf stability. Demand concentrates in Indian and Indonesian households where bulk purchasing aligns with monthly grocery cycles and humidity-resistant storage is essential.
- Liquid Concentrate:Cold-brew or hot-fill extracts requiring dilution before service. European and North American café chains are adopting this format for labor-cost arbitrage, reducing preparation time from three minutes to thirty seconds during peak service windows.
- Sachets:Single-serve packets containing pre-measured powder for individual preparation. Portability drives adoption in Southeast Asian workplace pantries and travel retail.
- Ready-to-Drink:Fully reconstituted beverages in bottles or cartons requiring no preparation. Convenience stores in Thai and Vietnamese urban corridors stock these for immediate consumption.
Powdered Mix holds the largest share; momentum sits with Liquid Concentrate.
Distribution Channel:
Channel selection determines margin capture, with modern trade extracting listing fees while direct digital routes preserve pricing control for specialty variants.
- Supermarkets:Organized retail chains with dedicated beverage aisles and promotional slotting. Indian metros including Mumbai and Delhi see concentrated shelf competition where masala and lemon variants vie for eye-level placement.
- Online Retail:E-commerce platforms and direct-to-consumer portals. Subscription models are gaining traction among Bangalore and Jakarta professionals seeking pantry replenishment without store visits.
- Convenience Stores:Small-format neighborhood shops with limited SKU breadth. Sachet formats dominate these outlets in Ho Chi Minh City and Manila due to price-point accessibility.
- Specialty Shops:Tea-focused retailers and gourmet food stores. Premium green tea and adaptogenic blends find placement here in London, Berlin, and New York boroughs.
Supermarkets retain volume leadership; Online Retail is climbing the fastest.
End User:
User segmentation separates household emotional purchasing from institutional procurement logic, with offices representing the most rapidly expanding contract segment.
- Households:Individual consumers purchasing for home consumption. Indian and Bangladeshi families favor multi-serve tins for daily morning chai rituals.
- Cafés:Independent and chain coffee shops requiring speed and consistency. Liquid concentrates reduce training burden for baristas in Paris and Melbourne specialty cafés.
- Restaurants:Full-service and quick-service food outlets. Standardized taste profiles help Malaysian and Singaporean chains maintain brand consistency across locations.
- Offices:Corporate pantries and co-working spaces. Indian IT corridors in Hyderabad and Pune are upgrading from loose tea to single-serve premix solutions.
Households anchor current demand; Offices show steepest expansion trajectory.
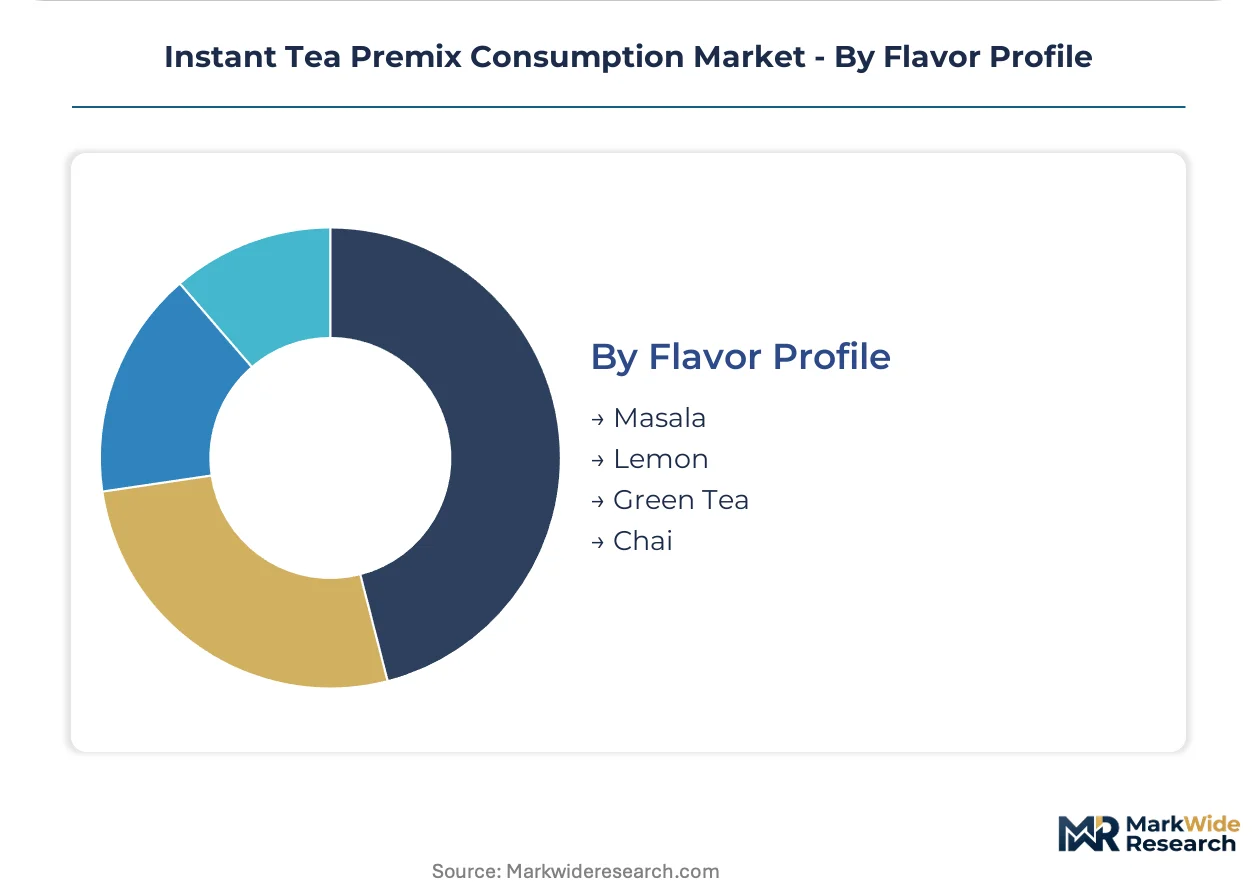
Flavor Profile:
Flavor segmentation maps cultural palate boundaries, with masala formulations concentrated in heritage markets and green tea variants penetrating wellness-positioned channels.
- Masala:Spice-forward blends incorporating cardamom, ginger, clove, and black pepper. Gujarati and Maharashtrian distribution networks sustain dominance through regional recipe fidelity.
- Lemon:Citrus-accented variants for refreshment positioning. Southeast Asian convenience retail favors these for hot-climate consumption.
- Green Tea:Unoxidized leaf extracts with antioxidant marketing claims. German and Japanese wellness retailers allocate premium shelf space to these variants.
- Chai:Milk-forward spiced preparations emphasizing creaminess. North American specialty cafés have adopted this profile for autumn seasonal menus.
Masala commands the largest installed base; Green Tea is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Mumbai and Jakarta convenience networks exceeds that of Berlin or Melbourne specialty channels by a factor of three, reflecting divergent consumption patterns across geographies. This asymmetry shapes where manufacturers deploy premium formulations versus mass-market sachet strategies.
India
Corporate pantry modernization in Hyderabad and Pune drives institutional procurement of single-serve premix solutions. FSSAI labeling mandates on additive disclosure and caffeine content constrain formulation flexibility for mass retail brands. The Wagh Bakri distribution network concentrates in Ahmedabad and Mumbai, where masala-forward formulations dominate Gujarati and Maharashtrian retail corridors.
Indonesia
Humidity-resistant powdered mix demand concentrates in Jakarta and Surabaya household monthly purchasing cycles. The national food and drug regulator enforces pre-mixed beverage safety standards that accelerate import substitution for domestic blenders. Bandung's packaging automation cluster supplies sachet-filling equipment to regional packagers competing with multinational scale.
Germany
Wellness-positioned green tea variants extract premium margins through Berlin and Munich specialty retailers. EFSA novel food pathways for adaptogenic ingredients shape which functional claims survive centralized scientific assessment. The Hamburg foodservice corridor adopts cold-brew liquid concentrates for café labor-cost arbitrage during peak service windows.
United States
Chai-flavored seasonal menus in Brooklyn and Austin specialty cafés drive North American adoption of spiced milk-forward preparations. FDA GRAS determinations for botanical extracts govern which probiotic-enhanced variants reach supermarket shelves. The Pacific Northwest direct-to-consumer subscription channel bypasses traditional distributor markups for pantry replenishment models.
Vietnam
Ready-to-drink bottles command immediate consumption in Ho Chi Minh City convenience networks where single-serve pricing aligns with daily wage purchasing patterns. The Ministry of Health's food safety regulations tighten disclosure requirements for dairy-creamer oxidation limits in tropical distribution. Da Nang's logistics hub enables cold-chain reach into humid central provinces previously constrained by shelf-life ceilings.
Instant Tea Premix Consumption Market Vendor Landscape
Concentration sits with multinational beverage conglomerates leveraging freeze-drying infrastructure across multiple categories, while regional packagers compete on distribution density and palate-specific formulation knowledge. Automated dosing technology has collapsed minimum efficient scale thresholds, eroding historical capital-cost advantages. Three archetypes dominate: integrated tea estate owners controlling leaf quality from garden to sachet, multi-category beverage manufacturers redeploying spray-drying assets, and regional specialists commanding ethnic distribution networks. Competitive moves center on backward integration into Assam and Kenyan auction sourcing, and micro-encapsulation licensing to match multinational sensory profiles.
Within the integrated estate tier, Tata Consumer Products Limited and Dilmah Ceylon Tea Company PLC exemplify upstream control strategies, with the former anchoring position through captive Assam and Darjeeling leaf supply. Nestlé S.A. occupies the multi-category manufacturer archetype, leveraging existing beverage infrastructure for powdered mix cost compression. Wagh Bakri Tea Group represents regional specialization, with distribution dominance in western Indian ethnic corridors built on masala formulation expertise rather than scale.
| Leading Market Players |
|---|
| Bigelow Tea |
| Whittard of Chelsea |
| Nestlé S.A. |
| Wagh Bakri Tea Group |
| Typhoo Tea Ltd. |
| Tata Consumer Products Limited |
| Dilmah Ceylon Tea Company PLC |
| Ito En Ltd. |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Automated sachet-filling scale economies have compressed minimum efficient production thresholds below 500 kilograms per shift, eroding the capital-cost barriers that historically protected multinational blenders and forcing price floors downward across powdered mix tiers.
Pricing Analysis
Customization-premium spreads in masala-forward formulations versus standard lemon variants reach three-to-one multiples in Mumbai and Ahmedabad retail corridors. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy bulk powder levels reflects brand heritage, FSSAI compliance depth, and creamer quality grade. Price erosion runs through economy sachets as Bandung packaging automation clusters equip regional Gujarati packagers with multinational-matching unit economics. Corporate pantry buyers in Hyderabad and Pune show lowest price sensitivity due to subscription contract structures, while convenience store shoppers in Ho Chi Minh City demand single-serve parity with daily wage thresholds.
Supply Chain Analysis
Monsoon-dependent Assam auction corridors and Kenyan Mombasa tea terminals constitute the dominant leaf chokepoint for non-integrated packagers. Raw material dependencies center on spray-dried dairy creamers from New Zealand, Indonesian palm oil derivatives, and Vietnamese flavoring compounds. Tariff exposure on Kenyan auction-grade leaves through Indian port congestion creates margin unpredictability for mid-tier blenders lacking backward integration into Darjeeling estates. Distribution runs through Wagh Bakri's Ahmedabad hub for western Indian ethnic networks and Nestlé's nationwide modern trade penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate pantry replenishment cycles signal cyclical recovery as Indian IT corridor employers upgrade from loose leaf to single-serve premix subscriptions.
For Market Incumbents: Shield masala formulation expertise through micro-encapsulation licensing to regional South Indian packagers adopting multinational sensory matching technology. Deepen backward integration into Assam auction sourcing before climate volatility hardens leaf price ceilings. Channel control through direct-to-pantry corporate subscriptions in Bangalore and Jakarta bypasses distributor markups eroding margin position. For New Entrants and Emerging Players: Anchor in cold-brew liquid concentrate white space serving European café chains seeking labor-cost arbitrage during peak service windows. Target adaptogenic variant development for EFSA novel food pathway pre-validation ahead of functional claim compliance windows. Direct-to-consumer subscription models in Pacific Northwest wellness corridors offer lowest customer acquisition friction against entrenched retail distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated estate owners with captive Assam and Darjeeling supply controlling leaf quality from garden to sachet. Five-to-ten year viability favors backward-integrated mid-caps over pure-play packagers exposed to auction price swings. Watch FSSAI enforcement intensity on additive disclosure as inflection signal for reformulation cost escalation favoring compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-encapsulation Licensing | Regional South Indian packagers match multinational sensory profiles without freeze-drying capital expenditure. |
| Backward Integration into Assam Estates | Tata Consumer Products anchors leaf quality control from garden to sachet through captive Darjeeling supply. |
| Direct-to-Pantry Corporate Subscriptions | Bangalore IT corridor employers bypass traditional distributor markups through technology-enabled replenishment models. |
| Cold-brew Liquid Concentrate Development | Berlin and Munich specialty cafés adopt speed-of-preparation formats commanding labor-cost arbitrage premiums. |
| EFSA Novel Food Pre-validation | Adaptogenic variant developers secure centralized scientific assessment ahead of European retail market access deadlines. |
Methodological Framework
Initial hypotheses were tested against primary input from tea estate operations managers, FSSAI regulatory affairs leads, modern trade category buyers, and corporate pantry procurement officers and refined through secondary validation against customs import records, FSSAI disclosure filings, Nielsen retail audit data, and auction price reports from Assam and Kenyan terminals. Bottom-up channel volume estimates triangulated against top-down macroeconomic consumption proxies.
Variance decomposition across product type, flavor profile, distribution channel, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by base-year share. Industry-specific forecast inputs incorporated FSSAI compliance timeline assumptions and corporate pantry modernization penetration curves.
Decision-makers should treat outputs as directional under stable monsoon patterns and corporate procurement budget continuity; material deviation in Assam auction prices or EFSA novel food pathway delays would warrant model refresh. Practitioners should keep alternative scenarios live as FSSAI enforcement intensity and freeze-drying technology accessibility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Asia-Pacific Organic Tea Market
Tea
Green Tea Market
Tea
Tea Packaging Market
Tea
Matcha Products Market
Tea
Tea Pitchers Market
Tea
Mate Tea Market
Tea
Global Tea Extract Market
Tea
Pyramid Tea Bags Market
Tea
Rooibos Tea Market
Tea
Africa Tea Market
Tea
Oolong Tea Market
Tea
Green Tea Leaves Market
Tea
Tea Infuser Market
Tea
Tea Concentrate Market
Tea
Out of Home Tea Market
Tea
Camellia Sinensis Leaf Extract Market