
 Campesterol Market | 2026-2036
Campesterol Market Size, Share, and Industry Trends Forecast 2026-2036
Campesterol Market Analytics
ISO 22000 food safety management certification is redrawing competitive boundaries in campesterol supply. BASF SE leverages backward integration into vegetable oil refining to secure feedstock cost advantages. Cargill Incorporated anchors its position through global oilseed crushing networks that feed sterol extraction. Arboris LLC specializes in tall oil-derived phytosterols for pharmaceutical-grade applications.
Campesterol is a C-28 plant sterol structurally similar to cholesterol, typically extracted from soybean oil, rapeseed oil, or tall oil pitch through crystallization and molecular distillation processes yielding purities from 85% to 95%. It functions primarily as a cholesterol-lowering agent in functional foods and as a precursor in steroid hormone synthesis. Natural campesterol dominates volume due to established oilseed supply chains, while esterified campesterol commands premium positioning in nutraceutical applications where enhanced bioavailability drives formulation value. Pharmaceutical firms represent the fastest-growing end user category as prescription phytosterol therapies gain traction under novel food and drug interface regulations.
EFSA novel food approvals govern ingredient eligibility across European formulations, while FDA GRAS notifications shape US market access pathways for campesterol-enriched products. REACH compliance requirements constrain synthetic production routes, tilting investment toward bio-based extraction technologies. Stakeholders must monitor evolving pharmacovigilance frameworks that could reclassify phytosterol dosage thresholds between food supplement and drug categories.
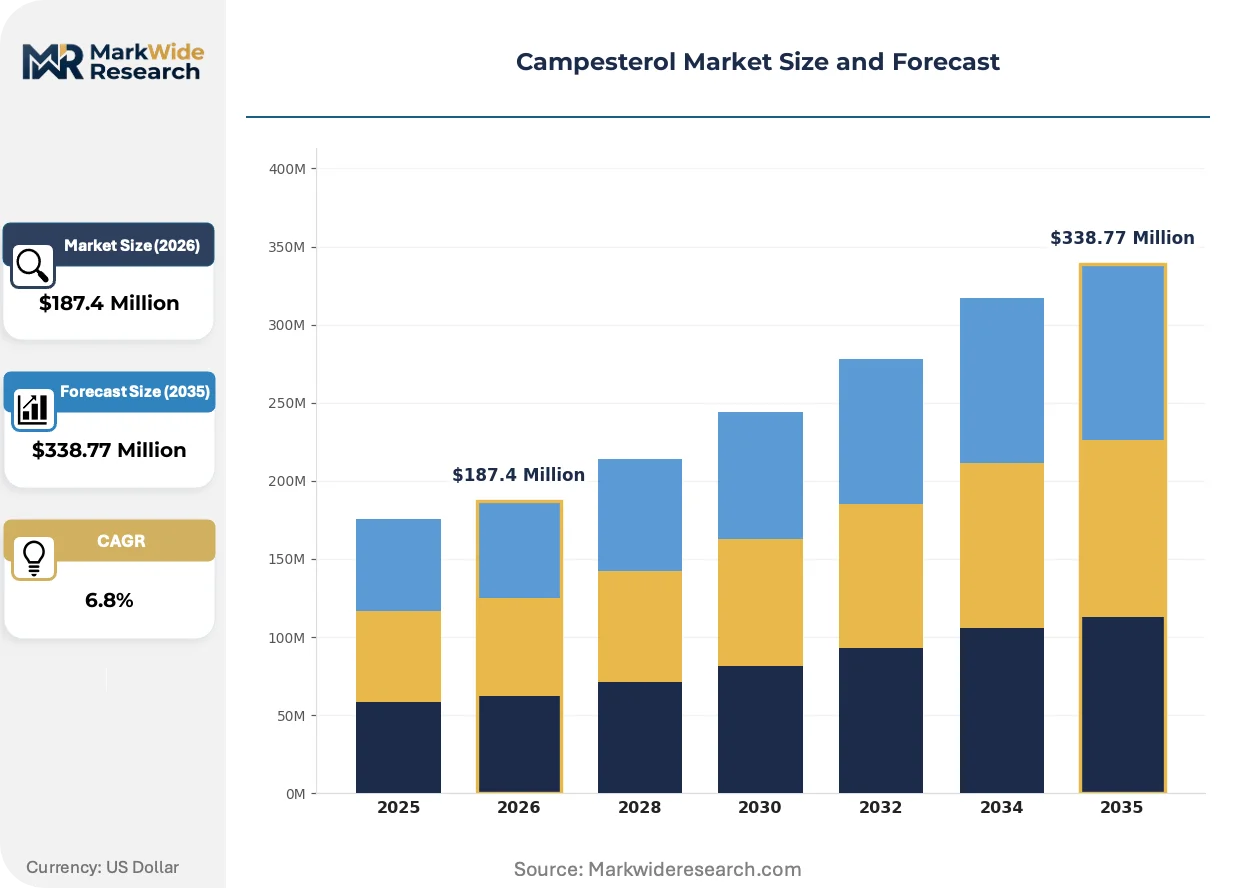
Market Dynamics
EFSA novel food approvals are compressing formulation timelines for cholesterol-lowering applications, forcing pharmaceutical and functional food manufacturers to synchronize R&D cycles with regulatory gatekeeping rather than market pull alone.
Growth Catalysts
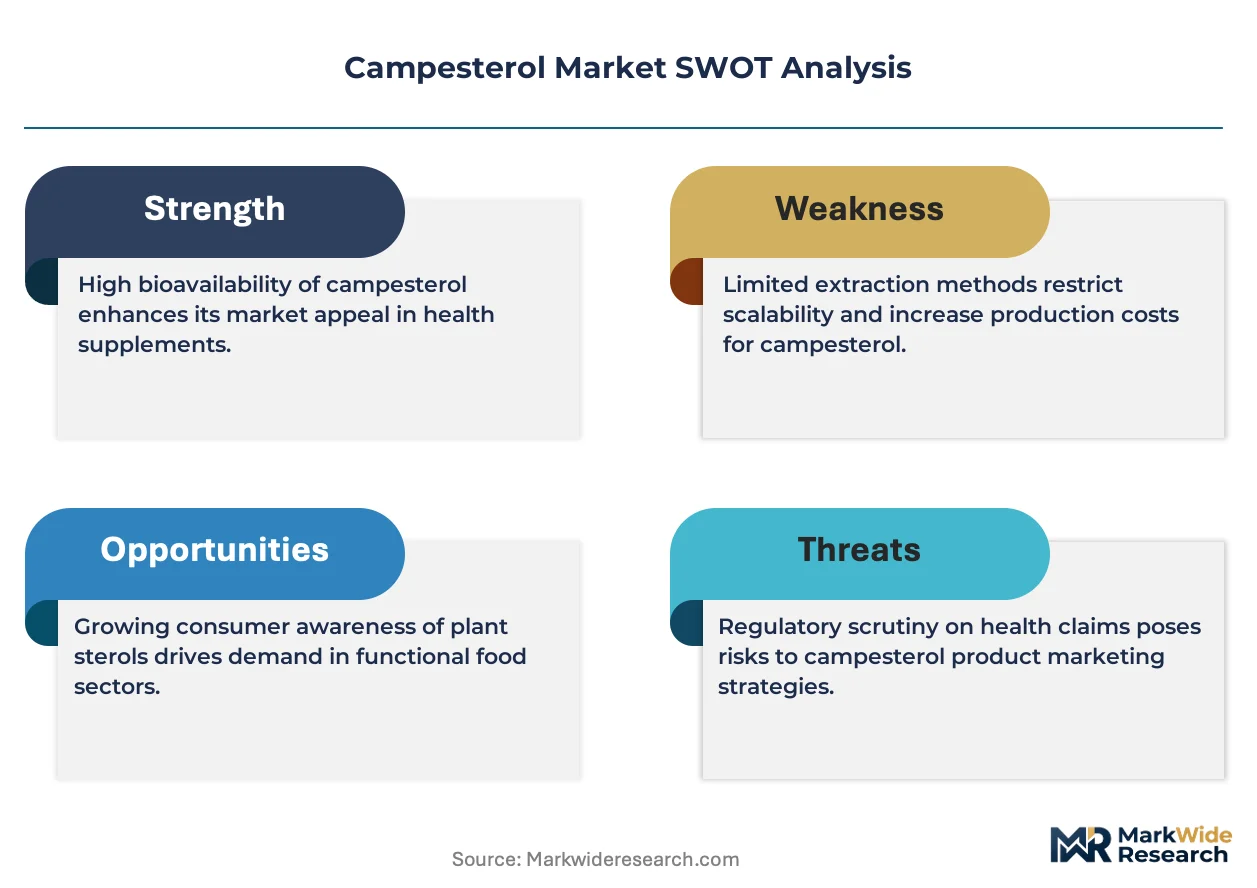
- REACH-compliant bio-based extraction:The EU chemical framework tilts investment toward vegetable oil refining and tall oil pitch processing, accelerating capacity expansion in compliant jurisdictions.
- Pharmaceutical-grade phytosterol demand:Prescription therapies targeting LDL reduction are pulling higher-purity campesterol volumes into steroid hormone synthesis pathways.
- Germany's functional food corridor:Concentrated buyer networks in Bavaria and Baden-Württemberg aggregate procurement volumes that justify dedicated sterol extraction facilities.
Market Restraints
- Soybean oil feedstock volatility:Agricultural commodity swings transmit directly to campesterol production economics, compressing margin predictability for non-integrated processors.
- Tall oil pitch supply concentration:Nordic pulp mill outputs constrain pharmaceutical-grade sterol availability, creating geographic single-point vulnerability.
- Stigmasterol substitution pressure:Competing C-29 phytosterols with equivalent cholesterol-lowering claims capture overlapping formulation slots at lower input cost.
Strategic Opportunities
- India's nutraceutical import substitution:FSSAI functional food category expansions create domestic manufacturing incentives for oilseed-derived phytosterols.
- Esterified campesterol bioavailability premium:Enhanced absorption formulations command price multiples in supplement channels versus raw sterol powders.
- ISO 22000 certification arbitrage:Food safety management credentials unlock institutional procurement contracts that exclude uncertified competitors.
Industry Challenges
- Pharmacovigilance dosage threshold ambiguity:Pending reclassification of phytosterol limits between food supplement and drug categories creates formulation risk for product developers.
- Molecular distillation capex intensity:Purity upgrades to 95%+ pharmaceutical grades require crystallization infrastructure that mid-scale extractors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Campesterol Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Campesterol, Synthetic Campesterol, Esterified Campesterol, Bio-Campesterol Application: Nutraceuticals, Food & Beverages, Pharmaceuticals, Personal Care End User: Food Manufacturers, Dietary Supplement Producers, Cosmetic Companies, Pharmaceutical Firms Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill Incorporated, Arboris LLC, Raisio plc, DuPont de Nemours Inc., Bunge Limited, Pharmachem Laboratories Inc., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Campesterol Market Evolving Landscape
Supercritical CO2 extraction is displacing solvent-based processing in high-purity applications, while regulatory data requirements for novel food dossiers are reshaping how manufacturers document sterol bioequivalence.
Membrane filtration pre-concentration is miniaturizing upstream vegetable oil processing, enabling regional crushers to capture sterol streams previously lost to large-scale refiners. Mid-tier oilseed processors in Poland and Ukraine are adopting skid-mounted membrane units at half the capital intensity of traditional distillation trains. This distributed extraction architecture is compressing feedstock transport distances and eroding the locational advantages of integrated majors.
REACH registration deadlines for synthetic phytosterol intermediates are forcing reformulation strategies across European pharmaceutical contractors. The ECHA substance evaluation workflow now demands chronic toxicity datasets that bio-based extractors bypass through natural product exemptions. Contract manufacturers in the Netherlands and Switzerland are accelerating partnerships with tall oil refiners to secure compliant sterol supply chains ahead of 2026 dossier deadlines.
Direct procurement from oilseed crushing cooperatives is displacing multi-tier distribution for mid-volume functional food manufacturers. German and French dairy alternatives producers now contract soybean processors for specified sterol content rather than purchasing standardized phytosterol blends. This specification-driven sourcing is visible most acutely in oat milk and plant-based yogurt segments, where label claims require traceable sterol provenance from named oilseed varieties.
Campesterol Market Segmentation
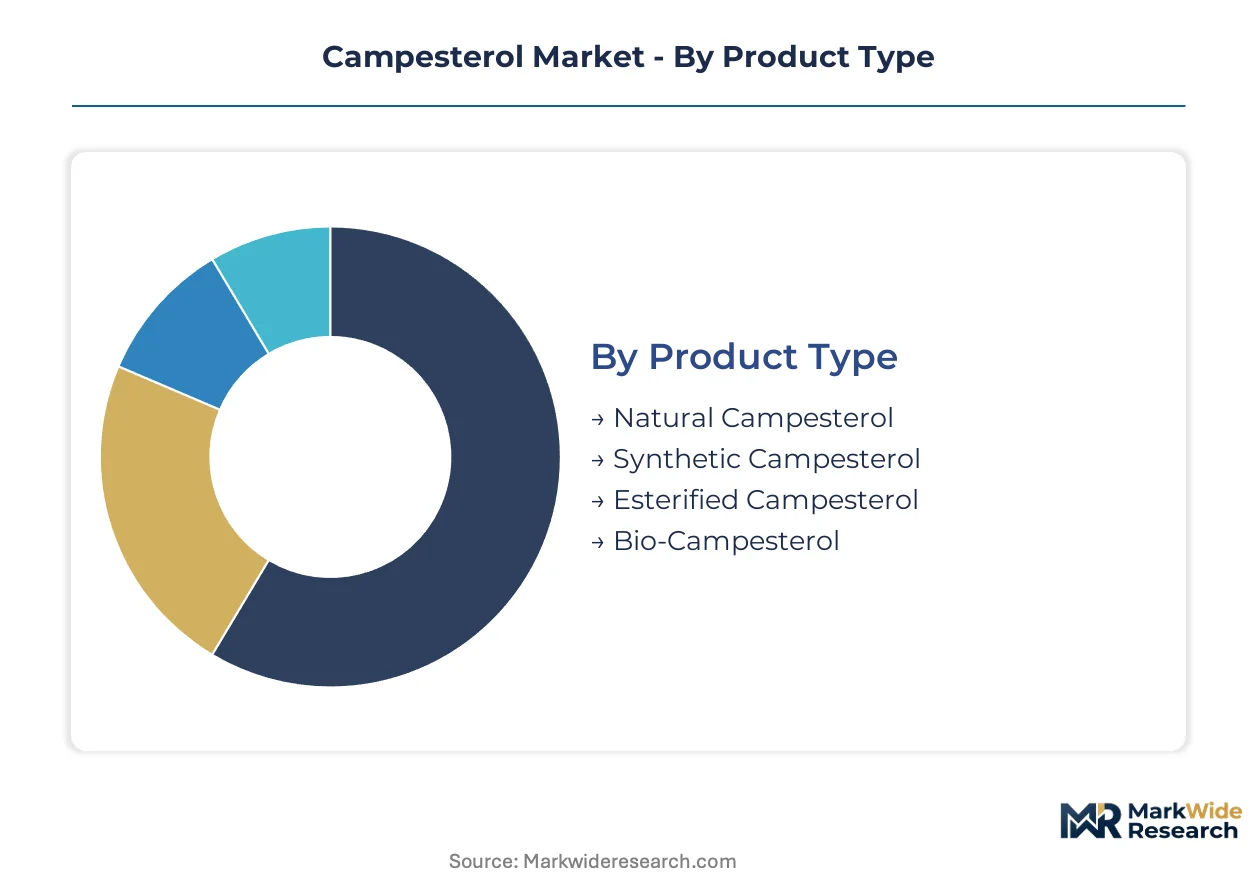
Campesterol's structural similarity to cholesterol creates divergent purity requirements across regulatory jurisdictions. EFSA novel food thresholds and FDA GRAS specifications fragment formulation strategies, forcing manufacturers to align product specifications with destination market rules rather than optimizing for universal application.
Product Type:
REACH registration deadlines and natural product exemptions bifurcate investment toward bio-based extraction routes, compressing synthetic capacity expansion in European jurisdictions.
- Natural Campesterol:Extracted from soybean oil, rapeseed oil, or tall oil pitch through crystallization and molecular distillation, yielding 85-95% purity grades. Demand concentrates in Germany's functional food corridor where BASF SE and Cargill Incorporated leverage integrated vegetable oil refining networks to secure feedstock cost advantages. EFSA novel food approvals favor natural-origin dossiers over synthetic alternatives.
- Esterified Campesterol:Chemically modified to enhance lipid solubility and intestinal absorption, commanding formulation premiums in supplement channels. Nutraceutical applications in France and Germany drive specification requirements as enhanced bioavailability supports differentiated label claims. Pharmacokinetic data requirements for novel food approvals favor esterified forms with documented absorption profiles.
- Synthetic Campesterol:Manufactured through chemical synthesis from sterol precursors, facing REACH chronic toxicity dataset requirements that bio-based routes bypass. Production economics favor large-scale pharmaceutical contractors with dedicated registration resources.
- Bio-Campesterol:Fermentation-derived or enzymatically processed variants emerging in pilot-scale production, targeting sustainability-positioned formulations. Limited commercial volumes constrain current procurement availability.
Established volume favors Natural Campesterol; emerging adoption favors Esterified Campesterol.
Application:
Cost tier differentiation separates commodity-grade functional food incorporation from pharmaceutical-grade steroid synthesis pathways.
- Pharmaceuticals:Prescription therapies targeting LDL reduction pull higher-purity campesterol volumes into steroid hormone synthesis, with purity thresholds of 95%+ required for active pharmaceutical ingredient status. German and French pharmaceutical firms expanding phytosterol procurement under EFSA novel food approvals drive specification intensity.
- Nutraceuticals:Dietary supplement formulations leverage campesterol's cholesterol-lowering claims in capsule, tablet, and softgel delivery systems. India's FSSAI functional food category expansions create import substitution incentives for domestic manufacturing.
- Food & Beverages:Functional food integration spans dairy alternatives, spreads, and fortified beverages where EFSA-approved health claims support consumer positioning. German oat milk and plant-based yogurt segments specify traceable sterol provenance from named oilseed varieties.
- Personal Care:Cosmetic applications exploit campesterol's emollient and anti-inflammatory properties in topical formulations, though volumes remain fractional compared to ingestible categories.
Pharmaceutical applications are climbing the fastest; Food & Beverages anchor current procurement scale.
End User:
Customer type fragmentation separates specification-driven pharmaceutical contractors from price-sensitive commodity food manufacturers.
- Pharmaceutical Firms:Prescription phytosterol therapies under novel food and drug interface regulations demand documented bioequivalence and pharmacovigilance compliance. REACH-compliant supply chains from tall oil refiners in Nordic regions concentrate procurement relationships.
- Food Manufacturers:German and French dairy alternatives producers contract directly with soybean processors for specified sterol content, displacing multi-tier distribution. ISO 22000 certification requirements filter supplier eligibility for institutional procurement.
- Dietary Supplement Producers:Mid-volume buyers aggregate demand through distributor networks, with esterified formulations commanding price multiples over raw sterol powders.
- Cosmetic Companies:Personal care formulators source lower-volume, cosmetic-grade specifications with less stringent purity requirements than pharmaceutical or nutraceutical channels.
Food Manufacturers dominate procurement tonnage; Pharmaceutical Firms drive specification complexity.
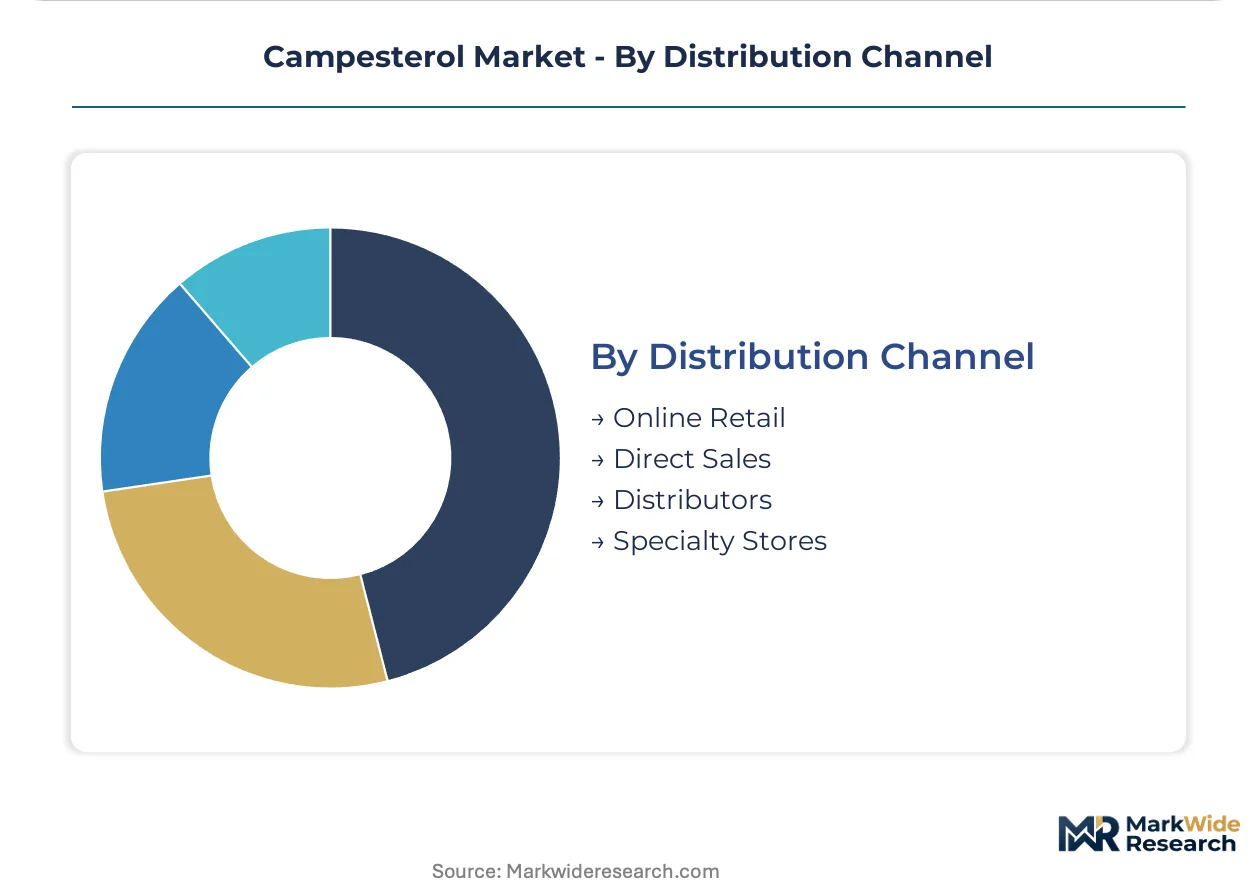
Distribution Channel:
Supply concentration in oilseed processing regions compresses distribution architecture toward direct procurement models.
- Direct Sales:Large-volume pharmaceutical and functional food manufacturers contract directly with integrated vegetable oil refiners and tall oil processors, eliminating margin layers. German and French buyers in Bavaria and Baden-Württemberg aggregate volumes justifying dedicated sterol extraction facilities.
- Distributors:Mid-tier nutraceutical and cosmetic buyers rely on specialized chemical distributors for smaller lot sizes and technical support, particularly in markets lacking integrated processing infrastructure.
- Online Retail:Supplement-grade campesterol powders and finished formulations reach end-consumers and small-scale formulators through B2B and B2C e-commerce channels.
- Specialty Stores:Health food retailers and professional supplement dispensaries carry finished products with campesterol content, representing minimal volume in the ingredient supply chain.
Direct Sales capture pharmaceutical and large food manufacturing volumes; Distributors serve mid-tier fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food approvals and REACH compliance requirements are concentrating campesterol investment in jurisdictions with established vegetable oil refining infrastructure and regulatory clarity.
Germany
Pharmaceutical firms in Bavaria and Baden-Württemberg are expanding phytosterol procurement for cholesterol-lowering drug formulations. EFSA novel food approvals govern ingredient eligibility across European formulations, compressing development timelines. BASF SE maintains integrated supply positions through backward integration into vegetable oil refining networks in these southern industrial clusters.
France
Dairy alternatives producers specify traceable sterol provenance from named oilseed varieties for oat milk and plant-based yogurt segments. ANSM pharmacovigilance frameworks monitor phytosterol dosage thresholds between food supplement and drug categories. The Île-de-France region anchors formulation R&D for prescription therapies targeting LDL reduction.
United States
FDA GRAS notifications shape market access pathways for campesterol-enriched products in functional foods and dietary supplements. Pharmachem Laboratories Inc. occupies positions within the contract manufacturing landscape. Midwest soybean processing corridors in Iowa and Illinois feed sterol extraction volumes for domestic nutraceutical channels.
India
FSSAI functional food category expansions create domestic manufacturing incentives for oilseed-derived phytosterols. Import substitution policies accelerate local crushing capacity for specified sterol content procurement. Maharashtra and Gujarat host emerging extraction facilities serving mid-volume dietary supplement producers.
China
SAMR novel food registration requirements parallel EFSA dossier complexity for phytosterol health claims. Yangtze River Delta refiners process soybean and rapeseed oil streams for regional nutraceutical manufacturers. Zhejiang and Jiangsu provinces concentrate membrane filtration adoption for distributed sterol capture.
Campesterol Market Competitive Landscape
Player mix skews toward integrated agricultural processors with captive oilseed supply chains and specialized phytosterol extractors serving pharmaceutical-grade specifications. Market structure exhibits tiered concentration: three to four multinational chemical and grain conglomerates control upstream feedstock access, while mid-scale tall oil refiners and regional crushers fragment downstream extraction. Strategic archetypes include backward-integrated vegetable oil majors, Nordic pulp-derivative specialists, and contract manufacturers with REACH registration capabilities. Dominant competitive moves center on ISO 22000 certification arbitrage for institutional procurement eligibility and membrane filtration technology licensing to regional crushers.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated processor archetype through upstream control over vegetable oil refining networks. Cargill Incorporated, a US-based agricultural processor, anchors the global oilseed crushing vector that feeds sterol extraction infrastructure. Arboris LLC represents the tall oil-derived specialist tier, occupying positions in pharmaceutical-grade phytosterol supply chains. These three entities illustrate the competitive spectrum from commodity-scale feedstock dominance to purity-focused extraction specialization.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Arboris LLC |
| Raisio plc |
| DuPont de Nemours Inc. |
| Bunge Limited |
| Pharmachem Laboratories Inc. |
| The Lubrizol Corporation |
| Others |
Value Network & Pricing Analysis
Stigmasterol substitution in functional food formulations simultaneously redraws supply geography toward Nordic tall oil corridors and compresses pricing premiums for non-pharmaceutical campesterol grades. This input displacement forces processors to choose between margin sacrifice in commodity tiers or capital-intensive purity upgrades for prescription-grade positioning.
Pricing Analysis
Cost-plus contracts indexed to soybean oil futures dominate procurement between German pharmaceutical firms and integrated refiners. Price differentiation separates ISO 22000-certified pharmaceutical grades from uncertified commodity sterol powders, with the latter facing intensifying cost compression from stigmasterol alternatives. Food manufacturers exhibit highest price sensitivity, while prescription therapy developers absorb premiums for documented bioequivalence dossiers.
Supply Chain Analysis
Germany, France, and the Nordic region anchor pharmaceutical-grade sterol production through integrated vegetable oil refining and tall oil pitch processing. Feedstock dependencies rest on soybean crushing volumes in Bavaria, rapeseed oil streams in Baden-Württemberg, and pulp mill derivatives from Scandinavian suppliers. Single-source vulnerability concentrates in Nordic tall oil pitch availability, while distribution runs through direct procurement contracts for large-volume buyers and specialized chemical distributors for mid-tier nutraceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Campesterol demand sits in early-cycle expansion as prescription phytosterol therapies gain formulary traction under novel food and drug interface regulations. Penetration remains below saturation thresholds across functional food and pharmaceutical synthesis applications.
For Market Incumbents: Fortify backward integration into vegetable oil refining to neutralize feedstock cost volatility from soybean commodity swings. Prioritize ISO 22000 certification renewal ahead of institutional procurement eligibility deadlines, while expanding membrane filtration licensing to regional crushers to preempt distributed extraction competition.
For New Entrants and Emerging Players: Mid-volume dietary supplement producers in India represent an underserved service layer where FSSAI functional food category expansions create domestic manufacturing incentives. Target Maharashtra and Gujarat for toll extraction partnerships with emerging oilseed crushers, leveraging esterified formulation capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors tall oil-derived specialists with REACH registration capabilities and pharmaceutical-grade purity infrastructure. Long-term viability over the next decade hinges on regulatory arbitrage between food supplement and drug classification thresholds. Watch EFSA pharmacovigilance dosage threshold decisions as the critical inflection signal for reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Bio-Based Extraction | ECHA substance evaluation workflows favor natural product exemptions over synthetic routes. |
| Membrane Filtration Technology Licensing | Polish and Ukrainian crushers adopt skid-mounted units to capture sterol streams. |
| ISO 22000 Certification Investment | Food safety credentials unlock institutional procurement contracts excluding uncertified competitors. |
| Direct Procurement Contracting | German dairy alternatives producers specify traceable sterol provenance from named oilseed varieties. |
| Esterified Formulation Development | Enhanced bioavailability commands price multiples in supplement channels versus raw powders. |
Research Methodology
Initial hypotheses were tested against primary input from phytosterol extraction plant managers, pharmaceutical procurement leads, regulatory affairs directors at functional food manufacturers, and tall oil refinery technical directors, then refined through secondary validation against EFSA novel food dossiers, REACH registration databases, FSSAI category notifications, and customs trade data for oilseed-derived sterol flows. Bottom-up capacity estimates from individual extraction facilities were triangulated against top-down demand projections from end-use consumption patterns.
Variance decomposition across the projection horizon isolates feedstock price volatility, regulatory reclassification probability, and substitution elasticity as primary uncertainty sources. Segmentation modeling spans product type tiers, application purity requirements, end-user specification intensity, and regional regulatory clusters. CAGRs were derived from normalized growth rate distributions fitted to historical adoption curves in comparable nutraceutical ingredient markets, with pharmaceutical-grade demand trajectories calibrated against steroid hormone synthesis volume trends.
Forecasts assume regulatory continuity in EFSA novel food frameworks and FDA GRAS notification pathways; material policy shifts toward stricter pharmacovigilance thresholds or synthetic sterol restrictions would require re-modeling. Specific risks include soybean oil commodity volatility, Nordic tall oil supply disruption, and stigmasterol formulation substitution acceleration. Recalibration cycles align with material shifts in EFSA dosage threshold determinations and REACH dossier deadline outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Edible Oil Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Isoamyl Laurate Market
Ingredients
Farnesene Market
Ingredients
Hops Derivative Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Whey Permeate Market
Ingredients
Europe Protein Market
Ingredients
Plant Extracts Market
Ingredients
Corn Oil Market
Ingredients
Potato Flour Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Cocoa Fiber Market
Ingredients
Macleaya Cordata Extract Market