
 United States Corn Glucose Market | 2026-2036
United States Corn Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
United States Corn Glucose Market Intelligence
Processing-plant operator shortages across the corn wet-milling belt is redrawing where capacity expansions prove viable. Cargill Inc. leverages its captive corn supply and ethanol co-location to sustain cost advantages in dextrose production. Ingredion Inc. anchors its position through specialty starch and sweetener R&D facilities in the Midwest. Archer Daniels Midland competes on sheer grind volume, operating multiple refineries with integrated syrup and starch output.
Corn glucose encompasses refined carbohydrate derivatives extracted from maize starch through enzymatic hydrolysis, typically yielding syrups with defined dextrose equivalent values between 20 and 95 for controlled sweetness and browning functionality. Manufacturers employ acid-enzyme or dual-enzyme processes to achieve specific saccharide profiles for binding, fermenting, or crystallization purposes. High fructose corn syrup retains dominant volume share within the product type dimension, though dextrose monohydrate gains share in pharmaceutical-grade applications requiring tighter purity specifications. Food and beverages absorbs the largest application volume, while the nutrition sector within end users shows fastest structural growth as sports and medical nutrition formulations expand.
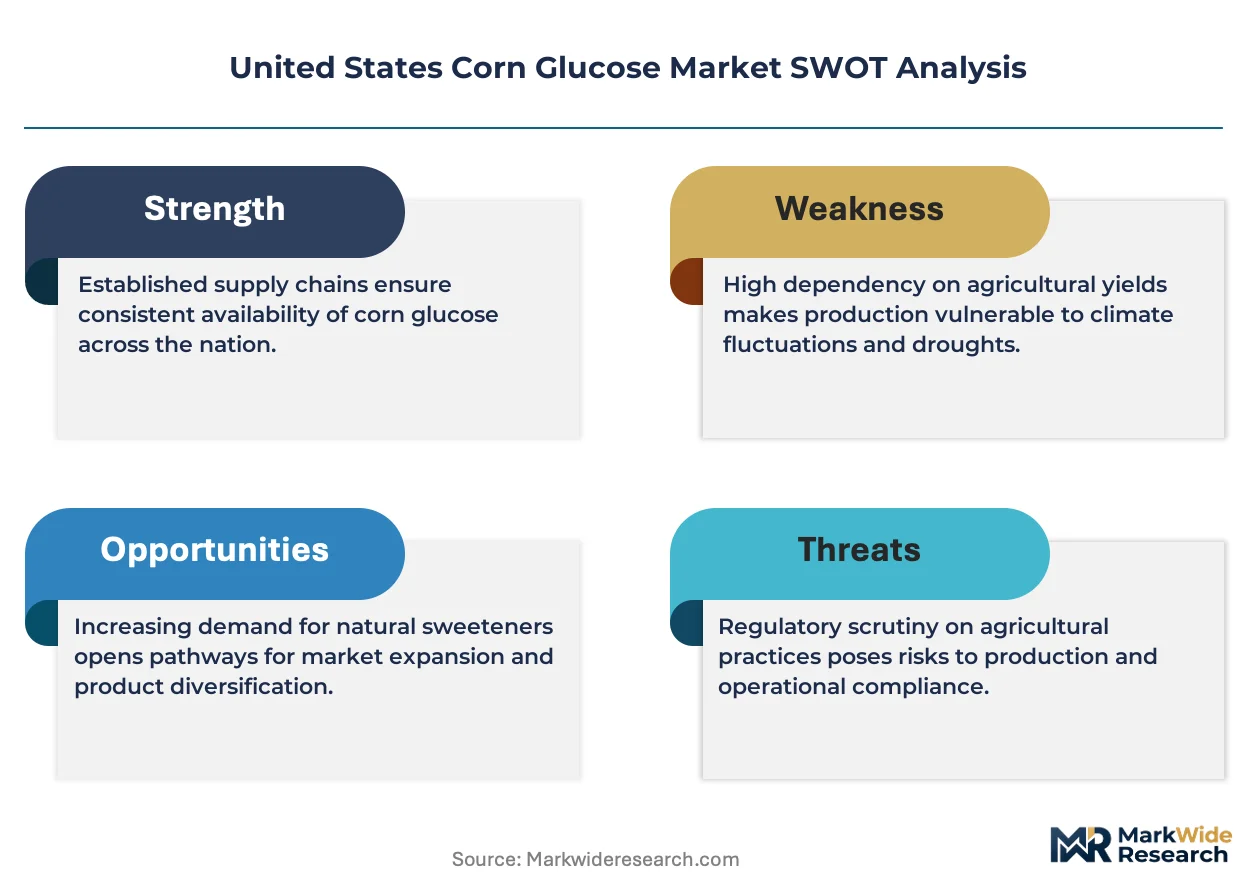
The FDA governs corn glucose labeling under food additive and GRAS frameworks, while the USDA oversees biobased product classifications affecting industrial starch applications. EPA renewable fuel standards indirectly influence corn allocation between ethanol and sweetener processing streams. State-level environmental permits in Iowa and Illinois constrain new wet-milling capacity, tightening effective supply. Stakeholders must weigh enzyme technology investments against regulatory pressure on added sugars when allocating capital across product lines.
Market Dynamics
The FDA's updated nutrition labeling requirements are forcing food manufacturers toward lower-sugar reformulations, redirecting corn glucose demand from conventional sweeteners toward clean-label binding and browning agents. Processing capacity concentrates in the Midwest corn belt where wet-milling infrastructure clusters near raw material supply.
Growth Catalysts
- Clean-label formulation mandates:Food manufacturers are expanding corn glucose use in reduced-sugar products to maintain functionality while meeting FDA disclosure requirements.
- Ethanol co-location economics:Corn wet-milling facilities integrated with ethanol plants capture shared infrastructure and captive feedstock supply across Iowa and Illinois.
- Medical nutrition demand:Sports and clinical nutrition formulations are absorbing dextrose monohydrate for rapid glycemic response applications.
Market Restraints
- Input cost volatility:Corn futures price swings directly compress wet-milling margins, with feedstock representing the dominant cost structure component.
- Supply concentration risk:Iowa and Illinois environmental permits constrain new capacity additions, tightening effective supply availability.
- Substitution threat:Tapioca and rice-derived glucose syrups compete for clean-label positioning in premium food applications.
Strategic Opportunities
- Pharmaceutical-grade dextrose:USP-grade crystallization capacity expansion addresses tightening purity specifications in injectable and oral dosage forms.
- Biobased product classification:USDA BioPreferred program incentives support industrial starch applications in packaging and adhesives.
- Enzyme technology convergence:Dual-enzyme hydrolysis systems paired with membrane filtration are opening specialty saccharide profiles for fermentation feedstocks.
Industry Challenges
- Processing-plant operator shortages:Skilled technician availability across the corn wet-milling belt is redrawing where capacity expansions prove viable.
- Regulatory compliance timelines:State-level environmental permitting in Iowa and Illinois extends project development cycles by 18-24 months.
- Legacy equipment integration:Retrofitting acid-enzyme systems with continuous chromatography separation creates operational friction at established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Corn Glucose Market |
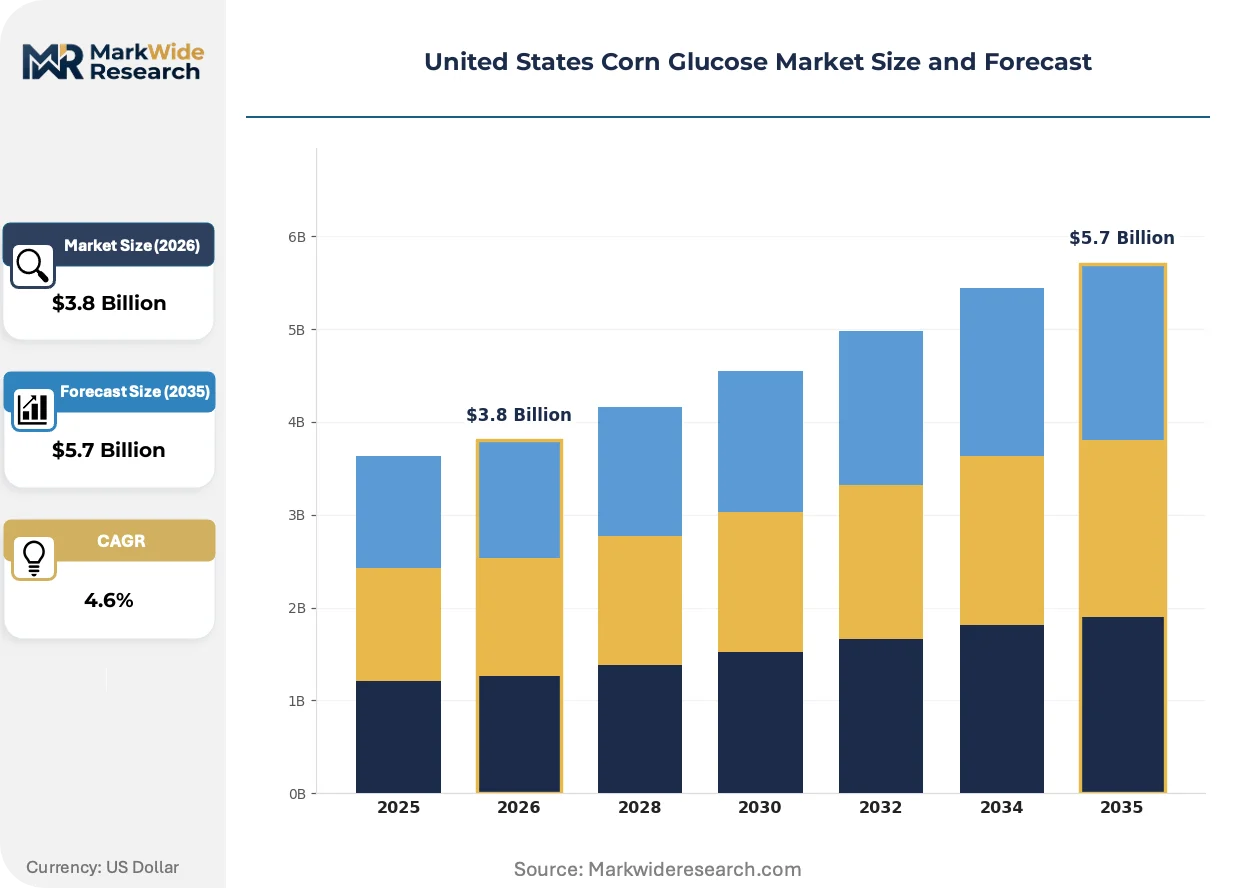
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
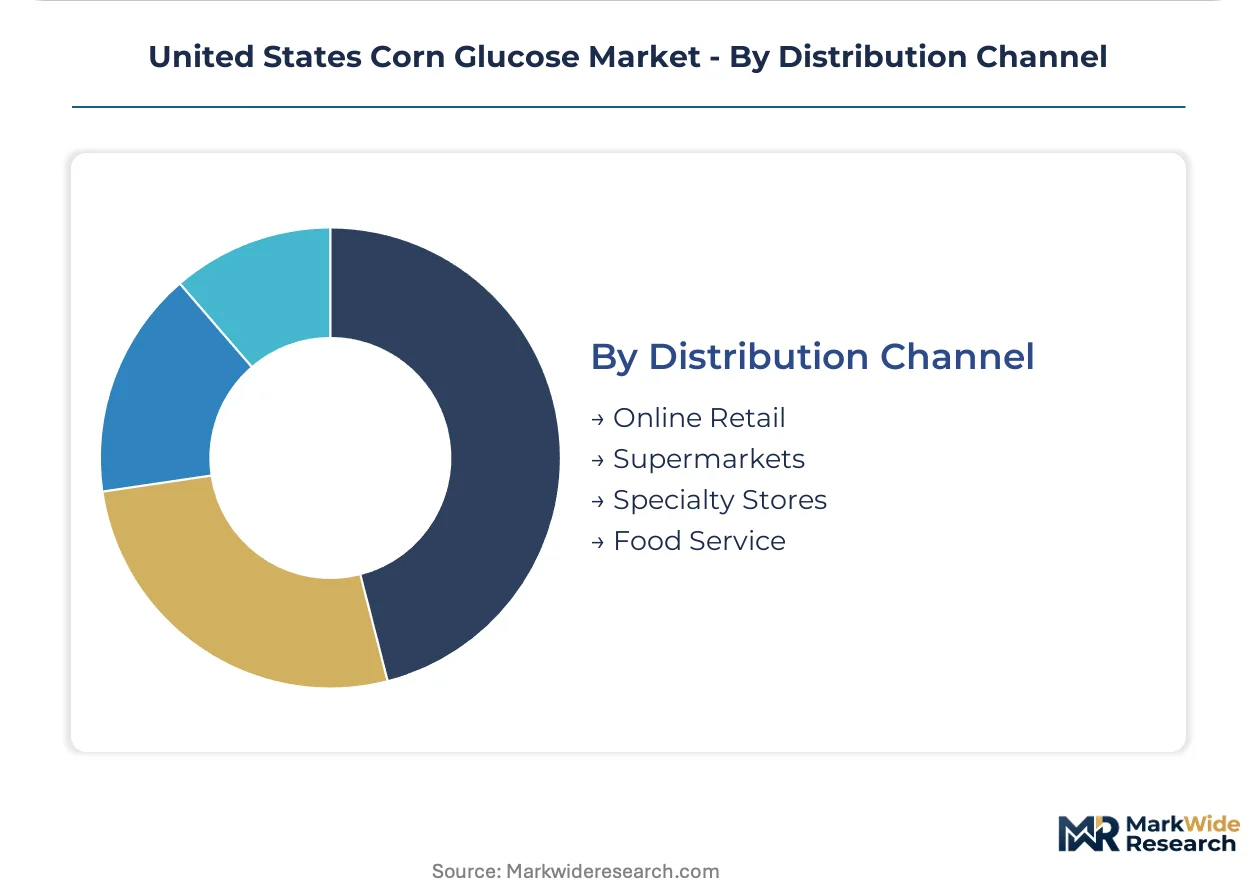
| Segmentation | Product Type: Corn Syrup, High Fructose Corn Syrup, Dextrose, Corn Starch Application: Food & Beverages, Pharmaceuticals, Cosmetics, Animal Feed End User: Food Manufacturers, Beverage Companies, Bakeries, Nutrition Sector Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Roquette Freres, Tereos S.A., Cargill Inc., Louis Dreyfus Holding B.V., Wilmar International Limited, Ingredion Inc., Global Sweeteners Holding Ltd., Bunge Ltd, Archer Daniels Midland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Corn Glucose Market Strategic Shifts & Innovations
Continuous chromatography and membrane filtration systems are compressing saccharide separation costs while enzyme engineering opens novel dextrose equivalent profiles. These advances intersect with regulatory pressure on added sugars and shifting procurement patterns among consolidated food manufacturers.
Membrane filtration technology is miniaturizing plant footprints while maintaining throughput, enabling modular capacity additions at existing wet-milling sites. Mid-sized food manufacturers are adopting these systems to access specialty glucose syrups without committing to greenfield construction. The technology is compressing capital requirements for product line diversification, particularly for dextrose monohydrate crystallization.
The FDA's updated nutrition facts label regulations are mandating added sugars disclosure, accelerating reformulation toward functional glucose applications that avoid the added sugars classification. Food manufacturers are redirecting procurement toward high-maltose corn syrups for browning and binding functionality. This regulatory friction most affects beverage and baked goods segments, where technical teams are rebalancing sweetness contribution against clean-label positioning.
Consolidated food manufacturers are unbundling after-sales technical service from commodity glucose supply contracts, treating formulation support as a separately negotiated value-add. This procurement model change disrupts traditional full-service relationships between wet-milling operators and regional food processors. The shift is most visible in the Midwest, where Cargill and Ingredion field technical service teams independent of commodity sales operations.
United States Corn Glucose Market Segmentation
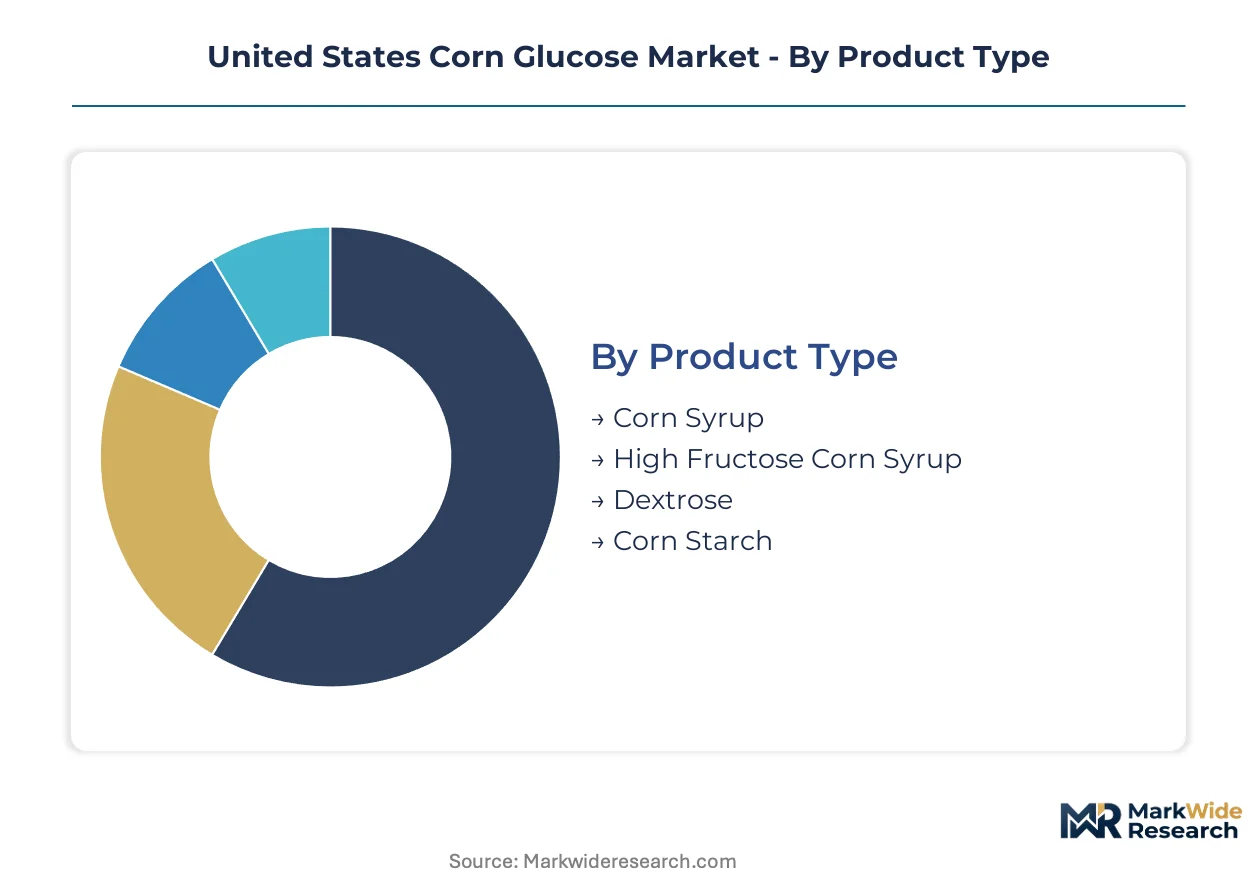
Segmentation reveals how FDA disclosure requirements and state-level environmental constraints reshape procurement patterns across the corn glucose value chain. Distinct product specifications, application purity standards, and channel economics determine where wet-milling operators capture margin.
Product Type:
FDA GRAS classifications and USDA BioPreferred eligibility create divergent compliance burdens across refined carbohydrate derivatives.
- High Fructose Corn Syrup:Enzymatic isomerization yields 42% or 55% fructose content for calibrated sweetness intensity. Beverage manufacturers in Texas and Georgia reformulate around added-sugar disclosure thresholds, compressing conventional HFCS volumes while elevating demand for reduced-fructose variants.
- Dextrose:Crystalline monohydrate and anhydrous forms meet USP purity specifications for pharmaceutical and medical nutrition applications. Sports nutrition formulators in Colorado and Utah specify rapid glycemic response dextrose for recovery formulations, tightening pharmaceutical-grade supply.
- Corn Syrup:Acid-enzyme hydrolysis produces defined dextrose equivalent syrups for browning and binding functionality.
- Corn Starch:Native and modified starches serve industrial biobased applications under USDA certification frameworks.
Established volume favors High Fructose Corn Syrup; emerging adoption favors Dextrose.
Application:
End-use purity requirements stratify manufacturing investments and facility certifications.
- Food & Beverages:FDA nutrition labeling mandates drive reformulation toward functional glucose applications that avoid added-sugar classification. Midwest bakeries and national beverage brands redirect procurement toward high-maltose syrups for Maillard browning without sweetness contribution.
- Pharmaceuticals:USP-grade dextrose monohydrate serves injectable solutions and oral dosage forms requiring endotoxin-controlled crystallization. Contract manufacturers in New Jersey and North Carolina specify tighter purity certificates, constraining qualified supplier pools.
- Cosmetics:Humectant and film-forming properties drive corn-derived polyol demand in personal care formulations.
- Animal Feed:Liquid and dried corn co-products provide fermentable energy in livestock rations across Iowa and Nebraska operations.
Volume concentration sits with Food & Beverages; steepest expansion trajectory belongs to Pharmaceuticals.
End User:
Procurement scale and technical service requirements fragment customer relationships across the value chain.
- Food Manufacturers:Consolidated CPG operators unbundle commodity supply from formulation support, treating technical service as separately negotiated. National brands negotiate multi-year dextrose equivalent specifications with dedicated plant capacity allocations.
- Nutrition Sector:Sports and clinical nutrition brands specify rapid-dissolution dextrose for glycemic management applications. Formulators in Utah and California demand certificate-of-analysis documentation exceeding standard food-grade requirements.
- Beverage Companies:Carbonated and ready-to-drink brands balance sweetness reduction against mouthfeel maintenance in reformulated portfolios.
- Bakeries:Regional and artisanal operations procure syrup in tote and drum quantities through distributor networks.
Contract scale favors Food Manufacturers; specification intensity favors Nutrition Sector.
Distribution Channel:
Logistics economics and order minimums determine channel viability for different customer scale tiers.
- Food Service:Broadline distributors consolidate corn syrup procurement for restaurant and institutional accounts. Sysco and US Foods route tanker deliveries through regional redistribution centers, capturing volume aggregation efficiencies.
- Online Retail:E-commerce platforms serve small-scale food manufacturers and specialty bakeries with packaged glucose products. Amazon Business and ingredient-specific marketplaces reduce minimum order thresholds for regional processors.
- Supermarkets:Club store and grocery retail channels move consumer-packaged corn syrup for home baking applications.
- Specialty Stores:Restaurant supply and bakery equipment dealers stock technical-grade syrups for professional accounts.
Volume throughput favors Food Service; accessibility gains favor Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling mandates and USDA biobased certification frameworks anchor demand patterns across the United States. Wet-milling capacity clusters in the Midwest corn belt, with state-level environmental permitting creating supply constraints that reshape regional procurement dynamics.
Midwest Corn Belt
Ethanol co-location economics dominate wet-milling investment decisions across Iowa and Illinois. State environmental permits in these states extend project timelines by 18-24 months, tightening effective supply availability. Processing infrastructure in Cedar Rapids and Decatur captures shared feedstock logistics and captive corn supply for integrated dextrose production.
Southeast
Beverage manufacturers in Georgia and Florida reformulate around added-sugar disclosure thresholds, compressing conventional HFCS demand while elevating reduced-fructose variants. FDA enforcement of updated nutrition facts labels accelerates technical service unbundling from commodity contracts. Atlanta-based CPG operators negotiate multi-year dextrose equivalent specifications with dedicated plant capacity allocations.
Mountain West
Sports nutrition formulators in Colorado and Utah specify rapid glycemic response dextrose for recovery applications, tightening pharmaceutical-grade supply chains. Certificate-of-analysis documentation requirements exceed standard food-grade specifications for these nutrition sector buyers. Denver and Salt Lake City clusters absorb expanding dextrose monohydrate volumes for clinical and athletic formulations.
Northeast Corridor
Contract pharmaceutical manufacturers in New Jersey and North Carolina specify USP-grade endotoxin-controlled crystallization for injectable solutions. Qualified supplier pools constrain procurement options as purity specifications tighten. Newark and Raleigh-Durham facilities drive demand for pharmaceutical-grade dextrose in oral dosage and parenteral applications.
Pacific Coast
Clean-label food manufacturers in California source tapioca and rice-derived glucose syrups for premium positioning against conventional corn derivatives. USDA BioPreferred program incentives support industrial starch applications in packaging and adhesives. Los Angeles and San Francisco Bay Area formulators balance functionality requirements against non-GMO and allergen-free procurement preferences.
United States Corn Glucose Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the corn glucose value chain. The market exhibits tiered concentration with integrated agribusiness conglomerates commanding volume share while specialty ingredient specialists capture premium positioning. Three archetypes dominate: captive-feedstock wet-millers with ethanol co-location, R&D-anchored specialty sweetener developers, and diversified global traders with multi-origin sourcing. Competitive moves center on enzyme technology licensing for novel saccharide profiles and modular membrane filtration capacity additions at existing sites.
Among integrated agribusiness operators, Cargill Inc., Archer Daniels Midland, and Ingredion Inc. exemplify distinct strategic positions. Cargill represents the captive-feedstock archetype with ethanol co-location advantages. Archer Daniels Midland anchors the scale-driven tier through sheer grind volume across multiple refineries. Ingredion occupies the specialty R&D position with dedicated starch and sweetener development facilities. These three structures illustrate how feedstock control, manufacturing scale, and technical service capabilities segment competitive positioning in FDA-regulated food and pharmaceutical-grade markets.
| Leading Market Players |
|---|
| Roquette Freres |
| Tereos S.A. |
| Cargill Inc. |
| Louis Dreyfus Holding B.V. |
| Wilmar International Limited |
| Ingredion Inc. |
| Global Sweeteners Holding Ltd. |
| Bunge Ltd |
| Archer Daniels Midland |
| Others |
Cost & Logistics Intelligence
FDA GRAS certification tiers gate both supplier qualification and price stratification across the United States corn glucose market. USP-grade pharmaceutical dextrose commands substantial premiums over standard food-grade syrups, while USDA BioPreferred eligibility unlocks separate pricing bands for industrial starch applications.
Pricing Analysis
Midwest corn belt processing facilities price dextrose monohydrate at a 15-25% discount to coastal pharmaceutical contract manufacturers, reflecting freight absorption and captive feedstock economics. Contract-based long-term offtake agreements dominate volume transactions, with spot markets serving only distressed or specialty orders. Price differentiation rests on certification grade and volume scale, with pharmaceutical-grade purity specifications widening spreads. Cost compression in standard food-grade syrups is intensifying because tapioca and rice-derived alternatives capture clean-label premiums. Regional bakeries and small-scale food manufacturers exhibit highest price sensitivity, while injectable dosage formulators accept premium positioning without negotiation.
Supply Chain Analysis
The United States anchors corn glucose production through integrated wet-milling infrastructure clustered across Iowa and Illinois. Corn futures volatility and enzyme input costs constitute the dominant raw material dependencies, with natural gas pricing for drying and evaporation representing a secondary cost driver. Single-source vulnerability concentrates in Midwest corn belt processing capacity, where state environmental permits constrain new entrant supply. Distribution runs through tanker truck networks to food manufacturers, with rail and barge movements serving bulk industrial starch accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern the United States corn glucose market as consolidated food manufacturers unbundle technical service from commodity supply contracts. This interoperability shift between procurement and formulation support creates new value-capture opportunities across the value chain.
For Market Incumbents: Fortify captive feedstock positions through ethanol co-location expansion in Iowa and Illinois, securing shared infrastructure economics against margin compression from alternative sweetener substitution. Deepen USP-grade crystallization capacity to defend pharmaceutical dextrose positioning against contract manufacturers tightening purity specifications. Prioritize enzyme technology licensing partnerships that open novel saccharide profiles for fermentation feedstock applications.
For New Entrants and Emerging Players: Differentiate on modular membrane filtration systems that enable specialty glucose syrup production without greenfield wet-milling construction. Target sports and clinical nutrition formulators in Colorado and Utah with certificate-of-analysis documentation exceeding standard food-grade requirements. Pursue direct technical service relationships with mid-sized food manufacturers bypassing consolidated CPG procurement consolidation.
For Investors and Strategic Acquirers: FDA's updated nutrition labeling requirements reshapes the acquisition landscape toward functional glucose applications that avoid added-sugar classification. Long-term viability favors wet-milling operators with integrated ethanol co-location and pharmaceutical-grade certification infrastructure. Monitor enzyme engineering breakthroughs enabling novel dextrose equivalent profiles as the primary inflection signal for specialty sweetener value migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Capacity Expansion | USP-grade crystallization addresses tightening purity specifications in New Jersey and North Carolina injectable manufacturing. |
| Enzyme Technology Licensing | Dual-enzyme hydrolysis partnerships open specialty saccharide profiles for fermentation feedstock diversification. |
| Ethanol Co-Location Integration | Shared infrastructure across Iowa and Illinois captures captive corn supply and compressed logistics costs. |
| Membrane Filtration Modularization | Footprint-miniaturized systems enable product line diversification without state environmental permitting delays. |
| Technical Service Unbundling | Separate formulation support contracts disrupt traditional full-service relationships with Midwest regional processors. |
Research Approach
Operator-level perspectives from wet-milling plant managers, food manufacturer procurement directors, pharmaceutical contract manufacturing executives, and enzyme technology suppliers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA GRAS notifications, USDA BioPreferred program certifications, EPA renewable fuel standard filings, and state-level environmental permit databases in Iowa and Illinois. Corn futures price data, wet-milling capacity utilization reports, and SEC 10-K disclosures from integrated agribusiness operators provided quantitative triangulation. Bottom-up segmentation modeling and top-down macroeconomic calibration ensured cross-verification across the analysis window.
Sensitivity analysis framed volume and value projections across product type, application purity tier, end-user procurement scale, and distribution channel logistics economics. Segmentation dimensions modeled include dextrose equivalent specification, USP versus food-grade certification, pharmaceutical versus nutritional versus industrial end-use, and regional corn belt versus coastal demand clusters. CAGRs derived from historical capacity expansion patterns, regulatory compliance timeline impacts, and substitution elasticity estimates for alternative sweetener penetration. Enzyme cost curves and membrane filtration adoption rates served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained corn price stability, unchanged FDA labeling frameworks, and current environmental permitting timelines would require recalibration. Forecasts reflect documented assumptions regarding ethanol co-location economics and pharmaceutical-grade demand trajectories. Recalibration cycles align with material shifts in enzyme technology breakthroughs, state-level regulatory amendments, and consolidated food manufacturer procurement restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Icing Shortening Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Mustard Oil Market
Ingredients
India Bakery Ingredients Market
Ingredients
Valerian Root Oil Market
Ingredients
Horny Goat Weed Extract Market
Ingredients
Shortening Powder Market
Ingredients
Jasmine Extract Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Bran Market
Ingredients
North America Gluten Free Flour Market
Ingredients
South America Spirulina Extract Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Corn Gluten Meal Market