
 Global Nutraceutical Ingredients Market | 2026-2036
Global Nutraceutical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nutraceutical Ingredients Market Analysis
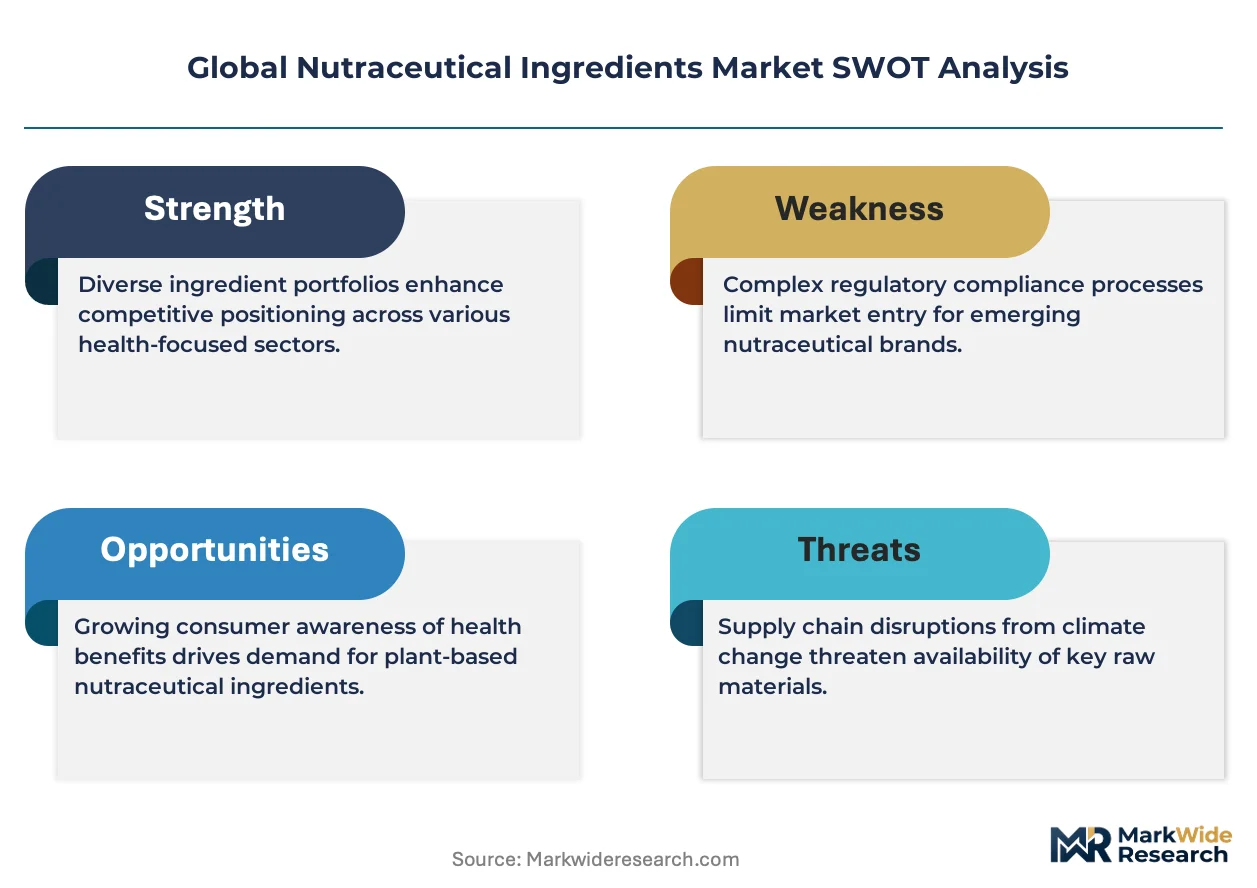
Pharmaceutical-grade specification tiers is rotating toward the center of competitive strategy as buyers demand batch-certified purity, COA traceability, and USP-NF compliance for ingredient sourcing. BASF SE leverages its integrated vitamin E and omega-3 platforms to sustain supply security across multiple continents. Royal DSM N.V. anchors its position through fermentation-based nutraceuticals, while Cargill, Incorporated dominates plant-derived protein and specialty carbohydrate segments with backward integration into agricultural feedstocks.
Nutraceutical ingredients comprise biologically active compounds including vitamins, minerals, herbal extracts, and probiotics, typically manufactured through fermentation, solvent extraction, or cold-pressing to achieve standardized potency for dietary supplements and functional foods. Probiotics and herbal extracts command premium positioning due to clinical substantiation requirements and limited qualified suppliers, whereas vitamins operate as high-volume, margin-compressed commodities where scale determines survival. Powder formulations lead volume throughput for business-to-business ingredient supply, while capsules and tablets capture higher value-add in finished goods channels directed at fitness enthusiasts and healthcare professionals.
FDA GRAS self-affirmation and FDA NDIN pathways govern market entry in the United States, while EFSA health claim authorizations under EU Regulation 1924/2006 determine permissible marketing language across Europe, directly shaping R&D investment and label architecture for ingredient suppliers. China's NMPA blue-hat registration system imposes additional clinical and stability testing burdens on imported functional ingredients. Stakeholders must monitor divergence between FDA enforcement discretion and EFSA's evolving positive lists for novel botanicals.
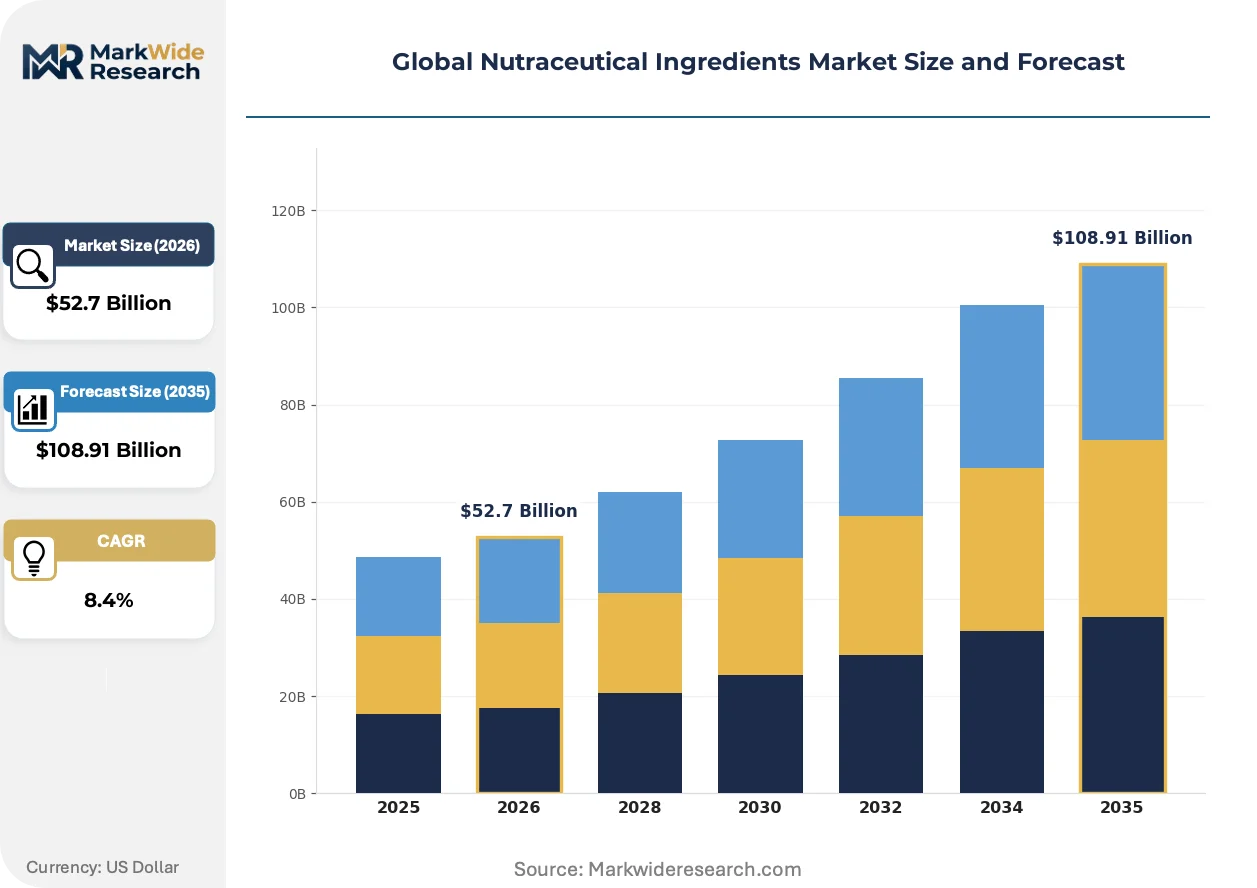
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins while elevating batch-certified traceability into a non-negotiable procurement criterion across functional food and supplement manufacturing.
Growth Catalysts
- FDA GRAS self-affirmation pathway:Accelerated market entry for novel bioactive compounds in United States dietary supplements, reducing time-to-revenue for fermentation-derived ingredients.
- Functional beverage formulation:Beverage manufacturers are expanding procurement of bioactive compounds as clean-label positioning demands replace synthetic additives with clinically substantiated natural alternatives.
- China NMPA blue-hat registration:Imported functional ingredients face additional clinical and stability testing burdens, but successful registrants capture premium positioning in the world's largest supplement-consuming population.
Market Restraints
- EFSA health claim authorization delays:EU Regulation 1924/2006 imposes multi-year substantiation timelines that freeze marketing language and compress R&D returns for botanical suppliers.
- Fermentation capacity concentration:Limited qualified fermentation facilities for probiotics and specialty amino acids creates supply bottlenecks in Germany, Netherlands, and select United States coastal clusters.
- Omega-3 raw material volatility:Wild-catch fish oil supply fluctuations and aquaculture feed competition generate input cost instability for DHA and EPA concentrate producers.
Strategic Opportunities
- Postbiotic metabolite applications:Heat-killed probiotic derivatives are opening formulation flexibility in ambient-stable functional beverages where live cultures fail.
- Cell-cultured botanical production:Plant cell fermentation is displacing solvent extraction for rare herbal actives, offering batch consistency independent of agricultural harvest cycles.
- India FSSAI functional food notification:Streamlined approval pathways for ingredients with established safety profiles are unlocking access to 1.4 billion consumers with rising discretionary health spending.
Industry Challenges
- USP-NF compliance talent scarcity:Analytical chemists with pharmaceutical-grade method validation expertise command premium compensation, constraining mid-tier ingredient suppliers.
- COA traceability system integration:Blockchain and ERP interoperability demands require capital deployment that fragments supplier IT roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nutraceutical Ingredients Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Probiotics Form: Powder, Capsule, Tablet, Liquid Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies End User: Healthcare Professionals, Fitness Enthusiasts, General Consumers, Athletes |
| Companies Covered | Cargill, Incorporated, BASF SE, Royal DSM N.V., Archer Daniels Midland (ADM), International Flavors & Fragrances Inc., Ajinomoto Co., Inc., Associated British Foods plc, Arla Foods amba, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nutraceutical Ingredients Market Emerging Trajectories
Precision fermentation and continuous processing technologies are reconfiguring cost structures for high-potency bioactives, while regulatory convergence pressures force simultaneous compliance with multiple jurisdiction-specific substantiation frameworks.
Precision fermentation platforms producing omega-3 fatty acids and rare cannabinoids are displacing agricultural extraction and chemical synthesis as the dominant production modality. Large-scale supplement contract manufacturers in Germany and United States are qualifying these ingredients at commercial scale. The technology is displacing traditional supply chains dependent on marine catch and crop cultivation, compressing geographic sourcing risk but elevating capital intensity barriers.
EFSA's evolving positive lists for novel botanicals under EU Regulation 2015/2283 are tightening entry criteria for traditional herbal ingredients without documented consumption history. The industrial consequence is a bifurcation between grandfathered botanicals and new entrants facing 18-24 month safety evaluation timelines. Botanical suppliers targeting European markets are redirecting R&D investment toward synthetic biology alternatives with clearer novel food pathways.
Direct-to-practitioner distribution is capturing share from traditional ingredient broker networks as healthcare professionals demand batch-specific certificates of analysis and clinical substantiation packages. Functional medicine clinics in United States and integrative pharmacy chains in Germany are consolidating procurement through qualified supplier portals. This channel migration is most visible in high-dose vitamin and professional-grade probiotic segments where clinical credibility commands price premiums.
Global Nutraceutical Ingredients Market Segmentation
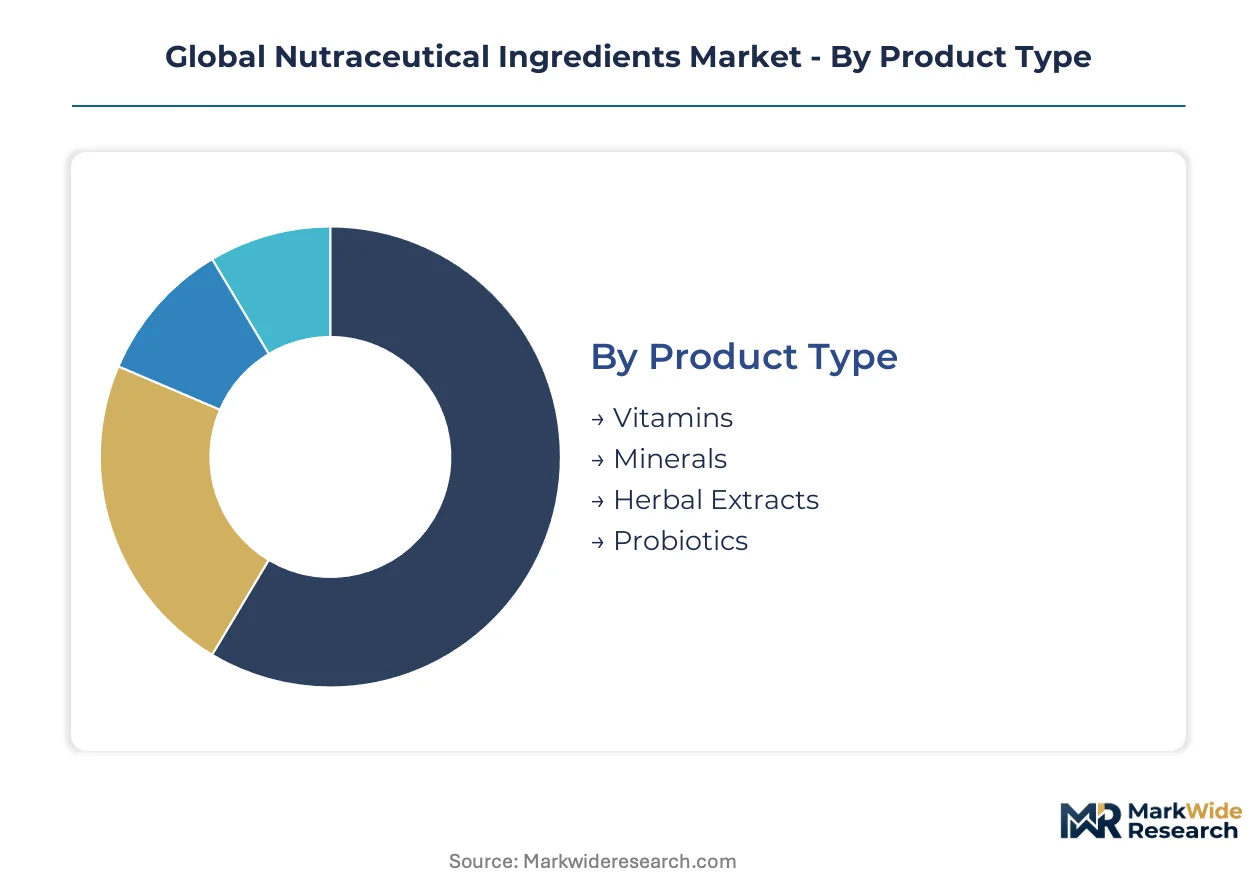
Ingredient specifications diverge sharply across end-use applications, with pharmaceutical-grade purity commanding tiered pricing premiums while commodity-grade volumes anchor supplier economics. Segmentation clarity enables procurement teams to match certificate-of-analysis tiers to regulatory submission requirements.
Product Type:
Herbal extracts and probiotics face acute substitution pressure from synthetic biology alternatives as precision fermentation platforms achieve commercial scale for rare bioactives.
- Vitamins:High-volume, margin-compressed commodity compounds manufactured through chemical synthesis or fermentation. Demand concentrates in United States and China for fortification of processed foods and mass-market supplements where cost-per-dose dominates procurement decisions.
- Probiotics:Live microbial cultures and heat-killed postbiotic derivatives requiring qualified fermentation capacity and stability-validated supply chains. German and Dutch manufacturing clusters face capacity bottlenecks as functional beverage manufacturers expand procurement for ambient-stable formulations.
- Minerals:Chelated and inorganic salt forms standardized for bioavailability.
- Herbal Extracts:Solvent-extracted or cell-cultured botanical actives with substantiation-dependent positioning.
Vitamins retain volume leadership; probiotics hold the steepest expansion curve.
Form:
Cost tier differentiation separates high-capital encapsulation equipment from commodity powder processing, with liquid formulations occupying a narrow premium niche.
- Powder:Bulk ingredient supply format dominating business-to-business channels. United States contract manufacturers and Chinese finished-goods exporters drive throughput for protein fortification and premix applications where blending efficiency outweighs dosing precision.
- Capsule:Gelatin and plant-based shell formats capturing value-add in practitioner-directed channels. German integrative pharmacies and United States functional medicine clinics consolidate procurement through qualified supplier portals demanding batch-specific certificates of analysis.
- Tablet:Compressed formulations for high-volume retail distribution.
- Liquid:Emulsion and suspension formats for pediatric and geriatric compliance segments.
Powder dominates ingredient supply tonnage; capsules gain share fastest in clinical credibility channels.
Distribution Channel:
Customer-type migration from broker networks to direct sourcing is compressing margin capture for traditional intermediaries while elevating traceability requirements.
- Online:Direct-to-consumer and direct-to-practitioner platforms consolidating procurement for subscription-based supplement regimens. United States telehealth integrations and Chinese cross-border e-commerce channels expand access to imported functional ingredients with NMPA blue-hat registration.
- Pharmacies:Professional-grade dispensing with clinical substantiation packages. German pharmacy chains and United States compound pharmacies qualify suppliers through documented USP-NF compliance and stability data.
- Supermarkets:Mass-market retail for commoditized vitamin and mineral formulations.
- Health Stores:Specialty retail for differentiated botanical and probiotic positioning.
Pharmacies anchor professional-grade volume; online channels climb the fastest as telehealth integrations deepen.
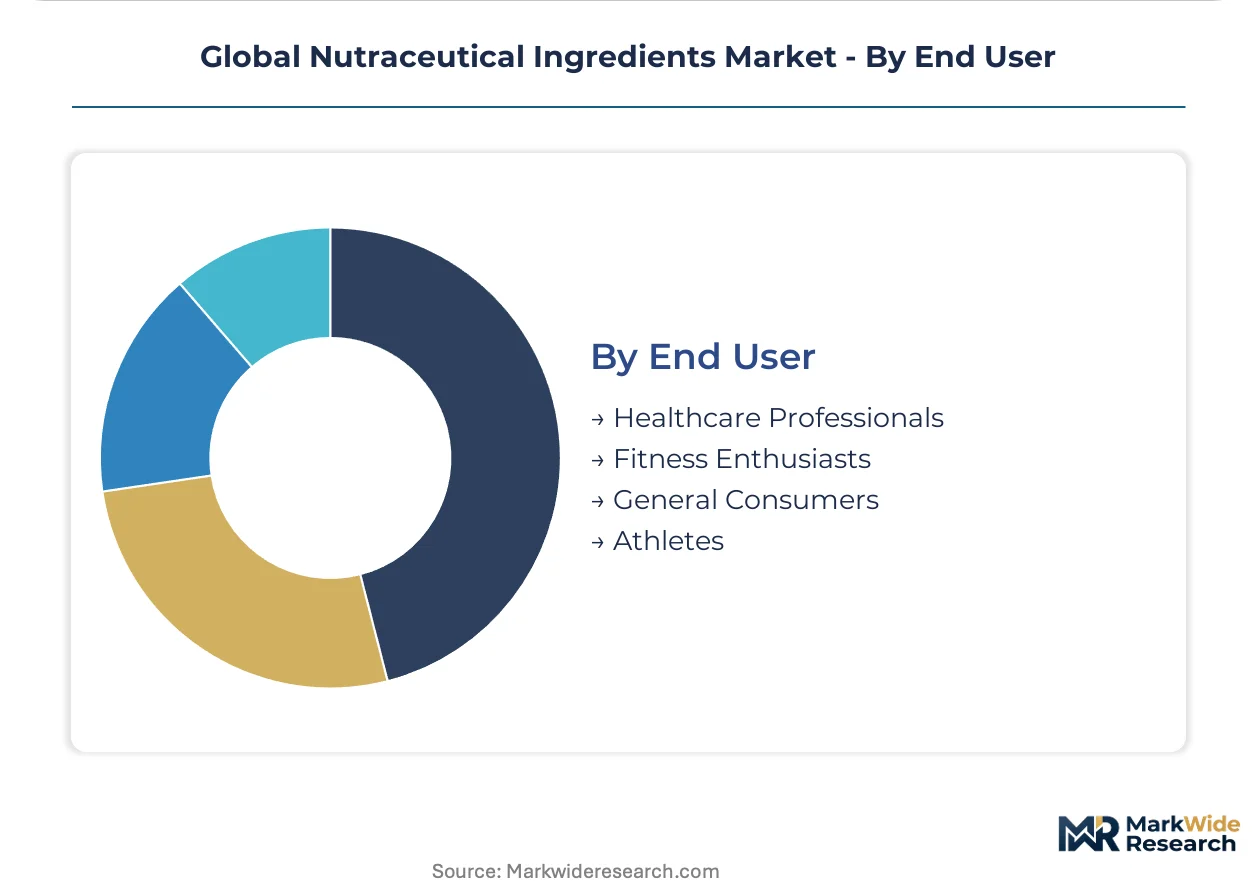
End User:
Application-specific dosing requirements and substantiation demands fragment procurement criteria across clinical, performance, and wellness use cases.
- Healthcare Professionals:Physicians, pharmacists, and registered dietitians prescribing evidence-backed formulations. United States functional medicine clinics and German integrative practices demand batch-certified purity with therapeutic-dose validation.
- Fitness Enthusiasts:Recreational athletes and wellness-focused consumers seeking performance and recovery positioning. Chinese urban professionals and United States boutique fitness communities drive demand for protein fortification and adaptogenic formulations.
- General Consumers:Preventive wellness seekers purchasing through mass retail and e-commerce.
- Athletes:Competitive and elite performers requiring banned-substance-tested certification.
General consumers retain volume leadership; healthcare professionals command the steepest pricing tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fermentation facilities export probiotic cultures to United States functional beverage manufacturers, while Chinese ingredient processors supply vitamin premixes to Southeast Asian supplement contract manufacturers. Trade corridors concentrate high-value bioactives between qualified manufacturing clusters and regulated end markets.
United States
FDA GRAS self-affirmation accelerates novel ingredient commercialization for dietary supplement brands. The agency's enforcement discretion on NDIN submissions shapes R&D timelines for fermentation-derived bioactives. Greater Boston and San Diego biotech clusters host precision fermentation scale-up facilities for omega-3 and cannabinoid production.
Germany
EFSA health claim authorization under EU Regulation 1924/2006 governs permissible marketing language for botanical suppliers targeting European markets. The country's national pharmaceutical regulator enforces pharmaceutical-grade purity specifications for professional-grade probiotic distribution. North Rhine-Westphalia concentrates qualified fermentation capacity facing supply bottlenecks for ambient-stable formulations.
China
NMPA blue-hat registration imposes clinical and stability testing burdens on imported functional ingredients seeking access to the world's largest supplement-consuming population. SAMR oversees dual carbon goals pressuring solvent extraction facilities toward cleaner production modalities. Yangtze River Delta ingredient processors dominate vitamin and mineral premix exports to Southeast Asian markets.
India
FSSAI functional food notifications unlock streamlined approval pathways for ingredients with established safety profiles across 1.4 billion consumers with rising discretionary health spending. The country's national food regulator harmonizes standards with Codex Alimentarius for export-oriented botanical extraction. Maharashtra and Gujarat host solvent extraction clusters transitioning toward cell-cultured botanical production.
Japan
METI promotes fermentation-based nutraceuticals through industrial technology grants targeting precision scale-up capabilities. PMDA's Foods with Function Claims system demands clinical substantiation packages that elevate procurement standards for professional-grade ingredients. Kanto region contract manufacturers qualify postbiotic metabolites for ambient-stable functional beverage formulations.
Global Nutraceutical Ingredients Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities, creating tiered competitive dynamics. BASF SE and Royal DSM N.V. anchor the publicly traded segment with integrated vitamin and fermentation platforms. Private specialists concentrate in botanical extraction and probiotic strain development. Three archetypes dominate: integrated chemical conglomerates, fermentation technology platforms, and agricultural processors with backward integration into feedstocks. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers secure qualified manufacturing assets.
Within the integrated chemical conglomerate tier, BASF SE represents pharmaceutical-grade specification leadership through its vitamin E and omega-3 platforms. Royal DSM N.V. occupies a position exemplifying fermentation-based nutraceutical production capabilities. Cargill, Incorporated anchors the agricultural processor archetype with captive supply of plant-derived protein and specialty carbohydrate feedstocks. These three companies collectively illustrate the competitive spectrum from petrochemical synthesis through biotechnology to agricultural value chains.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Royal DSM N.V. |
| Archer Daniels Midland (ADM) |
| International Flavors & Fragrances Inc. |
| Ajinomoto Co., Inc. |
| Associated British Foods plc |
| Arla Foods amba |
| Ingredion |
| Others |
Supply Flow & Price Mechanics
FDA GRAS self-affirmation and USP-NF certification tiers simultaneously gate supplier qualification and stratify price positioning across pharmaceutical-grade and commodity-grade procurement channels. Buyers demand batch-certified purity documentation as a non-negotiable entry ticket, while price differentiation widens between qualified fermentation facilities and unverified commodity processors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the nutraceutical ingredients market. Certification grade and volume scale drive price differentiation, with pharmaceutical-grade probiotic cultures commanding substantial premiums over commodity vitamin premixes. Pricing pressure stems from fermentation capacity concentration in Germany and the Netherlands, where qualified facilities face ambient-stable formulation bottlenecks. Mass-market supplement manufacturers exhibit highest price sensitivity, while functional beverage brands pursuing clean-label positioning demonstrate lowest sensitivity to premium tier pricing.
Supply Chain Analysis
Strategic stockpiling of omega-3 fish oil concentrates and probiotic cultures dominates inventory strategy as wild-catch supply fluctuations and fermentation capacity constraints elevate supply security priorities. Manufacturing concentrates in Germany, China, and the United States, with German facilities exporting probiotic cultures to North American functional beverage producers. Raw material dependencies include marine catch for EPA/DHA concentrates, agricultural feedstocks for plant-derived proteins, and fermentation substrates for specialty amino acids. Single-source vulnerability in qualified fermentation capacity creates structural risk. Distribution runs through direct-to-practitioner portals and qualified supplier networks serving healthcare professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutraceutical ingredients market sits in early-cycle expansion as precision fermentation platforms displace extraction-dependent supply chains and broaden bioactive accessibility. Postbiotic metabolite adoption in ambient-stable functional beverages exemplifies penetration tailwinds accelerating commercial scale-up.
For Market Incumbents: Consolidate fermentation capacity in North Rhine-Westphalia and Greater Boston clusters to defend against synthetic biology entrants achieving commercial scale for rare cannabinoids and omega-3 fatty acids. Deepen backward integration into agricultural feedstocks to secure captive supply of plant-derived protein isolates. Prioritize USP-NF compliance talent acquisition as analytical chemist scarcity constrains mid-tier competitors.
For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks market entry for novel fermentation-derived bioactives seeking positioning in United States dietary supplement channels. Target India's FSSAI functional food notification pathway for streamlined access to 1.4 billion consumers with rising discretionary health spending. Pursue white-space in postbiotic metabolite formulations where heat-killed derivatives unlock ambient-stable beverage applications beyond live culture limitations.
For Investors and Strategic Acquirers: EFSA's evolving positive lists for novel botanicals under EU Regulation 2015/2283 reshapes the acquisition landscape by bifurcating grandfathered ingredients from new entrants facing 18-24 month safety evaluation timelines. Long-term viability favors fermentation technology platforms with precision scale-up capabilities over solvent-dependent extraction specialists. Monitor NMPA blue-hat registration success rates as inflection indicator for premium positioning access in China's supplement-consuming population.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Qualified facilities in Germany and Netherlands alleviate bottlenecks for ambient-stable probiotic formulations. |
| Precision Platform Scale-Up | Commercial validation of cell-cultured botanical production displaces harvest-dependent extraction in Maharashtra clusters. |
| Regulatory Fast-Track Investment | FDA GRAS self-affirmation and India FSSAI notification accelerate novel bioactive time-to-revenue. |
| Direct-to-Practitioner Channel Development | United States functional medicine clinics and German integrative pharmacies consolidate procurement through qualified portals. |
| Backward Integration into Feedstocks | Captive agricultural supply secures plant-derived protein and specialty carbohydrate cost stability. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation technology directors, regulatory affairs specialists at ingredient suppliers, functional beverage formulation scientists, and healthcare professional procurement coordinators, then refined through secondary validation. Primary intelligence combined structured interviews with secondary sources including FDA GRAS notification filings, EFSA health claim submission databases, NMPA blue-hat registration records, and customs trade data tracking vitamin and probiotic concentrate flows. Bottom-up volume modeling across ingredient specifications and top-down market sizing triangulated to convergence thresholds.
Variance decomposition across the projection horizon isolates drivers by segmentation dimension including product type tier, form factor, distribution channel, and end-user application. CAGRs were derived from modeled volume trajectories calibrated to regulatory pathway timelines and manufacturing capacity expansion schedules. Forecast inputs incorporated fermentation yield improvements, novel food authorization success rates, and substitution elasticities between synthetic biology and extraction-based supply chains.
Decision-makers should treat outputs as directional under assumptions of sustained FDA enforcement discretion and EFSA positive list stability; material deviation would warrant model refresh. Revision becomes warranted when precision fermentation cost curves cross agricultural extraction parity or when major jurisdiction regulatory pathways experience structural modification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
GLP-1 Hydration Product Market