
 North America Bioactive Ingredients Market | 2026-2036
North America Bioactive Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bioactive Ingredients Market Analytics
NSF International certification for dietary supplements is reorganizing competitive tiers among North American bioactive ingredient suppliers. DSM sustains leadership through its integrated premix and human nutrition platforms spanning the United States and Mexico. Cargill Incorporated leverages its Minneapolis-based supply chain infrastructure to dominate plant-derived omega fatty acid distribution. Kerry Group plc differentiates through taste-masking technologies that expand bioactive incorporation into mainstream functional beverages.
Bioactive ingredients comprise physiologically active compounds—including vitamins, minerals, amino acids, and probiotic cultures—extracted, fermented, or synthesized to deliver targeted health benefits beyond basic nutrition, typically standardized to minimum purity thresholds and stability markers for shelf-life performance. These compounds serve nutraceutical, pharmaceutical, and cosmeceutical formulators seeking validated structure-function claims for immune, digestive, or cognitive endpoints. Probiotics and amino acids command expanding capacity investments as sports nutrition and gut health applications deepen. Plant-based sourcing anchors margin pools where organic certification and non-GMO verification support price premiums over synthetic and animal-derived alternatives.
The FDA's GRAS notification program and NDI guidance, alongside Health Canada's Natural and Non-prescription Health Products Directorate, define compliance burdens that filter market entrants and shape substantiation investments for bioactive health claims. California's Proposition 65 warning requirements and emerging state-level chemical disclosure statutes add layered compliance costs for suppliers distributing across the United States. Stakeholders must monitor how FDA enforcement priorities around synthetic biology-derived ingredients intersect with consumer preference shifts toward transparent supply chains.
Market Dynamics
The FDA's New Dietary Ingredient notification pathway is compressing product development timelines while simultaneously filtering marginal suppliers from the North American bioactive ingredients market. This regulatory gatekeeping is reshaping competitive tiers and forcing substantiation investments that favor scaled players with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Proposition 65 compliance infrastructure:California's chemical disclosure requirements are creating competitive moats for suppliers with pre-built toxicology databases and warning label systems, advantaging incumbents over new entrants.
- Sports nutrition formulators:Athletic recovery and performance-positioned products are accelerating amino acid complex procurement, particularly branched-chain formulations targeting the United States collegiate and professional sports segments.
- Precision fermentation:Biosynthesis platforms for bioactive peptides and rare amino acids are reducing dependence on agricultural feedstock volatility and enabling consistent purity profiles for pharmaceutical-grade applications.
Market Restraints
- GRAS self-affirmation costs:The FDA's voluntary GRAS notification process demands toxicology studies and expert panel reviews that impose six-figure minimum investments, excluding smaller ingredient innovators from mainstream distribution.
- Organic certification bottlenecks:United States Department of Agriculture organic accreditation for plant-derived bioactives faces inspector shortages and multi-year queue times, constraining supply expansion for premium-positioned ingredients.
- Synthetic biology substitution:Laboratory-cultured alternatives to botanical extracts are capturing share in cosmetic and pharmaceutical applications where batch consistency outweighs natural-source marketing claims.
Strategic Opportunities
- Canada's Natural and Non-prescription Health Products Directorate:Streamlined site licensing and reduced NNHPD backlog relative to FDA NDI timelines is attracting United States manufacturers to establish dual-registered production facilities in Ontario and British Columbia.
- Microbiome-targeted synbiotics:Combinations of prebiotic fibers with strain-specific probiotics are opening formulation white space in pediatric and geriatric nutrition where single-strain products dominate.
- Direct-to-practitioner distribution:Functional medicine and integrative health clinics are bypassing traditional supplement retail, creating high-margin channels for clinically validated bioactive complexes with biomarker-supported dosing protocols.
Industry Challenges
- Stability validation timelines:Accelerated shelf-life testing for novel delivery formats such as lipid nanoparticles and enteric coatings requires 18-24 month real-time studies, delaying commercialization.
- Cross-border customs harmonization:Discrepancies between FDA food additive classifications and Health Canada natural health product categories force dual formulation strategies for United States-Canada integrated supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bioactive Ingredients Market |
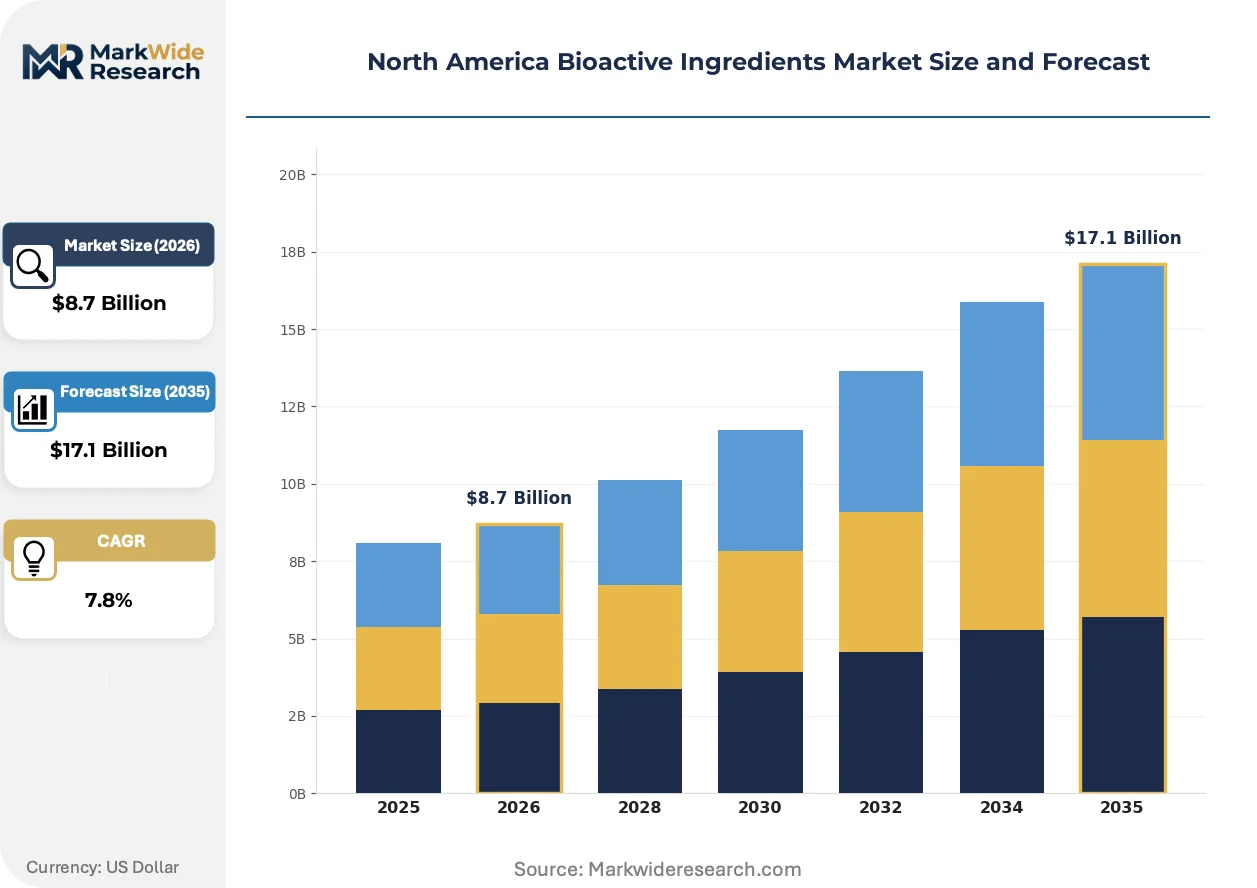
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Source: Plant-Based, Animal-Based, Microbial, Synthetic Application: Nutraceuticals, Functional Foods, Pharmaceuticals, Cosmetics Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | DuPont Nutrition & Biosciences, DSM, Cargill Incorporated, FMC Corporation, Kerry Group plc, Archer Daniels Midland Company, BASF SE, Sensient Technologies Corporation, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bioactive Ingredients Market Evolving Landscape
Bioprocessing advances and regulatory data requirements are simultaneously expanding the addressable application space for bioactives while concentrating supply capability among technology-integrated manufacturers. These forces are compressing the viable competitive set and elevating technical specification thresholds across nutraceutical and pharmaceutical channels.
Precision fermentation platforms for bioactive peptide production are decomposing the traditional agricultural extraction value chain by eliminating weather-dependent crop cycles and geographic sourcing constraints. United States contract manufacturers are adopting these biosynthesis systems at accelerating rates to secure pharmaceutical-grade purity certifications. This technology is decomposing margin pools previously captured by botanical extractors in California and the Pacific Northwest.
The FDA's draft guidance on NDI notifications for postbiotic ingredients is forcing substantiation investments that reshape competitive positioning among gut health suppliers. Manufacturers must now demonstrate safety data for inactivated microbial fractions and fermentation metabolites beyond traditional live culture requirements. Probiotic-focused suppliers in the Great Lakes manufacturing belt are responding by building dedicated toxicology and clinical trial capabilities previously absent from their operational models.
Practitioner-channel purchasing is displacing mass-market retail as the dominant growth vector for condition-specific bioactive formulations. Functional medicine clinics and registered dietitian networks are consolidating procurement through specialized distributors that demand batch-level certificates of analysis and biomarker validation studies. This channel rotation is most visible in California's biotechnology corridor and metropolitan Texas healthcare markets where integrative medicine practice density exceeds national averages.
North America Bioactive Ingredients Market Segmentation
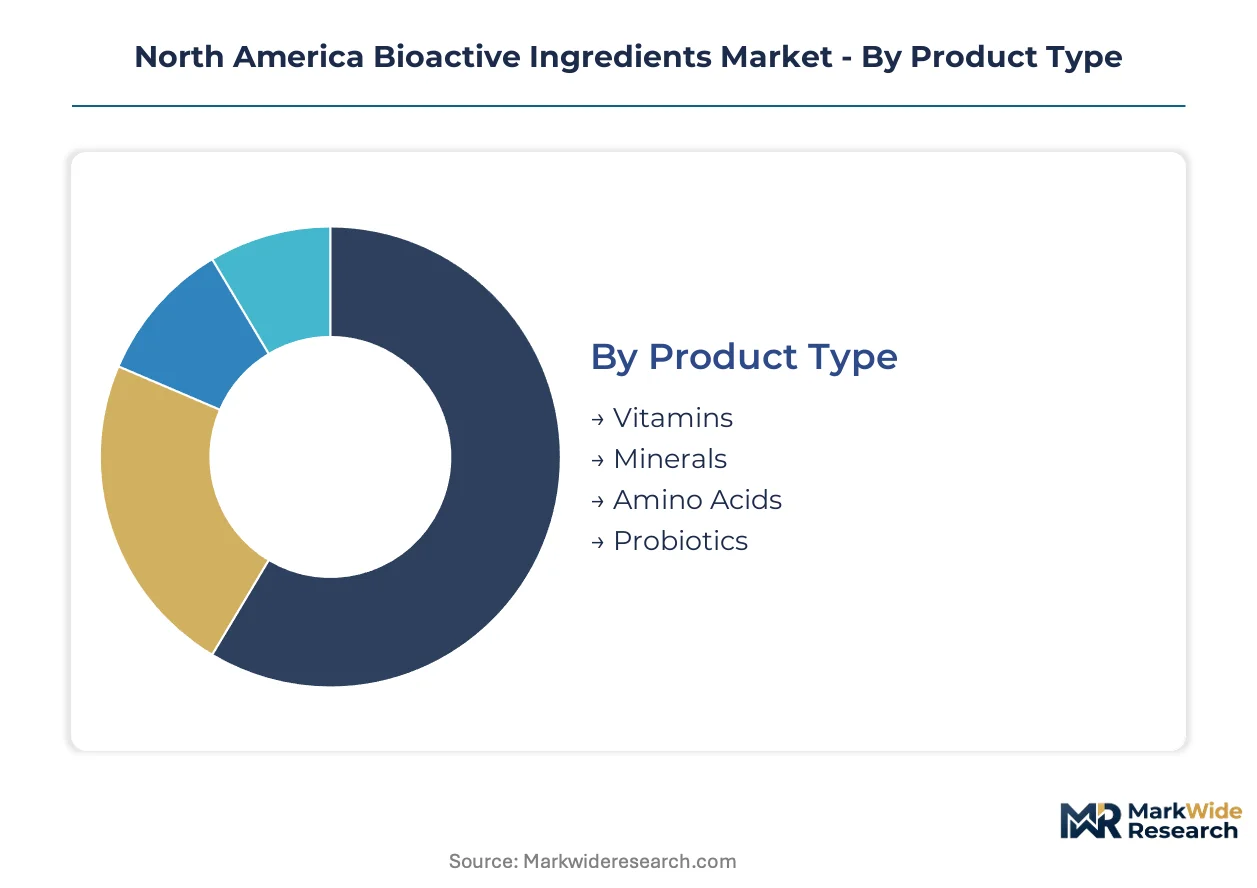
Segmentation in the North America bioactive ingredients market reflects divergent regulatory compliance burdens and sourcing constraints that reshape competitive positioning across product categories. Each dimension carries distinct margin structures and certification requirements that filter supplier capabilities and determine viable distribution pathways.
Product Type:
FDA's GRAS notification pathway and Health Canada's NNHPD site licensing create tiered substantiation costs that concentrate supply capability among scaled manufacturers with dedicated regulatory infrastructure.
- Vitamins:Fat-soluble and water-soluble compounds standardized to USP monograph specifications dominate fortification applications in United States breakfast cereals and dairy alternatives. Demand concentrates in Minneapolis-St. Paul manufacturing corridors where Cargill and DSM operate integrated premix facilities serving major food processors.
- Probiotics:Live microbial cultures requiring strain-specific safety documentation and stability validation through shelf-life testing. California's biotechnology corridor anchors production capacity for Lactobacillus and Bifidobacterium formulations targeting digestive health claims, with Great Lakes manufacturers expanding fermentation infrastructure to serve sports nutrition applications.
- Minerals:Chelated and inorganic forms meeting FCC purity standards for bioavailability optimization in prenatal and geriatric supplements.
- Amino Acids:Branched-chain and essential amino acid complexes driving procurement from sports nutrition formulators in Texas and Florida metropolitan markets.
Probiotics handles the majority of throughput; amino acids is the fastest mover on share.
Source:
Raw material provenance determines organic certification eligibility and Proposition 65 compliance burdens that stratify pricing across premium and commodity tiers.
- Plant-Based:Botanical extracts and phytochemicals from North American-grown crops including cranberries, blueberries, and turmeric root. United States Department of Agriculture organic accreditation bottlenecks constrain supply expansion, with inspector shortages extending queue times beyond twenty-four months for new entrants.
- Microbial:Precision fermentation platforms producing bioactive peptides and rare amino acids with pharmaceutical-grade purity profiles. United States contract manufacturers in California and Massachusetts are adopting biosynthesis systems to eliminate agricultural feedstock volatility.
- Synthetic:Laboratory-synthesized compounds including ascorbic acid and folic acid manufactured through chemical catalysis in Texas and Louisiana petrochemical corridors.
- Animal-Based:Marine-derived omega-3 fatty acids and dairy-sourced bioactive peptides subject to sustainability certification requirements from Alaska fisheries and Wisconsin dairy processing cooperatives.
Plant-based sourcing commands the steepest price premiums; microbial production is expanding most quickly as fermentation technology matures.
Application:
End-use specifications determine validation requirements ranging from structure-function claims to pharmaceutical-grade cGMP compliance.
- Functional Foods:Bioactive-fortified beverages and prepared foods requiring taste-masking technologies and thermal stability through UHT processing. Kerry Group's flavor systems enable probiotic incorporation into mainstream United States beverage lines previously inaccessible to live cultures.
- Nutraceuticals:Dietary supplements in capsule, tablet, and powder formats demanding NSF International certification and batch-level certificates of analysis. Direct-to-practitioner distribution through California and Texas functional medicine clinics is displacing mass-market retail as the dominant growth vector.
- Pharmaceuticals:Active pharmaceutical ingredients and excipients requiring FDA drug master file submissions and validated manufacturing processes.
- Cosmetics:Topical bioactives including ceramides and peptides subject to cosmetic ingredient review by the Personal Care Products Council and state-level chemical disclosure statutes.
Nutraceuticals carries the largest revenue base; functional foods is gaining share fastest through beverage format innovation.
Distribution Channel:
Channel selection determines margin capture and customer relationship intensity, with practitioner-direct models requiring clinical validation investments absent from retail pathways.
- Online:Direct-to-consumer and subscription-based platforms capturing United States metropolitan markets with biomarker-supported dosing protocols and personalized nutrition algorithms. Amazon and specialized nutraceutical platforms are consolidating procurement for condition-specific formulations.
- Health Stores:Specialty retailers including Whole Foods Market and independent co-ops demanding non-GMO verification and transparent supply chain documentation.
- Pharmacies:CVS, Walgreens, and regional chains stocking pharmacist-recommended brands with USP verification and insurance reimbursement eligibility.
- Supermarkets:Mass-market retail requiring slotting fees and promotional support that favor scaled suppliers with national distribution infrastructure.
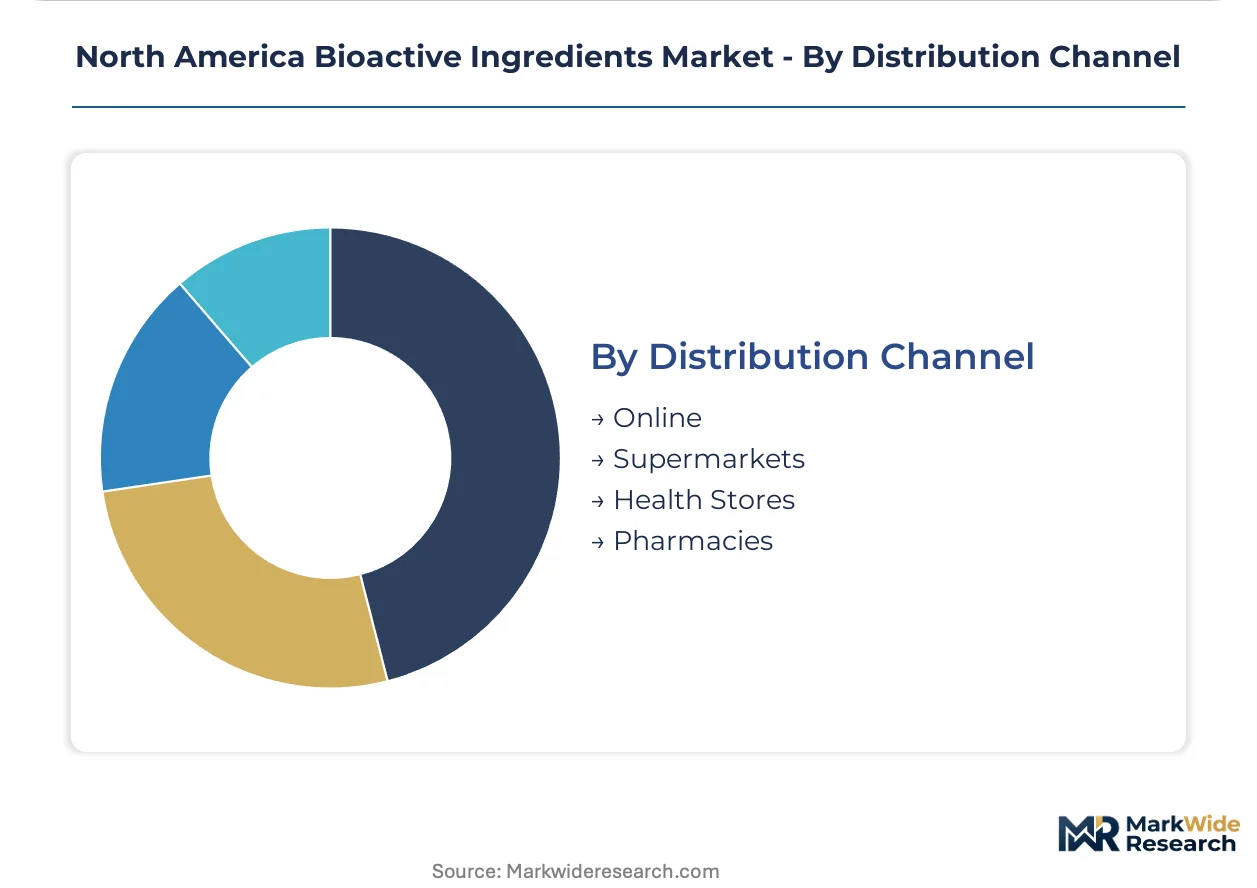
Online channels handle the majority of growth volume; health stores maintain the highest per-unit margins through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional foods manufacturers and sports nutrition formulators concentrate procurement across the continent's biotechnology corridors and manufacturing belts, with regulatory compliance infrastructure filtering supplier capabilities in each national market.
United States
California's biotechnology corridor anchors demand for probiotic and amino acid complexes, while the Great Lakes nutraceutical manufacturing belt expands fermentation capacity. The FDA's New Dietary Ingredient notification pathway and evolving GRAS self-affirmation protocols compress product development timelines. Minneapolis-St. Paul hosts integrated premix facilities serving major food processors with standardized vitamin fortification systems.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate attracts United States manufacturers seeking streamlined site licensing with reduced backlog relative to FDA timelines. Ontario and British Columbia host dual-registered production facilities serving cross-border supply chains. The Prairie Provinces supply agricultural feedstocks for plant-derived bioactive extraction, though organic certification bottlenecks constrain expansion.
Mexico
The Bajío Region and Nuevo León develop contract manufacturing infrastructure for United States brands seeking tariff-advantaged production. Mexico's national health regulator COFEPRIS maintains alignment with FDA food additive classifications for integrated North American supply chains. Jalisco's food processing cluster incorporates bioactive fortification for domestic and export-bound functional beverages.
North America Bioactive Ingredients Market Competitive Landscape
Player mix skews toward integrated nutrition platforms and specialized fermentation specialists, with tiered competitive positioning based on regulatory affairs infrastructure and premix integration depth. The vendor base separates into three strategic archetypes: multinational life-science conglomerates with human nutrition divisions, agribusiness-derived ingredient suppliers leveraging crop sourcing networks, and focused biotechnology specialists commercializing precision fermentation platforms. Dominant competitive moves include capacity expansion in pharmaceutical-grade fermentation infrastructure and strategic partnerships bridging biosynthesis technology with mainstream food processing channels.
Within the integrated nutrition tier, DSM and Kerry Group plc represent contrasting positioning archetypes. DSM exemplifies the vertically integrated life-science model spanning premix formulation through human nutrition applications. Kerry Group plc occupies a position emphasizing taste-masking and delivery technologies that enable bioactive incorporation into mainstream functional beverages. Among agribusiness-derived suppliers, Cargill Incorporated anchors the plant-derived omega fatty acid segment through Minneapolis-based supply chain infrastructure. These three companies illustrate how regulatory compliance scale and application-specific formulation capabilities determine competitive tier placement.
| Leading Market Players |
|---|
| DuPont Nutrition & Biosciences |
| DSM |
| Cargill Incorporated |
| FMC Corporation |
| Kerry Group plc |
| Archer Daniels Midland Company |
| BASF SE |
| Sensient Technologies Corporation |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with pharmaceutical-grade fermentation facilities lock in both supply access and price visibility for probiotic and amino acid suppliers navigating FDA New Dietary Ingredient notification timelines. These contracts tether ingredient buyers to named capacity reservations in California's biotechnology corridor and the Great Lakes manufacturing belt, insulating procurement costs from agricultural feedstock volatility while embedding compliance infrastructure costs into unit economics.
Pricing Analysis
Cost-plus contracts with agricultural commodity indexation dominate plant-derived bioactive procurement, particularly for organic-certified botanical extracts facing USDA accreditation bottlenecks. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels separates premium-positioned ingredients from commodity alternatives. Pricing pressure stems from precision fermentation platforms decomposing traditional extraction value chains by eliminating crop-cycle dependencies. Mass-market functional food manufacturers exhibit highest price sensitivity, while direct-to-practitioner channels absorb premium positioning through clinically validated dosing protocols.
Supply Chain Analysis
Port congestion along the Los Angeles-Long Beach corridor and container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for microbial fermentation feedstocks and specialized packaging materials. Supply concentrates in the United States, Canada, and Mexico under integrated North American trade frameworks, with California and Minnesota anchoring domestic fermentation capacity. Raw material dependencies include corn-derived dextrose for microbial culture media, pharmaceutical-grade nitrogen sources, and strain-specific cryopreservation systems. Single-source vulnerability pervades rare amino acid production where biosynthesis platforms remain concentrated among limited contract manufacturers. Distribution runs through specialized nutraceutical distributors serving practitioner channels alongside direct procurement by integrated food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among functional medicine clinic networks and consolidated sports nutrition brands, fragmenting procurement leverage previously held by mass-market retailers.
For Market Incumbents: Compound regulatory affairs infrastructure advantages by expanding toxicology databases for postbiotic substantiation ahead of FDA draft guidance finalization. Deepen captive supply of precision fermentation capacity in the Great Lakes region to preempt synthetic biology substitution threats in pharmaceutical-grade applications. Lock in organic certification pipelines through inspector training partnerships that address USDA accreditation bottlenecks constraining premium-tier competitors. For New Entrants and Emerging Players: Differentiate on microbiome-targeted synbiotic formulations combining strain-specific probiotics with prebiotic fibers, a white space underserved by single-strain incumbents. Target direct-to-practitioner distribution through Texas and California functional medicine clinics where procurement consolidation creates demand for biomarker-validated complexes. Pursue Health Canada site licensing in Ontario to exploit streamlined Natural and Non-prescription Health Products Directorate timelines relative to FDA NDI pathways. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology specialists commercializing precision fermentation platforms for pharmaceutical-grade bioactive peptides, where technical moats widen over the analysis window. Monitor FDA enforcement priorities around synthetic biology-derived ingredients as the inflection signal determining whether biosynthesis platforms capture share from botanical extractors or face disclosure-driven consumer backlash.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Pharmaceutical-grade purity certifications decompose agricultural extraction value chains in California and Pacific Northwest corridors. |
| Dual-Registered Production Facilities | Ontario and British Columbia sites exploit Health Canada NNHPD backlog advantages over FDA NDI timelines for cross-border supply chains. |
| Postbiotic Toxicology Investment | FDA draft guidance on inactivated microbial fractions forces substantiation capabilities previously absent from Great Lakes probiotic suppliers. |
| Direct-to-Practitioner Channel Buildout | Functional medicine clinic networks in metropolitan Texas and California consolidate procurement for clinically validated bioactive complexes. |
| Organic Certification Pipeline Expansion | USDA inspector training partnerships address twenty-four-month queue times constraining premium-positioned plant-derived ingredient supply. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs directors, fermentation facility operators, functional medicine practitioners, and sports nutrition formulators anchors the qualitative findings against secondary validation from FDA GRAS notifications, Health Canada NNHPD site licenses, USDA organic accreditation databases, and SEC filings of publicly traded nutrition platforms. Bottom-up capacity assessments at named production facilities triangulate against top-down demand modeling from functional food and nutraceutical procurement patterns.
Sensitivity analysis around FDA NDI notification timeline assumptions, precision fermentation yield improvements, and organic certification queue durations shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, source provenance, application specification, and distribution channel intensity. CAGRs derive from weighted scenario outcomes incorporating regulatory approval velocity, technology adoption curves for biosynthesis platforms, and channel migration patterns toward practitioner-direct procurement.
Material uncertainties — FDA enforcement shifts on synthetic biology-derived ingredients, Health Canada NNHPD backlog fluctuations, and precision fermentation yield breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline stability and technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe BBQ Charcoal Market
Ingredients
Italy Soy Protein Market
Ingredients
Waxy Maize Starch Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Corn Steep Liquor Market
Ingredients
Phytogenic Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Torula Yeast Market
Ingredients
Encapsulated Salt Market
Ingredients
Vegetable Glycerin Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Barley Flake Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Caramel Malt Market