
 Organic Starch Market | 2026-2036
Organic Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Starch Market Intelligence
EU Green Deal agricultural provisions is restructuring capital requirements for organic starch processors across Europe. Cargill, Inc. leverages its North American organic corn sourcing networks to supply European food manufacturers facing input certification bottlenecks. AGRANA Group anchors Central European production through integrated potato starch operations in Austria and Hungary. Roquette Frères specializes in pea and potato-derived organic starches for pharmaceutical-grade applications where EMA excipient standards apply.
Organic starch denotes carbohydrate polymers extracted from certified organic crops without synthetic chemical modification, retaining amylose-amylopectin ratios between 15-30% and 70-85% respectively depending on botanical source. These biopolymers serve as texturizers, binders, and stabilizers across food systems where clean-label claims require non-GMO, pesticide-free provenance. Corn starch and potato starch command the largest volume positions, though tapioca starch captures premium positioning in gluten-free bakery segments where neutral flavor and high paste clarity justify price premiums. Wheat starch occupies a mature niche in European pasta and noodle applications, while liquid and gel forms gain traction in ready-meal sauces and personal care emulsions where cold-process solubility reduces energy costs.
FDA organic labeling enforcement and USDA National Organic Program accreditation shape North American market access, while REACH and EU Green Deal farm-to-fork targets constrain European supply chains to certified organic acreage. BIS organic standards in India and China's GB/T organic certification create parallel compliance tracks for exporters serving Asia-Pacific buyers. Stakeholders must monitor divergence between regional organic certification reciprocity agreements, as non-aligned standards threaten to fragment sourcing strategies and inflate duplicate audit costs.
Market Dynamics
The EU Green Deal's farm-to-fork provisions are restructuring organic starch supply chains by mandating certified organic acreage for all agricultural inputs, forcing processors to rebuild procurement networks around traceable, pesticide-free crop sourcing.
Growth Catalysts
- Clean-label reformulation mandates:EU processed food manufacturers are accelerating native starch substitution for modified alternatives to meet EFSA clean-label standards.
- REACH compliance acceleration:Chemical modification restrictions in European pharmaceutical excipient applications are redirecting demand toward unmodified organic starches.
- Gluten-free bakery expansion:Tapioca starch demand concentrates in European gluten-free segments where neutral flavor and high paste clarity command formulation preference.
Market Restraints
- Organic corn input volatility:Weather-driven yield fluctuations in North American organic corn belts create raw material cost instability for starch processors.
- Central European supply concentration:Austria and Hungary host disproportionate organic potato starch capacity, creating geographic vulnerability to regional climate events.
- Modified starch substitution threat:Price-sensitive industrial buyers in non-food applications retain modified starch preference where clean-label claims carry no regulatory weight.
Strategic Opportunities
- Pharmaceutical-grade pea starch expansion:EMA excipient standards for organic-derived binders create formulation openings in tablet and capsule manufacturing.
- Cold-process liquid starch systems:Energy cost reduction in ready-meal sauce production is driving adoption of pre-gelatinized organic starch gels.
- Indian BIS organic certification alignment:Harmonized standards between EU and Indian organic frameworks reduce duplicate audit burdens for exporters serving subcontinent food processors.
Industry Challenges
- Organic certification timeline compression:Three-year land conversion periods for conventional-to-organic crop transition create supply planning gaps for starch processors.
- Amylose-amylopectin ratio control:Native starch functionality variance between harvest batches requires reformulation adjustments that slow clean-label product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Starch Market |
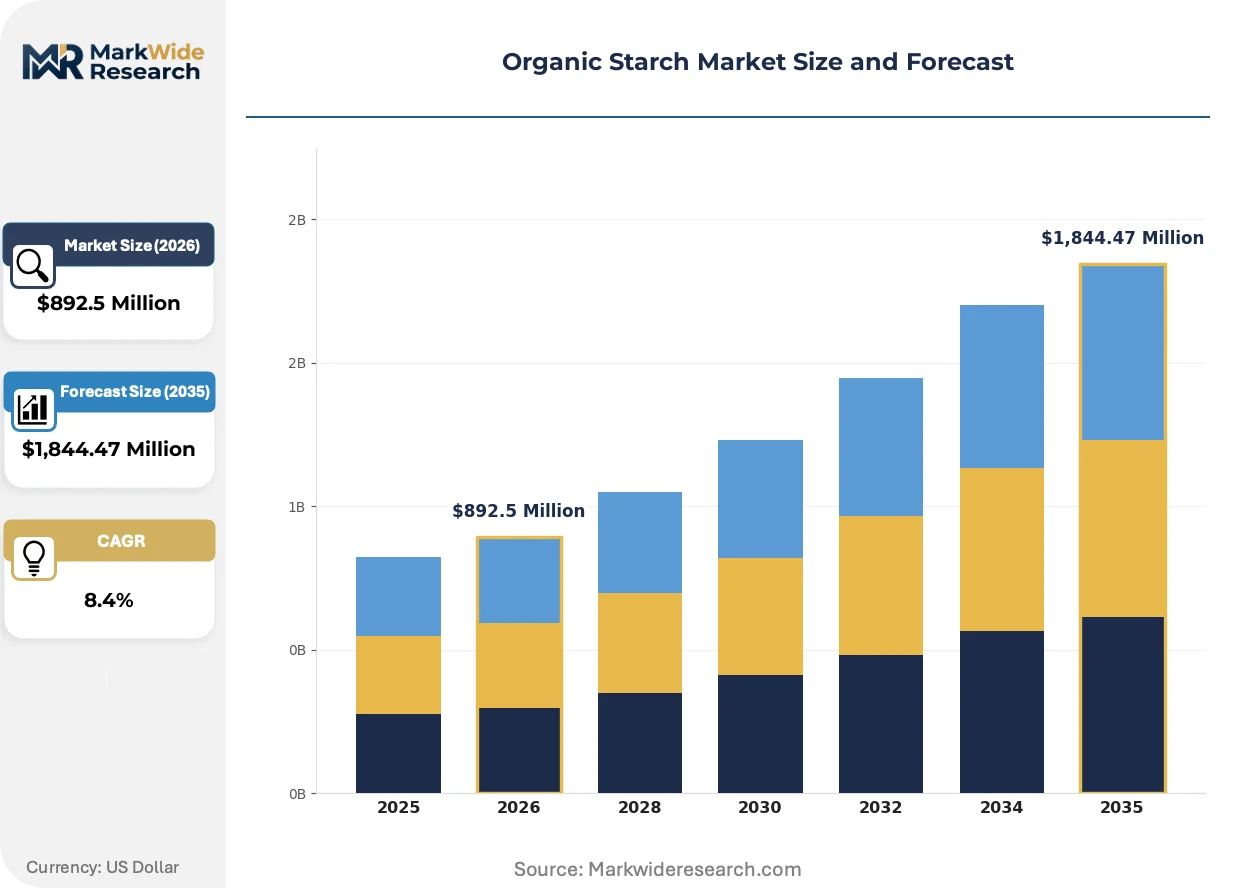
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,844.47 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Starch, Corn Starch, Potato Starch, Tapioca Starch Application: Food & Beverage, Pharmaceuticals, Personal Care, Paper & Packaging Form: Powder, Granule, Liquid, Gel End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Industrial Users |
| Companies Covered | Ingredion, Inc., AGRANA Group, Ulrick and Short Ltd., Aryan International, Tate & Lyle PLC, Archer Daniels Midland Company, Cargill, Inc., Roquette Frères, Marroquin Organic International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Starch Market Strategic Shifts & Innovations
Novel extraction technologies are reducing thermal degradation of native starch polymers, enabling broader clean-label applications while preserving functional properties that chemical modification previously guaranteed.
Enzymatic wet-milling systems are integrating into European organic starch facilities to replace conventional sulfur dioxide processing. German and French food manufacturers adopting these starches report improved paste stability in refrigerated sauces. The technology is integrating cold-process solubility into organic starch specifications previously requiring modified alternatives.
EU Green Deal agricultural provisions are tightening pesticide residue thresholds for organic crop certification. Starch processors must now verify supply chain compliance through blockchain-anchored traceability systems. Pharmaceutical and infant nutrition segments face the steepest compliance ramps as EFSA lowers acceptable synthetic input thresholds.
Certification-driven procurement is consolidating buyer preference around dual-certified organic and non-GMO starch suppliers. European co-manufacturers are displacing spot-market purchasing with multi-year supply agreements that lock in traceability documentation. This shift concentrates contract volume with processors maintaining integrated organic farming operations in France, Germany, and Austria.
Organic Starch Market Segmentation
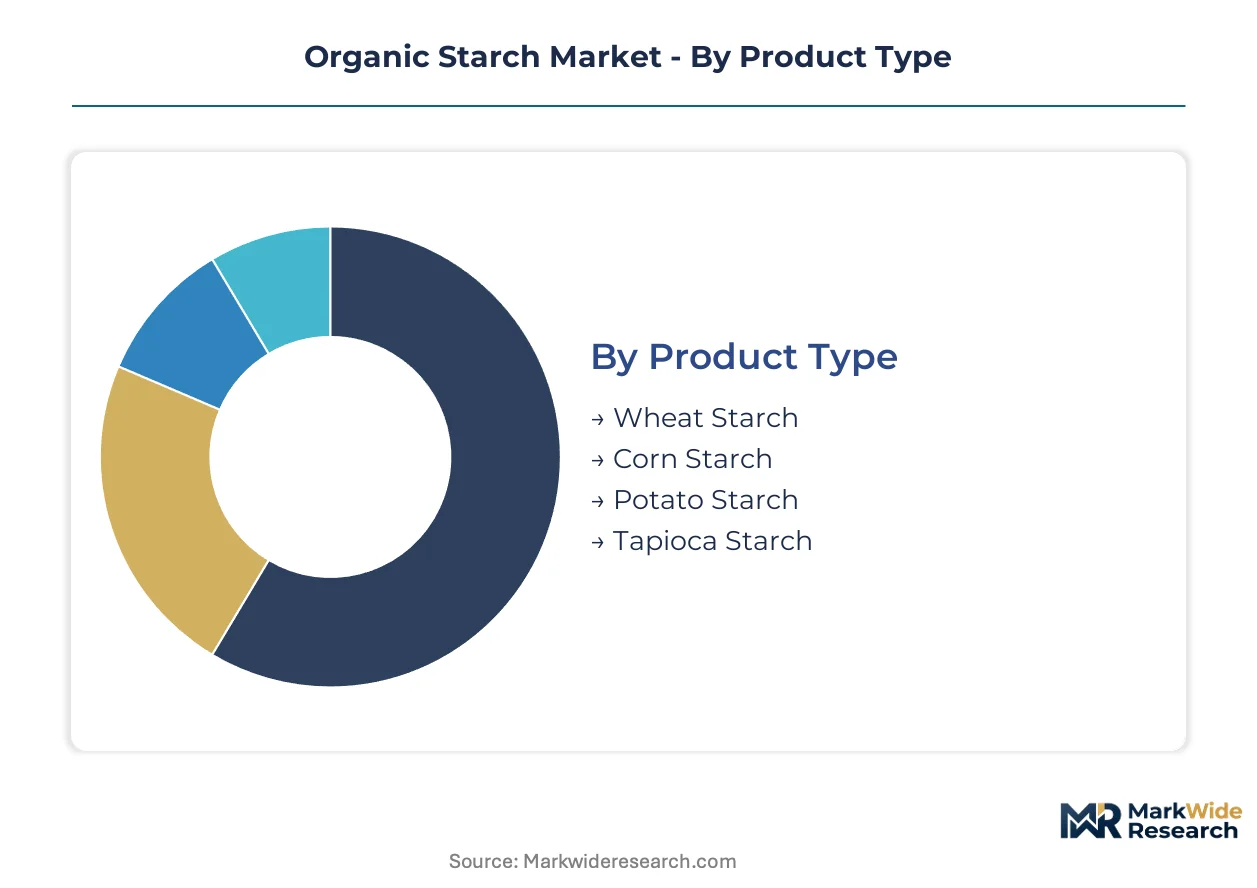
Organic starch procurement patterns diverge sharply across product grades and end-use specifications, with certification requirements dictating supplier qualification timelines and formulation compatibility. Segmentation reveals where EU Green Deal compliance costs concentrate and which buyer categories command premium positioning.
Product Type:
Certification burden varies by crop source: corn and potato starches face EU organic acreage verification under farm-to-fork rules, while tapioca imports trigger BIS and GB/T reciprocity checks for Asian supply chains.
- Corn Starch:Amylose-amylopectin ratios of 25:75 deliver reliable gel strength for sauce applications. North American organic corn belts supply European processors facing EU Green Deal input bottlenecks, though weather volatility creates raw material cost instability.
- Potato Starch:Higher amylopectin content (80%) yields exceptional paste clarity and freeze-thaw stability. Central European production clusters in Austria and Hungary serve pharmaceutical-grade demand where EMA excipient standards apply, creating geographic concentration risk.
- Tapioca Starch:Neutral flavor profile and high paste clarity command formulation preference in European gluten-free bakery segments.
- Wheat Starch:Mature positioning in Italian and German pasta applications where protein content requirements persist.
Corn starch sits at the top of the volume ranking, with tapioca starch climbing the fastest on gluten-free bakery expansion.
Application:
Cost tier stratification separates commodity food applications from pharmaceutical-grade contracts where EMA documentation requirements justify 40-60% price premiums.
- Food & Beverage:Clean-label reformulation mandates across EU processed food manufacturing accelerate native starch substitution for modified alternatives. German and French manufacturers report improved paste stability in refrigerated sauces using enzymatically processed organic corn starch.
- Pharmaceuticals:Tablet binder and capsule filler applications require REACH-compliant unmodified starches with batch-level traceability documentation. Pea starch derivatives gain traction where EMA excipient standards restrict synthetic input thresholds.
- Personal Care:Cold-process emulsion systems favor pre-gelatinized liquid starch forms that reduce manufacturing energy costs.
- Paper & Packaging:Price-sensitive industrial buyers retain modified starch preference where clean-label claims carry no regulatory weight.
Food and beverage commands absolute volume leadership, while pharmaceuticals posts the steepest margin expansion trajectory on certification-driven contract consolidation.
Form:
Application requirements dictate form selection: powder dominates dry-mix manufacturing, while liquid and gel forms penetrate ready-meal and personal care segments where cold-process solubility reduces energy inputs.
- Powder:Standardized moisture content below 13% enables extended shelf stability in ambient distribution. European pasta and bakery manufacturers specify powder grades for controlled hydration rates in automated production lines.
- Liquid:Pre-gelatinized cold-water soluble systems eliminate heating stages in sauce manufacturing, cutting energy costs 15-25% for ready-meal processors.
- Granule:Intermediate moisture formats serve specialty feed and fermentation applications requiring controlled release kinetics.
- Gel:High-viscosity pre-hydrated systems penetrate personal care emulsions where texture consistency across temperature ranges is critical.
Powder maintains volume dominance across all geographies, with liquid forms gaining share fastest on ready-meal sector automation.
End User:
Procurement sophistication separates multi-year contract buyers from spot-market participants, with pharmaceutical and infant nutrition firms driving blockchain-anchored traceability investments.
- Food Manufacturers:EU co-manufacturers displace spot purchasing with multi-year agreements locking in traceability documentation. Integrated organic farming operations in France, Germany, and Austria capture concentrated contract volume.
- Pharmaceutical Firms:EMA excipient standards and FDA organic labeling enforcement create dual-compliance procurement requirements for tablet and capsule binders.
- Cosmetic Companies:Personal care formulators prioritize cold-process liquid starches for emulsion stability with reduced thermal processing.
- Industrial Users:Paper and packaging applications show persistent price sensitivity, limiting organic starch penetration where modified alternatives satisfy technical requirements.
Food manufacturers represent the largest addressable base, with pharmaceutical firms expanding most quickly on excipient-grade certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agronomists and certified organic farm managers concentrate in Central European starch processing corridors, anchoring supply chain expertise that processors elsewhere struggle to replicate.
Germany
Clean-label food manufacturers in Bavaria and Baden-Württemberg accelerate native starch procurement as the EU Green Deal tightens agricultural input standards. The country's national food safety regulator enforces pesticide residue thresholds that exceed baseline EU requirements. Frankfurt and Hamburg host co-manufacturing clusters where multi-year supply agreements displace spot-market purchasing.
France
Pharmaceutical-grade pea starch demand concentrates in Île-de-France as EMA excipient standards restrict synthetic input thresholds. The EU Green Deal's farm-to-fork provisions mandate certified organic acreage verification for all agricultural inputs. Lyon and Marseille anchor formulation R&D clusters where enzymatic wet-milling systems integrate into organic starch specifications.
United States
North American organic corn belts supply European processors facing EU Green Deal input certification bottlenecks. FDA organic labeling enforcement and USDA National Organic Program accreditation shape market access requirements. Iowa and Illinois farming operations leverage blockchain-anchored traceability systems to verify supply chain compliance for export contracts.
India
BIS organic standards create parallel compliance tracks for exporters serving domestic and Asia-Pacific buyers. The country's national food safety regulator harmonizes standards with EU organic frameworks to reduce duplicate audit burdens. Maharashtra and Gujarat processing clusters specialize in tapioca starch derivatives for gluten-free bakery applications.
Austria
Integrated organic potato starch operations anchor Central European production capacity as geographic concentration risk intensifies. The EU Green Deal agricultural provisions restructure capital requirements for processors across the region. Lower Austria and Burgenland host disproportionate organic potato starch capacity serving pharmaceutical-grade demand where EMA standards apply.
Organic Starch Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated structure where scale advantages clash with traceability depth. The vendor base organizes around three strategic archetypes: integrated agricultural processors with captive organic farming operations, specialty ingredient distributors bridging certification gaps, and regional millers serving protected geographic indications. Capacity expansion and strategic partnerships dominate competitive moves as processors rebuild procurement networks around traceable, pesticide-free crop sourcing.
Among diversified agricultural processors, Cargill, Inc. and Archer Daniels Midland Company occupy positions spanning multiple crop origins and certification frameworks. AGRANA Group exemplifies the integrated specialist archetype through Central European potato starch concentration. Roquette Frères sits within the pharmaceutical-grade tier where EMA excipient documentation requirements create formulation barriers for commodity players.
| Leading Market Players |
|---|
| Ingredion, Inc. |
| AGRANA Group |
| Ulrick and Short Ltd. |
| Aryan International |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Cargill, Inc. |
| Roquette Frères |
| Marroquin Organic International |
| Others |
Cost & Logistics Intelligence
Enzymatic wet-milling adoption across European organic starch facilities compresses processing costs while concentrating procurement leverage among processors with captive organic farming operations in France, Germany, and Austria. This production-method transition simultaneously reduces sulfur dioxide handling expenses and tightens supply-side control over certified organic acreage verification under EU Green Deal farm-to-fork rules.
Pricing Analysis
Bundled certification-and-traceability packages command substantial premiums over unbundled commodity spot purchases in this market. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels separates EMA excipient-compliant starches from baseline organic food ingredients. Price differentiation rests on blockchain-anchored documentation depth and batch-level amylose-amylopectin ratio consistency. Cost compression in industrial-grade tiers is intensifying because price-sensitive paper and packaging buyers retain modified starch preference where clean-label claims carry no regulatory weight. Pharmaceutical firms show least price sensitivity due to EMA documentation requirements, while industrial users represent the most elastic demand segment.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle clean-label reformulation demand from German and French co-manufacturing clusters, while specialty distributors bridge certification gaps for smaller pharmaceutical and personal care formulators. Geographic supply concentration centers on Austria, Hungary, and France for organic potato starch, with North American organic corn belts feeding European processors facing input certification bottlenecks. Raw material dependencies include certified organic corn, pesticide-free potato crops, and imported tapioca roots subject to BIS and GB/T reciprocity verification. Single-source vulnerability concentrates in Central European potato starch capacity where Austria and Hungary host disproportionate pharmaceutical-grade production. Distribution runs through multi-year supply agreements that lock in traceability documentation, displacing spot-market purchasing across EU processed food manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EMA excipient standards and FDA organic labeling enforcement concentrate procurement preference around dual-certified suppliers with integrated farming operations. The demand-shift toward pharmaceutical-grade pea starch specifications justifies premium positioning for processors with EMA documentation capabilities.
For Market Incumbents: Cement backward integration into certified organic acreage through long-term land lease arrangements in France, Germany, and Austria to secure supply chain control against emerging pure-play organic specialists. Expand enzymatic wet-milling capacity to defend margin position against processors reliant on conventional sulfur dioxide processing as REACH compliance accelerates. Prioritize blockchain-anchored traceability investments to maintain pharmaceutical and infant nutrition contract concentration.
For New Entrants and Emerging Players: Cold-process liquid starch systems represent an underserved buyer archetype among ready-meal sauce manufacturers seeking energy cost reduction without modified starch regulatory exposure. Target Indian BIS-EU harmonization corridors where reduced duplicate audit burdens create export openings for tapioca starch derivatives. Penetrate through specialty distributor partnerships that bridge certification gaps for mid-tier European food manufacturers displaced from incumbent supply agreements.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional millers with protected geographic indications but limited pharmaceutical-grade certification depth. Long-term viability favors processors with integrated organic farming operations spanning multiple crop origins to hedge against weather-driven yield volatility in North American organic corn belts. Watch EMA excipient standard revisions as the signal to watch for inflection in contract consolidation velocity toward documentation-heavy suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | EU Green Deal farm-to-fork rules mandate traceable pesticide-free crop sourcing for starch processors. |
| Enzymatic Wet-Milling Capacity Expansion | German and French food manufacturers report improved paste stability in refrigerated sauces using this technology. |
| Blockchain-Anchored Traceability Implementation | Pharmaceutical and infant nutrition segments face steepest compliance ramps as EFSA lowers synthetic input thresholds. |
| Long-Term Supply Agreement Consolidation | European co-manufacturers displace spot-market purchasing with multi-year contracts locking in documentation. |
| Pharmaceutical-Grade Pea Starch Development | EMA excipient standards for organic-derived binders create formulation openings in tablet and capsule manufacturing. |
Research Approach
Multiple input streams — structured interviews with organic starch procurement managers at European food manufacturers, technical discussions with enzymatic processing equipment suppliers, and regulatory compliance tracking across EMA and FDA frameworks — were reconciled against secondary validation from customs trade data, EU organic certification databases, and SEC filings from diversified agricultural processors. Primary engagement spanned plant managers at Central European potato starch facilities, procurement leads at German and French co-manufacturing clusters, and distribution channel partners serving pharmaceutical excipient markets. Secondary sources included EU Green Deal implementation reports, BIS organic standard harmonization documents, and EFSA pesticide residue threshold updates. Bottom-up volume modeling across crop origins and end-use segments was cross-checked against top-down market sizing from trade flow analysis.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of corn, potato, tapioca, and wheat starch categories by application tier and certification grade. Segmentation dimensions included product type, application vertical, physical form, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of organic acreage expansion rates, clean-label reformulation adoption curves, and pharmaceutical excipient specification tightening. Industry-specific forecast inputs incorporated three-year land conversion timelines for conventional-to-organic crop transition and enzymatic wet-milling capacity buildout schedules across European processing facilities.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-grade categories carry tighter precision than industrial-grade applications where modified starch substitution obscures organic demand signals. Forecasts reflect assumptions regarding EU Green Deal implementation pacing, organic certification reciprocity agreement durability, and climate volatility in North American organic corn production regions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Acetylated Starch Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
North America Gums Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Organic Pastry Flour Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Bovine Gelatin Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Global Starch Derivatives Market
Ingredients
Cocoa Bean Extract Market
Ingredients
United States Wheat Protein Market
Ingredients
Bean Pasta Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Europe Potato Protein Market