
 Global Malt and Malt Extracts Market | 2026-2036
Global Malt and Malt Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Malt and Malt Extracts Market Outlook
European malting capacity is restructuring around energy-efficient kilning investments as natural gas costs force plant modernization decisions. Boortmalt leverages its Belgian heritage and continental malthouse network to sustain supply relationships with major brewers. Muntons plc anchors its position through integrated malt extract production for food manufacturing customers. Malteurop Group competes on barley origination scale across France and Eastern Europe.
Malt and malt extracts comprise germinated cereal grains—typically barley—dried in kilns to develop enzymatic activity, color, and flavor compounds measured by diastatic power and Lovibond degrees, serving primarily as fermentable substrates for brewing and natural sweeteners for food processing. Dry malt extract holds mature volume leadership in homebrewing and industrial baking applications where shelf stability reduces logistics complexity. Liquid malt extract dominates commercial brewery procurement where flavor freshness and dissolution speed command premium positioning. Malted barley maintains structural importance in craft brewing segments that prioritize provenance labeling and traditional mash protocols.
FDA food additive regulations and EU REACH chemical safety frameworks govern malt extract purity standards and labeling requirements for cross-border trade. Germany's BfR and France's ANSES evaluate mycotoxin thresholds in malting barley, directly shaping supplier qualification protocols for European brewers. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal as scope-three emissions reporting extends to agricultural inputs.
Market Dynamics
Natural gas cost volatility is forcing malting plants across Europe to accelerate kiln electrification and heat recovery retrofits, restructuring capital deployment timelines for the sector's most energy-intensive processing stage.
Growth Catalysts
- EU Green Deal agricultural standards:Carbon accounting mandates for scope-three emissions are compelling brewers to source certified low-carbon malting barley, creating premium contract structures for compliant suppliers.
- Craft brewing flavor differentiation:Specialty malt portfolios with distinct Lovibond color ranges and diastatic power specifications are commanding price premiums in North American and German markets.
- Malt extract diversification:Food manufacturers are substituting refined sugars with enzymatic malt extracts in clean-label bakery and confectionery formulations.
Market Restraints
- Barley input cost volatility:Fertilizer price swings and drought frequency in Australian and Canadian growing regions compress malting margin predictability.
- Supply concentration in Rhine-Ruhr corridor:German malting capacity clustering creates single-point vulnerability for continental European brewer procurement.
- Gluten-free substitution threat:Sorghum and rice-based brewing adjuncts are displacing malted barley in specific dietetic beverage segments.
Strategic Opportunities
- India specialty malt underpenetration:Premium beer segment expansion in Maharashtra and Karnataka states lacks domestic specialty malting infrastructure.
- Biogas kiln technology convergence:Anaerobic digestion of malt byproducts paired with electrified kilning enables net-zero production claims.
- E-commerce ingredient channels:Direct-to-homebrewer liquid malt extract subscriptions are bypassing traditional distributor markups in US and UK markets.
Industry Challenges
- Master maltster skill scarcity:Traditional germination and kilning expertise is retiring faster than apprenticeship pipelines in Czech Republic and Belgium.
- Organic certification timeline compression:Three-year land conversion requirements for EU organic malt barley are misaligning with brewer sustainability pledges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Malt and Malt Extracts Market |
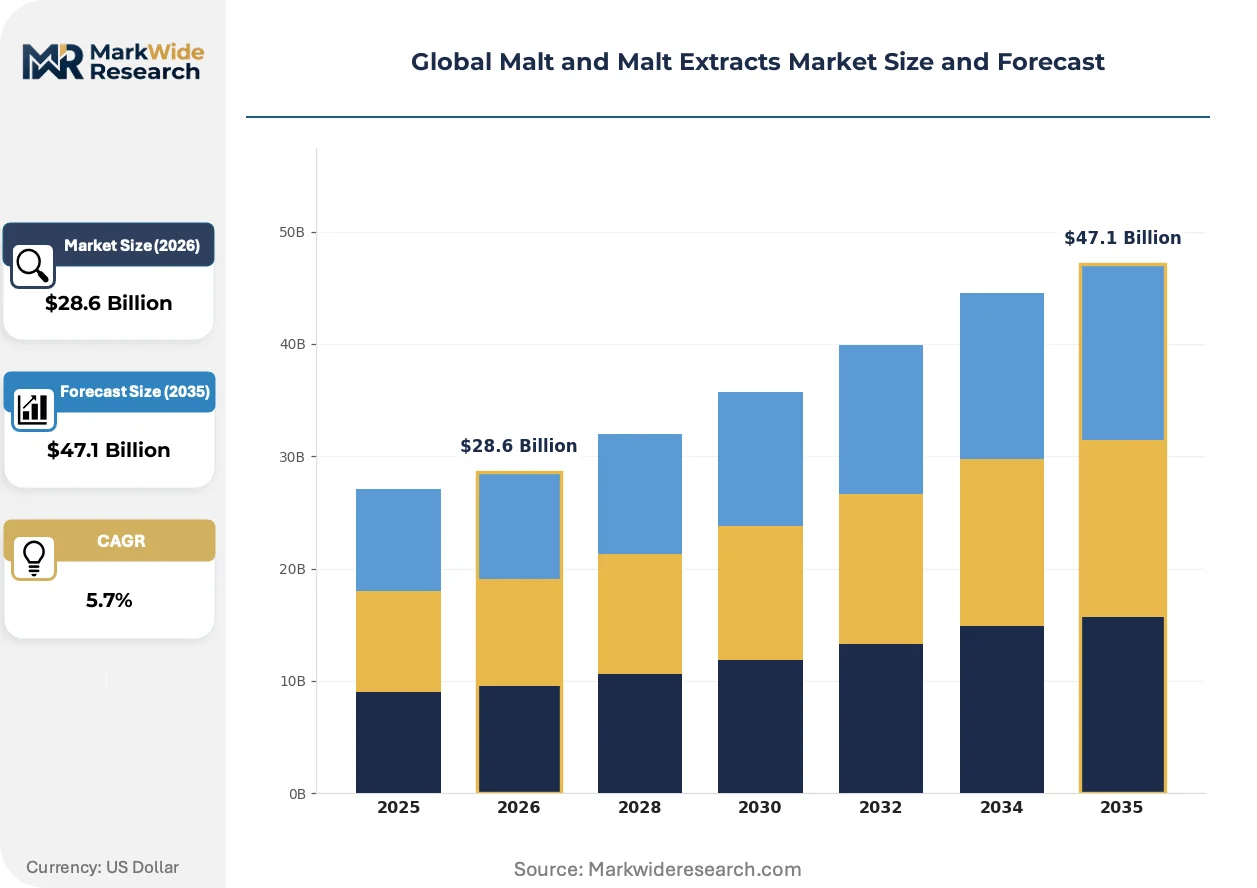
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.1 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Malt Extract, Dry Malt Extract, Malt Powder, Malted Barley End Use: Beverage, Bakery, Confectionery, Animal Feed Form: Granular, Flake, Liquid, Powdered Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Boortmalt, Muntons plc, Malteurop Group, Malt Products Corporation, Viking Malt, GrainCorp Limited, Groupe Soufflet, Holland Malt, Rahr Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Malt and Malt Extracts Market Strategic Shifts
Electrification of thermal processes and digital quality control systems are converging to redefine malt house operational economics, while regulatory carbon disclosure requirements reshape supplier qualification protocols.
Automated inline near-infrared spectroscopy is automating real-time moisture and protein monitoring during germination and kilning stages. Large-scale malting groups in Germany and France are deploying these systems to reduce laboratory testing bottlenecks. This sensor integration is automating process control adjustments that previously required manual intervention, compressing batch-to-batch variability and reducing energy overruns.
REACH chemical safety frameworks are tightening purity documentation requirements for malt extract imports into EU food manufacturing channels. The European Chemicals Agency is expanding substance registration obligations to cover enzymatic processing aids. Food-grade malt extract suppliers serving German and Dutch industrial bakeries are responding by consolidating analytical testing partnerships and harmonizing certificate of analysis formats.
Direct contracting between craft brewers and heritage barley growers is displacing spot-market purchasing for provenance-labeled malt programs. This relationship-based sourcing is consolidating procurement decisions into smaller buying committees at regional brewing cooperatives. The shift is most visible across Pacific Northwest and Upper Midwest US clusters, where estate-malt designations now command measurable price premiums over commodity equivalents.
Global Malt and Malt Extracts Market Segmentation
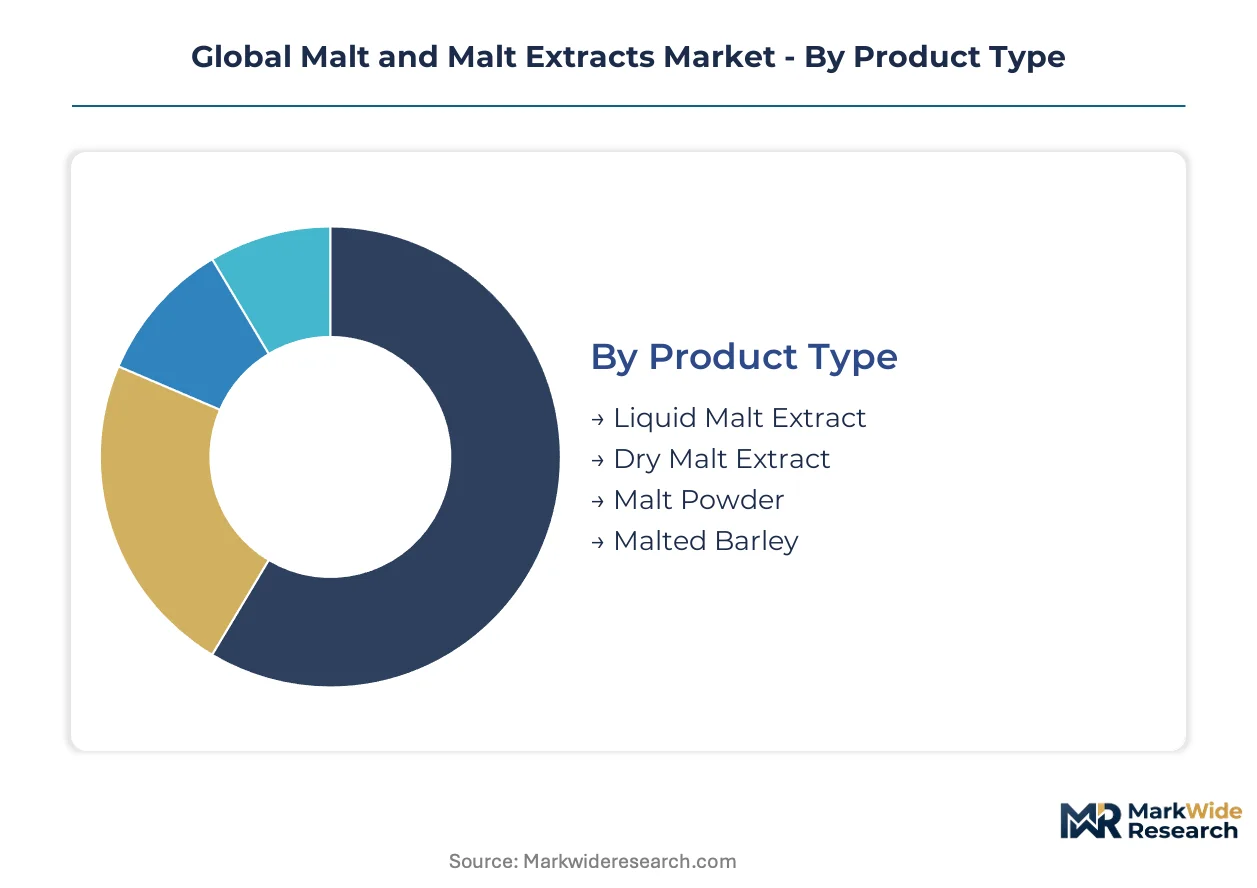
Segmentation in the malt and malt extracts market reveals distinct procurement patterns across product formats and end-use applications. Supply concentration varies sharply by segment, with beverage-grade specifications commanding stricter quality protocols than food manufacturing alternatives.
Product Type:
Supply concentration tilts heavily toward formats that balance shelf stability with enzymatic performance, creating divergent margin structures across liquid and dry processing lines.
- Liquid Malt Extract:Unfermented wort concentrated through vacuum evaporation preserves heat-sensitive enzymes and aromatic compounds. Commercial breweries in Germany and the Czech Republic specify this format for flavor consistency in premium lager production, though refrigerated logistics constrain distribution radius.
- Dry Malt Extract:Spray-dried or drum-dried powder achieves moisture levels below 5%, enabling ambient storage and transcontinental shipment. Homebrewing retailers across the United States and United Kingdom stock this format as their default SKU, driven by inventory turnover efficiency and lower shipping costs per unit extract.
- Malt Powder:Finely milled roasted malt delivers color and flavor without enzymatic activity, finding use in dry baking mixes where Maillard-derived notes substitute for artificial caramel.
- Malted Barley:Intact germinated grains retain full diastatic power for traditional mashing protocols; craft breweries in Belgium and the United States favor this format for provenance labeling and mash tun flexibility.
Malted barley absorbs the bulk of installed capacity; liquid malt extract is expanding most quickly.
End Use:
Application-driven specification tiers separate beverage-grade enzymatic requirements from food-grade flavoring priorities, with distinct supplier qualification protocols governing each channel.
- Beverage:Brewing applications demand precise diastatic power, FAN (free amino nitrogen), and beta-glucan specifications to support fermentation kinetics. Large-scale lager producers in Germany contract directly with malting groups for batch-specific certificates of analysis.
- Bakery:Malt extracts function as natural sweeteners and browning agents in artisan bread formulations. Industrial bakers in France and the Netherlands specify enzymatically active extracts to improve dough handling without chemical additives.
- Confectionery:Roasted malt syrups provide bitter-caramel notes in chocolate coatings and toffee applications where clean-label positioning displaces artificial flavorants.
- Animal Feed:Malt culms and rootlets from germination floors serve as protein-rich fiber supplements for ruminant nutrition, though this segment operates at lower price points than food-grade channels.
Beverage applications dominate volume throughput; bakery substitution of refined sugars is climbing the fastest.
Form:
Physical state determines handling equipment requirements and dissolution kinetics, with granular formats commanding premium positioning in automated processing environments.
- Granular:Free-flowing particles sized for pneumatic conveying systems suit large-scale brewery malt handling and automated bakery dosing equipment.
- Flake:Rolled or flaked malted barley accelerates starch gelatinization in specialty brewing applications where rapid conversion supports experimental grist formulations.
- Liquid:Pumpable concentrates eliminate dust exposure and enable precise flow-metered addition in continuous food processing lines.
- Powdered:Instantized particles with modified starch coatings improve dispersibility in cold-water applications such as protein beverages and nutritional mixes.
Granular forms capture the majority of industrial procurement; liquid concentrates are gaining share fastest in automated processing installations.
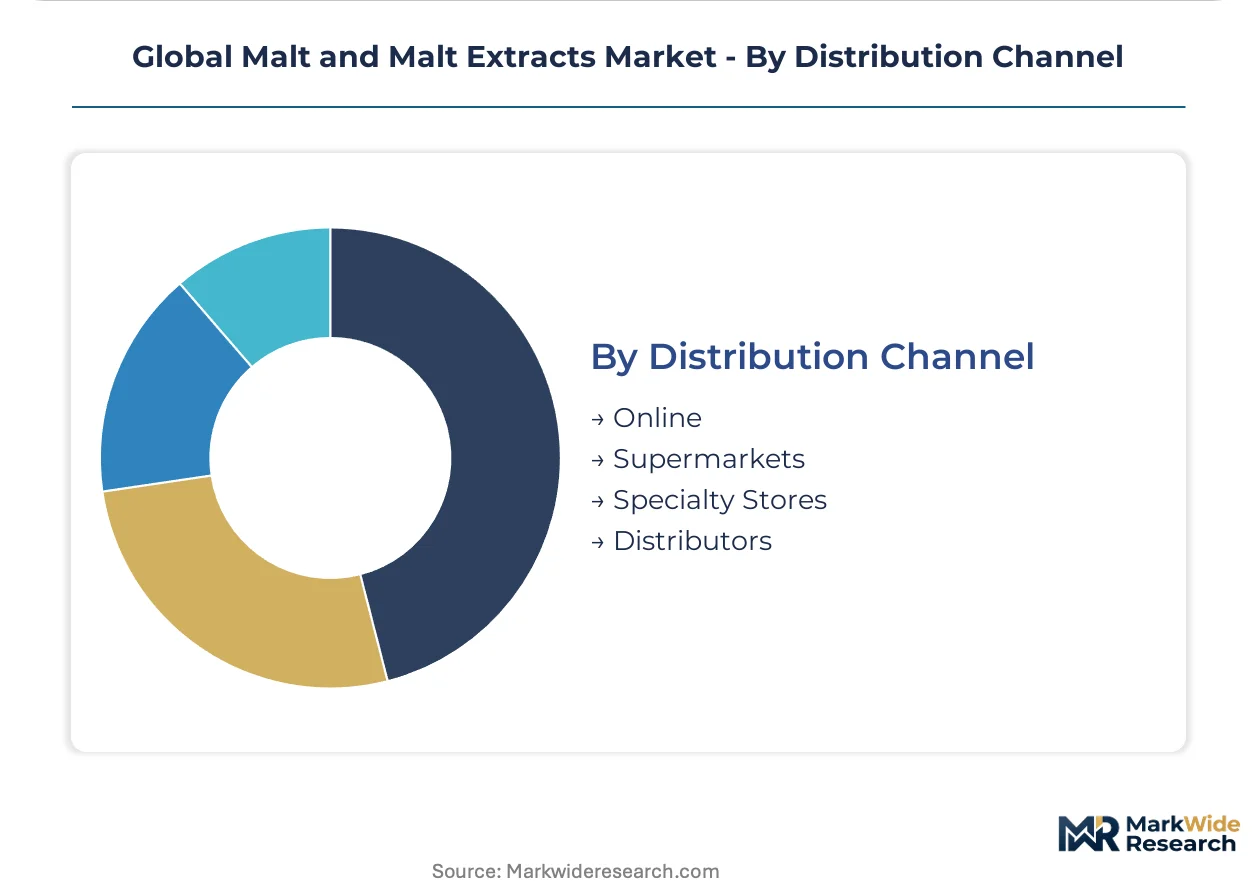
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with direct distributor relationships dominating bulk beverage procurement while digital channels fragment small-lot purchasing.
- Online:Direct-to-consumer platforms and B2B marketplaces serve homebrewing hobbyists and small craft breweries seeking specialty malt varieties unavailable through traditional distribution. Subscription models for liquid malt extract are compressing distributor markups in the United States and United Kingdom.
- Supermarkets:Mass retail placement for dry malt extract and malt-based beverage concentrates targets occasional bakers and non-alcoholic drink consumers in Germany and Austria.
- Specialty Stores:Homebrewing retailers and brewing supply shops provide technical guidance and grain milling services, sustaining premium positioning for heritage barley varieties.
- Distributors:Regional beverage ingredient distributors manage bulk logistics, quality documentation, and just-in-time delivery for commercial breweries across France, Belgium, and the Netherlands.
Distributor networks handle the bulk of commercial brewery volume; online channels are expanding most quickly in craft and homebrewing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malting barley cultivation concentrates in the North European Plain, where soil chemistry and maritime climate patterns sustain enzymatic quality specifications demanded by premium brewers. Processing capacity clusters along Rhine-Ruhr industrial corridors and Great Lakes shipping networks, creating procurement dependencies that reshape regional trade flows.
Germany
Traditional brewing heritage in Bavaria and Baden-Württemberg sustains premium malt consumption for Reinheitsgebot-compliant lager production. The BfR enforces mycotoxin thresholds in malting barley that directly shape supplier qualification protocols for domestic brewers. Munich and Hamburg anchor continental Europe's densest malting capacity cluster, where electrified kilning retrofits are accelerating under EU Green Deal carbon accounting mandates.
United States
Craft brewing expansion across the Pacific Northwest and Upper Midwest drives specialty malt demand for provenance-labeled estate programs. FDA food additive regulations govern malt extract purity standards for cross-border bakery and confectionery applications. Wisconsin and Montana barley-growing regions are consolidating direct contracting relationships with heritage maltsters, displacing spot-market purchasing for flavor-differentiated portfolios.
France
Industrial baking demand in Paris Basin and Nord-Pas-de-Calais sustains enzymatic malt extract procurement for clean-label dough conditioning. ANSES evaluates contaminant thresholds alongside EFSA harmonized standards, tightening documentation requirements for food manufacturing channels. Strasbourg and Lille host integrated malting groups that leverage Eastern European barley origination scale for continental supply security.
Belgium
Trappist and lambic brewing traditions in Flanders and Wallonia preserve specialty kilning techniques for aromatic complexity. REACH chemical safety frameworks extend substance registration obligations to enzymatic processing aids, reshaping import documentation for malt extract suppliers. Antwerp's continental malthouse network sustains supply relationships with major brewers seeking Belgian heritage positioning.
India
Premium beer segment expansion in Maharashtra and Karnataka states lacks domestic specialty malting infrastructure, creating import dependency for craft brewers. FSSAI standards govern food-grade malt extract labeling for bakery and confectionery substitution of refined sugars. Mumbai and Bangalore brewing clusters are driving demand for enzymatic extracts that support clean-label positioning in urban consumer markets.
Global Malt and Malt Extracts Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue craft-provenance and clean-label extract niches. The vendor base stratifies across three capability tiers: integrated agricultural processors controlling barley origination, specialized maltsters commanding heritage kilning expertise, and extract refiners serving industrial food manufacturing. Two dominant competitive moves are reshaping positioning: biogas kiln technology convergence for net-zero production claims, and direct-to-homebrewer subscription channels that bypass traditional distributor markups.
Within the integrated agricultural processing tier, Boortmalt and Malteurop Group exemplify scale-driven origination strategies across continental Europe. Muntons plc occupies a position bridging malt production and extract refinement for food manufacturing customers. Among these, the Belgian-heritage malting specialist and the French-Eastern European origination group represent divergent geographic anchoring approaches that shape procurement relationships with major brewers.
| Leading Market Players |
|---|
| Boortmalt |
| Muntons plc |
| Malteurop Group |
| Malt Products Corporation |
| Viking Malt |
| GrainCorp Limited |
| Groupe Soufflet |
| Holland Malt |
| Rahr Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive barley origination across French and Eastern European growing regions anchors supply security for integrated malting groups while simultaneously underwriting pricing power through volume-scale contracting. This backward integration into agricultural inputs insulates major processors from spot-market volatility in malting barley, creating divergent margin structures between estate-malt specialists and commodity traders.
Pricing Analysis
Certificate-of-analysis bundling separates beverage-grade malt contracts from unbundled food-manufacturing extract sales, with brewers paying premiums for batch-specific diastatic power documentation. Three-tier pricing structure across estate-provenance, regional-standard, and commodity-economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-tier liquid malt extract is intensifying because refrigerated logistics constraints limit distribution radius competition. Craft brewers exhibit lowest price sensitivity for heritage barley designations, while industrial bakeries drive hardest bargaining on enzymatic extract tonnage.
Supply Chain Analysis
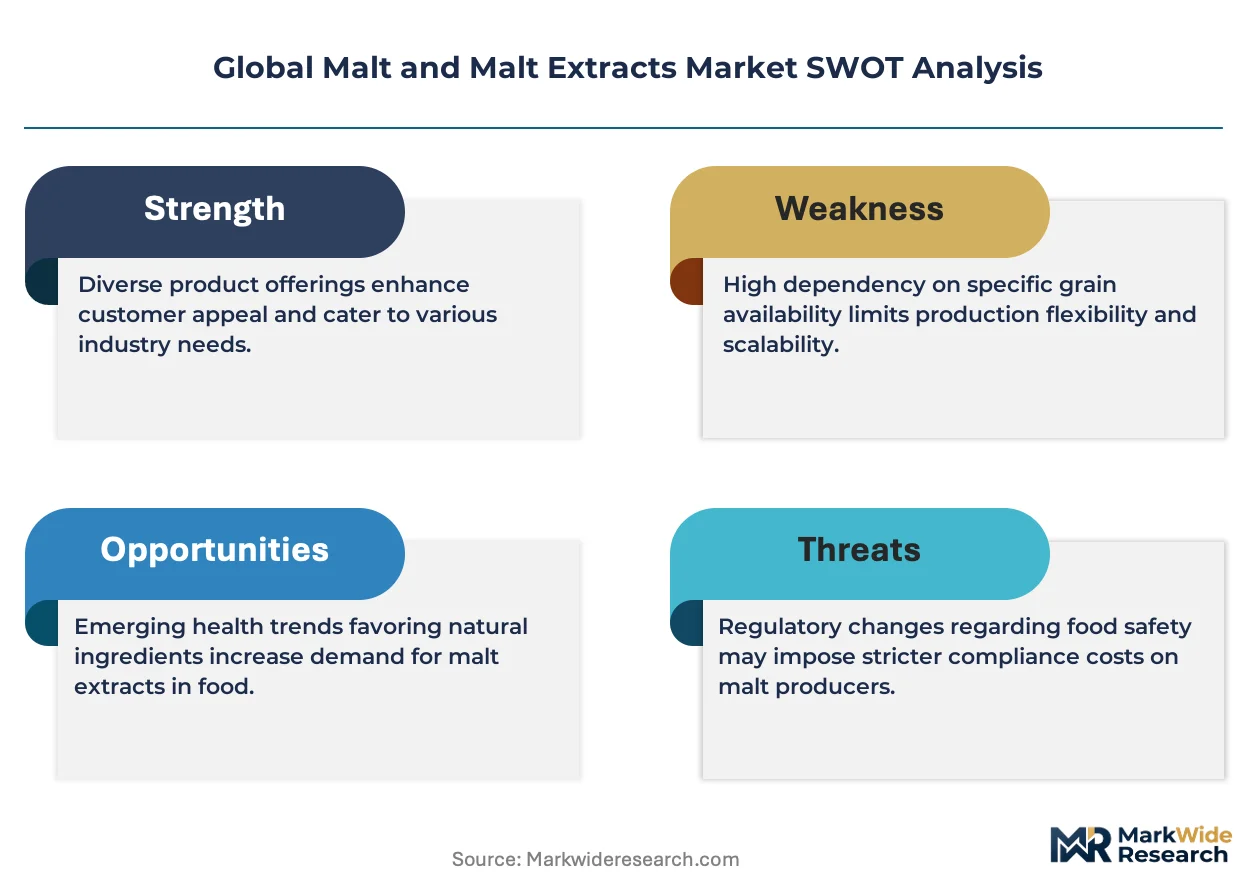
Malting barley supply rests on Australian, Canadian, and French growing regions where maritime climate patterns sustain enzymatic quality specifications. Germination floor operations draw from fertilizer-intensive agricultural inputs and natural gas-dependent kilning energy, tethering cost structures to commodity cycles. Single-source vulnerability concentrates in the Rhine-Ruhr corridor where German malting capacity clustering creates continental procurement risk. Distribution runs through regional beverage ingredient distributors managing bulk logistics and just-in-time delivery for commercial breweries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal scope-three emissions reporting creates a barrier-to-entry moat for certified low-carbon barley suppliers. The regulatory burden favors incumbents with established carbon accounting infrastructure and penalizes speculative entrants lacking agricultural origination scale.
For Market Incumbents: Hedge against barley input volatility through long-term contracting with heritage growers in Montana and Wisconsin, displacing spot-market exposure. Accelerate electrified kilning retrofits ahead of EU carbon disclosure deadlines to capture premium contract structures from sustainability-committed brewers. Master maltster apprenticeship pipelines in Belgium and Czech Republic represent a critical capability defense against knowledge attrition. For New Entrants and Emerging Players: Direct-to-homebrewer subscription channels bypass traditional distributor markups and compress customer acquisition costs in United States and United Kingdom markets. Target underpenetrated specialty malt demand in Maharashtra and Karnataka states where domestic Indian infrastructure lags premium beer expansion. Clean-label bakery extract positioning leverages enzymatic substitution trends without requiring beverage-grade certification overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated agricultural processors with captive barley origination and established brewer relationships. Long-term viability favors operators with biogas kiln technology convergence enabling net-zero production claims against tightening EU standards. Watch anaerobic digestion adoption rates as the inflection signal separating compliant premium suppliers from stranded commodity assets.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Kilning Retrofit | EU Green Deal carbon accounting mandates accelerate capital deployment for scope-three compliance in German malthouses. |
| Heritage Barley Direct Contracting | Pacific Northwest estate-malt programs command measurable premiums over commodity equivalents through provenance labeling. |
| Biogas Kiln Technology Convergence | Anaerobic digestion of malt byproducts paired with electrified processing enables verifiable net-zero production claims. |
| E-commerce Ingredient Channel Launch | Subscription models for liquid malt extract compress distributor markups in United States homebrewing markets. |
| Specialty Malt Portfolio Expansion | Distinct Lovibond color ranges and diastatic power specifications capture craft brewing flavor differentiation premiums. |
Study Parameters
Independent corroboration across malting plant managers, brewer procurement leads, and food manufacturing R&D directors underwrites the qualitative findings on processing technology adoption. Primary interviews with barley growers in Australian and Canadian regions, distribution channel partners in Benelux markets, and regulatory affairs specialists at BfR and ANSES were validated against customs and trade data, EU agricultural emission disclosures, and SEC filings from listed grain processors. Bottom-up volume builds from installed malting capacity and top-down demand estimates from beverage production statistics were reconciled through iterative triangulation.
Rate-of-change decomposition across product format, end-use application, and geographic adoption pattern governed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include liquid versus dry extract formats, beverage versus food manufacturing end-uses, and craft versus industrial buyer archetypes. CAGRs were derived from elasticity-adjusted demand projections incorporating barley yield variability and regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal implementation timelines and craft brewery formation rates in underpenetrated markets.
Inputs from malting trade associations and agricultural ministry statistics were available through the study window; gaps in real-time carbon accounting verification at farm level introduce uncertainty bands around low-carbon premium sizing. Forecasts reflect documented assumptions on electrification capital costs and brewer willingness-to-pay for certified provenance. A small set of triggers including EU scope-three enforcement stringency and Australian drought frequency warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Butter Market
Ingredients
Textural Food Ingredients Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Textured Soy Flour Market
Ingredients
Vitamin D Ingredients Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Potato Peel Powder Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Mineral Premix Market
Ingredients
US Choline Bitartrate Market