
 Citrus Based Dietary Fibers Market | 2026-2036
Citrus Based Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Based Dietary Fibers Market Analysis
EFSA's health claim assessments is restructuring the cost-of-entry calculus for citrus fiber suppliers seeking European market access. Ingredion Incorporated leverages its global ingredient platform to sustain formulation partnerships across beverage and bakery channels. CP Kelco Inc. anchors its position through specialized pectin and citrus fiber extraction expertise in hydrocolloid applications.
Citrus based dietary fibers comprise cell wall polysaccharides including pectin, cellulose, and hemicellulose extracted from citrus peel byproducts, typically containing 60-80% total dietary fiber with water-holding capacities exceeding 8g/g for premium grades. These fibers function as fat replacers, texturizers, and stabilizers in reduced-calorie and clean-label food systems. Orange fiber dominates volume given the scale of orange juice processing residuals, while grapefruit fiber commands premium positioning in dietary supplement applications for its higher bioactive flavonoid content. The food industry end user segment captures the deepest margin pools through long-term supply contracts with multinational processed food manufacturers.
FDA's dietary fiber definition under the Nutrition Facts Label final rule shapes which citrus fiber structures qualify for declared fiber content in US products. EFSA's health claim evaluation framework and EU Regulation 1924/2006 determine permitted nutritional communications for citrus fiber-enriched foods across European markets. Stakeholders must monitor evolving enzyme-assisted extraction technologies and their implications for fiber purity thresholds under both FDA and EFSA guidance documents.
Market Dynamics
Enzyme-assisted extraction technology is compressing fiber purity thresholds and requalifying citrus fiber structures under evolving FDA and EFSA guidance, forcing suppliers to rebuild validation dossiers.
Growth Catalysts
- Clean-label texture modification:Beverage formulators in North America are expanding citrus fiber inclusion to replace synthetic hydrocolloids in reduced-calorie formulations.
- EU Regulation 1924/2006:EFSA's health claim assessment framework is creating qualified fiber communication pathways for fortified bakery and supplement applications.
- Grapefruit fiber bioactives:Dietary supplement manufacturers are capturing premium positioning through flavonoid-rich grapefruit fiber differentiation.
Market Restraints
- Orange peel supply concentration:Volume dependency on Florida and São Paulo orange juice processing residuals creates geographic vulnerability to citrus crop cycles.
- FDA fiber definition friction:The Nutrition Facts Label final rule disqualifies certain citrus fiber structures from declared fiber content, narrowing qualified ingredient pools.
- Pectin substitution pressure:Apple and sugar beet pectin sources compete for hydrocolloid applications with comparable gelling functionality.
Strategic Opportunities
- Germany bakery innovation cluster:Long-term supply contracts with multinational processed food manufacturers in Baden-Württemberg offer deep margin capture potential.
- California plant-based corridor:Meat and dairy alternative manufacturers in Los Angeles and San Francisco counties are integrating citrus fiber for fat mimetic functionality.
- Enzyme-pectin convergence:Combined enzymatic extraction and pectin coproduction technologies are opening integrated citrus peel valorization models.
Industry Challenges
- Extraction technician scarcity:Specialized enzyme-assisted processing expertise remains concentrated among legacy pectin manufacturers.
- Dual-agency validation timelines:Parallel FDA and EFSA fiber qualification dossiers extend time-to-market for novel citrus fiber structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Based Dietary Fibers Market |
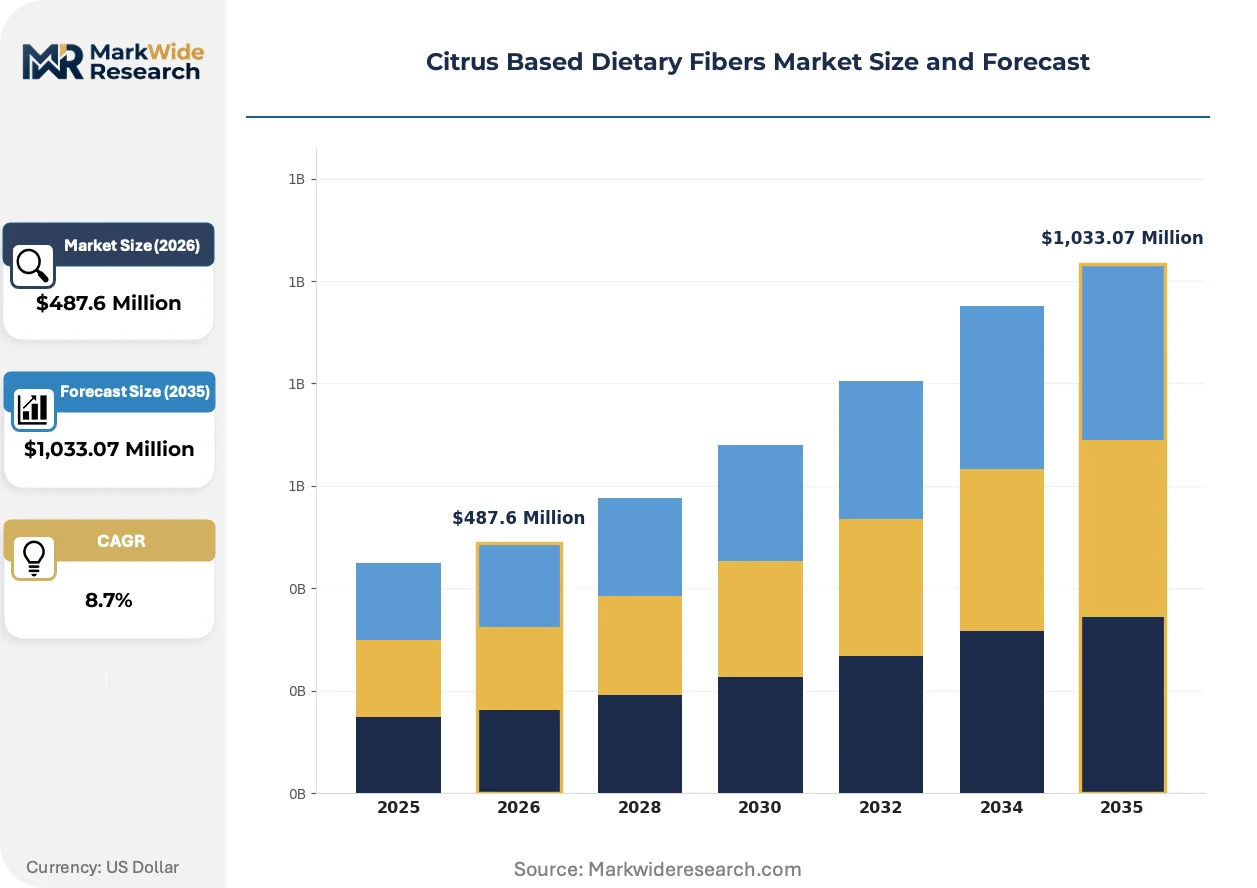
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange Fiber, Lemon Fiber, Grapefruit Fiber, Lime Fiber Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Industry, Pharmaceuticals, Dietary Supplements, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Ingredion Incorporated, Golden Health, CP Kelco Inc., CEAMSA, Herbafood Ingredients GmbH, Cargill Inc., Tate & Lyle PLC, Florida Food Products Inc., Fiberstar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Based Dietary Fibers Market Emerging Trajectories
Technology, regulatory redefinition, and procurement model evolution are converging to reshape competitive positioning across extraction, formulation, and end-use channels.
Enzyme-assisted extraction is electrifying citrus fiber purification by targeting specific pectin-cellulose bonds without thermal degradation. Premium-grade suppliers in Germany and California are adopting these systems to achieve water-holding capacities exceeding 8g/g. This precision is electrifying the cost structure for clean-label fat replacement in plant-based meat systems.
EFSA's evolving health claim assessments are restructuring ingredient qualification pathways for European market access. The framework demands clinical substantiation for fiber-specific physiological effects beyond generic bulking claims. Bakery and supplement manufacturers in Germany and France are reformulating to align with permitted nutritional communications under EU Regulation 1924/2006.
Direct supply agreements between citrus fiber extractors and plant-based food manufacturers are displacing traditional ingredient distributor intermediation. California's manufacturing corridor is consolidating procurement through captive supply relationships with Arizona and Florida peel processors. This channel compression is most visible in meat alternative and functional beverage verticals where formulation partnerships lock in multi-year volume commitments.
Citrus Based Dietary Fibers Market Segmentation
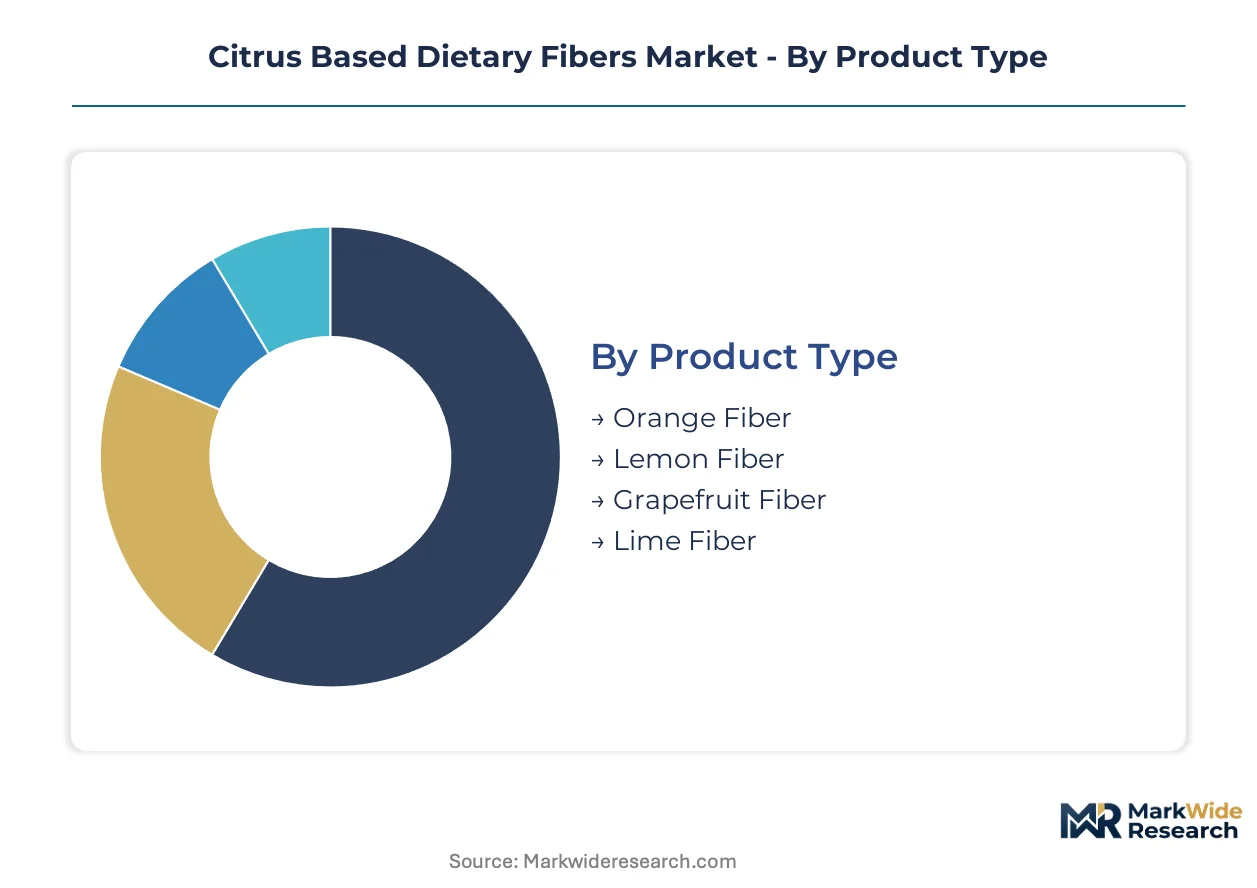
Citrus fiber procurement patterns diverge sharply across product grades and application requirements. Formulators prioritize water-holding capacity thresholds and clean-label certification tiers when selecting specific citrus sources.
Product Type:
Standardization dominates commodity grades while premium extraction protocols enable customized functional profiles for targeted end-uses.
- Orange Fiber:Cell wall polysaccharides extracted from Valencia and Navel orange peel residuals, typically yielding 60-80% total dietary fiber with water-holding capacities of 6-10g/g depending on extraction intensity. Beverage manufacturers in California and São Paulo procurement corridors favor this grade for cost-efficient texture modification in reduced-calorie formulations, though volume dependency on Florida and Brazilian orange juice processing creates geographic vulnerability to crop cycles.
- Grapefruit Fiber:Higher naringin and hesperidin flavonoid content distinguishes this grade, commanding premium positioning in dietary supplement applications. Supplement manufacturers in Germany's Baden-Württemberg cluster leverage these bioactives for antioxidant positioning, with EFSA health claim assessments under EU Regulation 1924/2006 shaping permitted nutritional communications.
- Lemon Fiber:Lower pectin yield but cleaner flavor profile suits delicate bakery applications requiring minimal taste interference.
- Lime Fiber:Niche positioning in Latin American beverage markets leverages regional processing infrastructure.
Leading the category by volume: Orange Fiber. Growing fastest: Grapefruit Fiber.
Application:
Cost tiers separate commodity texture modification from premium functional nutrition positioning across end-use channels.
- Beverages:Clean-label hydrocolloid replacement in reduced-calorie and plant-based drink systems. North American formulators are expanding inclusion rates to displace synthetic stabilizers, with enzyme-assisted extraction technologies enabling higher purity grades that qualify under FDA's evolving dietary fiber definition.
- Bakery Products:Fat mimetic functionality and moisture retention in reduced-calorie bread and pastry applications. Germany's bakery innovation cluster drives specification intensity through long-term supply contracts with multinational processed food manufacturers.
- Dairy Products:Texture stabilization in yogurt and fermented applications, particularly in European clean-label reformulations.
- Confectionery:Gelling and structuring in reduced-sugar candy systems, constrained by flavor masking requirements.
Volume concentrates in Beverages. Steepest expansion trajectory: Bakery Products.
End User:
Customer type determines margin capture potential through contract structure and technical service intensity.
- Food Industry:Multinational processed food manufacturers lock in multi-year volume commitments through direct supply agreements, displacing traditional ingredient distributor intermediation. California's plant-based food manufacturing corridor exemplifies this channel compression, with meat alternative and functional beverage verticals consolidating procurement through captive relationships with Arizona and Florida peel processors.
- Dietary Supplements:Premium pricing for bioactive-enriched grapefruit fiber grades, with EFSA health claim substantiation requirements restructuring qualification pathways.
- Pharmaceuticals:Excipient applications in controlled-release formulations, limited by pharmacopeial certification requirements.
- Animal Feed:Citrus peel valorization for ruminant nutrition, competing with other agricultural fiber sources on cost.
Deepest margin pools: Food Industry. Gaining share fastest: Dietary Supplements.
Distribution Channel:
Supply concentration dictates channel efficiency across geographic and customer scale segments.
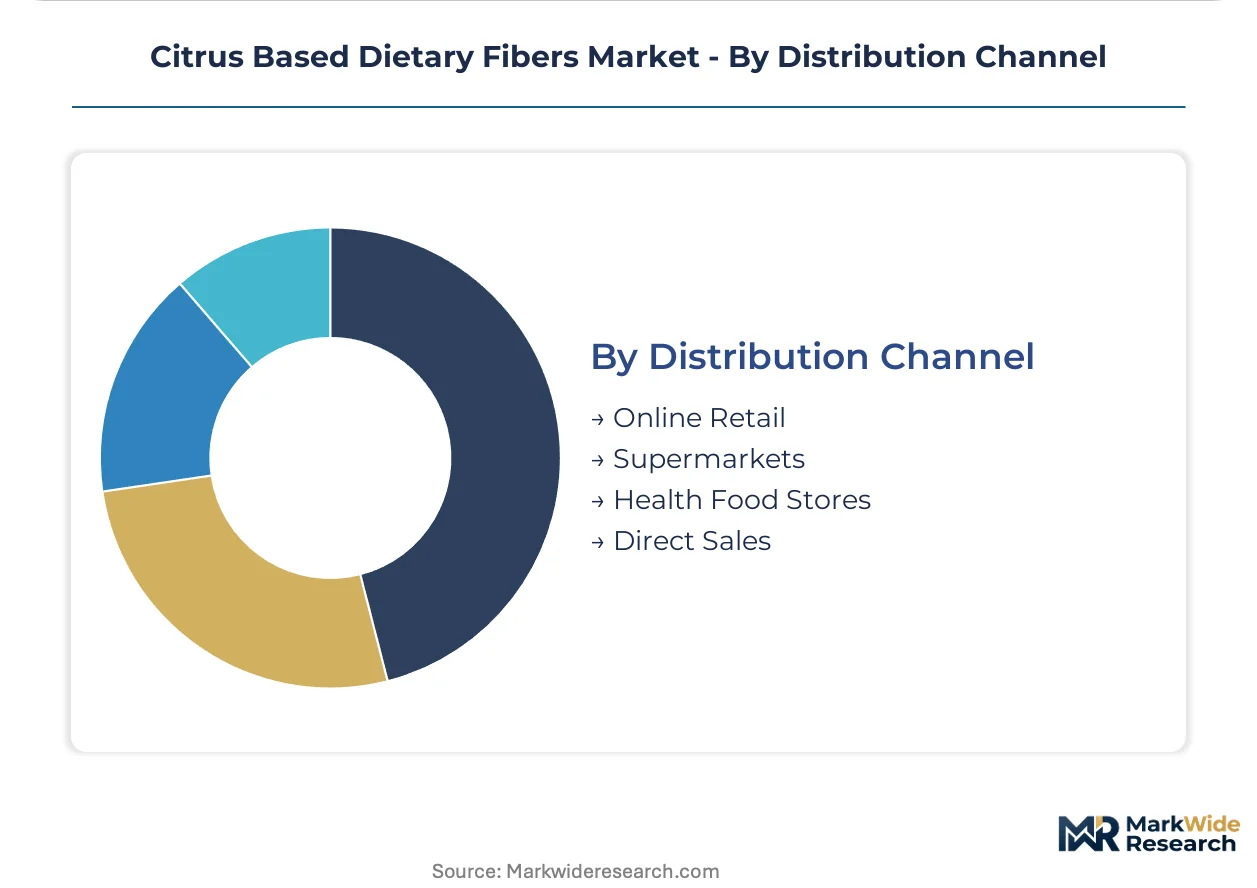
- Direct Sales:Formulation partnerships between citrus fiber extractors and plant-based food manufacturers enable technical collaboration and multi-year volume commitments. This channel dominates California's manufacturing corridor and Germany's bakery cluster.
- Supermarkets:Private-label fiber ingredient retail for small-scale food manufacturers and institutional buyers.
- Health Food Stores:Niche positioning for organic-certified and specialty grades targeting artisanal producers.
- Online Retail:Emerging procurement path for mid-scale manufacturers seeking transparent specification documentation and flexible order quantities.
Primary volume flow: Direct Sales. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's food innovation zones concentrate European citrus fiber demand through tax-advantaged R&D facilities. California's plant-based manufacturing corridor anchors North American procurement through direct supply relationships with Arizona peel processors. São Paulo's orange juice processing belt generates residual feedstock for Latin American extraction capacity.
United States
Beverage formulators in Los Angeles County displace synthetic hydrocolloids with clean-label citrus fiber for reduced-calorie applications. FDA's Nutrition Facts Label final rule disqualifies certain fiber structures from declared content, narrowing qualified ingredient pools. California's plant-based meat corridor integrates citrus fiber for fat mimetic functionality through captive supply agreements with Florida peel processors.
Germany
Bakery manufacturers in Baden-Württemberg lock in multi-year volume commitments for texture modification in reduced-calorie bread systems. EFSA's health claim assessments under EU Regulation 1924/2006 restructure permitted nutritional communications for fortified applications. Stuttgart's processed food innovation cluster drives specification intensity through direct extractor partnerships.
Brazil
São Paulo's orange juice processing residuals supply volume-dependent fiber extraction for export markets. The country's national food safety regulator monitors fiber purity thresholds under Mercosur harmonization protocols. Campinas' agricultural processing belt concentrates peel valorization infrastructure for hydrocolloid coproduction.
China
Functional beverage manufacturers in Guangdong Province adopt citrus fiber for clean-label stabilization in reduced-sugar formulations. SAMR's evolving dietary fiber standards shape import qualification pathways for foreign suppliers. The Pearl River Delta's food manufacturing corridor consolidates procurement through direct relationships with domestic peel processors.
Citrus Based Dietary Fibers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction, formulation, and distribution tiers. The vendor base stratifies between global ingredient platforms with multi-category portfolios and regional citrus fiber specialists with peel-processor captive supply. Three archetypes dominate: hydrocolloid-integrated extractors, beverage-focused formulators, and bakery-specialized distributors. Capacity expansion and direct supply agreement formation constitute the dominant competitive moves, displacing traditional distributor intermediation in California and Germany.
Among North American ingredient platforms, Ingredion Incorporated and Florida Food Products Inc. occupy positions spanning beverage and bakery channels. CP Kelco Inc. anchors the hydrocolloid-integrated archetype through specialized extraction expertise. European specialists Herbafood Ingredients GmbH and CEAMSA exemplify regional concentration in Baden-Württemberg and Galicia respectively. Tate & Lyle PLC and Cargill Inc. represent diversified conglomerates with global formulation partnerships.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Golden Health |
| CP Kelco Inc. |
| CEAMSA |
| Herbafood Ingredients GmbH |
| Cargill Inc. |
| Tate & Lyle PLC |
| Florida Food Products Inc. |
| Fiberstar Inc. |
| Others |
Supply Flow & Price Mechanics
Captive supply relationships between Arizona peel processors and California plant-based manufacturers anchor both procurement security and premium-grade pricing power across the citrus fiber value chain. This backward integration into raw material sourcing insulates contract holders from spot-market volatility while compressing margins for distributor-dependent competitors.
Pricing Analysis
Short lead-time premiums of 15-20% apply to enzyme-assisted extraction grades qualifying under FDA's evolving fiber definition, while spot inventory discounts penetrate standard orange fiber tiers. Three-tier pricing structure across premium enzyme-extracted, standard chemical-extracted, and economy peel-residual grades separates hydration-performance thresholds. Cost compression in standard grades is intensifying because Brazilian orange juice processing fluctuations expand supply uncertainty. Small-scale artisanal manufacturers exhibit highest price sensitivity, whereas multinational beverage formulators prioritize specification consistency over unit cost.
Supply Chain Analysis
Domestic-content mandates under California's clean-label procurement preferences are reshaping sourcing toward Arizona and Florida peel processors with verified chain-of-custody documentation. Geographic supply concentration centers on Brazil, the United States, and Spain, with São Paulo's orange juice belt feeding export-oriented extraction capacity. Raw material dependencies rest on Valencia and Navel orange peel residuals, specialized enzyme formulations, and pectin coproduction infrastructure. Single-source vulnerability runs through Florida's hurricane-exposed citrus belt. Distribution runs through direct formulation partnerships displacing traditional ingredient distributors in North American and European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Citrus fiber market positioning is becoming a vertical-integration race, with upstream control over enzyme-assisted extraction capacity and downstream captive supply agreements representing the decisive margin levers.
For Market Incumbents: Lock in multi-year peel supply agreements with São Paulo and Florida processors before harvest cycle volatility intensifies. Expand enzyme-assisted extraction capacity in Baden-Württemberg to capture EFSA-compliant premium grades. Apple and sugar beet pectin substitution pressure demands accelerated R&D in grapefruit fiber bioactive differentiation. For New Entrants and Emerging Players: E-commerce ingredient platforms targeting mid-scale European bakery manufacturers offer the most penetrable entry vector. Online retail procurement channels enable transparent specification documentation and flexible order quantities without distributor markup. Germany's artisanal bread innovation cluster presents underserved demand for lemon fiber's cleaner flavor profile. For Investors and Strategic Acquirers: Exit pathways concentrate in hydrocolloid-integrated extractors with captive enzyme technology and established EFSA validation dossiers. Five-to-ten year viability hinges on regulatory qualification moats rather than commodity volume scale. Monitor FDA fiber definition finalization timing as the critical inflection signal for portfolio rebalancing between standard and premium-grade exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Peel Supply Agreement | Insulates contract holders from Florida-Brazil crop cycle volatility. |
| Enzyme-Assisted Extraction Scale-Up | Unlocks EFSA and FDA qualification pathways for premium-grade positioning. |
| Direct Formulation Partnership | Displaces distributor intermediation in California's plant-based corridor. |
| Grapefruit Fiber Bioactive Certification | Enables antioxidant health claim substantiation under EU Regulation 1924/2006. |
| Pectin Coproduction Integration | Maximizes peel valorization economics through hydrocolloid diversification. |
Methodological Framework
Document review covered FDA guidance documents, EFSA health claim assessments, EU Regulation 1924/2006 implementation reports, and citrus processing industry trade data, complemented by interviews with extraction plant managers, beverage formulator R&D directors, bakery procurement leads, and dietary supplement regulatory affairs specialists. Secondary validation drew from customs import records, food ingredient distributor transaction databases, and enzyme technology patent filings. Bottom-up volume modeling and top-down value reconciliation ensured cross-method consistency.
Historical extraction capacity expansion patterns were cross-referenced against expert panel input on enzyme technology adoption timelines. Segmentation modeling spanned product type, application vertical, end-user category, and geographic regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label reformulation intensity and EFSA health claim approval trajectories. Forecast inputs included orange juice processing residual availability indices and plant-based meat alternative formulation partnership formation rates.
The model holds under stable FDA-EFSA regulatory convergence assumptions; deviation in fiber definition finalization timing or enzyme cost curves would shift volume trajectories. Forecasts reflect documented assumptions regarding EFSA health claim substantiation success rates and California procurement channel consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydroxytyrosol Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Native Starch Market
Ingredients
Mung Bean Starch Market
Ingredients
Vitamin D Ingredients Market
Ingredients
Egg White Powder Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Edible Animal Fat Market
Ingredients
Drum to Hopper Blends Premix Market