
 Carotenes Market | 2026-2036
Carotenes Market Size, Share, and Industry Trends Forecast 2026-2036
Carotenes Market Analytics
Multi-source extraction from both synthetic and natural origins is hardening as the dominant procurement pattern among carotene suppliers. BASF SE leverages its petrochemical feedstock integration to sustain cost-competitive synthetic beta-carotene output at scale. Kemin Industries anchors its position through vertically controlled marigold cultivation for lutein and zeaxanthin extraction. DSM-Firmenich differentiates via fermentation-derived carotenoids that bypass agricultural supply volatility.
Carotenes comprise lipid-soluble tetraterpenoid pigments—alpha-carotene, beta-carotene, lutein, and zeaxanthin—synthesized via either chemical catalysis or biological extraction from algae, plants, and fungi, serving primarily as colorants, antioxidants, and provitamin A precursors across formulated goods. Powder and oil forms dominate current volume given their compatibility with dry premixes and lipid-based food matrices, though suspension formats are gaining traction in beverage fortification where dispersion stability determines shelf-life performance. Nutraceuticals represent the fastest-expanding application segment as dietary supplement producers seek GRAS-affirmed ingredients for eye health and immune positioning.
FDA color additive regulations and EFSA novel food catalog listings collectively shape product approval pathways and label claim permissibility for carotene suppliers seeking multi-jurisdiction placement. BIS food additive standards in India and China's GB standards for natural food colorants add further compliance layers for manufacturers targeting Asia-Pacific expansion. Stakeholders must monitor evolving clean-label certification thresholds and fermentation-derived ingredient acceptance curves to calibrate portfolio mix decisions.
Market Dynamics
Fermentation-derived carotenoid production is compressing agricultural supply dependencies while FDA and EFSA regulatory divergence forces dual-track compliance investments from ingredient suppliers seeking multi-territory placement.
Growth Catalysts
- EFSA Novel Food Catalog Expansion:Accelerated beta-carotene approvals for fortified dairy applications in Germany and France are opening formulation pipelines previously restricted to synthetic alternatives.
- Algae Cultivation Scale-Up:Closed-photobioreactor systems for Haematococcus pluvialis astaxanthin extraction are reducing seasonality risks that plagued open-pond operations.
- Clean-Label Certification Thresholds:Retailer-driven non-GMO and organic standards in US natural foods channels are displacing petroleum-derived colorants from premium product lines.
Market Restraints
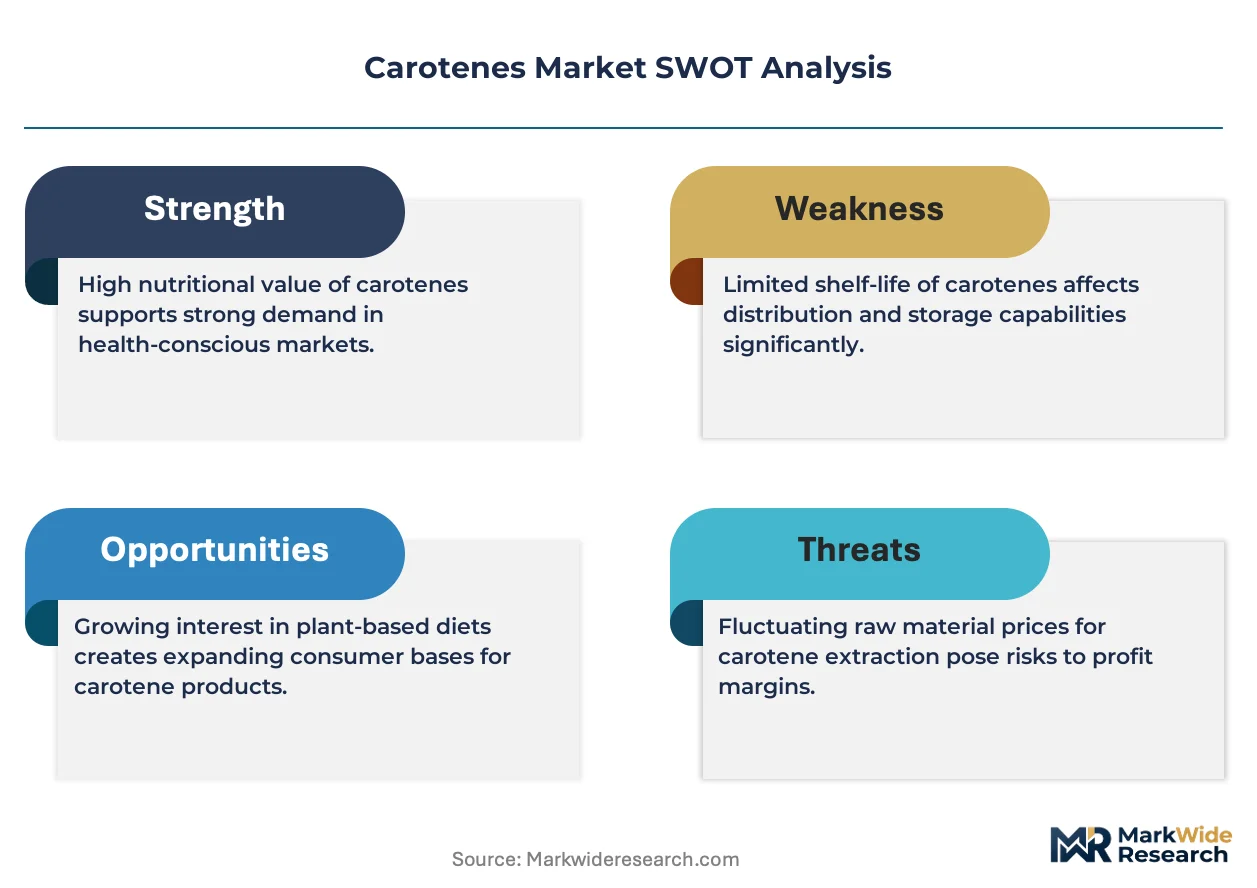
- Marigold Feedstock Volatility:Climate-sensitive flower cultivation in India and Mexico creates lutein supply uncertainty that synthetic producers exploit in contract negotiations.
- Petrochemical Input Tethering:Synthetic beta-carotene remains cost-anchored to benzene and acetylene price cycles that natural extractors cannot match at volume.
- Fermentation Capacity Concentration:Commercial-scale microbial carotenoid facilities cluster in Switzerland and the Netherlands, creating geographic single-point vulnerabilities.
Strategic Opportunities
- China GB Standard Alignment:Natural food colorant classifications under SAMR are easing import pathways for fermentation-derived ingredients previously categorized as additives.
- Beverage Suspension Formats:Nano-dispersion technologies for oil-soluble carotenoids in clear drinks address a $400 million addressable gap in functional hydration.
- India PLI Scheme Leverage:Production-linked incentives for specialty chemicals are attracting contract fermentation investments that could rebalance Asia-Pacific supply origins.
Industry Challenges
- Dual-Jurisdiction GRAS Submissions:Parallel FDA notification and EFSA novel food dossier preparation drains technical regulatory capacity from mid-scale suppliers.
- Photobioreactor Capex Burden:Algae cultivation infrastructure requires $50-80 million per commercial facility, excluding downstream extraction equipment.
- Cross-Contamination Protocol Complexity:Fermentation facilities switching between carotenoid strains face validation timelines that extend batch release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotenes Market |
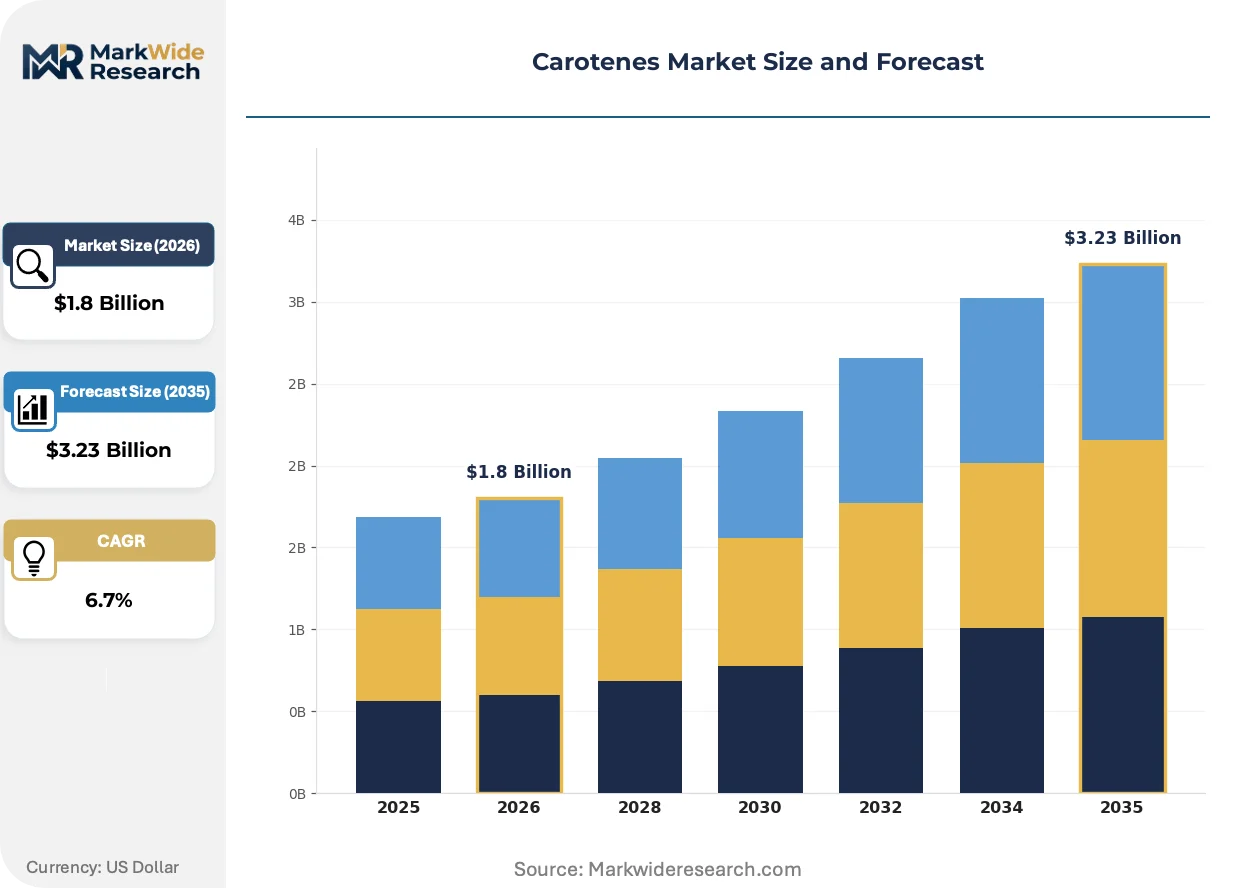
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Carotene, Beta-Carotene, Lutein, Zeaxanthin Form: Powder, Oil, Granules, Suspension Application: Food & Beverages, Nutraceuticals, Cosmetics, Animal Feed Customer Type: Food Manufacturers, Dietary Supplement Producers, Personal Care Brands, Feed Suppliers |
| Companies Covered | BASF SE, Kemin Industries, DSM-Firmenich, Allied Biotech Corporation, Chr. Hansen Holdings A/S, Döhler GmbH, Cyanotech Corporation, Sensient Technologies Corporation, Algatech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotenes Market Evolving Landscape
Continuous processing technologies and regulatory data-sharing mechanisms are compressing development timelines while buyer consolidation in nutraceuticals reshapes supplier relationship economics.
Precision fermentation platforms utilizing engineered Yarrowia lipolytica strains are automating carotenoid biosynthesis pathways that previously required multi-step chemical catalysis. Dietary supplement contract manufacturers in North America and Western Europe are adopting these systems at pilot scale, with commercial volumes expected within eighteen months. This automation is collapsing the traditional twelve-to-eighteen-month agricultural cultivation cycle into sub-ninety-day production windows.
REACH substance registration requirements for synthetic carotenoid intermediates are tightening documentation burdens on petrochemical-derived supply chains. ECHA's 2024 updated guidance on persistent, bioaccumulative, and toxic assessments now captures several legacy beta-carotene synthesis precursors. European food colorant distributors are responding by accelerating qualification of fermentation-derived alternatives that bypass petroleum feedstock classification.
Long-term offtake agreements between carotenoid suppliers and finished goods manufacturers are displacing spot-market purchasing that dominated the 2015-2022 period. Major dietary supplement brands in Germany and the United States now contract eighteen-to-twenty-four-month supply visibility, transferring inventory carrying costs upstream. This shift concentrates procurement leverage among buyers with balance-sheet capacity to commit volume, squeezing smaller formulators into distributor-mediated channels with narrower margin structures.
Carotenes Market Segmentation
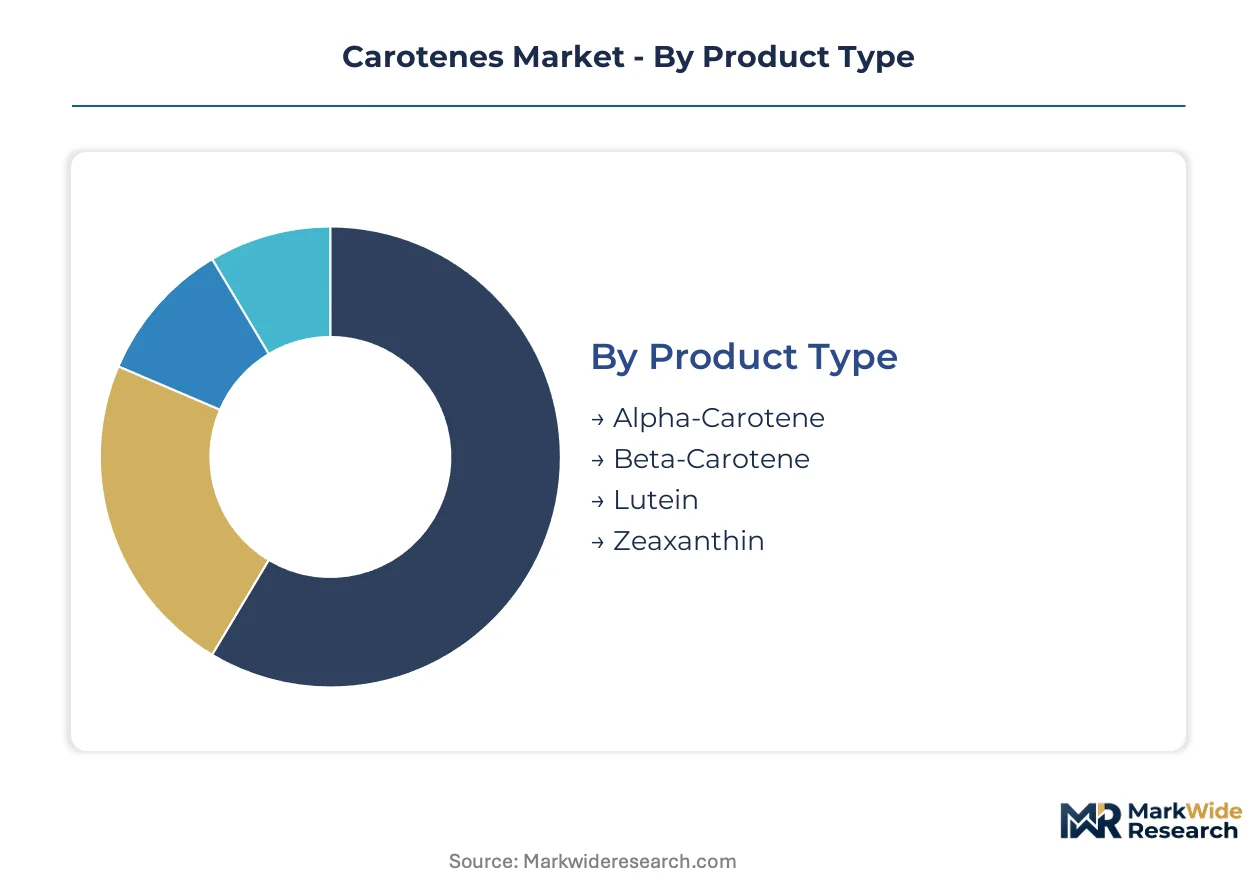
Carotene suppliers calibrate portfolio mix across four intersecting dimensions where form-factor compatibility and regulatory pathway complexity determine margin capture. Product type selection locks in synthesis method and agricultural exposure, while application focus dictates certification burden and customer concentration risk.
Product Type:
Volume concentration tilts toward beta-carotene given its dual utility as colorant and provitamin A precursor, though premium pricing accrues to specialized eye-health carotenoids with narrower supply bases.
- Beta-Carotene:Synthetic chemical catalysis and fermentation-derived routes both supply this provitamin A precursor, with FDA color additive approvals enabling broad food and beverage deployment. German dairy fortification programs under EFSA novel food catalog listings are absorbing expanded fermentation-derived volumes as synthetic alternatives face REACH documentation tightening.
- Lutein:Marigold flower extraction dominates this xanthophyll pigment used in eye health positioning, creating agricultural supply vulnerability to Indian and Mexican climate patterns. Dietary supplement contract manufacturers in North America command eighteen-to-twenty-four-month supply visibility agreements that transfer inventory risk upstream to extractors.
- Alpha-Carotene:Lesser-utilized provitamin A carotenoid concentrated in carrot and pumpkin sources.
- Zeaxanthin:Marigold co-extraction product paired with lutein in ocular health formulations.
Today's leader: Beta-Carotene. Tomorrow's challenger: Lutein.
Form:
Application matrix compatibility—dry premixes versus lipid matrices versus aqueous beverages—determines form selection and dictates dispersion technology requirements.
- Powder:Spray-dried and microencapsulated formats serve dry premix manufacturers and tablet compressors seeking flowability and shelf stability. Nutraceutical contract manufacturers in North America favor this form for multivitamin formulations where uniform distribution across batch volumes is critical.
- Oil:Lipid-dissolved carotenoids integrate directly into softgel encapsulation and fat-based food matrices without additional emulsification steps. Softgel producers absorb the majority of oil-form volumes given superior bioavailability claims in eye health supplement positioning.
- Granules:Agglomerated particles for direct compression tableting with reduced dust generation.
- Suspension:Nano-dispersed oil-soluble carotenoids in aqueous media for clear beverage fortification where optical clarity must be maintained.
Powder and oil formats anchor current revenue, yet suspension technologies are climbing the fastest as functional hydration brands seek clean-label colorant alternatives.
Application:
End-use diversification spreads regulatory compliance burden while concentrating R&D investment in segments with strongest margin expansion potential.
- Nutraceuticals:Dietary supplement producers drive GRAS-affirmed ingredient demand for immune and eye health positioning, with German and US brands contracting long-term offtake agreements that displace spot purchasing. Precision fermentation platforms utilizing engineered Yarrowia lipolytica strains are collapsing traditional agricultural cultivation cycles into sub-ninety-day production windows for this segment.
- Food & Beverages:Natural colorant substitution under FDA and EFSA frameworks is displacing petroleum-derived alternatives in premium product lines. US natural foods channels impose retailer-driven non-GMO and organic standards that filter supplier qualification.
- Cosmetics:Topical antioxidant applications in personal care formulations with stability challenges in emulsion systems.
- Animal Feed:Poultry pigmentation and aquaculture coloration with cost-sensitive procurement patterns.
Nutraceuticals capture premium pricing; food and beverages deliver volume scale.
Customer Type:
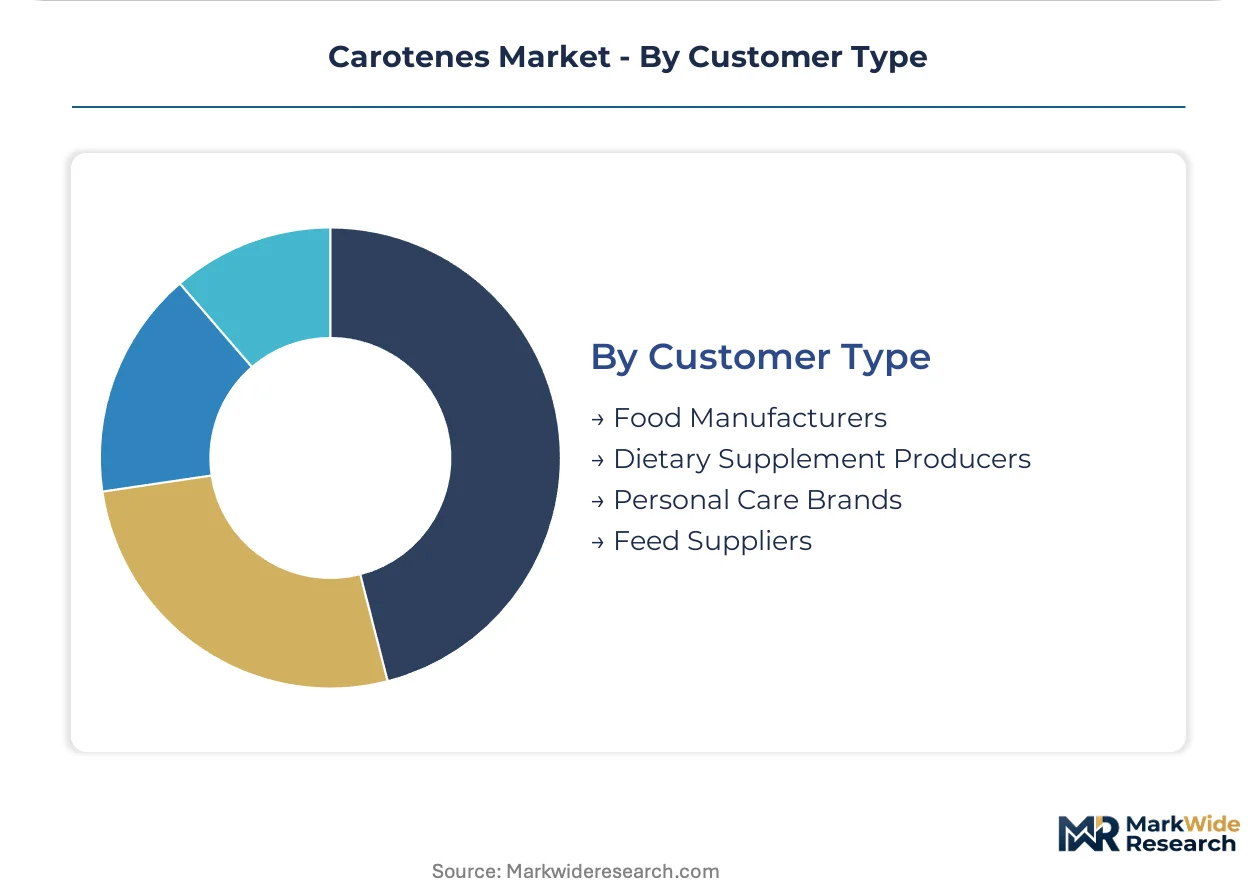
Procurement leverage concentrates among buyers with balance-sheet capacity for volume commitments, squeezing smaller formulators into distributor-mediated channels.
- Dietary Supplement Producers:GRAS notification and EFSA novel food dossier preparation capabilities distinguish tier-one contract manufacturers who command direct supplier relationships. These buyers now require eighteen-to-twenty-four-month supply visibility, transferring inventory carrying costs upstream and concentrating procurement leverage.
- Food Manufacturers:Clean-label certification thresholds in US natural foods channels and EFSA-compliant fortification programs in Germany and France shape sourcing decisions. Dual-jurisdiction compliance investments drain technical regulatory capacity from mid-scale suppliers serving this customer type.
- Personal Care Brands:Cosmetic formulators with stability and aesthetic performance requirements distinct from ingestible applications.
- Feed Suppliers:Cost-optimized procurement with synthetic beta-carotene preference given petrochemical price anchoring.
Dietary supplement producers set specification standards; food manufacturers absorb commoditized volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland chemical corridor anchors European carotene demand through its concentration of fermentation-derived ingredient facilities serving fortified dairy applications.
United States
Food and beverage manufacturers in California and New Jersey are expanding natural colorant sourcing under FDA color additive regulations. The FDA's GRAS notification pathway enables rapid market entry for novel fermentation-derived carotenoids. Chicago-based dietary supplement contract manufacturers command eighteen-to-twenty-four-month supply visibility agreements that transfer inventory risk upstream.
Germany
EFSA novel food approvals are accelerating beta-carotene integration across fortified dairy applications in Bavaria and North Rhine-Westphalia. The country's federal food safety authority enforces strict additive compliance that favors documented fermentation supply chains. Frankfurt's ingredient distribution cluster is absorbing expanded volumes as synthetic alternatives face REACH documentation tightening.
China
GB standards for natural food colorants under SAMR are easing import pathways for fermentation-derived ingredients previously categorized as additives. The Yangtze River Delta hosts expanding closed-photobioreactor facilities for Haematococcus pluvialis cultivation. Zhejiang province's specialty chemical parks are attracting production-linked incentive investments for carotenoid fermentation capacity.
India
BIS food additive standards and FSSAI fortification guidelines are shaping import and domestic production requirements for carotenoid suppliers. The PLI scheme for specialty chemicals is attracting contract fermentation investments in Maharashtra and Gujarat. Marigold cultivation clusters in Karnataka and Tamil Nadu supply lutein extractors serving North American nutraceutical contracts.
Switzerland
Precision fermentation platforms utilizing engineered Yarrowia lipolytica strains are automating carotenoid biosynthesis in Basel's pharmaceutical corridor. Swissmedic's oversight of novel food ingredients aligns with EFSA frameworks while maintaining distinct national dossier requirements. The country's concentrated microbial production facilities create geographic single-point vulnerabilities for European supply security.
Carotenes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived alternatives and clean-label certification positioning. The supplier base organizes around three strategic archetypes: petrochemical-integrated synthetic manufacturers, agricultural-extraction specialists with captive cultivation, and biotechnology platforms utilizing precision fermentation. Competitive moves concentrate on dual-jurisdiction regulatory qualification and long-term offtake contracting that displaces spot-market purchasing.
Within the synthetic production tier, BASF SE anchors petrochemical feedstock integration. Kemin Industries exemplifies agricultural-extraction specialists through its marigold cultivation control. DSM-Firmenich occupies the biotechnology platform position with fermentation-derived carotenoid capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Kemin Industries |
| DSM-Firmenich |
| Allied Biotech Corporation |
| Chr. Hansen Holdings A/S |
| Döhler GmbH |
| Cyanotech Corporation |
| Sensient Technologies Corporation |
| Algatech Ltd. |
| Others |
Value Network & Pricing Analysis
Benzene and acetylene price cycles cascade through petrochemical-derived beta-carotene production into three-tier pricing stratification across fermentation-derived, synthetic, and agricultural-extraction grades. Food manufacturers in Germany and the United States absorb divergent cost structures as REACH documentation burdens tighten on petroleum feedstock classifications while EFSA novel food approvals accelerate fermentation alternatives.
Pricing Analysis
Input-cost pass-through from marigold cultivation volatility in India and Mexico compresses lutein extractor margins while synthetic producers exploit agricultural uncertainty in contract negotiations. Three-tier pricing structure across premium fermentation-derived, standard synthetic, and economy feed-grade levels differentiates on certification burden and supply chain traceability. Pricing pressure stems from REACH substance registration requirements capturing legacy beta-carotene synthesis precursors. Feed suppliers exhibit highest price sensitivity given cost-optimized procurement patterns, while dietary supplement producers absorb premium tiers for GRAS-affirmed positioning.
Supply Chain Analysis
Single-source vulnerability sits with Switzerland and the Netherlands for commercial-scale microbial carotenoid fermentation capacity, creating geographic concentration risk for European supply security. Raw material dependencies span petrochemical feedstocks for synthetic routes, marigold flowers from Karnataka and Tamil Nadu for lutein extraction, and algae biomass from closed-photobioreactor facilities in China and Israel. Supply chain risk centers on climate-sensitive agricultural cultivation cycles that precision fermentation platforms are collapsing into sub-ninety-day production windows. Distribution runs through Frankfurt's ingredient distribution cluster for European reach and Chicago-based contract manufacturers for North American nutraceutical placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carotenes market functions as a geographic-arbitrage play between Switzerland's concentrated fermentation infrastructure and India's emerging contract manufacturing capacity under PLI scheme incentives, with regulatory compliance cost differentials driving portfolio relocation decisions.
For Market Incumbents: Deploy backward integration into captive marigold cultivation to neutralize climate-driven supply volatility threatening lutein extractors. Secure eighteen-to-twenty-four-month offtake agreements with German dairy fortification programs before REACH documentation tightening accelerates synthetic displacement. Precision fermentation platforms utilizing engineered Yarrowia lipolytica strains represent the critical capability gap that agricultural-extraction specialists must neutralize through acquisition or partnership. For New Entrants and Emerging Players: Precision fermentation automation offers the most penetrable wedge for displacing established synthetic and agricultural supply chains. Target beverage suspension format applications where nano-dispersion technologies address unmet functional hydration demand with limited incumbent qualification. Pursue China GB standard alignment under SAMR as the go-to-market angle, leveraging natural food colorant reclassification to bypass additive approval timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology platforms possessing dual-jurisdiction regulatory dossiers already filed with FDA and EFSA. Long-term viability over a five-to-ten-year window favors fermentation-derived carotenoid capabilities that bypass agricultural supply volatility and petroleum feedstock tethering. Monitor ECHA persistent bioaccumulative and toxic assessment updates as the signal to watch for accelerated synthetic displacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marigold Cultivation | Kemin Industries exemplifies how captive agricultural supply neutralizes Indian climate volatility threatening lutein extractors. |
| Precision Fermentation Scale-Up | DSM-Firmenich's Yarrowia lipolytica platforms collapse twelve-month cultivation cycles into sub-ninety-day production windows. |
| Dual-Jurisdiction GRAS Submission | Parallel FDA notification and EFSA novel food dossiers drain technical capacity from mid-scale suppliers seeking multi-territory placement. |
| Long-Term Supply Agreement | German dietary supplement brands now contract eighteen-to-twenty-four-month visibility, transferring inventory carrying costs upstream. |
| China GB Standard Alignment | SAMR natural food colorant reclassification eases import pathways for fermentation-derived ingredients previously categorized as additives. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow reconstruction, and stakeholder interviews — were reconciled to construct supply-demand balances across synthetic, fermentation-derived, and agricultural-extraction routes. Primary interviews with fermentation facility technical directors, dietary supplement contract manufacturer procurement leads, EFSA novel food dossier consultants, and marigold cultivation cluster managers in Karnataka were cross-validated against secondary sources including FDA GRAS notification databases, EFSA novel food catalog listings, REACH substance registration filings, and customs trade data for carotenoid intermediate flows. Bottom-up capacity modeling and top-down consumption estimates were triangulated to anchor volume projections.
Data-stream reconciliation across product type, synthesis method, application segment, and geographic regulatory cluster enabled segmented growth trajectory modeling. The analytical framework incorporated beta-carotene versus specialized eye-health carotenoid demand splits, powder-oil-suspension form factor evolution, and nutraceutical versus food and beverage application penetration rates. CAGRs were derived from fitted growth curves calibrated to historical approval velocity and substitution elasticity parameters. Industry-specific forecast inputs included EFSA novel food approval pipeline velocity and photobioreactor capacity expansion announcements across the Yangtze River Delta.
The model holds under stable regulatory approval timelines and continued clean-label certification threshold elevation; deviation in REACH enforcement intensity or sudden marigold crop failure would shift volume trajectories materially. Forecasts reflect documented assumptions regarding fermentation technology adoption curves and dual-jurisdiction compliance investment capacity among mid-scale suppliers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Global Starch Derivatives Market
Ingredients
Honey Powder Market
Ingredients
MCT Oil Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Soy Protein Concentrate Market
Ingredients
North America Phytosterols Market
Ingredients
South America Clean Ingredients Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Europe Corn Glucose Market
Ingredients
Wheat Germ Oil Market
Ingredients
Pea Fiber Market
Ingredients
Maracuja Oil Market
Ingredients
Home Baking Ingredients Market