
 Fig Ingredient Market | 2026-2036
Fig Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Fig Ingredient Market Foresight
Clean-label extraction and minimal-processing technologies is fragmenting traditional fig ingredient production into multiple quality tiers and regional supply networks. Valley Fig Growers leverages its California orchard base to control upstream paste supply. Olam International Limited competes through diversified sourcing across Mediterranean and Middle Eastern growing regions. Mariani Packing Company anchors its position with established dried fig distribution into North American retail channels.
Fig ingredients comprise processed derivatives from Ficus carica fruit, including whole dried fruit, concentrated paste with 70-75% soluble solids, and spray-dried powder retaining polyphenol content, serving as natural sweeteners, texturizers, and fiber fortifiers across food systems. Dried figs sustain the largest volume position due to extended shelf stability and established bakery procurement patterns, while fig powder captures accelerating interest from health supplement formulators seeking prebiotic fiber claims. Health supplements as an application segment leads growth trajectory as functional food positioning drives R&D investment, though confectionery maintains deeper margin pools through premium chocolate inclusion products.
FDA food additive regulations and USDA organic certification standards govern product claims and import documentation for fig ingredients entering United States commerce, with FSMA traceability rules intensifying supplier verification burdens. The EU Green Deal deforestation regulation and EFSA novel food assessments shape market access for new fig-derived extracts and concentrated formats. Stakeholders must monitor evolving clean-label certification requirements and origin-verification technologies to defend supply chain credibility.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandate is compressing import windows for Mediterranean fig processors and forcing rapid traceability infrastructure deployment across Turkish and Californian orchards.
Growth Catalysts
- Clean-label bakery reformulation:European and North American food manufacturers are substituting refined sugars with fig paste in artisan bread and energy bar applications.
- EFSA novel food pathway:Accelerated approvals for concentrated fig extracts enable functional food positioning in prebiotic fiber supplements.
- Turkey's processing dominance:Aegean region concentration of sun-drying infrastructure and paste production creates procurement efficiencies for multinational ingredient buyers.
Market Restraints
- Input cost volatility:Irrigation water scarcity in California's Central Valley elevates fresh fig procurement premiums for domestic paste producers.
- Supply concentration risk:Turkish processors control an estimated majority of global dried fig export volume, creating single-origin vulnerability.
- Substitution threat:Date paste and raisin concentrate compete directly on sweetness index and fiber claims in clean-label formulations.
Strategic Opportunities
- Underpenetrated Chinese functional food sector:SAMR health food registration reforms create entry pathways for polyphenol-rich fig powder in digestive wellness positioning.
- EU organic certification tailwind:CAP greening incentives subsidize conversion costs for Turkish cooperatives seeking EU organic fig paste premiums.
- Direct-to-manufacturer e-procurement platforms:Digital marketplaces connecting Aegean processors with European SME bakeries bypass traditional broker markups.
Industry Challenges
- FSMA traceability compliance:FDA's enhanced supplier verification requirements demand blockchain-enabled lot tracking from orchard to paste facility.
- Spray-drying capex intensity:Fig powder production requires significant investment in low-temperature drying technology to preserve heat-sensitive bioactives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fig Ingredient Market |
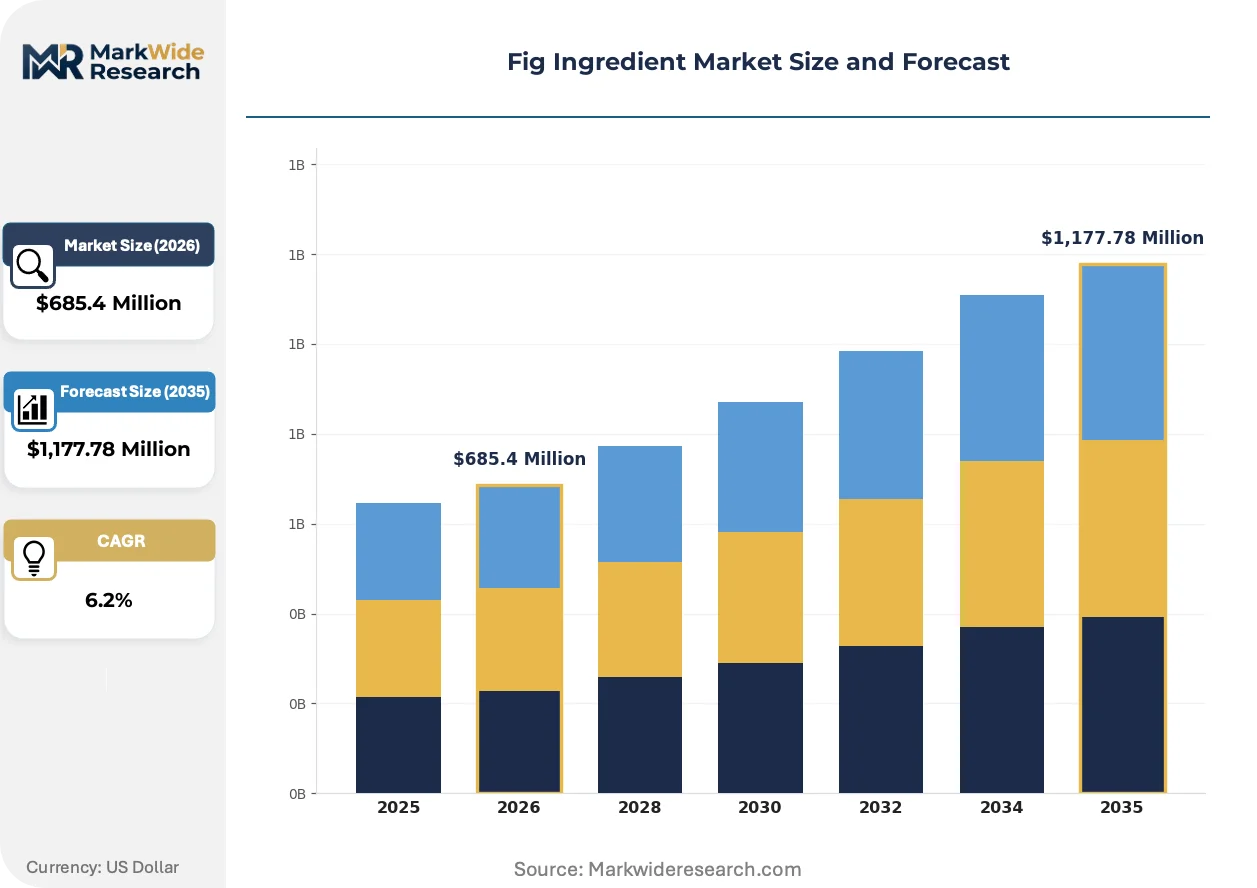
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Figs, Dried Figs, Fig Paste, Fig Powder Application: Beverages, Baking, Confectionery, Health Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Food Manufacturers, Restaurants, Bakeries, Health Food Stores |
| Companies Covered | Valley Fig Growers, Go Figa, Stonewall Kitchen, Rutherford Meyer, Olam International Limited, Archer Daniels Midland Company, Mariani Packing Company, Borges Agricultural & Industrial Nuts, Royal Nut Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fig Ingredient Market Shifts & Advancements
Minimal-processing extraction methods and origin-verification technologies are fragmenting quality tiers and reconfiguring procurement relationships between orchard operators and finished goods manufacturers.
Cold-pressing and infrared drying technologies are collapsing traditional thermal degradation losses in fig paste production. Premium chocolate manufacturers and supplement formulators are accelerating adoption of these methods to preserve anthocyanin content. The technology is collapsing price premiums previously commanded by freeze-dried alternatives.
EU Green Deal deforestation regulation enforcement is tightening due diligence requirements for imported dried fruit. Turkish exporters must now provide geolocation data proving orchard plots exclude recently converted forest land. North American retail chains are responding by demanding third-party verified chain-of-custody documentation.
Long-term contracting is displacing spot purchasing among major bakery ingredient buyers seeking supply security. European industrial bakeries are locking in multi-year fig paste agreements directly with Aegean processing cooperatives. This pattern is most visible in Germany and the Netherlands where clean-label reformulation timelines are most aggressive.
Fig Ingredient Market Segmentation
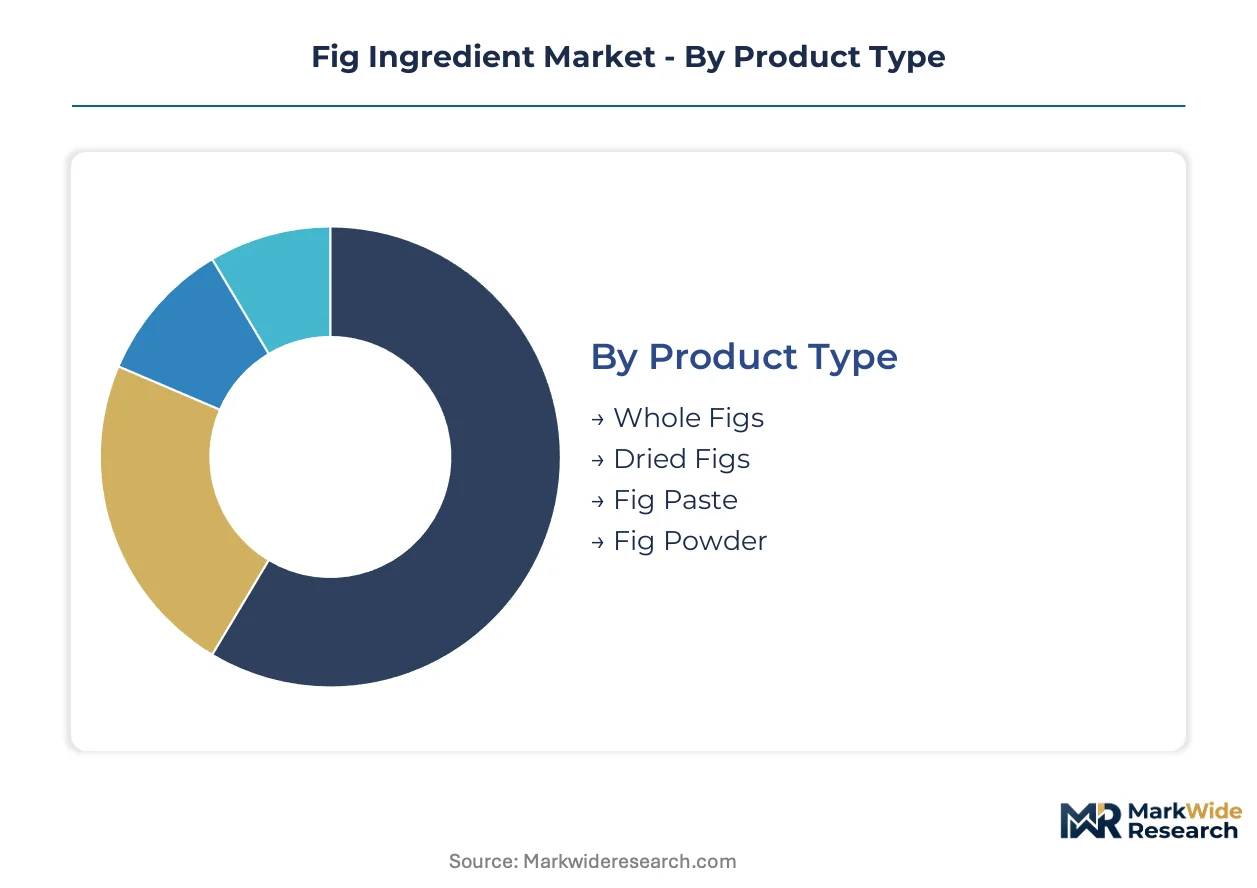
Segmentation in the fig ingredient market reveals how procurement relationships and quality specifications diverge across processing tiers. Understanding these divides helps suppliers align production investments with the diverging technical requirements of industrial buyers versus artisan end-users.
Product Type:
After-sales service intensity varies sharply across product types, with powder and paste buyers demanding formulation support that whole dried fig purchasers rarely require.
- Dried Figs:Sun-dried or mechanically dehydrated whole fruit with 14-20% moisture content maintains shelf stability through established pasteurization protocols. German and Dutch industrial bakeries anchor procurement volumes for clean-label energy bar applications, though California's drought-driven irrigation cost spikes compress margin pools for domestic suppliers.
- Fig Paste:Concentrated puree with 70-75% soluble solids serves as direct sugar replacement in artisan bread formulations. European manufacturers are locking in multi-year supply agreements with Aegean processing cooperatives to secure deforestation-compliant origin documentation under EU Green Deal enforcement.
- Whole Figs:Fresh or minimally processed fruit for premium retail and foodservice channels carries perishability constraints that limit distribution radius.
- Fig Powder:Spray-dried particulate retaining polyphenol content for supplement fortification demands capital-intensive low-temperature drying infrastructure.
Dried figs hold the largest share; momentum sits with fig powder as prebiotic fiber claims accelerate R&D investment.
Application:
Cost tier stratification separates commodity bakery procurement from premium chocolate inclusion contracts that command threefold price multiples.
- Baking:Industrial bread and energy bar manufacturers substitute refined sugars with fig paste to achieve clean-label positioning. Long-term contracting is displacing spot purchasing among major European buyers seeking supply security against Turkish origin concentration risk.
- Health Supplements:Prebiotic fiber and digestive wellness positioning drives accelerating interest from formulators seeking heat-stable polyphenol delivery. SAMR health food registration reforms in China create entry pathways for polyphenol-rich fig powder.
- Confectionery:Premium chocolate inclusion products maintain deeper margin pools through artisan positioning and limited-batch scarcity marketing.
- Beverages:Natural sweetener applications in functional drinks remain underdeveloped relative to competing date and raisin concentrates.
Baking commands volume leadership; health supplements are expanding most quickly as functional food positioning reshapes procurement priorities.
Distribution Channel:
Volume concentration favors wholesaler relationships for industrial-scale paste procurement, while specialty stores capture premium dried fruit markups.
- Wholesalers:Bulk ingredient distributors connect Aegean processing cooperatives with European and North American food manufacturers. Direct-to-manufacturer e-procurement platforms are fragmenting traditional broker relationships by connecting Turkish processors with SME bakeries.
- Specialty Stores:Premium retail channels for organic and origin-verified dried figs command price premiums through third-party certification storytelling.
- Supermarkets:Mass retail dried fig placement competes on shelf-stable convenience against raisin and date alternatives.
- Online Retail:Direct-to-consumer fig powder sales for home baking and wellness applications remain nascent relative to established supplement ingredient channels.
Wholesalers dominate industrial volume; specialty stores are gaining share fastest as origin-verification technologies enable premium differentiation.
End User:
Customer type determines specification stringency, with food manufacturers demanding full FSMA traceability documentation that restaurant buyers rarely require.
- Food Manufacturers:Industrial-scale bakery and confectionery operations drive standardized paste procurement with lot-level blockchain tracking. FDA's enhanced supplier verification requirements intensify compliance burdens for Turkish exporters seeking US market access.
- Bakeries:Artisan and industrial bread producers represent the core demand base for clean-label reformulation with fig-derived sweeteners.
- Restaurants:Foodservice channels for whole fig and paste applications prioritize cost efficiency over origin certification.
- Health Food Stores:Retail positioning for organic and functional fig products depends on EFSA novel food pathway approvals for concentrated extract claims.
Food manufacturers anchor procurement volume; health food stores are climbing the fastest as polyphenol positioning penetrates consumer wellness categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish Aegean processors ship dried figs and concentrated paste to German and Dutch industrial bakeries under long-term supply agreements. California's Central Valley orchards supply North American clean-label manufacturers facing drought-driven irrigation cost premiums.
Turkey
Industrial bakeries in Germany and the Netherlands drive Aegean region paste procurement for clean-label energy bar reformulation. The EU Green Deal deforestation regulation forces Turkish exporters to provide geolocation data proving orchard plots exclude converted forest land. Izmir and Aydın provinces concentrate sun-drying infrastructure and cooperative processing facilities serving multinational ingredient buyers.
United States
California's drought conditions elevate fresh fig procurement premiums for domestic paste producers competing with Turkish imports. FDA FSMA traceability rules intensify supplier verification burdens for orchard-to-facility blockchain tracking. The Central Valley's Madera and Fresno counties anchor dried fig processing and paste production for North American bakery supply chains.
Germany
Industrial bread manufacturers substitute refined sugars with fig paste to meet clean-label positioning requirements in retail and foodservice channels. EFSA novel food assessments govern market access for concentrated fig extracts in functional food applications. The Baden-Württemberg and Bavaria regions host formulation R&D centers driving procurement specification tightening.
China
SAMR health food registration reforms create entry pathways for polyphenol-rich fig powder in digestive wellness positioning. The country's national food safety regulator enforces dual carbon goals compliance for imported ingredient processing facilities. Yangtze River Delta functional food manufacturers trial fig-derived prebiotic fiber formulations for domestic supplement brands.
Netherlands
European distribution hubs in Rotterdam and Amsterdam consolidate Aegean paste shipments for redistribution to SME bakeries across the continent. EU organic certification tailwinds subsidize conversion costs for Turkish cooperatives seeking premium positioning. Dutch ingredient traders deploy digital procurement platforms connecting Aegean processors directly with bakery customers.
Fig Ingredient Market Competitive Landscape
On the supply side, the industry is bifurcated between orchard-controlled upstream operators and diversified commodity traders. Turkish Aegean cooperatives and California growers anchor the upstream tier with captive raw material access. Mid-scale paste specialists and spray-drying technology operators occupy the processing tier. Competitive moves concentrate on multi-year supply contracting and traceability infrastructure deployment to satisfy EU Green Deal and FDA compliance requirements.
Among orchard-based operators, Valley Fig Growers exemplifies the California-controlled supply model with in-house orchard assets, while Mariani Packing Company represents the established dried fruit distribution archetype into North American retail channels. Olam International Limited sits within the diversified sourcing tier with Mediterranean and Middle Eastern procurement networks spanning multiple growing regions. These three archetypes illustrate the structural tension between origin-controlled and geographically diversified supply strategies.
| Leading Market Players |
|---|
| Valley Fig Growers |
| Go Figa |
| Stonewall Kitchen |
| Rutherford Meyer |
| Olam International Limited |
| Archer Daniels Midland Company |
| Mariani Packing Company |
| Borges Agricultural & Industrial Nuts |
| Royal Nut Company |
| Others |
Supply & Pricing Matrix
Undercapacity in California's Central Valley drying infrastructure is elevating procurement premiums for domestic paste producers and compressing their pricing flexibility against Turkish imports. Aegean processors exploit this utilization gap to enforce long-term contract premiums while California operators absorb drought-driven irrigation cost spikes.
Pricing Analysis
Technology-generation pricing gaps separate cold-pressed infrared-dried premium paste from conventional thermal-degraded standard grades and commodity sun-dried economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects polyphenol retention rates and EFSA novel food pathway compliance status. Cost compression in standard-grade paste is intensifying because date paste substitutes compete on equivalent sweetness indices. Industrial bakeries exhibit highest price sensitivity due to volume procurement scale, while supplement formulators accept premium multiples for heat-stable bioactive retention.
Supply Chain Analysis
Upstream fresh fig feedstock draws from Turkey's Aegean region, California's Central Valley, and select Mediterranean cooperative networks. Sun-drying infrastructure, low-temperature spray-drying equipment, and blockchain-enabled traceability systems constitute critical input dependencies. Single-source vulnerability concentrates in Turkish export dominance for dried fig volume. Distribution runs through Rotterdam-Amsterdam hub consolidation for European SME bakery redistribution and direct-to-manufacturer e-procurement platform fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label extraction technology disruption and EU Green Deal deforestation enforcement are compressing traditional procurement windows and rewarding traceability infrastructure investment.
For Market Incumbents: Pre-empt substitution threats from date and raisin concentrate competitors by locking multi-year supply agreements with Aegean cooperatives before CAP greening subsidies expand organic conversion. Defend margin position through backward integration into captive orchard assets in California's Madera County to offset irrigation cost volatility. Accelerate blockchain lot-tracking deployment to satisfy FDA FSMA verification requirements ahead of compliance deadlines. For New Entrants and Emerging Players: Build out spray-drying capacity serving Chinese functional food manufacturers seeking SAMR-registered polyphenol powder for digestive wellness positioning. Underpenetrated white-space sits with Yangtze River Delta supplement brands lacking established fig-derived prebiotic suppliers. Target German industrial bakeries through digital procurement platforms bypassing traditional broker markups. For Investors and Strategic Acquirers: Capital is best deployed toward orchard-controlled mid-tier processors with deforestation-compliant geolocation documentation and existing EU organic certification. Long-term viability across the analysis window hinges on traceability infrastructure ownership rather than commodity trading relationships. The signal to watch is FDA enforcement intensity against Turkish exporters lacking blockchain-enabled supplier verification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive supply of California figs insulates against drought-driven input cost spikes and Turkish import competition. |
| Blockchain Traceability Deployment | EU Green Deal geolocation requirements and FDA FSMA rules demand lot-level orchard-to-facility tracking infrastructure. |
| EFSA Novel Food Pathway Investment | Accelerated approvals for concentrated fig extracts enable premium functional food positioning in prebiotic supplements. |
| Direct-to-Manufacturer E-Procurement Platform | Digital marketplaces connecting Aegean processors with European SME bakeries fragment traditional broker relationships. |
| Low-Temperature Spray-Drying Capacity Buildout | Capital-intensive infrastructure preserves heat-sensitive anthocyanins for premium chocolate and supplement applications. |
Research Methodology
A standing panel of fig paste procurement managers at European industrial bakeries, Aegean cooperative processing directors, California orchard operations managers, and FDA regulatory compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Green Deal implementation documentation, USDA organic certification databases, Turkish export customs records, and EFSA novel food assessment filings. Bottom-up volume modeling triangulated against top-down ingredient demand projections from food manufacturer R&D spending patterns.
Scenario-bracketing framed conservative, baseline, and expansion cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled included product type tier, application end-use, distribution channel structure, and geographic regulatory cluster. CAGRs derived from trend extrapolation of clean-label reformulation intensity, functional food R&D allocation shifts, and traceability compliance cost absorption rates. Industry-specific forecast inputs incorporated irrigation water pricing trajectories in California's Central Valley and CAP subsidy conversion timelines for Turkish organic certification.
Stress conditions across Aegean drought frequency, California groundwater regulation tightening, and EU deforestation enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding substitution elasticity between fig paste and competing natural sweeteners. Cross-checking against SAMR health food registration approval velocity and EFSA novel food backlog clearance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sunflower Lecithin Market
Ingredients
Textured Wheat Protein Market
Ingredients
Pea Flour Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Corn Steep Liquor Market
Ingredients
Ice Cream Bases Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Corn Gluten Meal Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Biotech Ingredients Market
Ingredients
Beverage Ingredients Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Textured Milk Protein Market