
 Mediterranean Women’s Cycle Support Ingredient Systems Market | 2026-2036
Mediterranean Women’s Cycle Support Ingredient Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Women’s Cycle Support Ingredient Systems Market Insights
Specialty pharmacy and practitioner channels across Southern Europe is rewriting how cycle support formulations reach end consumers. O Positiv leverages Mediterranean botanical sourcing networks to secure consistent chasteberry and dong quai supply chains. HUM Nutrition anchors its position through subscription-based distribution that sustains recurring revenue from perimenopausal women in France and Spain. Ritual competes on transparent supply chain disclosure, while Thorne specializes in clinician-validated dosing protocols that dominate practitioner recommendations across the region.
Mediterranean Women's Cycle Support Ingredient Systems encompass standardized botanical extracts, bioavailable mineral chelates, and targeted probiotic strains formulated to address hormonal fluctuations, menstrual discomfort, and associated physiological symptoms in women, typically manufactured through low-temperature drying, cold-press extraction, or microencapsulation to preserve active compound integrity. Botanicals lead ingredient type demand due to deep cultural acceptance of herbal remedies across Southern European consumer bases, while gummies and liquids within formulation format are expanding fastest among adolescents and wellness enthusiasts who reject traditional pill formats. Perimenopausal women and athletes within consumer segment represent concentrated margin pools, as these groups demonstrate higher willingness to pay for clinically positioned premium positioning.
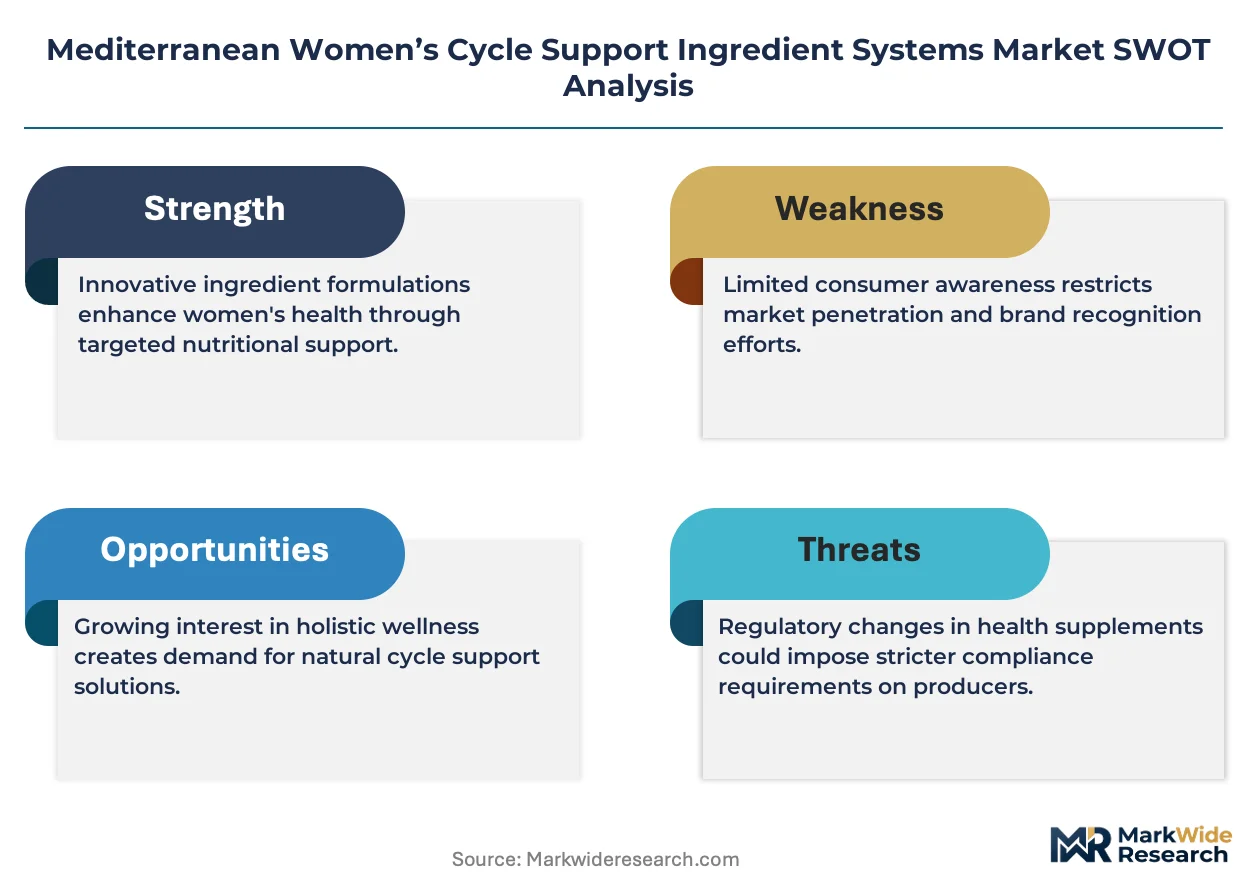
EFSA novel food safety assessments and EU Nutrition and Health Claims Regulation enforcement shape permissible marketing language and substantiation requirements across member states, while national regulators in Italy and Spain impose additional pharmacovigilance reporting on hormone-active botanicals that limits formulation freedom. Stakeholders must monitor evolving EFSA opinions on botanical safety and adapt substantiation portfolios before health claim rejections force portfolio restructuring.
Market Dynamics
EFSA novel food safety assessments are compressing formulation freedom across the Mediterranean, forcing suppliers to rebuild substantiation portfolios before health claim rejections trigger portfolio restructuring. This regulatory pressure concentrates competitive advantage among firms with preemptive clinical investment.
Growth Catalysts
- EFSA Harmonization:Centralized novel food approvals under EFSA are standardizing cross-border product launches, reducing national regulatory fragmentation that previously trapped formulations in single markets.
- Specialty Pharmacy Expansion:Practitioner-validated distribution channels across Southern Europe are professionalizing consumer access, embedding cycle support into clinical wellness protocols.
- Bioavailable Chelates:Mineral absorption technologies are displacing conventional oxide forms, commanding premium positioning in perimenopausal segments.
Market Restraints
- Chasteberry Supply Concentration:Mediterranean botanical sourcing networks cluster in specific Italian and Spanish growing regions, exposing formulations to climatic volatility and harvest inconsistency.
- Pharmacovigilance Burden:Italy's national regulator imposes additional hormone-active botanical reporting requirements that extend product development timelines and elevate compliance costs.
- Substitution by Synthetic Hormones:Prescription hormonal therapies retain reimbursement advantages in France and Spain, constraining botanical uptake among cost-sensitive demographics.
Strategic Opportunities
- Greek Market Underpenetration:Athens and Thessaloniki direct-to-consumer platforms remain underserved relative to Italian and Spanish saturation, offering first-mover positioning for subscription models.
- Microencapsulation Convergence:Cold-press extraction combined with probiotic strain stabilization is enabling shelf-stable liquid formats that capture adolescent rejection of pill formats.
- EU Green Deal Incentives:Sustainable sourcing certifications are unlocking preferential retail placement in Lombardy and Emilia-Romagna organic channels.
Industry Challenges
- Clinical Validation Talent Scarcity:Women's health-specific biostatisticians and EFSA dossier specialists command premium compensation in Bologna and Milan research clusters, constraining mid-cap expansion.
- Legacy System Integration:Practitioner channel distributors face friction embedding subscription platforms into established pharmacy inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Women’s Cycle Support Ingredient Systems Market |
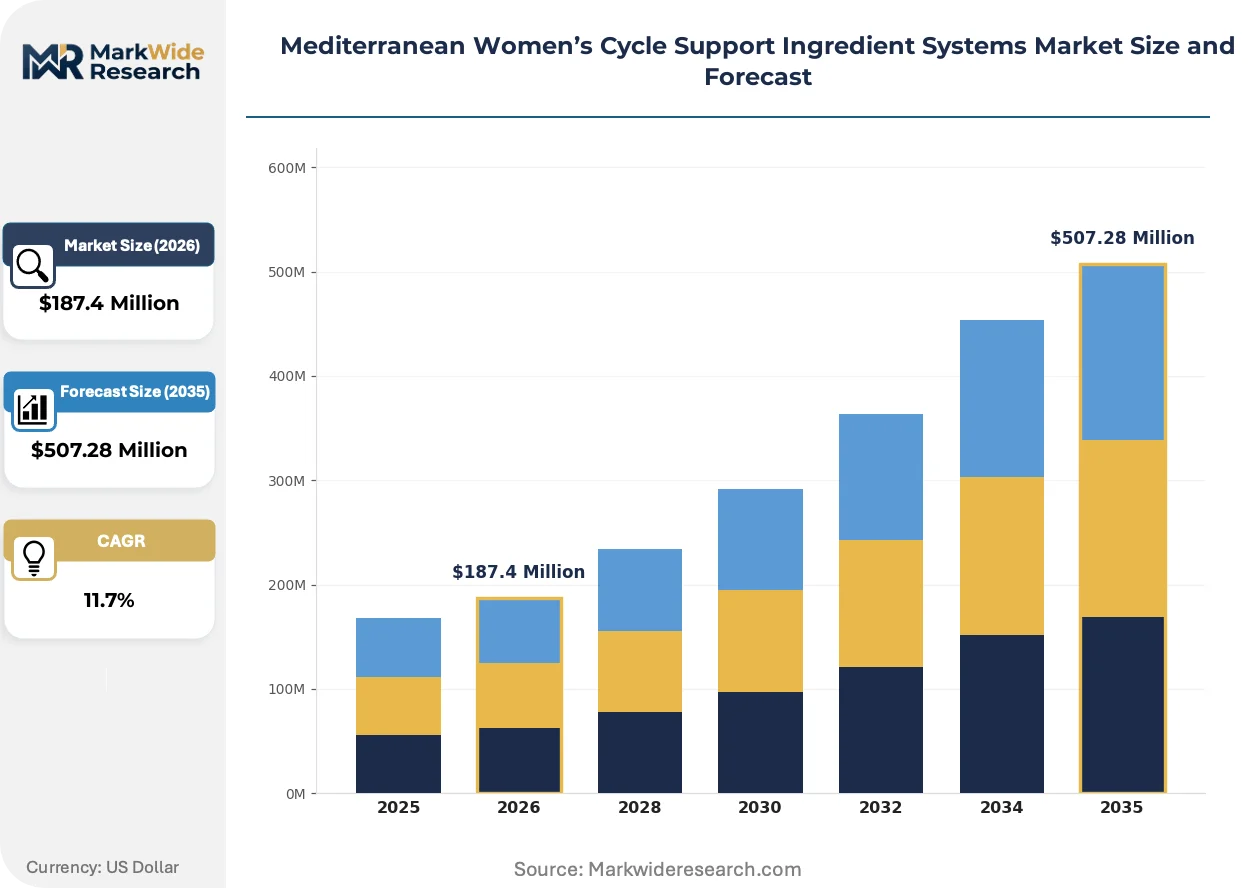
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Botanicals, Vitamins, Minerals, Enzymes, Probiotics, Amino Acids Formulation Format: Powders, Capsules, Tablets, Liquids, Softgels, Gummies Physiological Focus: Hormonal Balance, Menstrual Comfort, Fertility Enhancement, Mood Regulation, Energy Support, Digestive Health Consumer Segment: Adolescents, Pregnant Females, Lactating Mothers, Perimenopausal Women, Athletes, Wellness Enthusiasts |
| Companies Covered | O Positiv, HUM Nutrition, OLLY, Elix Healing, Thorne, MegaFood, Boiron, Ritual, Flo Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Women’s Cycle Support Ingredient Systems Market Trends and Innovations
Digital health integration is virtualizing how cycle support formulations reach end consumers, collapsing traditional channel hierarchies while elevating transparency expectations. This structural shift rewards firms with direct data relationships and punishes opaque supply chains.
Cold-press extraction technology is virtualizing active compound preservation in chasteberry and dong quai processing. Premium positioned suppliers across Lombardy are adopting these systems to replace heat-degraded conventional extracts. The technology is virtualizing quality differentiation, compressing margins for legacy oven-dried botanical processors.
EFSA's evolving botanical safety opinions are tightening permissible marketing language across EU member states. Formulators must now pre-substantiate hormone-active claims before national launch, eliminating post-market positioning adjustments. Italian and Spanish regulatory affairs teams are absorbing the heaviest compliance burden as EFSA scrutiny intensifies.
Subscription-based replenishment is displacing pharmacy impulse purchasing among perimenopausal women in France and Spain. Direct-to-consumer platforms capture recurring revenue while specialty retailers lose foot traffic for cycle support categories. This behavioral pivot concentrates in urban clusters where digital health literacy intersects with wellness expenditure capacity.
Mediterranean Women’s Cycle Support Ingredient Systems Market Segmentation
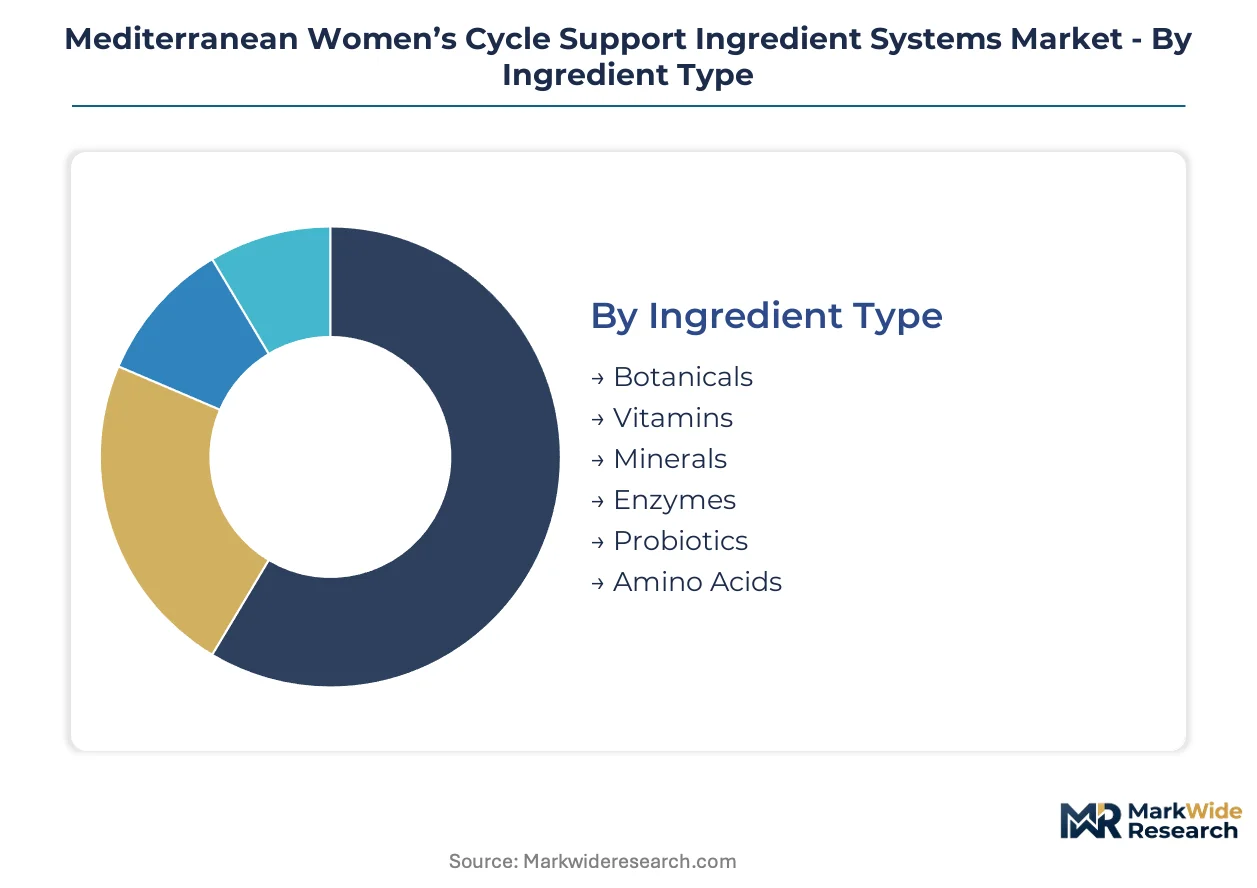
Ingredient type diversity across Mediterranean Women's Cycle Support Ingredient Systems creates distinct margin architectures. Formulation formats and physiological focus areas further stratify competitive positioning across Southern European distribution channels.
Ingredient Type:
Cost tier differentiation separates commodity mineral inputs from clinically positioned botanical extracts and precision probiotics.
- Botanicals:Standardized chasteberry, dong quai, and vitex extracts dominate premium positioning. Deep cultural acceptance across Italian and Spanish consumer bases sustains pricing power despite EFSA novel food substantiation burdens.
- Vitamins:B-complex and vitamin D3 formulations target luteal phase symptom management. Demand concentrates in France's pharmacy channel where practitioner recommendations drive prescription-adjacent purchasing.
- Minerals:Bioavailable magnesium glycinate and iron bisglycinate displace oxide forms. Perimenopausal women in Lombardy and Emilia-Romagna demonstrate highest willingness to pay for chelated absorption technologies.
- Enzymes:Bromelain and serrapeptase variants address inflammatory menstrual symptoms. Limited clinical dossier investment constrains EFSA health claim eligibility.
- Probiotics:Lactobacillus and Bifidobacterium strains target gut-hormone axis modulation. Microencapsulation advances enable shelf-stable liquid formats capturing adolescent rejection of pill formats.
- Amino Acids:L-theanine and N-acetylcysteine support cortisol regulation and antioxidant status. Niche positioning limits volume scale outside specialty sports nutrition channels.
Botanicals hold installed capacity. Probiotics are rotating up the share rankings.
Formulation Format:
Application-driven format selection reflects age-cohort swallowability preferences and compliance psychology across Southern Europe.
- Powders:Bulk active delivery enables dose customization and stackable regimens. Athletes and biohackers in Barcelona and Madrid fitness clusters drive concentrated demand for unflavored base formulations.
- Capsules:Two-piece gelatin and vegetable cellulose shells remain the compliance default. Italy's pharmacy channel maintains capsule preference among perimenopausal women seeking clinical credibility signals.
- Tablets:Compressed mineral and vitamin matrices offer cost-efficient manufacturing. Price-sensitive demographics in Greece sustain tablet volume despite slower disintegration profiles.
- Liquids:Cold-press extracted botanical tinctures preserve volatile compound integrity. Direct-to-consumer platforms in France report fastest subscription attachment rates for liquid cycle support.
- Softgels:Lipid-soluble vitamin and omega delivery systems target hormone synthesis support. Limited differentiation versus capsules constrains premium positioning.
- Gummies:Pectin-based matrices with natural flavor masking capture adolescent and young adult rejection of pharmaceutical aesthetics. Gummies are climbing the fastest among format innovations.
Capsules hold installed capacity. Gummies are rotating up the share rankings.
Physiological Focus:
Customer type severity and symptom specificity determine formulation complexity and pricing architecture across Mediterranean markets.
- Hormonal Balance:Chasteberry-centered protocols target progesterone-estrogen modulation. Italian regulatory scrutiny on hormone-active botanicals extends development timelines for this positioning.
- Menstrual Comfort:Cramp and bloating relief formulations combine antispasmodic botanicals with magnesium. Spain's specialty pharmacy channel embeds these into clinical wellness protocols.
- Fertility Enhancement:Inositol, CoQ10, and folate complexes support ovulatory function. Premium pricing concentrates in Milan and Bologna where research university proximity elevates clinical credibility expectations.
- Mood Regulation:Saffron extract and 5-HTP variants address luteal phase affective symptoms. EFSA health claim restrictions limit permissible marketing language.
- Energy Support:Iron and B-vitamin complexes target menstrual fatigue. Athletes in French and Spanish endurance sports clusters demonstrate concentrated demand.
- Digestive Health:Probiotic and digestive enzyme combinations address cycle-related gastrointestinal disturbance. Microbiome positioning gains traction among wellness enthusiasts.
Hormonal Balance holds installed capacity. Fertility Enhancement is rotating up the share rankings.
Consumer Segment:
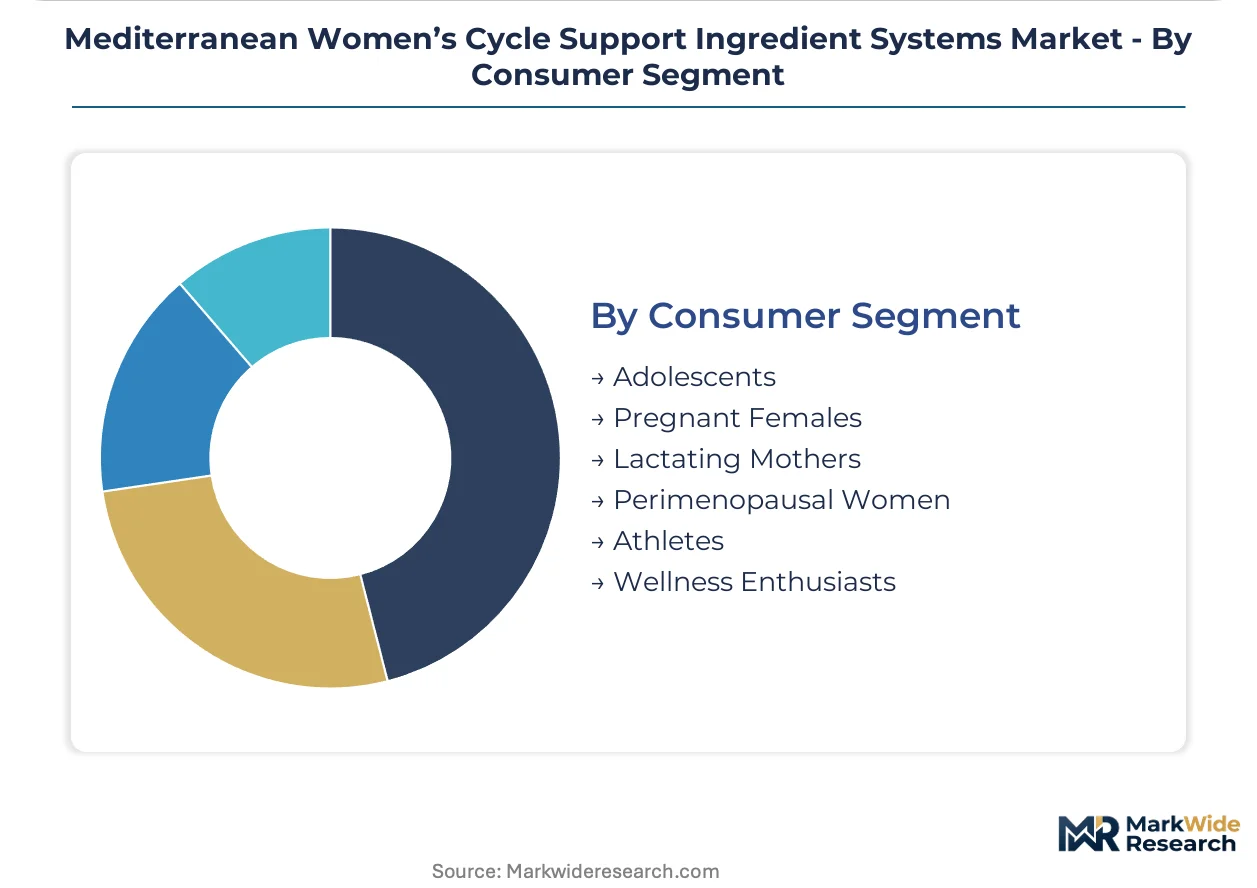
Geography and life-stage intersect to create distinct margin pools across Southern European urban clusters.
- Adolescents:Gummy and liquid formats with gentle botanical dosing address menarche transition. Athens and Thessaloniki direct-to-consumer platforms remain underserved relative to Italian saturation.
- Pregnant Females:Prenatal-adjacent formulations require stringent teratogenic safety profiles. Prescription channel dominance limits botanical uptake.
- Lactating Mothers:Galactagogue and nutritional repletion positioning targets postpartum recovery. Limited dedicated cycle support marketing distinguishes this segment.
- Perimenopausal Women:Hormonal fluctuation management commands highest willingness to pay across all segments. Subscription models in France and Spain capture recurring revenue from this cohort.
- Athletes:Menstrual cycle-aware training protocols drive demand for iron, magnesium, and adaptogenic complexes. Sports nutrition crossover creates channel complexity.
- Wellness Enthusiasts:Biohacking and optimization psychology sustains premium positioning for novel delivery technologies. Digital health literacy correlates with subscription attachment.
Perimenopausal Women hold installed capacity. Adolescents are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food safety assessments anchor regulatory harmonization across Southern Europe, compressing formulation freedom while standardizing cross-border product launches. National pharmacovigilance requirements in Italy and Spain impose additional compliance burdens that extend development timelines. Demand concentrates in research university clusters near Bologna and Milan, where women's health startups access clinical validation infrastructure.
Italy
Italy's Lombardy and Emilia-Romagna regions host the densest concentration of cycle support formulation development. The Ministry of Health imposes hormone-active botanical reporting requirements that elevate compliance costs beyond EFSA baselines. Bologna's research universities supply clinical validation talent to women's health startups clustering in the metropolitan area.
Spain
Spain's specialty pharmacy channel professionalizes consumer access through practitioner-validated distribution networks. The Spanish Agency for Medicines and Health Products enforces pharmacovigilance protocols on hormone-active ingredients that parallel Italian stringency. Barcelona and Madrid fitness clusters drive concentrated demand for powder-format cycle support among athletes.
France
France's pharmacy channel retains prescription-adjacent purchasing patterns for menstrual comfort formulations. ANSM oversight intersects with EU Nutrition and Health Claims Regulation enforcement to limit permissible marketing language. Subscription models in urban centers capture recurring revenue from perimenopausal women seeking convenience.
Greece
Greece remains underpenetrated relative to Italian and Spanish market saturation, offering first-mover positioning for direct-to-consumer platforms. Athens and Thessaloniki lack the research university density of Northern Italian clusters, constraining local clinical validation capacity. National organic certification programs align with EU Green Deal incentives for sustainable sourcing.
Mediterranean Women’s Cycle Support Ingredient Systems Market Competitive Landscape
Subscription-based specialists and transparent supply chain disruptors split the market between recurring revenue capture and credibility positioning. The competitive structure favors firms with preemptive clinical investment that withstand EFSA substantiation compression. Three archetypes dominate: direct-to-consumer subscription platforms, practitioner-channel validators, and transparent sourcing specialists. Geographic expansion into underpenetrated Greek markets and microencapsulation technology licensing represent the dominant competitive moves.
Within the subscription-platform tier, HUM Nutrition and O Positiv exemplify recurring revenue models that sustain customer lifetime value through automated replenishment. Ritual occupies a position emphasizing supply chain transparency disclosure that resonates with wellness enthusiasts seeking ingredient provenance verification. Thorne anchors the practitioner-validation archetype through clinician-dosing protocols that dominate pharmacy recommendations across Southern Europe. These three firms represent distinct strategic responses to EFSA harmonization pressure.
| Leading Market Players |
|---|
| O Positiv |
| HUM Nutrition |
| OLLY |
| Elix Healing |
| Thorne |
| MegaFood |
| Boiron |
| Ritual |
| Flo Health |
| Others |
Pricing and Supply Chain Analysis
Barcelona-Valencia freight corridors absorb elevated per-unit logistics costs for chasteberry extracts originating in Spanish growing regions, compressing margins for standard-grade formulations while amplifying price premiums for cold-pressed botanicals certified under EU organic protocols.
Pricing Analysis
The customization-premium spread separates practitioner-validated protocols from mass-market gummy formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA substantiation depth and bioavailable chelate inclusion. Cost compression in economy tablet tiers intensifies because Greek price-sensitive demographics resist subscription attachment. Athletes in French endurance sports clusters demonstrate least price sensitivity; adolescents in Athens direct-to-consumer channels exhibit highest.
Supply Chain Analysis
Tariff exposure between Italian processing facilities and French distribution hubs dominates supply chain risk architecture for hormone-active botanicals. Raw material sourcing draws from concentrated chasteberry cultivation in Abruzzo and Sicily, dong quai networks in Emilia-Romagna, and probiotic strain banks in Lombardy. Single-source vulnerability concentrates in Italian cold-press extraction equipment providers. Distribution runs through specialty pharmacy networks in Spain and France, with direct-to-consumer platforms gaining share in urban Italian clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as subscription infrastructure and EFSA dossier databases achieve interoperability across Southern European regulatory clusters.
For Market Incumbents: Entrench practitioner channel relationships through clinician-validated dosing protocols that withstand ANSM and Agenas scrutiny. Secure captive supply of Abruzzo chasteberry harvests through backward integration into Italian growing cooperatives. Defend against synthetic hormone substitution in French reimbursement channels by embedding cycle support into hospital wellness protocols.
For New Entrants and Emerging Players: Establish a beachhead in Athens and Thessaloniki direct-to-consumer platforms where subscription penetration lags Italian saturation by substantial margin. Target adolescent gummy formats with microencapsulated probiotic liquids that capture rejection of pharmaceutical aesthetics. Leverage EU Green Deal certification incentives to unlock preferential placement in Lombardy organic retail channels.
For Investors and Strategic Acquirers: EFSA dossier specialists with preemptive clinical investment represent the highest-conviction acquisition archetype for long-term viability. Platform-enabled subscription operators with recurring revenue infrastructure in France and Spain warrant premium multiples. Monitor EFSA botanical safety opinion velocity as inflection indicator for portfolio restructuring risk.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Preemptive substantiation compresses competitor formulation freedom before health claim rejections trigger restructuring. |
| Backward Integration into Italian Botanical Cultivation | Captive supply of Abruzzo chasteberry harvests insulates against climatic volatility and harvest inconsistency. |
| Microencapsulation Technology Licensing | Shelf-stable liquid formats capture adolescent rejection of pill formats while enabling probiotic strain stabilization. |
| Specialty Pharmacy Channel Expansion | Practitioner-validated distribution embeds cycle support into clinical wellness protocols across Spain and France. |
| Direct-to-Consumer Platform Launch in Greece | Athens and Thessaloniki underpenetration offers first-mover positioning for subscription-based replenishment models. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regulatory affairs specialists at EFSA-focused consultancies, pharmacy category managers in Milan and Barcelona, women's health startup founders in Bologna research clusters, and botanical extraction facility operators in Abruzzo. Secondary validation drew from EFSA novel food opinions, EU Nutrition and Health Claims Regulation enforcement records, Italian Ministry of Health pharmacovigilance reports, and Spanish Agency for Medicines and Health Products guidance documents. Bottom-up volume estimates triangulated against top-down category spending analysis.
Calibration against historical EFSA approval timelines and subscription platform revenue disclosures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include ingredient type stratification, formulation format preference by age cohort, physiological focus area positioning, and consumer segment willingness-to-pay tiers. CAGRs were derived from growth rate convergence analysis applied to perimenopausal population projections and digital health platform penetration curves.
Stress conditions across EFSA opinion delays, chasteberry harvest volatility, and synthetic hormone reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization velocity and subscription adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Salad Oil Market
Ingredients
Sodium Caseinate Market
Ingredients
Horny Goat Weed Extract Market
Ingredients
North America Milk Protein Market
Ingredients
Bakery Ingredients Market
Ingredients
Psyllium Products Market
Ingredients
Mung Bean Protein Market
Ingredients
Cocoa Processing Market
Ingredients
Pea Peptones Market
Ingredients
North America Agar Market
Ingredients
Carob Powder Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Soy Hydrolysates Market
Ingredients
Caramel Malt Market
Ingredients
Vegan Ingredients Market
Ingredients
Ben Oil Market