
 Food Supplement Ingredients Market | 2026-2036
Food Supplement Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Food Supplement Ingredients Market Analysis
Asset-light contract manufacturing and white-label financing is fragmenting competitive barriers in food supplement ingredients, allowing mid-tier brands to source clinically validated actives without captive fermentation capacity. ADM leverages its North American oilseed processing network to backward integrate into plant-based protein isolates. BASF SE anchors European synthetic vitamin production through its Ludwigshafen complex. dsm-firmenich differentiates via its precision fermentation platform for omega-3 and human milk oligosaccharides.
Food supplement ingredients comprise bioactive compounds, isolated nutrients, and botanical extracts formulated for oral delivery to support physiological functions beyond basic nutrition; manufacturers employ spray drying, microencapsulation, and solvent extraction to preserve stability and bioavailability through shelf life. Vitamins retain the largest value share due to fortification mandates and established clinical validation, while fermented ingredients represent the fastest-expanding source category as precision biotechnology cuts production costs for niche actives. Powder formulations dominate bulk ingredient trade, though capsule and liquid finished forms command higher margin pools in direct-to-consumer channels.
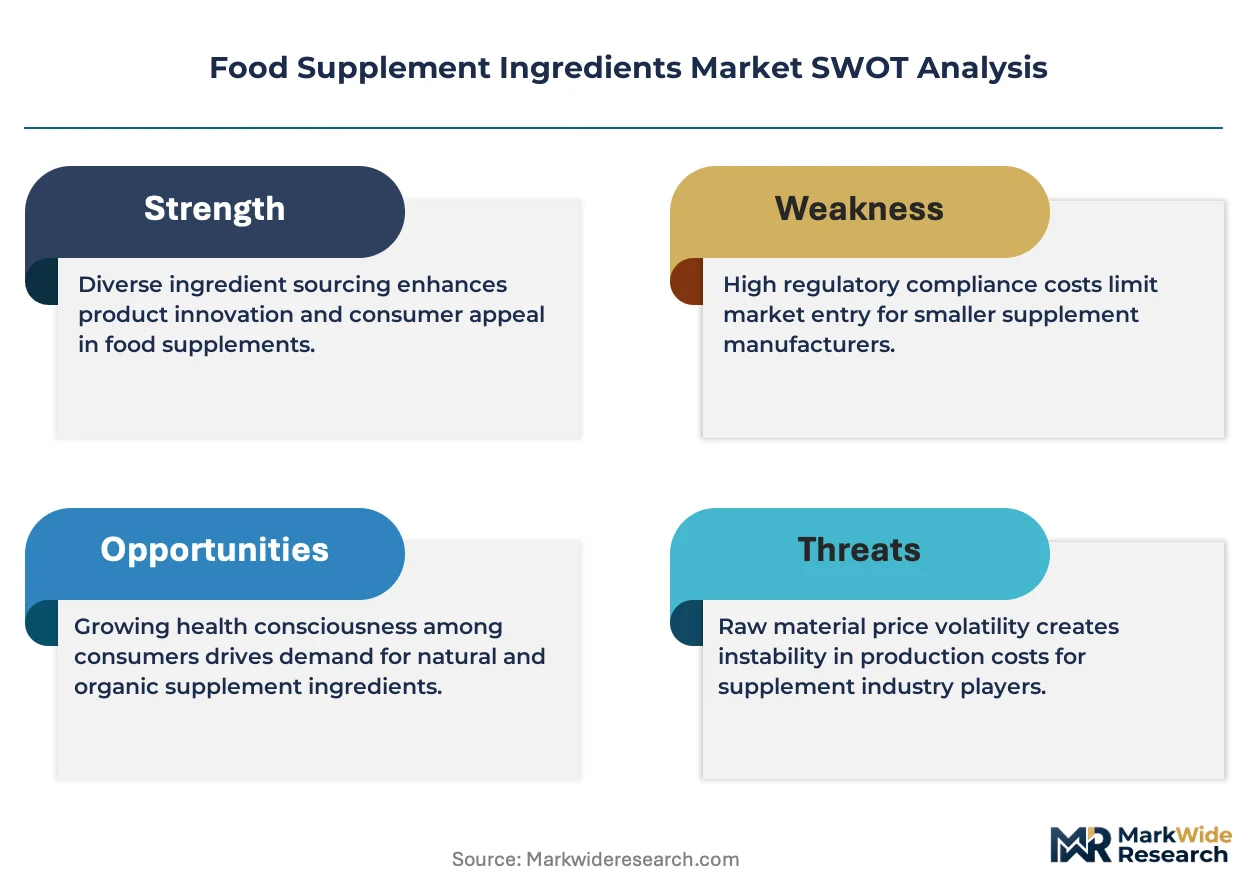
EFSA novel food evaluations and FDA New Dietary Ingredient notifications shape market access timelines and substantiation costs for innovative ingredients. USDA organic certification and EU organic regulation constrain synthetic processing aids in premium positioning. Stakeholders must monitor how FDA enforcement discretion on NDI enforcement reshapes competitive moats for first movers versus fast followers.
Market Dynamics
Precision fermentation biotechnology is compressing production economics for niche bioactives, enabling contract manufacturers to bypass capital-intensive captive capacity while EFSA novel food assessments raise substantiation barriers for synthetic alternatives.
Growth Catalysts
- EFSA Novel Food Framework:Accelerated safety evaluations for fermentation-derived ingredients are opening shelf space for bioactive peptides and human milk oligosaccharides in EU member states.
- Sports Nutrition Formulation:Clean-label protein fortification is pulling plant-based isolates and branched-chain amino acids into pre-workout and recovery product lines.
- Frankfurt Biotech Corridor:Clustered fermentation infrastructure around Germany's Rhine-Main region is reducing logistics costs for amino acid producers serving Central European contract manufacturers.
Market Restraints
- Soy Protein Isolate Volatility:North American oilseed crush margins fluctuate with biodiesel policy shifts, transmitting cost instability to plant-based protein sourcing.
- Chinese Synthetic Vitamin Dominance:Concentrated production of ascorbic acid and B-vitamin intermediates in Shandong and Jiangsu provinces creates single-source vulnerability for European blenders.
- Bioavailability Ceiling:Lipid-soluble vitamin microencapsulation using gum arabic and modified starches hits absorption rate limits that oil-based suspensions circumvent.
Strategic Opportunities
- USDA Organic Certification Gap:Synthetic processing aid restrictions in premium positioning are creating first-mover advantage for enzymatic extraction methods that avoid petrochemical solvents.
- Direct-to-Consumer Capsule Channels:Branded finished forms are capturing margin pools that bulk powder traders cannot access, rewarding backward integration into encapsulation.
- Omega-3 Algal Fermentation:Precision biotechnology convergence with carbon capture feedstocks is enabling EPA/DHA production independent of marine fishery volatility.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Strain optimization and downstream purification expertise concentrates among PhD-level specialists with pharmaceutical fermentation backgrounds.
- FDA NDI Notification Timelines:New Dietary Ingredient dossier preparation and enforcement discretion uncertainty compresses product launch windows for innovative botanical extracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Supplement Ingredients Market |
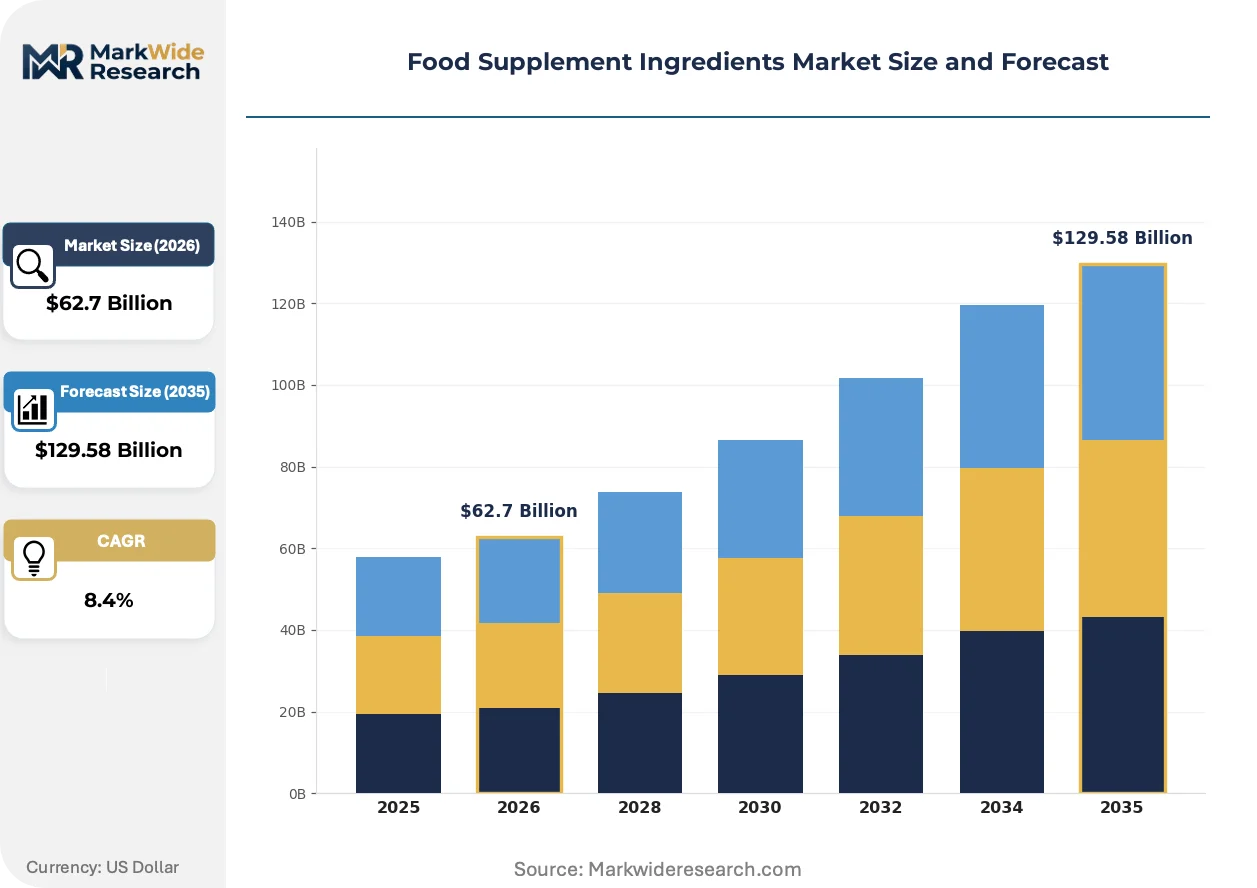
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $129.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Amino Acids, Vitamins, Minerals, Herbal Extracts Form: Powder, Capsule, Tablet, Liquid Application: Sports Nutrition, Weight Management, General Health, Immune Support Source: Plant-Based, Animal-Derived, Synthetic, Fermented |
| Companies Covered | Cargill, Incorporated, ADM, BASF SE, dsm-firmenich, International Flavors & Fragrances, Ingredion, Tate & Lyle, Ajinomoto Co., Inc., Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Supplement Ingredients Market Emerging Trajectories
Spray drying and microencapsulation hardware is giving way to continuous processing and single-use bioreactor systems that cut changeover costs for multi-product contract facilities.
Cell-free enzymatic synthesis is rendering obsolete traditional solvent extraction for high-purity botanical actives. Specialty supplement brands in Germany and the Netherlands are adopting these biocatalytic routes for polyphenol standardization. The shift is compressing batch-to-batch variability while eliminating residual solvent testing burdens.
EFSA's tightened novel food evaluation timelines are forcing ingredient innovators to front-load toxicology investment before pilot-scale production. Synthetic biology startups now sequence safety dossiers into strain development roadmaps rather than treating regulatory submission as a post-scale formality. German contract manufacturers report eighteen-month lead time extensions for first-in-class fermentation ingredients.
Buyer concentration among direct-to-consumer subscription brands is disintermediating traditional ingredient distributors. Sports nutrition companies in the United States now source clinically validated actives through platform APIs that bypass broker markups. This channel compression is visible most acutely in California and Texas, where vertically integrated brands operate captive quality assurance laboratories.
Food Supplement Ingredients Market Segmentation
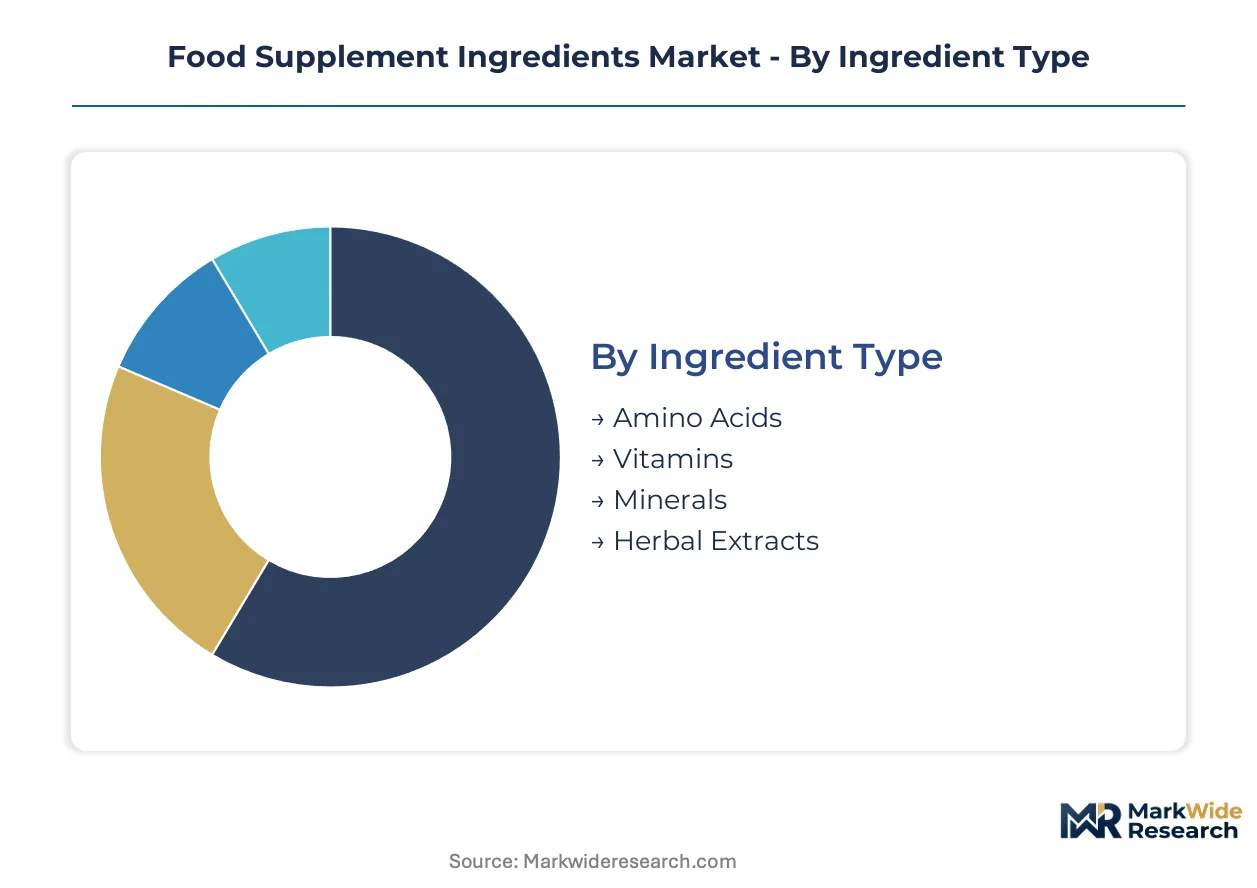
Ingredient categorization in food supplements determines formulation complexity, regulatory pathway selection, and margin capture potential across contract manufacturing and branded finished goods. Manufacturers align portfolio investments with end-use concentration patterns and certification requirements that vary sharply by delivery format and bioactive source.
Ingredient Type:
Use-case spectrum spans clinical fortification mandates at one extreme to discretionary performance optimization at the other, with each ingredient class carrying distinct substantiation burdens and supply chain risk profiles.
- Vitamins:Isolated or synthetic compounds including fat-soluble and water-soluble variants used for deficiency correction and metabolic support. Demand concentrates in general health applications across Germany and the United States where fortification mandates and aging demographics sustain volume; EFSA health claims substantiation creates compliance cost barriers for novel formulations.
- Amino Acids:Proteinogenic and non-proteinogenic building blocks including branched-chain variants for muscle protein synthesis. Sports nutrition brands in the Frankfurt biotech corridor source fermentation-derived grades for clean-label positioning; precision biotechnology is compressing production economics for niche actives.
- Minerals:Inorganic elements formulated as chelates, oxides, or carbonates for bioavailability enhancement.
- Herbal Extracts:Botanical concentrates standardized for marker compounds via solvent or enzymatic extraction methods.
Established volume favors vitamins; emerging adoption favors amino acids.
Form:
Cost tier differentiation separates commodity bulk inputs from value-added delivery systems that command premium positioning in direct-to-consumer channels.
- Powder:Bulk ingredient state requiring reconstitution or blending into finished formulations. Contract manufacturers in North America and Europe source powder actives for sports nutrition and weight management applications where dose flexibility and cost efficiency outweigh convenience premiums.
- Capsule:Gelatin or hydroxypropyl methylcellulose shells encapsulating powders or oils for targeted release. Precision dosing and portability drive demand among subscription-based wellness brands; backward integration into encapsulation equipment captures margin pools unavailable to bulk traders.
- Tablet:Compressed powders with binders and disintegrants for controlled dissolution profiles.
- Liquid:Aqueous or oil-based suspensions enabling rapid absorption and pediatric or geriatric compliance.
Commodity trade flows concentrate in powder; branded margin capture concentrates in capsule.
Application:
Customer type stratification distinguishes institutional fortification programs from discretionary consumer spending with divergent price sensitivity and loyalty patterns.
- Sports Nutrition:Pre-workout, intra-workout, and recovery formulations targeting muscle protein synthesis and energy metabolism. Clean-label requirements under EFSA novel food assessments are tightening formulation standards; brands in Germany and the Netherlands are adopting enzymatic extraction to avoid synthetic processing aids.
- General Health:Daily multivitamin and mineral supplementation for deficiency prevention and wellness maintenance. Volume concentrates in mass-market retail channels across the United States where FDA dietary supplement regulations govern labeling and manufacturing practice compliance.
- Weight Management:Appetite modulation and metabolic support formulations.
- Immune Support:Seasonal and ongoing supplementation targeting respiratory and systemic defense mechanisms.
Revenue scale favors general health; formulation innovation intensity favors sports nutrition.
Source:
Supply concentration patterns reflect capital requirements, intellectual property intensity, and geographic clustering of biotechnology infrastructure.
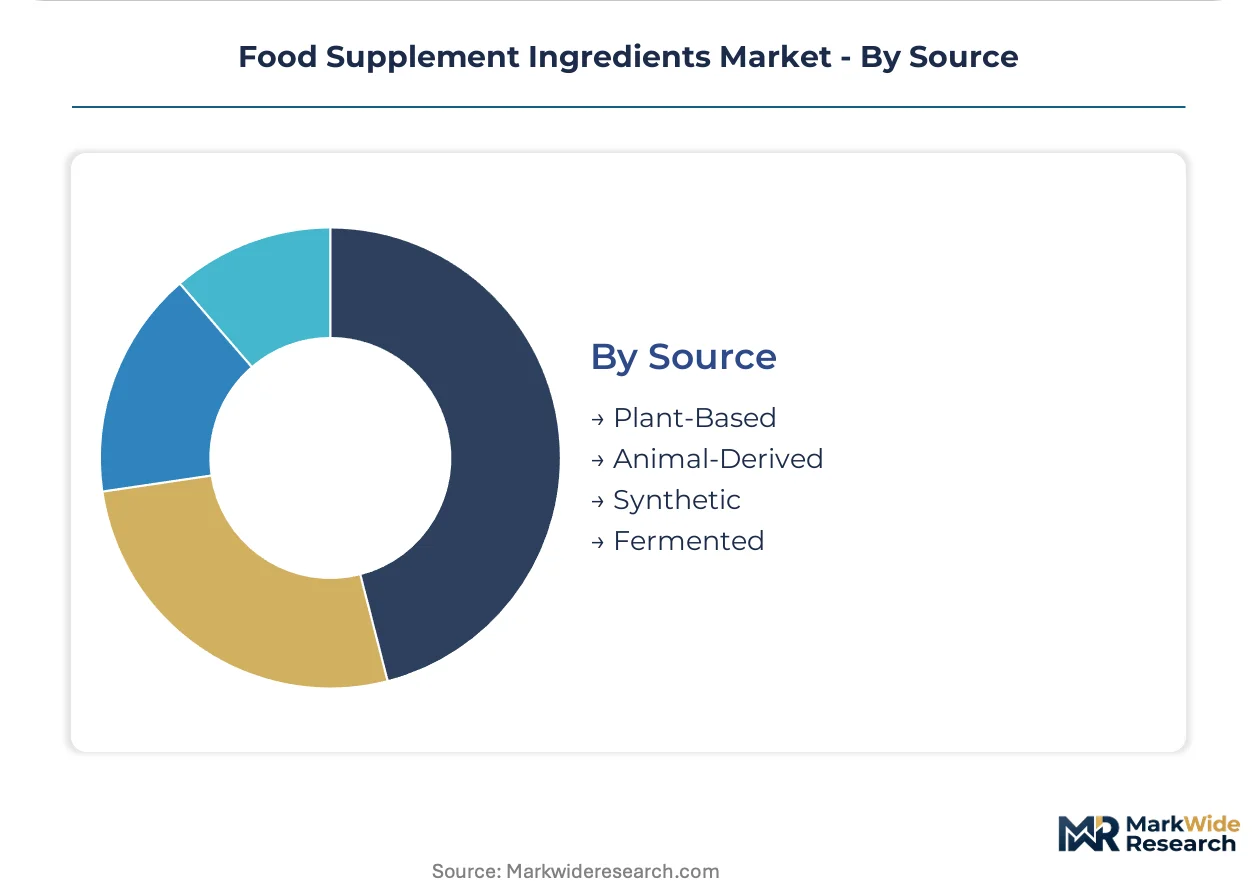
- Fermented:Precision biotechnology and traditional fermentation producing amino acids, omega-3 fatty acids, and human milk oligosaccharides. dsm-firmenich and specialized contract manufacturers leverage single-use bioreactor systems to cut changeover costs; EFSA novel food evaluations front-load toxicology investment before pilot-scale production.
- Synthetic:Chemical synthesis routes for vitamins, minerals, and certain amino acids with established pharmacopeial monographs. Production concentrates in Shandong and Jiangsu provinces of China for ascorbic acid and B-vitamin intermediates, creating single-source vulnerability for European blenders.
- Plant-Based:Extracted or isolated actives from agricultural commodities including oilseeds, algae, and botanical biomass.
- Animal-Derived:Marine, dairy, or other animal-sourced ingredients including fish oil omega-3 and collagen peptides.
Volume foundation rests on synthetic; steepest expansion trajectory belongs to fermented.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments and USDA organic certification programs are redirecting ingredient sourcing toward clustered biotechnology infrastructure in Germany, the United States, and China.
Germany
Sports nutrition brands demand fermentation-derived amino acids for clean-label positioning. EFSA novel food evaluations front-load toxicology requirements before pilot-scale production. The Frankfurt biotech corridor concentrates precision fermentation capacity serving Central European contract manufacturers.
United States
Direct-to-consumer subscription brands disintermediate traditional ingredient distributors through platform API sourcing. FDA New Dietary Ingredient notifications compress product launch windows for innovative botanical extracts. California and Texas host vertically integrated brands operating captive quality assurance laboratories.
China
Shandong and Jiangsu provinces dominate synthetic vitamin intermediate production for ascorbic acid and B-vitamins. SAMR registration requirements govern imported novel food ingredients entering domestic formulation channels. Zhejiang and Jiangsu coastal manufacturing zones supply global blenders with pharmacopeial-grade actives.
Netherlands
Specialty supplement brands adopt cell-free enzymatic synthesis for polyphenol standardization. EU organic regulation restricts synthetic processing aids in premium positioning strategies. Rotterdam logistics hubs facilitate intra-EU distribution of fermented omega-3 and human milk oligosaccharide ingredients.
Japan
Aging demographics sustain clinical fortification demand for vitamin and mineral premixes. PMDA consultation procedures guide novel food ingredient safety substantiation for functional food applications. Osaka and Tokyo metropolitan areas concentrate encapsulation technology providers serving domestic finished goods manufacturers.
Food Supplement Ingredients Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where oilseed processors and precision fermentation platforms anchor separate supply tiers. The vendor base organizes around three strategic archetypes: agricultural commodity processors backward integrating into plant proteins, synthetic chemical conglomerates anchoring vitamin production, and biotechnology specialists leveraging single-use bioreactor systems. Dominant competitive moves include M&A consolidation of contract manufacturing capacity and strategic partnerships bridging fermentation technology with carbon capture feedstock sourcing.
Within the agricultural processing tier, Cargill, Incorporated and ADM represent integrated supply chain controllers that span North American oilseed crush operations through downstream ingredient isolation. BASF SE anchors European synthetic production capacity from its Ludwigshafen manufacturing complex. dsm-firmenich occupies a position exemplifying biotechnology-led differentiation through precision fermentation platforms.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| BASF SE |
| dsm-firmenich |
| International Flavors & Fragrances |
| Ingredion |
| Tate & Lyle |
| Ajinomoto Co., Inc. |
| Arla Foods amba |
| Others |
Supply Flow & Price Mechanics
Chinese synthetic vitamin dominance in Shandong and Jiangsu provinces determines both three-tier pricing spreads across premium fermentation-derived, standard synthetic, and economy-grade botanical inputs, and supply chain shape through single-source dependency for European blenders seeking ascorbic acid and B-vitamin intermediates.
Pricing Analysis
Certification level creates the primary spread, with EFSA novel food approval and USDA organic designation commanding substantial premia over pharmacopeial-grade synthetic alternatives. Contract manufacturers employ project-based pricing for custom fermentation runs, while spot markets govern bulk amino acid powders. Cost compression in standard synthetic vitamins is intensifying because Shandong producers are expanding capacity; sports nutrition brands show least price sensitivity for clean-label fermented grades, while mass-market general health segments resist premium positioning.
Supply Chain Analysis
Export control regimes on precision biotechnology equipment constrain strain optimization technology flows to Chinese and Indian contract manufacturers. Supply concentrates in Germany for fermentation-derived amino acids, China for synthetic vitamin intermediates, and the Netherlands for enzymatically extracted botanicals. Downstream distribution runs through Rotterdam logistics hubs serving intra-EU finished goods manufacturers, with single-source vulnerability in Jiangsu province B-vitamin feedstocks creating tariff exposure for European blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract manufacturing service layers—including regulatory dossier preparation, strain development partnerships, and quality assurance laboratory access—are expanding faster than captive fermentation hardware, creating attach-rate opportunities for ingredient platforms.
For Market Incumbents: Pre-empt precision fermentation platform consolidation by acquiring PhD-level bioprocess engineering talent pools in Germany's Frankfurt corridor before contract manufacturers lock exclusive arrangements. Anchor backward integration into encapsulation equipment to capture direct-to-consumer capsule margins that bulk powder traders cannot access, defending against sports nutrition brands disintermediating traditional distributors through platform API sourcing. For New Entrants and Emerging Players: Establish a beachhead in USDA organic-certified enzymatic extraction for polyphenol standardization, where synthetic processing aid restrictions create first-mover advantage over solvent-dependent incumbents. Target Netherlands specialty supplement brands adopting cell-free biocatalytic routes; your go-to-market angle should emphasize eighteen-month lead time compression versus EFSA novel food evaluation timelines that burden first-in-class fermentation ingredients. For Investors and Strategic Acquirers: The market sits at a fermentation-capacity buildout phase that favors biotechnology specialists with single-use bioreactor systems over agricultural commodity processors. Long-term viability across the projection horizon hinges on carbon capture feedstock integration for omega-3 algal production; watch FDA enforcement discretion on NDI notifications as the inflection signal separating first-mover substantiation moats from fast-follower commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Expansion | Single-use bioreactor deployment cuts changeover costs for multi-product contract facilities serving EFSA novel food assessments. |
| Regulatory Dossier Front-Loading | Toxicology investment sequencing into strain development roadmaps compresses eighteen-month EFSA lead time extensions for first-in-class ingredients. |
| Backward Integration into Encapsulation | Captive capsule production captures margin pools unavailable to bulk powder traders in direct-to-consumer subscription channels. |
| Carbon Capture Feedstock Partnership | Algal omega-3 production independent of marine fishery volatility enables EPA/DHA sourcing resilience for sports nutrition brands. |
| Enzymatic Extraction Certification | USDA organic-compliant biocatalytic routes eliminate residual solvent testing burdens for Netherlands polyphenol standardization. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation platform executives, EFSA regulatory affairs specialists, sports nutrition brand formulators, and contract manufacturing procurement leads, and refined through secondary validation of FDA New Dietary Ingredient notification databases, EFSA novel food approval registers, USDA organic certification records, and customs trade flows for amino acid and vitamin intermediates. Bottom-up volume builds from individual ingredient categories were triangulated against top-down market sizing from oilseed crush margin analysis and biotechnology infrastructure investment tracking.
Demand-supply balance modeling across the analysis window incorporated ingredient type segmentation by clinical substantiation burden, form factor differentiation between bulk powder and value-added capsule delivery, application concentration in sports nutrition versus general health, and source category shifts from synthetic to fermented production. CAGRs were derived from production capacity expansion announcements, EFSA evaluation timeline trends, and buyer concentration patterns among direct-to-consumer subscription platforms. Forecast inputs included Frankfurt biotech corridor infrastructure utilization rates and Chinese synthetic vitamin intermediate export volumes.
Stress conditions across EFSA novel food evaluation acceleration, FDA NDI enforcement discretion shifts, and Chinese export tariff exposure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding precision fermentation cost compression trajectories and clean-label certification adoption curves. Material shifts in carbon capture feedstock commercialization timelines or marine fishery volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Pea Starch Concentrate Market