
 Middle East and Africa Lipids Market | 2026-2036
Middle East and Africa Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lipids Market Foresight
The EU Green Deal is decoupling European export standards from regional production norms, compelling MEA suppliers to adopt cleaner processing benchmarks. Cargill, Incorporated leverages its crushing and refining footprint to sustain supply continuity across North African ports. Wilmar International Ltd. anchors its position through integrated palm oil sourcing from Southeast Asian estates into African distribution networks. Kerry Group differentiates via specialty lipid formulations tailored to pharmaceutical encapsulation requirements in Gulf markets.
Lipids encompass a structurally diverse class of hydrophobic or amphiphilic organic molecules including triglycerides, phospholipids, sterols, and fatty acids, typically characterized by hydrocarbon chain lengths of 4 to 36 carbons and melting points governed by saturation degree and cis-trans isomerism. These compounds serve as essential energy reservoirs, cellular membrane constituents, and solubilization vehicles in industrial formulations. Triglycerides dominate volume flows given their centrality to edible oil and oleochemical value chains, while phospholipids command premium positioning in pharmaceutical liposome and emulsion applications. Plant-based sourcing leads the region due to abundant palm, sunflower, and soybean cultivation, though microbial lipids are gaining traction for omega-3 concentrates as marine supply volatility persists.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce compositional purity thresholds and labeling mandates that determine market access across Gulf Cooperation Council jurisdictions. South Africa's Department of Health and the emerging African Medicines Agency framework are tightening GMP-adjacent requirements for lipid excipients used in antiretroviral and vaccine formulations. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan national standards when configuring regional manufacturing and distribution strategies.
Market Dynamics
The African Medicines Agency harmonization is compressing registration timelines for pharmaceutical-grade lipids while Gulf regulators impose divergent purity benchmarks, forcing suppliers to maintain dual compliance architectures across the region.
Growth Catalysts
- Pharmaceutical Formulation Surge:Antiretroviral and vaccine production in South Africa is pulling high-purity phospholipid demand. The country's Department of Health procurement mandates prioritize local excipient sourcing.
- SFDA Purity Thresholds:Saudi Food and Drug Authority compositional standards are filtering substandard imports and elevating premium lipid positioning in Gulf Cooperation Council markets.
- Microbial Omega-3 Cultivation:Fermentation-based EPA/DHA concentrates are displacing volatile marine supply chains. UAE and Saudi biotech facilities are scaling heterotrophic algae platforms.
Market Restraints
- Palm Oil Price Volatility:Malaysian and Indonesian export duty fluctuations transmit directly into African oleochemical input costs, compressing blender margins in Nigeria and Egypt.
- Refining Capacity Concentration:North African port infrastructure for crushing and fractionation remains concentrated in Morocco and Tunisia, creating bottleneck risk for sub-Saharan distribution.
- Synthetic Surfactant Substitution:Petrochemical-derived emulsifiers are undercutting natural lipid prices in industrial cleaning and personal care formulations across price-sensitive East African markets.
Strategic Opportunities
- Ethiopian Pharmaceutical Manufacturing:The country's industrial park incentives and duty-free pharmaceutical zone status create first-mover positioning for lipid excipient warehousing.
- ESMA-Compliant Blending Hubs:Emirates Authority for Standardization and Metrology certification infrastructure enables re-export positioning into East African markets lacking domestic testing capacity.
- Algae-Biotech Convergence:Integration of photobioreactor engineering with CRISPR strain optimization is opening pharmaceutical-grade DHA production at desert-adjacent facilities in Oman and Jordan.
Industry Challenges
- GMP-Adjacent Talent Scarcity:Pharmaceutical lipid manufacturing requires analytical chemists trained in ICH Q3D elemental impurity protocols, a skill set concentrated in South Africa and Egypt.
- African Medicines Agency Transition Friction:National regulatory bodies in Kenya, Nigeria, and Ghana maintain parallel registration requirements during harmonization, duplicating compliance costs.
- Cold Chain Lipid Stability:Vaccine adjuvant emulsions require uninterrupted 2-8°C distribution, a specification that exceeds last-mile infrastructure in Sahelian corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lipids Market |
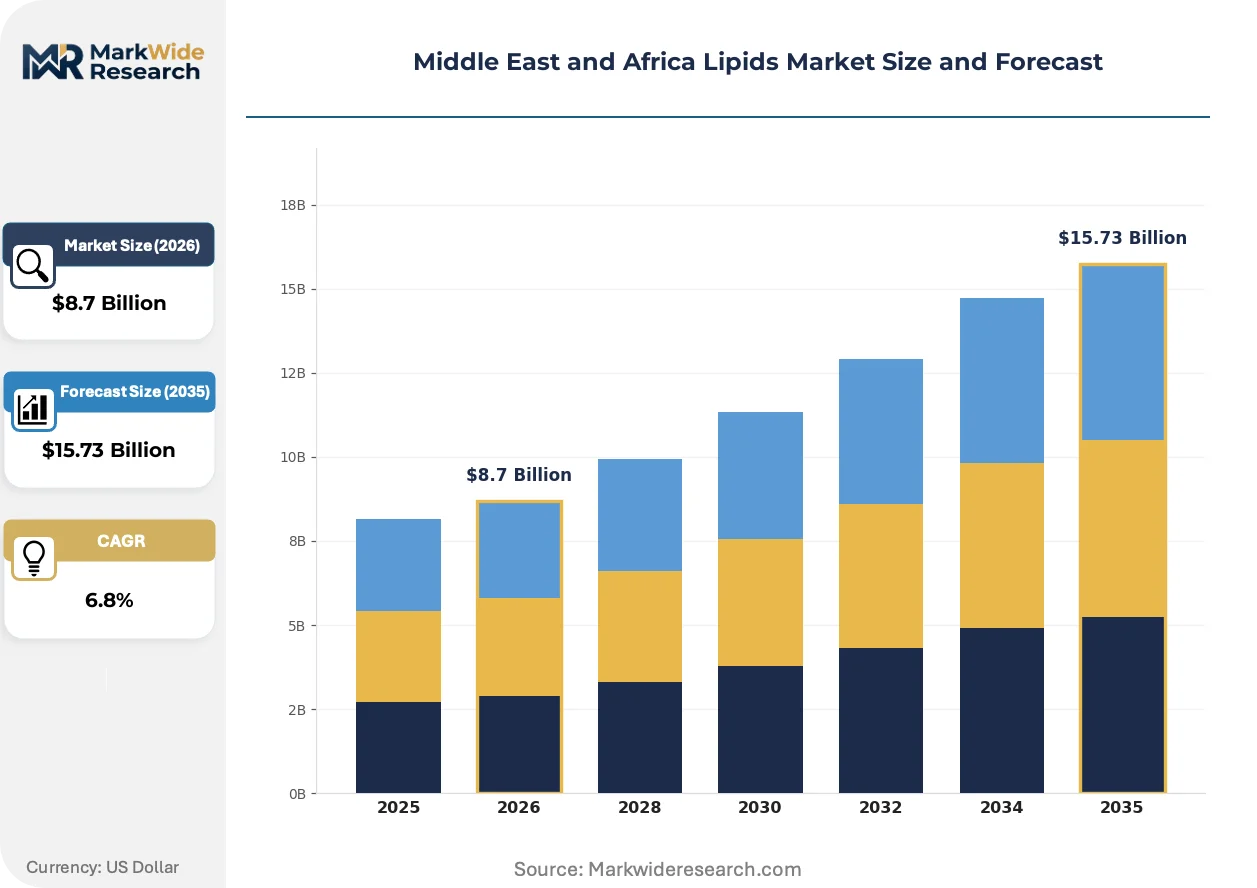
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triglycerides, Phospholipids, Sterols, Fatty Acids Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutrition Source: Plant-Based, Animal-Based, Microbial, Synthetic Form: Liquid, Solid, Semi-Solid, Powder |
| Companies Covered | Cargill, Incorporated, Bunge Limited, ADM (Archer Daniels Midland Company), Kerry Group, Royal DSM, Austevoll Seafood ASA, Wilmar International Ltd., Oleon NV, Bidco Africa, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lipids Market Shifts & Advancements
Continuous processing technology and biotechnological strain engineering are compressing batch cycle times and enabling pharmaceutical-grade lipid production outside traditional crushing geographies.
Supercritical CO2 extraction is decentralizing omega-3 concentration from solvent-based hexane refining. Gulf pharmaceutical manufacturers are adopting this technology to bypass marine supply volatility. The shift enables onshore EPA/DHA production from microbial feedstocks at Jebel Ali and King Abdullah Economic City facilities.
EU Green Deal carbon border adjustments are restructuring export eligibility for MEA lipid processors. South African oleochemical exporters face new embodied emissions documentation requirements. The country's industrial energy mix, dominated by coal-fired grid power, is forcing processors to procure renewable certificates or risk European market exclusion.
Formulation houses in the Gulf are consolidating supplier relationships around excipient vendors offering bundled analytical documentation. Procurement teams at Saudi and UAE pharmaceutical manufacturers now prioritize suppliers with pre-validated drug master files. This concentration is marginalizing traders lacking in-house quality assurance capabilities across Dubai and Jeddah distribution channels.
Middle East and Africa Lipids Market Segmentation
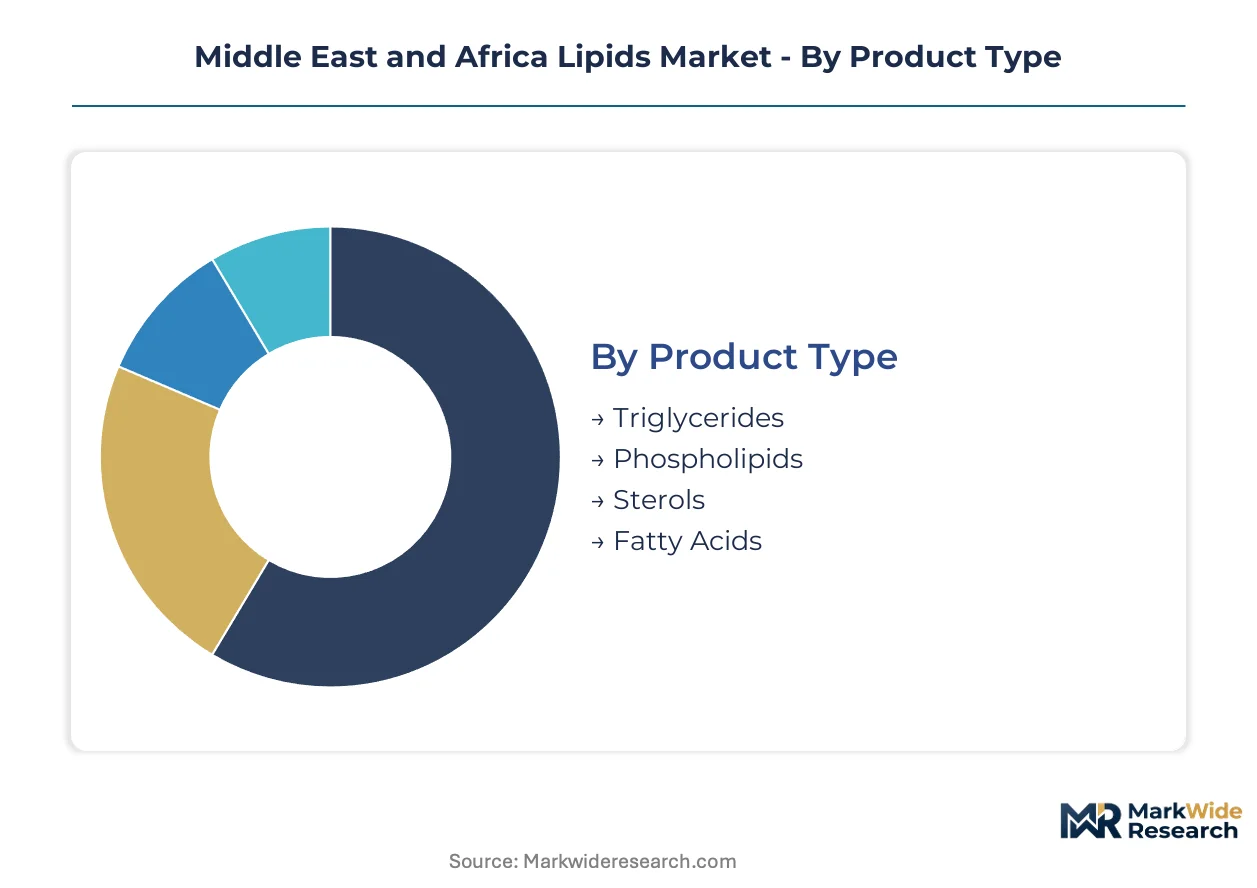
Lipid buyers across the Middle East and Africa fragment sharply by purity requirements and end-use specifications. Pharmaceutical formulators in South Africa and the Gulf demand excipient-grade documentation that food manufacturers rarely require.
Product Type:
Technical sophistication separates commodity purchasers from specialty buyers in this category.
- Triglycerides:These three-fatty-acid esters constitute the foundational volume in edible oils and oleochemical feedstocks. South African food processors and North African refiners absorb bulk shipments for margarine and shortening production, though palm oil price volatility in Southeast Asian source markets compresses blender margins.
- Phospholipids:Amphiphilic membrane constituents with glycerophosphate backbones enable liposome encapsulation and parenteral emulsion stability. Antiretroviral manufacturers in South Africa and vaccine adjuvant formulators in Saudi Arabia are pulling pharmaceutical-grade lecithin and purified phosphatidylcholine at premium pricing.
- Sterols:Plant-derived cholesterol analogs serve functional food fortification and cosmetic emollient applications.
- Fatty Acids:Fractionated carboxylic acid chains feed surfactant and lubricant value chains across Egyptian and Nigerian oleochemical plants.
Volume sits with triglycerides; growth tilts toward phospholipids.
Application:
Regulatory intensity varies dramatically across these demand pools.
- Food & Beverage:Edible oil applications dominate tonnage, with Gulf food manufacturers requiring ESMA-compliant labeling and South African processors adhering to Department of Health standards for fortified products.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications command the steepest expansion trajectory. Lipid nanoparticle formulations for mRNA delivery and long-acting injectable depots are pulling high-purity phospholipid demand in Saudi Arabia and the UAE.
- Cosmetics:Emollient and emulsifier applications in Gulf personal care manufacturing favor stable supply relationships over price minimization.
- Nutrition:Dietary supplement omega-3 concentrates from microbial fermentation are displacing marine fish oil in UAE and Saudi biotech facilities.
Food and beverage retains volume leadership; pharmaceutical applications are climbing the fastest.
Source:
Supply chain provenance determines carbon footprint documentation and regulatory acceptance.
- Plant-Based:Palm, sunflower, and soybean oils anchor regional supply, with Malaysian and Indonesian export duties transmitting directly into African oleochemical input costs.
- Animal-Based:Tallow and fish oil derivatives serve niche pharmaceutical and pet food applications where halal certification requirements constrain Gulf market access.
- Microbial:Heterotrophic algae fermentation platforms in the UAE and Saudi Arabia are scaling EPA and DHA production independent of marine supply volatility.
- Synthetic:Petrochemical-derived fatty alcohols and esters compete on price in industrial cleaning formulations across price-sensitive East African markets.
Plant-based sourcing dominates current volume; microbial platforms are gaining share fastest.
Form:
Physical state dictates packaging, storage, and handling infrastructure requirements.
- Liquid:Bulk tanker and drum shipments of refined oils flow through North African port infrastructure concentrated in Morocco and Tunisia.
- Solid:Fractionated stearins and fully hydrogenated fats serve confectionery and bakery applications requiring oxidative stability.
- Semi-Solid:Partially hydrogenated and interesterified products occupy intermediate rheological specifications for spreadable formulations.
- Powder:Spray-dried and microencapsulated lipids enable dry blend compatibility in infant nutrition and clinical nutrition powders manufactured in South Africa.
Liquid forms capture current volume; powder formats are expanding most quickly in pharmaceutical and clinical nutrition segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Free Zone anchors lipid distribution across Gulf markets, with re-export flows extending into East African corridors lacking domestic refining capacity.
Saudi Arabia
Pharmaceutical-grade phospholipid demand from mRNA formulation facilities drives excipient procurement. SFDA purity mandates filter substandard imports while elevating documentation requirements for drug master files. King Abdullah Economic City hosts biotech facilities scaling heterotrophic algae platforms for omega-3 concentrates.
United Arab Emirates
ESMA certification infrastructure enables blending hub positioning for re-export into African markets. Supercritical CO2 extraction adoption bypasses marine supply volatility for EPA/DHA production. Dubai's logistics corridors concentrate pre-validated excipient warehousing serving Gulf pharmaceutical manufacturers.
South Africa
Antiretroviral and vaccine production pulls high-purity lecithin demand from domestic formulators. Department of Health procurement mandates prioritize local excipient sourcing for public health programs. Durban port infrastructure handles bulk triglyceride shipments for regional oleochemical processing.
Egypt
Nutritional fortification programs sustain food-grade lipid consumption despite currency-driven import cost pressures. The country's national food safety regulator enforces compositional standards for edible oil labeling. Alexandria's crushing facilities fractionate imported palm and sunflower oils for North African distribution.
Morocco
Oleochemical export orientation faces EU Green Deal carbon border documentation requirements. Renewable energy procurement becomes critical for European market access given coal-dominated grid alternatives. Casablanca's port infrastructure remains the primary North African gateway for sub-Saharan lipid shipments.
Middle East and Africa Lipids Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with crushing and refining footprints spanning multiple geographies. Regional specialists compete through ESMA-compliant certification infrastructure and pre-validated drug master files. Three archetypes dominate: Southeast Asian plantation-integrated traders, European specialty lipid formulators, and African regional distributors with local blending capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing fermentation platforms and supercritical extraction assets.
Within the plantation-integrated tier, Wilmar International Ltd. and Cargill, Incorporated exemplify upstream control over palm and soybean supply chains extending into African distribution networks. Kerry Group occupies a position among specialty formulators, anchoring pharmaceutical encapsulation capabilities tailored to Gulf market requirements. These three entities represent the archetype spectrum from commodity volume to premium excipient positioning across the Middle East and Africa.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Bunge Limited |
| ADM (Archer Daniels Midland Company) |
| Kerry Group |
| Royal DSM |
| Austevoll Seafood ASA |
| Wilmar International Ltd. |
| Oleon NV |
| Bidco Africa |
| Others |
Supply & Pricing Matrix
Malaysian palm oil futures volatility cascades through Middle East and Africa lipid markets, compressing blender margins in Nigeria and Egypt while elevating premium-grade phospholipid pricing power in Gulf pharmaceutical corridors. Buyers stratify around certification tiers as ESMA and SFDA mandates filter substandard imports, creating pricing separation between commodity triglycerides and excipient-grade documentation bundles.
Pricing Analysis
Yield-guaranteed pricing anchors pharmaceutical-grade phospholipid contracts in Saudi Arabia and the UAE, where mRNA formulation facilities prioritize batch consistency over unit cost minimization. Price differentiation rests on drug master file validation and ICH Q3D elemental impurity documentation, with Gulf procurement teams paying premiums for pre-validated excipient bundles. Cost compression in commodity triglycerides is intensifying because Malaysian and Indonesian export duty fluctuations transmit directly into African oleochemical input costs. Food manufacturers across Egypt and Nigeria exhibit highest price sensitivity, while Saudi vaccine formulators demonstrate lowest elasticity due to regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm oil estates that feed crushing and fractionation infrastructure concentrated in Morocco and Tunisia. Raw material dependencies center on Southeast Asian crude palm oil, Ukrainian sunflower seed shipments, and Argentine soybean exports. Tariff exposure runs through North African port bottlenecks that constrain sub-Saharan distribution capacity. Distribution runs through Jebel Ali Free Zone re-export corridors extending into East African markets lacking domestic refining infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refining capacity concentration in Morocco and Tunisia props pricing power for pharmaceutical-grade lipids across the Middle East and Africa. North African port infrastructure constraints create supply bottlenecks that sustain margin premiums for integrated suppliers with captive crushing assets.
For Market Incumbents: Lock in backward integration into heterotrophic algae fermentation platforms before microbial omega-3 cultivation scales across UAE and Saudi biotech facilities. Secure ESMA-compliant certification infrastructure to defend against specialty lipid formulators entering Gulf markets with pre-validated drug master files. Prioritize capacity addition in Ethiopian industrial parks to capture first-mover positioning in duty-free pharmaceutical zones.
For New Entrants and Emerging Players: Enter via Ethiopian pharmaceutical manufacturing corridors where industrial park incentives and local procurement mandates create white-space opportunities for lipid excipient warehousing. Target East African markets lacking domestic testing capacity by establishing ESMA-certified blending hubs for re-export positioning. Pursue go-to-market angles centered on bundled analytical documentation for Gulf formulators consolidating supplier relationships.
For Investors and Strategic Acquirers: The window for entry favors regional distributors with local blending capabilities and established relationships with South African Department of Health procurement channels. Acquisition target archetypes include African oleochemical processors with GMP-adjacent analytical capabilities and Gulf-based logistics operators with cold chain infrastructure for vaccine adjuvant emulsions. Watch microbial lipid production scale at desert-adjacent facilities in Oman and Jordan as inflection indicator for marine omega-3 displacement trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | UAE and Saudi biotech facilities scale EPA/DHA production independent of volatile marine supply chains. |
| ESMA-Compliant Blending Hub Establishment | Certification infrastructure enables re-export positioning into East African markets lacking testing capacity. |
| Capacity Expansion in Ethiopian Industrial Parks | Duty-free pharmaceutical zone status creates first-mover positioning for lipid excipient warehousing. |
| Supercritical CO2 Extraction Adoption | Gulf manufacturers bypass solvent-based refining to produce pharmaceutical-grade omega-3 concentrates onshore. |
| Long-term Supply Agreement with South African Formulators | Department of Health procurement mandates prioritize local excipient sourcing for antiretroviral programs. |
Research Methodology
Independent corroboration across customs and trade data, pharmaceutical regulatory filings, and plantation company disclosures underwrites the qualitative findings in this analysis. Primary interviews with lipid procurement managers at Gulf pharmaceutical manufacturers, crushing facility operators in Morocco and Tunisia, and regulatory affairs leads navigating African Medicines Agency harmonization were combined with secondary validation from SFDA and ESMA regulatory databases, South African Department of Health procurement records, and Southeast Asian export duty schedules. Bottom-up volume modeling and top-down value triangulation were applied across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across product type, application, source, and form segmentation dimensions. CAGRs were derived through iterative reconciliation of historical trade flows with projected pharmaceutical formulation demand and oleochemical processing capacity additions. Forecast inputs incorporated African Medicines Agency registration timeline compression, EU Green Deal carbon border adjustment implementation, and heterotrophic algae platform scale-up trajectories at UAE and Saudi biotech facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between Gulf harmonization initiatives and sub-Saharan national standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Vitamin C Ingredients Market
Ingredients
MCT Oil Market
Ingredients
China Beer Adjuncts Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Spray-Dried Isolate Market
Ingredients
North America Rice Bran Oil Market
Ingredients
North America Carrageenan Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Oat Fiber Market
Ingredients
Industrial Starch Market
Ingredients
Chewing Gum Base Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Konjac Flour Market
Ingredients
Savory Ingredients Market