
 Low Calorie Cooking Oil Market | 2026-2036
Low Calorie Cooking Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Cooking Oil Market Analytics
India is narrowing its supply gap for low-calorie cooking oils through expanded domestic refining capacity and oilseed processing infrastructure. Cargill leverages integrated crushing and refining assets across multiple continents to secure feedstock cost advantages. Wilmar International anchors its position through palm oil fractionation expertise and Southeast Asian supply chain control. Archer Daniels Midland Company competes via specialty oilseed breeding programs targeting modified fatty acid profiles.
Low calorie cooking oil comprises edible oils engineered with reduced caloric density per unit volume, typically achieved through water-in-oil emulsion technology, structured lipid modification, or blending with lower-fat carriers to deliver approximately four to nine calories per gram versus conventional oils. These formulations serve commercial kitchens and packaged food producers seeking to maintain sensory performance while meeting nutritional labeling requirements. Olive oil and avocado oil command premium positioning in household and specialty retail channels due to perceived health halo effects and monounsaturated fat profiles. Sunflower oil occupies volume-driven segments across food manufacturing and institutional catering where cost-performance balance governs procurement decisions.
The FDA governs nutrient content claims and serving size disclosures for reduced-calorie oil products marketed in the United States, while EFSA establishes permissible health claim frameworks across European jurisdictions. India's FSSAI mandates fat content thresholds and labeling transparency for edible oil products sold through domestic distribution channels. Stakeholders must monitor evolving front-of-package warning systems and trans fat elimination mandates that reshape formulation priorities and regional market access conditions.
Market Dynamics
Water-in-oil emulsion technology and structured lipid modification are compressing caloric density thresholds while EU F-Gas Regulation and nutrient profiling standards tighten permissible claims across commercial foodservice procurement.
Growth Catalysts
- EU Nutrient Profiling Standards:Tightening fat content claim thresholds are forcing commercial kitchens across Germany and the United Kingdom to reformulate frying and baking applications with certified low-calorie alternatives.
- Urban Foodservice Clustering:Dense metropolitan restaurant networks in Tokyo, London, and Berlin generate concentrated procurement volumes for reduced-calorie frying formulations at scale.
- Trans Fat Elimination Mandates:National bans on partially hydrogenated oils across multiple jurisdictions are redirecting food manufacturers toward modified lipid architectures that maintain functionality without caloric penalty.
Market Restraints
- Palm Oil Feedstock Concentration:Southeast Asian supply chain control by integrated agribusiness groups creates input cost volatility and geopolitical exposure for fractionation-dependent formulations.
- Sensory Performance Ceiling:Water-in-oil emulsion stability limits restrict caloric reduction below four calories per gram without compromising fry stability and mouthfeel in high-temperature applications.
- Front-of-Package Warning Systems:Chilean and Mexican nutrient warning labels are expanding across Latin American trade blocs, creating regulatory friction for imported oil products with emulsifier additives.
Strategic Opportunities
- India Domestic Refining Expansion:Greenfield oilseed processing infrastructure in Maharashtra and Gujarat offers white-space penetration for localized low-calorie oil production serving institutional catering.
- Avocado Oil Premium Positioning:Monounsaturated fat profiles and health halo effects command price premiums in Japanese specialty retail and direct-to-consumer channels.
- Clean Label Emulsifier Innovation:Convergence of enzymatic interesterification and natural stabilizer chemistry enables regulatory-compliant caloric reduction without synthetic additive disclosure requirements.
Industry Challenges
- Specialized Lipid Chemist Shortage:Formulation expertise in structured triglyceride design remains concentrated within legacy edible oil R&D centers, constraining product pipeline velocity for mid-scale entrants.
- Dual Certification Timelines:Simultaneous FDA nutrient content claim validation and EFSA health claim assessment create 18-24 month market entry delays for multinational product launches.
- Legacy Fryer Equipment Compatibility:Existing commercial kitchen infrastructure optimized for conventional oil viscosity profiles requires retrofit investment to handle water-in-oil emulsion behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Cooking Oil Market |
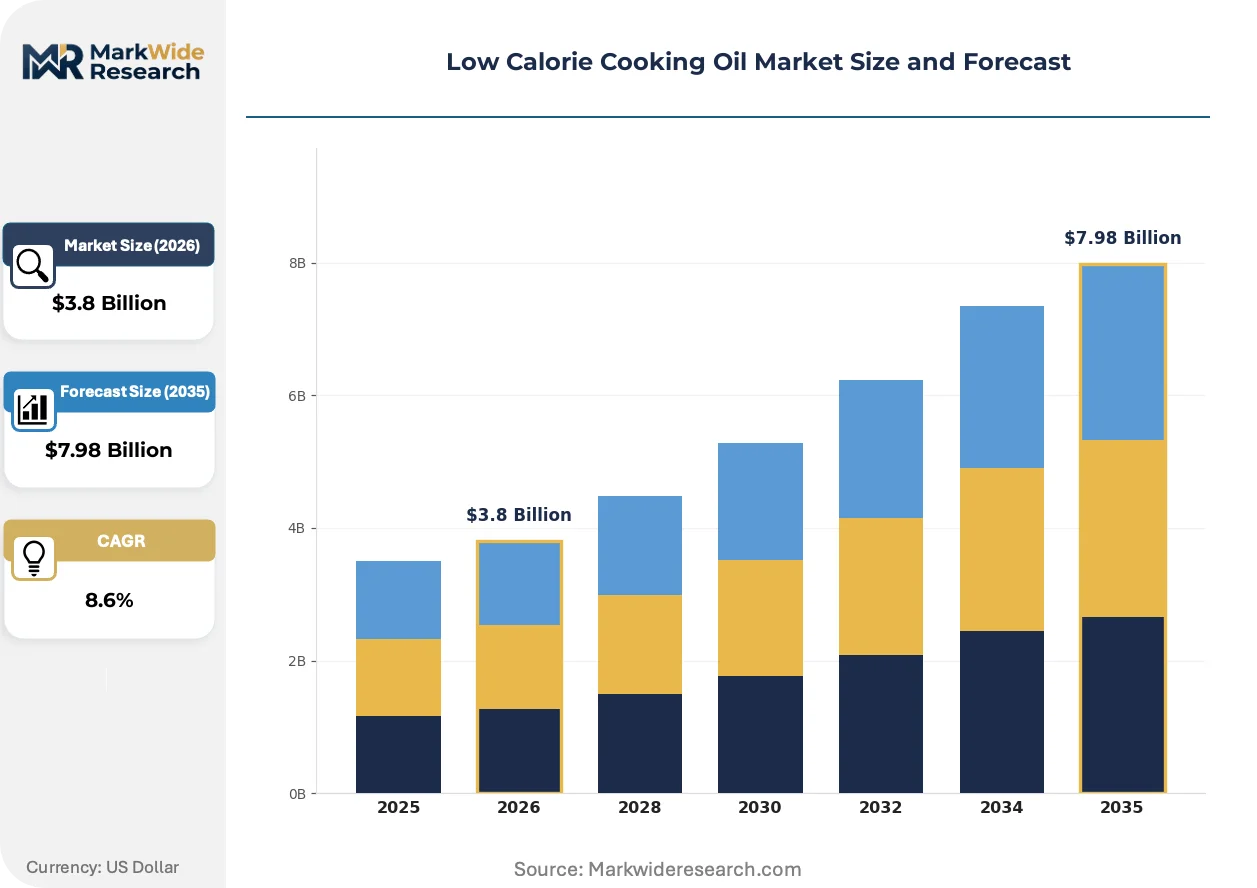
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Coconut Oil, Avocado Oil, Sunflower Oil End User: Household, Restaurants, Catering Services, Food Manufacturers Application: Frying, Baking, Dressing, Marinades Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Wilmar International, Cargill, Archer Daniels Midland Company, CHS, Conagra Foods, Bunge, Associated British Foods, International Foodstuff Company, Beidahuang Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Cooking Oil Market Evolving Landscape
Enzymatic interesterification and precision fermentation-derived lipid structures are rewriting formulation economics while regulatory front-of-package systems and procurement centralization reshape commercial buyer behavior.
Enzymatic interesterification platforms rearrange fatty acid positions on glycerol backbones to engineer structured lipids with targeted melting profiles and reduced caloric density. Quick-service restaurant chains and contract food manufacturers in the United States are piloting these enzymatically modified oils at accelerating rates. The technology is rendering obsolete traditional chemical interesterification methods that rely on sodium methoxide catalysts and generate higher trans fat residuals.
EFSA's evolving health claim substantiation requirements under the EU Nutrition and Health Claims Regulation are tightening clinical evidence thresholds for reduced-fat product positioning. Food manufacturers must now generate human intervention studies demonstrating maintained satiety and nutrient bioavailability, compressing permissible marketing language. Mediterranean packaged food exporters targeting German and French retail channels are restructuring formulation teams to integrate clinical trial design capabilities.
Centralized procurement consortia among North American hospital systems and university foodservice networks are consolidating supplier qualification around unified nutritional specifications. These buying cooperatives are displacing decentralized restaurant-level oil purchasing with multi-year framework agreements tied to certified caloric density thresholds. The shift is most visible across California and New York State healthcare procurement systems where contract terms now mandate third-party laboratory verification of caloric claims.
Low Calorie Cooking Oil Market Segmentation
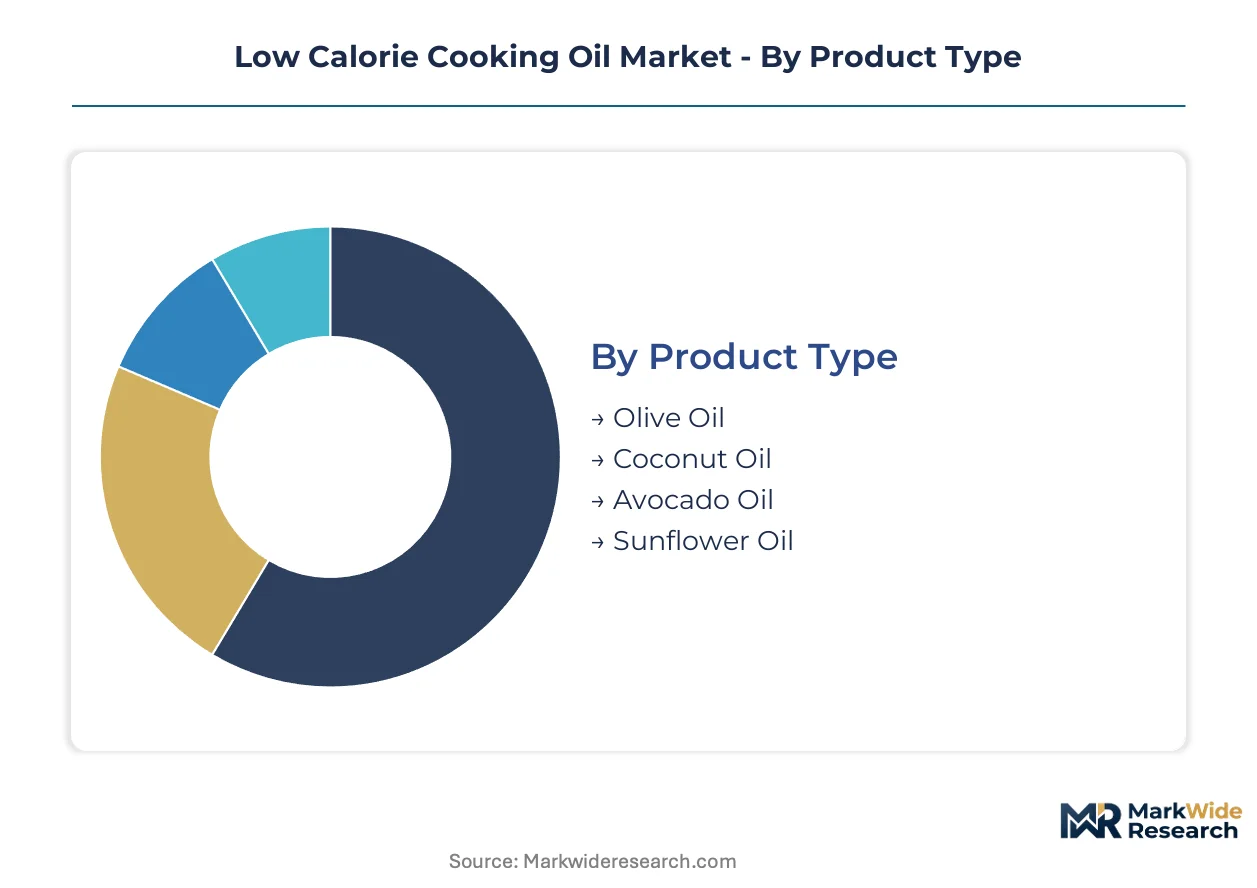
Low calorie cooking oil segmentation reflects divergent technical requirements across temperature-intensive frying versus ambient dressing applications, with formulation chemistry and caloric density thresholds varying sharply by end-use environment. Procurement patterns split between cost-optimized institutional buyers and premium-positioned household segments seeking health halo positioning.
Product Type:
Olive oil and avocado oil anchor premium household positioning, while sunflower oil dominates volume-driven food manufacturing procurement.
- Olive Oil:Cold-pressed and refined variants deliver monounsaturated fat profiles with established Mediterranean diet associations. German and Japanese specialty retail channels concentrate demand for extra-virgin grades certified under EFSA health claim frameworks.
- Avocado Oil:High smoke point and neutral flavor enable frying applications without caloric density penalties. Tokyo's urban foodservice clusters drive premium procurement for reduced-calorie fryer formulations targeting health-conscious consumers.
- Coconut Oil:Medium-chain triglyceride content supports ketogenic diet positioning in direct-to-consumer channels.
- Sunflower Oil:Linoleic acid variants dominate institutional catering across Maharashtra and Gujarat where cost-performance balance governs procurement.
The dominant share belongs to Sunflower Oil, while Avocado Oil is closing the gap fastest.
End User:
Procurement scale and certification requirements diverge sharply between fragmented household purchasing and centralized foodservice contracting.
- Restaurants:Quick-service chains across London and Berlin mandate third-party caloric verification for frying oil contracts under EU nutrient profiling standards. Water-in-oil emulsion stability governs specification acceptance.
- Food Manufacturers:Packaged snack producers in the United States pilot enzymatic interesterification oils to maintain fry stability while meeting FDA nutrient content claim thresholds. Reformulation timelines stretch 18-24 months for dual jurisdiction launches.
- Household:Premium olive and avocado oil purchases concentrate in Japanese specialty retail and California direct-to-consumer channels.
- Catering Services:Hospital and university foodservice networks in New York State consolidate procurement around certified caloric density specifications.
Food Manufacturers command the largest procurement volumes, with Restaurants expanding specifications most aggressively.
Application:
Temperature exposure and emulsion stability requirements dictate formulation selection across the use-case spectrum.
- Frying:High-temperature applications demand structured lipids with modified triglyceride architectures maintaining stability above 180°C. Commercial kitchens across Germany and the United Kingdom face EU F-Gas Regulation compliance pressures alongside caloric reduction targets.
- Baking:Creaming and shortening functionality requires specific melting profile engineering without trans fat residuals. Mediterranean packaged food exporters restructure formulation teams to integrate EFSA-compliant clinical trial capabilities.
- Dressing:Ambient emulsion stability permits higher water content and lower caloric density in vinaigrette applications.
- Marinades:Flavor carrier functionality prioritizes oil penetration and adhesion over thermal stability.
Frying absorbs the dominant formulation investment, though Baking is gaining specification momentum fastest.
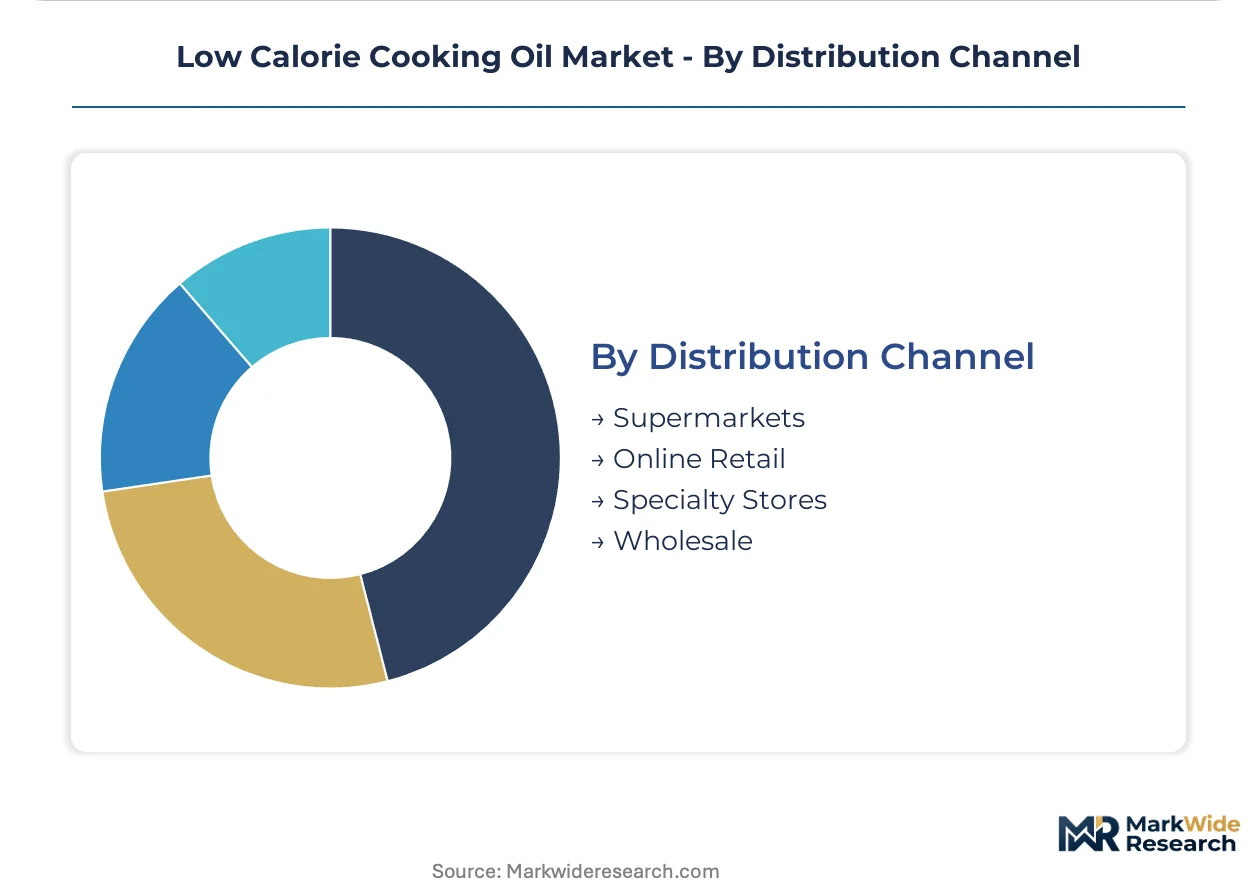
Distribution Channel:
Channel selection correlates with buyer scale, certification requirements, and price transparency needs.
- Supermarkets:Mass-market olive and sunflower oil distribution across German and United Kingdom retail chains depends on front-of-package labeling compliance. Chilean and Mexican warning label expansion creates regulatory friction for emulsifier-containing formulations.
- Wholesale:Institutional catering procurement in Maharashtra and Gujarat routes through oilseed processing infrastructure serving localized low-calorie production. Multi-year framework agreements displace decentralized restaurant purchasing.
- Online Retail:Direct-to-consumer avocado oil positioning in Japanese specialty channels leverages health halo effects and subscription replenishment.
- Specialty Stores:Premium extra-virgin olive oil curation targets California and New York State household segments seeking provenance verification.
Wholesale channels dominate volume throughput, while Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's nutrient profiling standards and the EU F-Gas Regulation anchor the dominant regulatory geography for low-calorie cooking oil commercialization. Urban foodservice clusters in Germany, the United Kingdom, and Japan concentrate procurement scale. India's domestic refining expansion is narrowing supply gaps through Maharashtra and Gujarat infrastructure investments.
United States
Quick-service restaurant chains pilot enzymatic interesterification oils at accelerating rates. FDA nutrient content claim validation creates 18-24 month market entry timelines for reduced-calorie formulations. California and New York State healthcare procurement systems mandate third-party laboratory verification of caloric density claims.
Germany
Commercial kitchens across Berlin reformulate frying applications under tightening EU nutrient profiling standards. The F-Gas Regulation pressures foodservice operators to align equipment specifications with reduced-calorie oil thermal behavior. German specialty retail channels concentrate demand for extra-virgin olive grades certified under EFSA health claim frameworks.
United Kingdom
London's dense metropolitan restaurant networks generate concentrated procurement volumes for water-in-oil emulsion frying formulations. EFSA health claim substantiation requirements compress permissible marketing language for packaged food exporters. Contract food manufacturers restructure formulation teams to integrate clinical trial design capabilities.
Japan
Tokyo's urban foodservice clusters drive premium procurement for avocado oil reduced-calorie fryer formulations. METI standards intersect with consumer health consciousness to elevate monounsaturated fat positioning. Japanese specialty retail and direct-to-consumer channels concentrate household purchases of premium olive and avocado oil variants.
India
Maharashtra and Gujarat oilseed processing infrastructure supports localized low-calorie oil production for institutional catering. FSSAI mandates fat content thresholds and labeling transparency for edible oil products sold through domestic distribution channels. Greenfield refining capacity expansion narrows the supply gap for cost-optimized sunflower oil formulations.
Low Calorie Cooking Oil Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around integrated agribusiness groups with captive feedstock access and specialized lipid technology providers with formulation expertise. Three archetypes dominate: Southeast Asian palm oil fractionation specialists, North American oilseed processors with breeding program assets, and diversified food conglomerates with retail channel control. Competitive moves center on backward integration into crushing assets and multi-year framework agreement capture with centralized procurement consortia.
Within the integrated agribusiness tier, Wilmar International and Cargill exemplify divergent geographic anchoring strategies. Wilmar International occupies a position tied to Southeast Asian supply chain control and palm oil fractionation expertise. Cargill represents the North American model of leveraging integrated crushing and refining assets across multiple continents. Archer Daniels Midland Company sits within the specialty technology vector, anchored by oilseed breeding programs targeting modified fatty acid profiles.
| Leading Market Players |
|---|
| Wilmar International |
| Cargill |
| Archer Daniels Midland Company |
| CHS |
| Conagra Foods |
| Bunge |
| Associated British Foods |
| International Foodstuff Company |
| Beidahuang Group |
| Others |
Value Network & Pricing Analysis
The Malacca Strait shipping corridor carries palm kernel and fractionated oil feedstocks from Southeast Asian crushing facilities to European and Japanese refiners, with freight cost volatility amplifying margin compression for water-in-oil emulsion producers while enabling sharp price differentiation between integrated agribusiness groups and independent formulators.
Pricing Analysis
Price spreads between German foodservice procurement contracts and Indian institutional catering tenders exceed threefold, reflecting divergent certification burdens and cold-chain logistics requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA health claim validation status and enzymatic modification depth. Pricing pressure stems from front-of-package warning label expansion across Latin American trade blocs, forcing reformulation costs onto exporters. Quick-service restaurant chains in the United States exhibit lowest price sensitivity due to multi-year framework agreement structures, while Maharashtra-based catering contractors face acute margin constraints.
Supply Chain Analysis
EU F-Gas Regulation restrictions on fluorinated greenhouse gas equipment limit technology transfer for advanced fractionation systems to non-EU markets, constraining capacity expansion in competing geographies. Supply concentrates in Indonesia and Malaysia for palm oil feedstocks, with Ukraine and Russia for sunflower seed crushing before regional conflict disruptions. Raw material dependencies center on crude palm oil, high-oleic sunflower seed, and enzymatic catalysts for interesterification platforms. Single-source vulnerability pervades Southeast Asian palm oil fractionation expertise, with distribution running through integrated agribusiness groups controlling crushing-to-refining assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic interesterification platforms and tightening EU nutrient profiling standards are compressing formulation economics while redirecting procurement toward certified low-calorie alternatives, creating a high-growth disruption window for stakeholders with captive feedstock access or clinical trial capabilities.
For Market Incumbents: Entrench position through backward integration into Maharashtra and Gujarat oilseed crushing assets to capture India's domestic refining expansion, while accelerating EFSA health claim dossier investments to preempt 18-24 month validation timelines that emerging competitors cannot absorb. Lock in multi-year framework agreements with North American hospital procurement consortia before centralized buying specifications solidify around third-party caloric verification mandates. For New Entrants and Emerging Players: Build out localized production capacity in India's greenfield refining zones to serve institutional catering procurement at cost-optimized sunflower oil price points, bypassing incumbent Southeast Asian palm oil supply chain control. Target Japanese specialty retail channels for premium avocado oil positioning through direct-to-consumer subscription models, leveraging METI standards convergence with consumer health consciousness to justify price premiums without emulsion technology investments. For Investors and Strategic Acquirers: EFSA's evolving clinical evidence thresholds for reduced-fat health claims reshape the acquisition landscape toward formulation teams with integrated clinical trial design capabilities rather than commodity refining assets. Five-to-ten year viability favors targets with enzymatic interesterification platforms and existing dual-jurisdiction regulatory filings. Watch for FDA nutrient content claim validation backlogs as inflection indicator for competitive positioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | Captive palm kernel and sunflower seed supply secures margin control against Southeast Asian feedstock volatility. |
| EFSA Health Claim Dossier Investment | Clinical trial capabilities unlock premium positioning in German and French retail channels under tightening substantiation rules. |
| Enzymatic Interesterification Scale-Up | Modified triglyceride architectures displace chemical catalyst methods, eliminating trans fat residuals for FDA compliance. |
| Multi-Year Framework Agreement Capture | Centralized procurement consortia in California and New York State healthcare systems displace decentralized restaurant purchasing. |
| Clean Label Emulsifier R&D | Natural stabilizer chemistry navigates Chilean and Mexican front-of-package warning label expansion without synthetic additive disclosure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service restaurant procurement directors, commercial kitchen equipment manufacturers, lipid technology R&D heads, and institutional catering contract managers. Secondary validation drew from EFSA health claim register filings, FDA nutrient content claim guidance documents, FSSAI fat content threshold notifications, and EU F-Gas Regulation implementation reports. Bottom-up volume estimates from country-level foodservice procurement data were triangulated against top-down agribusiness crushing capacity disclosures.
Calibration against historical price spreads between premium and economy oil tiers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, application temperature regime, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections incorporating regulatory compliance cost pass-through assumptions. Industry-specific inputs encompassed enzymatic catalyst cost curves and water-in-oil emulsion stability thresholds in high-temperature frying applications.
Stress conditions across palm oil feedstock price volatility, EU F-Gas Regulation enforcement intensity, and front-of-package warning label geographic expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clinical trial timeline compression and centralized procurement consortium formation velocity. Material shifts in trans fat elimination mandate implementation schedules or enzymatic interesterification cost parity achievement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dried Fruit Ingredients Market
Ingredients
United Kingdom Protein Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
African Brewing Enzymes Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Compressed Yeast Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Food Botanicals Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Instant Dry Yeast Market
Ingredients
Egg White Powder Market
Ingredients
North America Cocoa Products Market
Ingredients
Europe Gelatin Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
L-Arabinose Market
Ingredients
Canola Oil Market