
 Lime Market | 2026-2036
Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Lime Market Intelligence
Mexico's lime kiln capacity build-out is fragmenting supply patterns across North American construction and chemical offtake. Carmeuse leverages vertical integration from quarry to terminal to secure logistics advantages in the Great Lakes corridor. Lhoist Group anchors European supply through captive limestone reserves and specialty hydrated lime production. Graymont Limited competes across the Pacific Northwest with deep regional distribution networks serving pulp mills and water treatment facilities.
Lime encompasses calcium oxide (quicklime) and calcium hydroxide (hydrated lime) produced by calcining limestone at temperatures exceeding 900 degrees Celsius, yielding products with 90-95% CaO content for pH modification, fluxing, and binding applications. Quicklime dominates metallurgical flux demand where steel slag chemistry requires high-reactivity grades with low silica and sulfur content. Hydrated lime captures margin pools in water treatment and flue gas desulfurization where precise particle sizing and slaking control differentiate suppliers. Agricultural lime remains volume-heavy but price-constrained across Midwestern row-crop operations.
EPA National Ambient Air Quality Standards and OSHA permissible exposure limits shape kiln emissions controls and worker safety protocols across US production sites. China's MEE enforces dual carbon goals through GB standard updates that mandate energy-efficient vertical shaft kiln retrofits or shutdowns. India's CEA power plant regulations drive hydrated lime consumption for flue gas treatment in coal-dependent regions. Stakeholders must weigh carbon capture integration against limestone reserve depletion rates when committing capital to new calcination capacity.
Market Dynamics
Steel decarbonization mandates are compressing demand for traditional metallurgical quicklime while simultaneously creating premium markets for ultra-low-sulfur flux grades. Kiln operators face simultaneous pressure from China's GB emission standards and India's CEA flue gas regulations, forcing capital allocation toward emission controls or retirement.
Growth Catalysts
- Steel Slag Chemistry Requirements:Electric arc furnace expansion in India and Southeast Asia drives procurement of high-reactivity quicklime with sub-0.5% sulfur content for slag conditioning.
- EPA NAAQS Compliance:US coal power plants accelerate hydrated lime consumption for SO2 scrubbing as MATS deadlines tighten mercury and acid gas emission limits.
- Carbon Capture Integration:Direct air capture and post-combustion carbon capture facilities specify calcium oxide sorbents, creating new offtake channels outside traditional industrial applications.
Market Restraints
- Energy Cost Volatility:Natural gas and petroleum coke price swings constitute 35-45% of quicklime production costs, eroding margin stability for merchant kiln operators without captive fuel supply.
- Limestone Reserve Depletion:High-calcium limestone deposits with sub-3% magnesium content are concentrating in fewer geographies, extending haul distances and tightening feedstock security.
- Dolomitic Lime Substitution:Magnesium-bearing alternatives capture share in agricultural and some construction applications where calcium purity is less critical.
Strategic Opportunities
- Flue Gas Treatment in Coal-Dependent Regions:India's CEA mandates for thermal power plants create sustained hydrated lime demand across Uttar Pradesh, Odisha, and Chhattisgarh state clusters.
- Slaking Automation:Precision-controlled hydration systems enable on-site production of high-purity calcium hydroxide for water treatment, bypassing bulk transport costs.
- Agricultural Soil Amendment:pH correction programs in Brazil's Cerrado and US Corn Belt offer volume expansion as climate-stressed soils require more frequent liming cycles.
Industry Challenges
- Kiln Operator Skill Scarcity:Vertical shaft and rotary kiln combustion optimization requires expertise that is aging out of the workforce faster than vocational programs replenish supply.
- Emissions Control Capex Burden:Baghouse upgrades, SNCR systems, and continuous emissions monitoring equipment demand capital outlays that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lime Market |
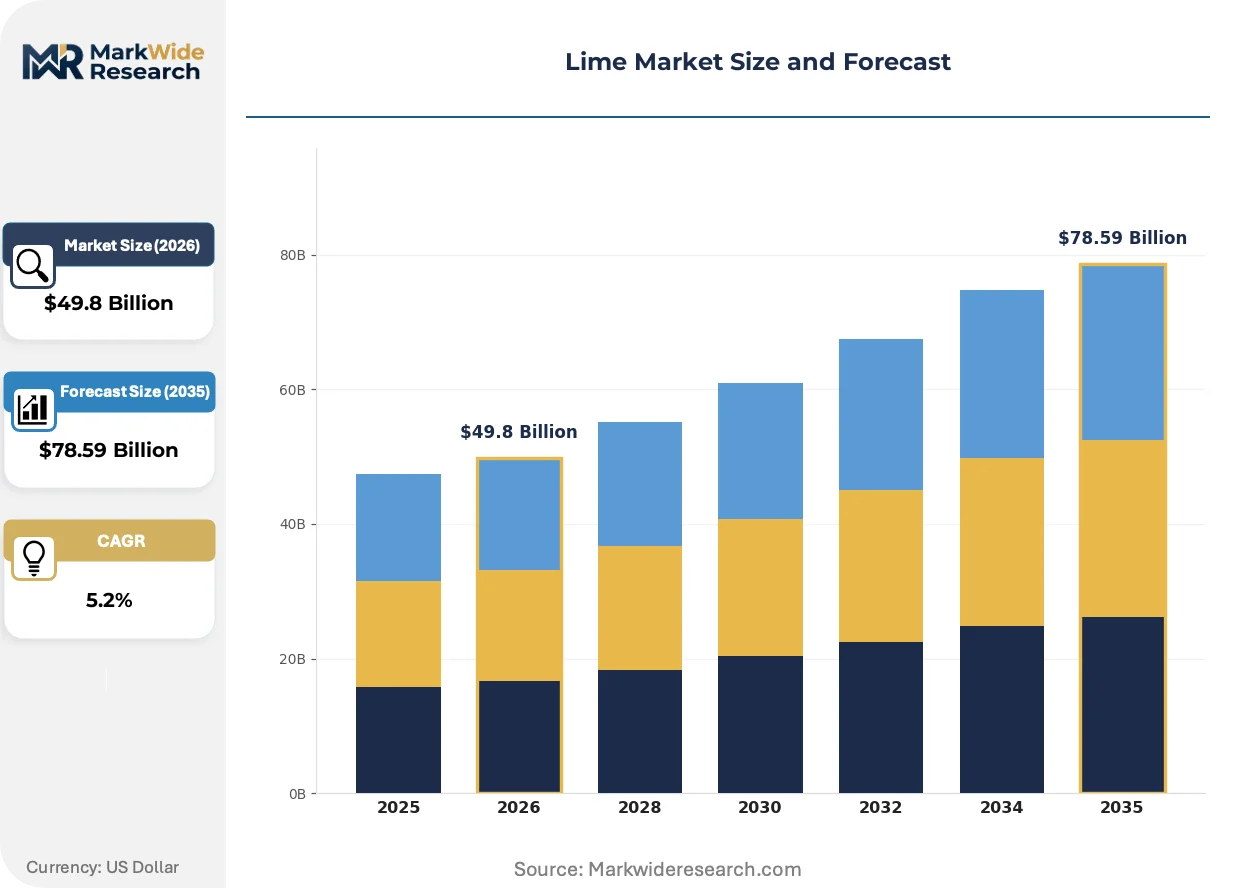
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $78.59 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quicklime, Agricultural Lime, Dolomitic Lime, High-Calcium Lime Application: Soil Stabilization, Water Treatment, Steel Manufacturing, Chemical Processing, Construction Materials End User Industry: Metallurgy, Agriculture, Water Supply Plants, Chemical Plants, Construction Firms Packaging Type: Bags, Bulk Bags, Loose Bulk, Drums, Paper Sacks |
| Companies Covered | Mississippi Lime Company, Cheney Lime & Cement Company, Carmeuse, Valley Minerals, Linwood Mining & Minerals Corporation, Graymont Limited, United States Lime & Minerals, LafargeHolcim, Lhoist Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lime Market Strategic Shifts & Innovations
Calcination technology is digitizing at the kiln control layer while regulatory pressure fragments product specifications across geographies. Suppliers must simultaneously manage legacy asset performance and pilot novel sorbent applications for carbon management.
Advanced process control systems with real-time kiln temperature profiling and predictive maintenance algorithms are digitizing combustion efficiency optimization. Steel mills and chemical processors with continuous offtake requirements deploy these systems to reduce fuel consumption per ton of quicklime produced. The resulting operational transparency is digitizing contract structures toward guaranteed reactivity specifications rather than commodity tonnage.
China's MEE enforcement of dual carbon goals through updated GB standards is forcing vertical shaft kiln retrofits or permanent closures across Shandong and Hebei provinces. Kiln operators must install waste heat recovery and particulate capture systems or exit the market entirely. This regulatory compression is concentrating supply among integrated producers with capital reserves for compliance.
Long-term service agreements with guaranteed reactivity performance are displacing spot-market lime procurement at major water treatment utilities. Municipal buyers in the US Great Lakes and Ohio River corridors favor suppliers assuming slaking and dosing system maintenance risk. This contractual shift is most visible where EPA Safe Drinking Water Act compliance pressures demand consistent pH control without operational burden on plant staff.
Lime Market Segmentation
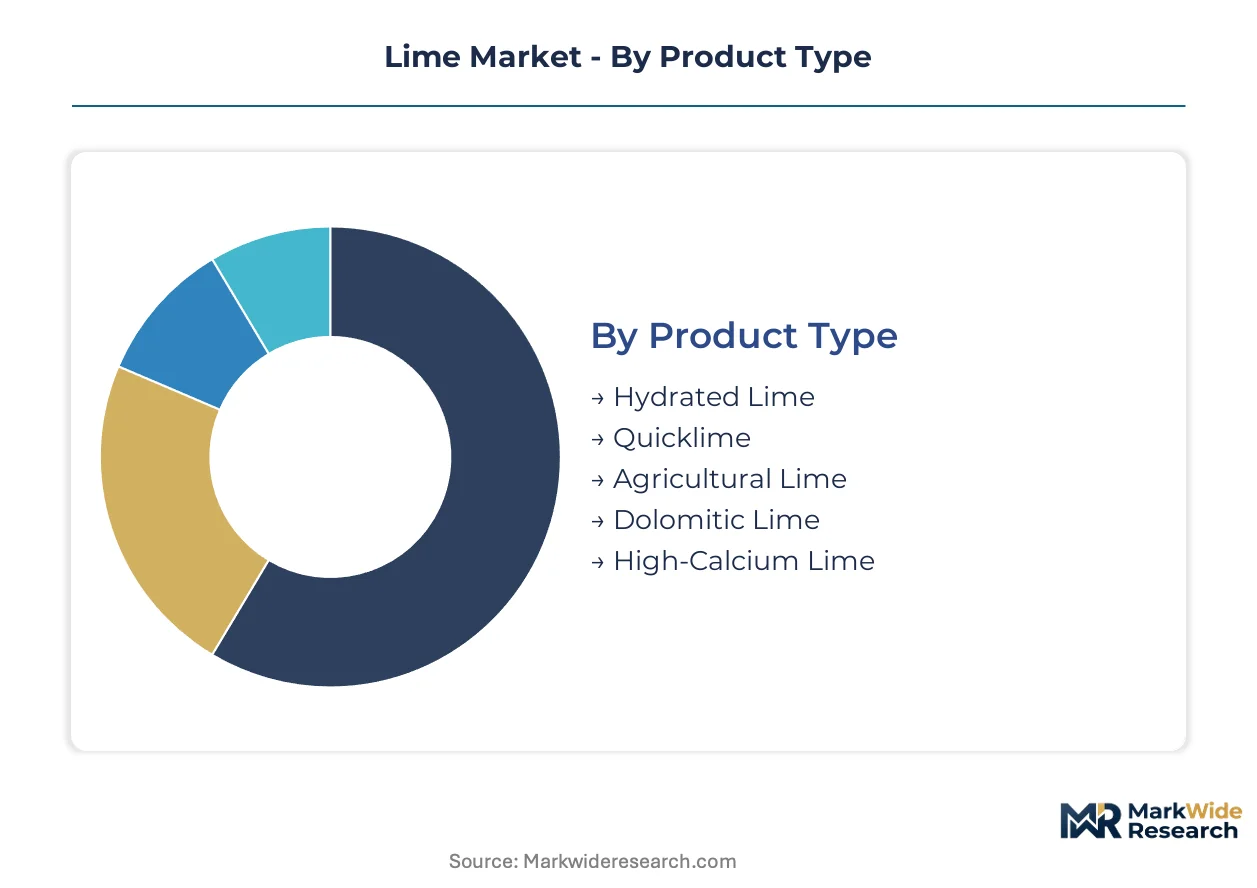
Lime market segmentation reveals how product chemistry, logistics configuration, and end-use specifications fragment procurement patterns across industrial buyers. Suppliers must align calcination capacity with precise reactivity grades while managing packaging economics that swing dramatically by customer scale and handling infrastructure.
Product Type:
Cost tier differentiation separates commodity-grade agricultural lime from premium metallurgical quicklime with tight sulfur specifications.
- Quicklime:Calcium oxide produced at 900-1200°C calcination delivers 90-95% CaO content with high reactivity for slag conditioning. Steel mills in India and Southeast Asia drive procurement of sub-0.5% sulfur grades as electric arc furnace capacity expands.
- Hydrated Lime:Controlled slaking of quicklime yields calcium hydroxide with precise particle sizing for water treatment and flue gas desulfurization. India's CEA power plant mandates sustain demand across Uttar Pradesh and Odisha state clusters.
- Agricultural Lime:Ground limestone with lower calcium purity serves pH correction in Midwestern US row-crop operations and Brazil's Cerrado region.
- Dolomitic Lime:Magnesium-bearing composition captures share where calcium purity is less critical, particularly in agricultural and select construction applications.
- High-Calcium Lime:Premium grade with sub-3% magnesium content commands sourcing priority as high-purity limestone reserves concentrate in fewer geographies.
Quicklime commands the established base. The steepest expansion runs through hydrated lime as flue gas treatment regulations tighten across coal-dependent power systems.
Application:
Application segmentation tracks how lime chemistry maps to distinct industrial process requirements and regulatory compliance burdens.
- Steel Manufacturing:Metallurgical flux demand concentrates on high-reactivity quicklime for slag chemistry control. Decarbonization mandates are compressing traditional volume while creating premium tiers for ultra-low-sulfur grades.
- Water Treatment:Municipal utilities specify hydrated lime for pH modification and softening. EPA Safe Drinking Water Act compliance pressures drive long-term service agreements with guaranteed reactivity performance.
- Construction Materials:Soil stabilization and asphalt applications absorb volume-heavy but price-constrained hydrated lime grades across North American infrastructure projects.
- Chemical Processing:Precipitated calcium carbonate and other derivatives require consistent reactivity specifications that digitize contract structures toward performance guarantees.
- Soil Stabilization:Highway and building foundation applications demand reliable supply continuity with less stringent chemical purity than metallurgical or water treatment uses.
Steel manufacturing anchors revenue concentration. Water treatment is climbing the fastest as municipal buyers outsource operational risk through performance-based contracts.
End User Industry:
Customer type segmentation exposes how procurement scale and technical sophistication fragment supplier relationships and pricing power.
- Metallurgy:Integrated steel mills and mini-mills with continuous offtake deploy advanced process control systems to reduce fuel consumption per ton. These buyers digitize contracts toward guaranteed reactivity rather than commodity tonnage.
- Water Supply Plants:Municipal utilities across the US Great Lakes and Ohio River corridors favor suppliers assuming slaking and dosing system maintenance risk.
- Agriculture:Midwestern cooperatives and Brazilian large-scale operators drive volume but face price constraints from dolomitic lime substitution and climate-stressed liming cycle variability.
- Chemical Plants:Continuous processors with precise specification requirements concentrate procurement among integrated suppliers with captive limestone reserves.
- Construction Firms:Project-based demand creates spot-market exposure with higher logistics sensitivity than industrial accounts with dedicated terminal infrastructure.
Metallurgy retains the deepest supplier integration. Water supply plants are gaining share fastest as service contracting displaces spot procurement.
Packaging Type:
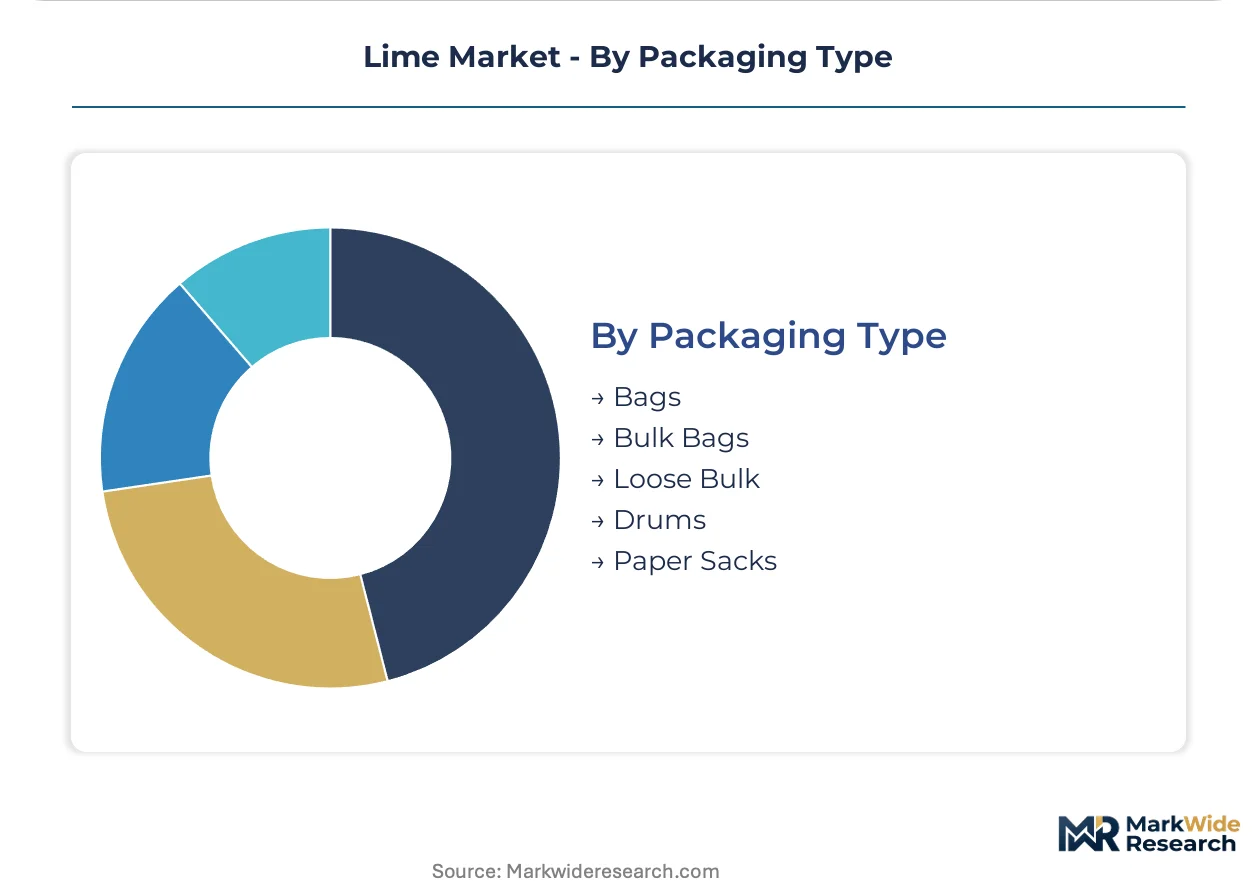
Packaging configuration directly determines distribution economics and customer accessibility across fragmented agricultural and concentrated industrial segments.
- Bulk Bags:Intermediate packaging serves mid-scale water treatment and chemical processors without pneumatic handling infrastructure. This format bridges loose bulk efficiency and bagged flexibility.
- Loose Bulk:Pneumatic trailer delivery minimizes unit costs for steel mills and large municipal utilities with silo storage. Regional distribution networks concentrate around Great Lakes terminal infrastructure.
- Bags:25-50kg sacks reach small agricultural and construction customers through distributor networks. Higher per-ton packaging costs are offset by handling convenience.
- Drums:Sealed steel containers serve specialty chemical applications requiring moisture protection and precise dosing control.
- Paper Sacks:Multi-wall construction provides breathable storage for hydrated lime in humid climates where caking resistance matters.
Loose bulk dominates volume throughput. Bulk bags are expanding most quickly as mid-scale industrial users upgrade handling systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-calcium limestone reserves cluster in select geographies, concentrating calcination capacity near quarry sites with favorable chemistry and logistics access to industrial corridors. Kiln operators in China, India, the United States, Germany, and Brazil anchor supply for metallurgical flux, water treatment, and construction applications.
China
Steel mills in Hebei and Shandong provinces drive procurement of sub-0.5% sulfur quicklime for electric arc furnace slag conditioning. The MEE enforces dual carbon goals through updated GB standards that mandate vertical shaft kiln retrofits or permanent closures. Shandong's lime producers face concentrated pressure to install waste heat recovery systems or exit entirely.
India
Thermal power plants across Uttar Pradesh, Odisha, and Chhattisgarh sustain hydrated lime demand for flue gas desulfurization under CEA mandates. Infrastructure expansion and metallurgy growth absorb rising quicklime output from captive kiln operations. The Delhi-Mumbai Industrial Corridor anchors logistics networks serving both steel decarbonization and coal plant compliance markets.
United States
EPA NAAQS compliance accelerates hydrated lime consumption at coal power plants in the Ohio River and Great Lakes corridors. Municipal water treatment utilities in these regions favor long-term service agreements with guaranteed reactivity performance. Carmeuse leverages terminal infrastructure along the Great Lakes to secure logistics advantages for bulk pneumatic delivery.
Germany
Specialty hydrated lime production for chemical processing concentrates in industrial clusters with captive limestone reserves. The EU Green Deal and REACH regulations shape emissions control investments at calcination facilities. Lhoist Group anchors European supply through integrated quarry-to-terminal operations serving water treatment and flue gas applications.
Brazil
Agricultural pH correction programs in the Cerrado region drive volume demand for lower-grade lime products amid climate-stressed soil conditions. ANVISA and environmental regulators shape handling protocols for bulk agricultural distribution. São Paulo-based distributors bridge loose bulk efficiency with bagged flexibility for mid-scale farming cooperatives.
Lime Market Key Industry Players
Vertically integrated multinationals and regional quarry operators split the market between premium metallurgical grades and price-constrained agricultural volumes. Consolidation concentrates supply among producers with captive limestone reserves and deep terminal infrastructure. Three archetypes dominate: integrated giants with global quarry networks, regional specialists with logistics-advantaged positions, and agricultural-focused grind-and-distribute operators. Competitive moves center on M&A to secure high-calcium limestone deposits and capacity expansion near steel mill clusters.
Within the integrated tier, Carmeuse, Lhoist Group, and Graymont Limited exemplify archetypes spanning quarry-to-terminal control. Carmeuse occupies a position emphasizing Great Lakes logistics density. Lhoist Group anchors European specialty production with captive reserve positions. Graymont Limited sits within the Pacific Northwest regional specialist category, serving pulp mill and water treatment accounts through distribution network depth.
| Leading Market Players |
|---|
| Mississippi Lime Company |
| Cheney Lime & Cement Company |
| Carmeuse |
| Valley Minerals |
| Linwood Mining & Minerals Corporation |
| Graymont Limited |
| United States Lime & Minerals |
| LafargeHolcim |
| Lhoist Group |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Shandong and Hebei provinces is forcing kiln operators toward aggressive pricing for metallurgical quicklime while simultaneously driving consolidation among compliant producers. This utilization imbalance compresses margins for merchant operators lacking captive limestone reserves or integrated terminal infrastructure.
Pricing Analysis
China's MEE enforcement of updated GB standards dictates the pricing tier structure across Asian quicklime markets. Three-tier pricing structure across premium, standard, and economy levels separates sub-0.5% sulfur metallurgical grades from commodity construction lime and agricultural products. Price differentiation rests on reactivity certification and logistics proximity to steel mill clusters. Cost compression in standard-grade quicklime is intensifying because energy price volatility erodes merchant kiln margins. Agricultural cooperatives exhibit highest price sensitivity, while integrated steel mills with continuous offtake accept premium pricing for guaranteed specification consistency.
Supply Chain Analysis
High-calcium limestone deposits in China, India, and the United States anchor upstream feedstock security for calcination capacity. Quicklime production draws from petroleum coke, natural gas, and metallurgical coal as primary fuel inputs. Supply chain risk centers on single-source vulnerability where vertical shaft kiln retrofits fail MEE compliance deadlines. Distribution runs through Great Lakes terminal infrastructure and pneumatic trailer networks serving steel mills and municipal utilities with silo storage capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service agreements with guaranteed reactivity performance represent a service-attach opportunity expanding faster than commodity tonnage sales. Municipal water treatment utilities increasingly outsource slaking system maintenance and dosing optimization to suppliers.
For Market Incumbents: Pre-empt kiln operator skill scarcity by embedding predictive maintenance algorithms and remote combustion optimization into customer contracts. Secure captive limestone reserves with sub-3% magnesium content before reserve depletion extends competitor haul distances. Backward integration into quarry operations in India's Chhattisgarh and Odisha states anchors feedstock security against rising domestic infrastructure demand. For New Entrants and Emerging Players: Brazil's Cerrado agricultural corridor offers underpenetrated volume opportunity where climate-stressed soils require more frequent liming cycles. Target mid-scale farming cooperatives with bulk bag distribution bridging loose bulk efficiency and handling convenience. Deploy slaking automation technology to bypass transport costs for regional water treatment accounts lacking pneumatic infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across flue gas desulfurization-grade hydrated lime as India's CEA mandates tighten. Long-term viability favors integrated producers with captive reserves and terminal infrastructure over merchant kiln operators exposed to fuel price volatility. Acquisition target archetype: regional specialists with logistics-advantaged positions in coal-dependent power corridors. The signal to watch is MEE enforcement velocity driving permanent vertical shaft kiln closures in Shandong province.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive supply of sub-3% magnesium content feedstock secures margin stability against reserve depletion. |
| Long-term Service Agreement Expansion | Municipal utilities in Ohio River corridor outsource slaking maintenance under EPA Safe Drinking Water Act pressure. |
| Waste Heat Recovery Installation | GB standard compliance enables continued operation in China's Shandong province amid MEE enforcement. |
| Slaking Automation Deployment | On-site calcium hydroxide production bypasses bulk transport costs for mid-scale water treatment accounts. |
| Terminal Infrastructure Expansion | Great Lakes pneumatic delivery networks lock in steel mill and utility offtake against competitor logistics. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with kiln operations managers, steel procurement leads, municipal water treatment directors, and flue gas desulfurization engineers; and secondary validation through MEE GB standard filings, CEA power plant compliance records, EPA NAAQS enforcement data, and SEC 10-K disclosures from integrated lime producers. Bottom-up capacity modeling triangulated against top-down consumption estimates across metallurgical flux, water treatment, and construction applications.
Forecast inputs considered calcination capacity utilization, fuel cost trajectories, and regulatory enforcement timelines across the projection horizon. Segmentation dimensions modeled include product chemistry grade, end-use industry, packaging configuration, and regional production hub. CAGRs were derived from regression analysis of historical procurement volumes against steel output, power generation capacity, and infrastructure investment patterns. Industry-specific inputs incorporated electric arc furnace expansion rates in India and CEA flue gas mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese producers or integrated multinationals would shift outcomes. Cross-checking against EIA industrial energy consumption data and IEA carbon capture deployment trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Hydrogen Silicone Fluid Market